
 Nanocrystalline Soft Magnetic Material Market | 2026-2036
Nanocrystalline Soft Magnetic Material Market Size, Share, and Industry Trends Forecast 2026-2036
Nanocrystalline Soft Magnetic Material Market Foresight
Market Context
Qualified metallurgical engineering talent is collapsing across advanced magnetic materials foundries, constraining capacity expansion for nanocrystalline ribbon production. VACUUMSCHMELZE leverages its German technical workforce to sustain leadership in ultra-thin ribbon manufacturing. Hitachi Metal anchors Asian supply through integrated melt-spinning operations in Japan. Qingdao Yunlu competes on cost-positioned core assemblies serving domestic transformer rebuilds.
Technical Definition and Segments
Nanocrystalline soft magnetic materials are iron-based alloys with grain sizes below 100 nanometers, typically produced via rapid solidification melt-spinning followed by controlled crystallization annealing to achieve coercivity under 2 A/m and permeability exceeding 100,000. These properties enable miniaturization of electromagnetic components in power electronics and grid infrastructure. Ribbon form dominates transformer and inductor applications due to superior stacking factor and core loss performance, while powder segments serve molded choke coils in automotive DC-DC converters. Alloy compositions containing niobium and copper additions command premium positioning in aerospace-grade electromagnetic shields.
Regulatory Environment
EPA efficiency mandates for distribution transformers and EU Ecodesign requirements under the F-Gas Regulation are tightening permissible core loss specifications, directly favoring nanocrystalline substitutions over conventional silicon steel. China's GB standards for energy-saving electrical equipment and Japan's METI Top Runner program create parallel compliance pathways that OEMs must navigate simultaneously. Stakeholders should monitor how regional efficiency benchmarks diverge, as certification multiplicity will determine which alloy grades capture cross-border volume.
Market Dynamics
Transformer core procurement is pivoting toward ultra-low-loss materials as grid operators face stranded asset risk from legacy silicon steel installations that cannot meet tightening efficiency mandates.
Growth Catalysts
- EPA Distribution Transformer Efficiency Standards:The 2027 phase-in of amended DOE efficiency rules for liquid-immersed and dry-type distribution transformers mandates maximum core loss thresholds that nanocrystalline alloys satisfy natively.
- EV Powertrain Integration:Onboard charger and DC-DC converter manufacturers are specifying nanocrystalline common-mode chokes to achieve power density targets above 50 kW per liter.
- East Asian Manufacturing Clustering:Ribbon production concentrates in Japanese and Chinese melt-spinning corridors, creating localized supply security for regional transformer rebuild programs.
Market Restraints
- Niobium and Copper Input Volatility:Alloy additions comprising 2-4% of ribbon mass expose producers to London Metal Exchange price swings that compress margin on long-term supply contracts.
- German Technical Workforce Bottleneck:Qualified metallurgical engineers capable of operating ultra-thin ribbon annealing lines number fewer than 400 across European foundries, capping expansion velocity.
- Amorphous Metal Substitution:Hitachi Metal's Metglas amorphous alloy retains cost advantage in distribution transformers below 500 kVA, constraining nanocrystalline penetration at the volume tier.
Strategic Opportunities
- India Distribution Grid Modernization:The country's rural electrification program and renewable integration targets create latent demand for high-efficiency distribution transformers that domestic silicon steel cannot satisfy.
- Wireless Charging Infrastructure:Resonant inductive coupling systems for autonomous electric vehicle fleets require high-frequency magnetic cores with permeability profiles unique to nanocrystalline compositions.
- EU F-Gas Regulation Phase-Down:Natural ester and dry-type transformer designs favored under fluorinated gas restrictions align with nanocrystalline thermal performance characteristics, opening retrofit volume.
Industry Challenges
- Rapid Solidification Process Control:Melt-spinning operators face yield degradation when casting ribbons below 18 micrometers thickness, requiring real-time pyrometry systems that extend commissioning timelines.
- Multi-Jurisdiction Certification Burden:OEMs must simultaneously satisfy GB standards for China entry, METI Top Runner for Japan, and DOE efficiency compliance for North America, multiplying testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanocrystalline Soft Magnetic Material Market |
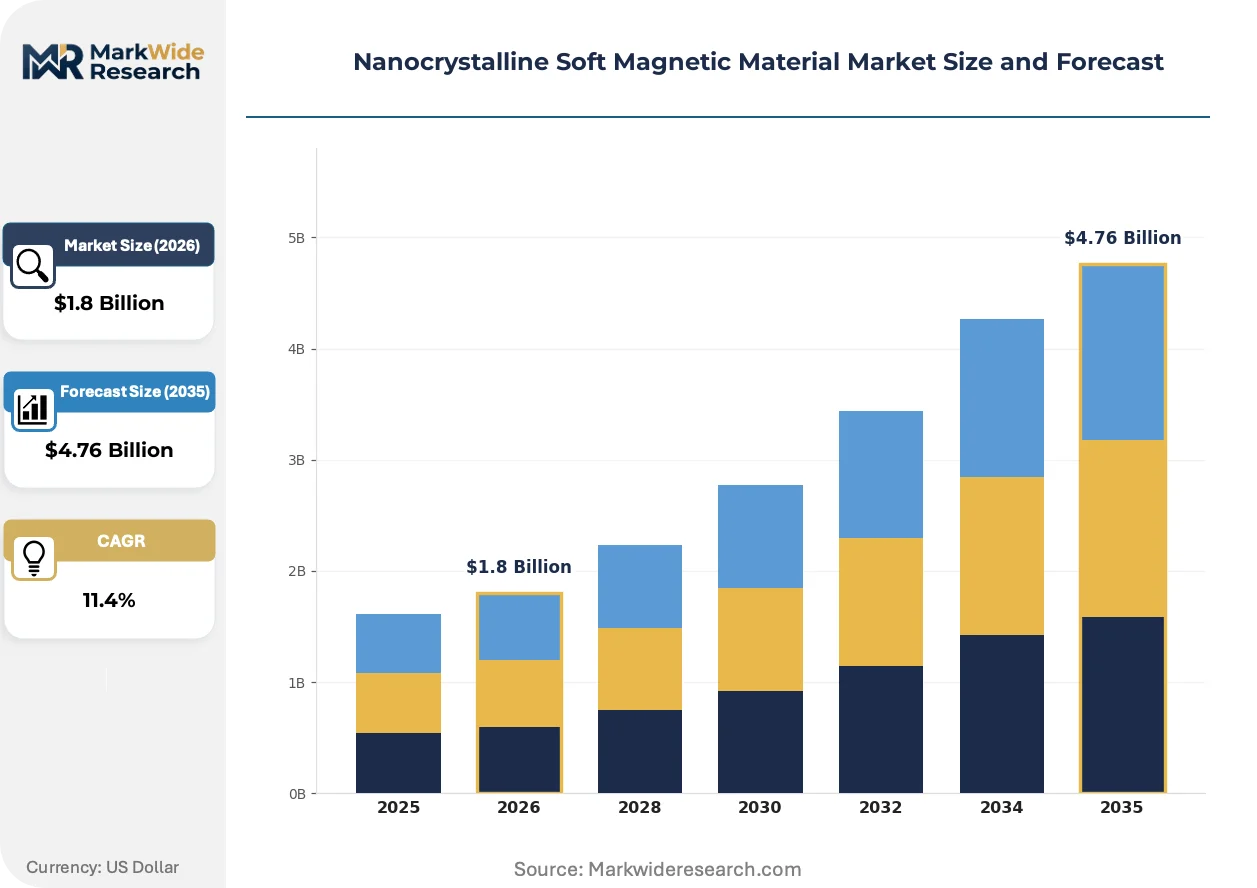
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
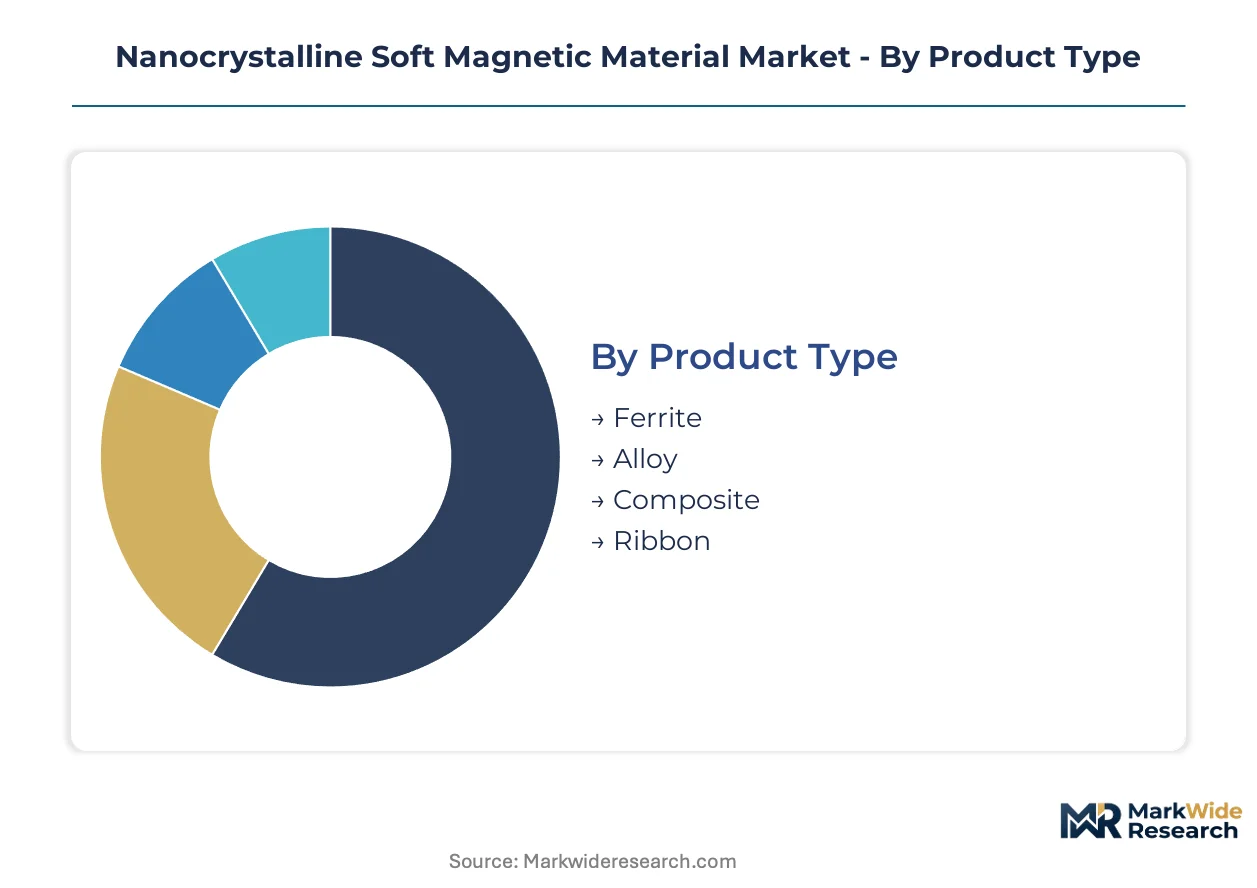
| Segmentation | Product Type: Ferrite, Alloy, Composite, Ribbon Application: Transformers, Inductors, Electric Motors, Sensors Form: Powder, Sheet, Wire, Core End User: Automotive, Industrial, Electronics, Aerospace |
| Companies Covered | Hitachi Metal, VACUUMSCHMELZE, Advanced Technology, Qingdao Yunlu, China Amorphous Technology, Henan Zhongyue, OJSC MSTATOR, Foshan Huaxin, Londerful New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanocrystalline Soft Magnetic Material Market Shifts & Advancements
Melt-spinning process control and annealing automation are compressing the performance gap between laboratory-grade ribbon and production-scale output, enabling specification-grade supply to mainstream transformer manufacturers.
Sub-20-micrometer nanocrystalline ribbon is displacing conventional ferrite and powdered iron cores in 100-500 kHz power conversion applications. Server power supply manufacturers at 48V direct-current rack architectures have adopted these ribbons for output inductors, achieving 40% volume reduction against incumbent materials. The structural consequence is displacement of manganese-zinc ferrite from data center power architectures above 10 kW per rack.
China's GB 20052-2020 energy efficiency standard for power transformers mandates 30% core loss reduction against prior baselines, effective for new installations from 2024. Provincial grid companies in Jiangsu and Guangdong have incorporated compliance verification into procurement scoring, redirecting transformer tender awards toward nanocrystalline-qualified suppliers. Domestic ribbon producers are scaling annealing furnace capacity to capture this mandated substitution window.
Direct mill-to-transformer OEM relationships are compressing traditional distributor channels for high-performance core materials. Tier-one transformer manufacturers in Japan and Germany now contract ribbon supply on 36-month indexed agreements, bypassing regional metal traders. This pattern concentrates procurement leverage with Hitachi Metal and VACUUMSCHMELZE while marginalizing secondary distributors in European and North American markets.
Nanocrystalline Soft Magnetic Material Market Segmentation
Nanocrystalline soft magnetic material procurement splits across four distinct dimensions. Each segmentation axis reveals different margin concentrations and technical barriers to entry.
Product Type:
Ribbon commands the steepest premium tiers due to melt-spinning complexity and annealing precision requirements.
- Ribbon:Ultra-thin cast strips below 25 micrometers achieve permeability exceeding 100,000 after controlled crystallization. Grid transformer manufacturers in Jiangsu province specify ribbon cores to meet GB 20052-2020 loss mandates.
- Alloy:Iron-based compositions with niobium and copper additions enable grain refinement below 100 nanometers. Aerospace electromagnetic shield suppliers pay alloy premiums for temperature stability above 150°C.
- Ferrite:Manganese-zinc formulations serve cost-sensitive inductor applications below 1 MHz switching frequency.
- Composite:Polymer-bonded magnetic particles fill molded choke geometries for automotive DC-DC converters.
Ribbon holds installed capacity. Alloy is rotating up the share rankings.
Application:
Volume concentrates where efficiency regulations force material substitution against legacy silicon steel.
- Transformers:Distribution and power transformer cores absorb ribbon volume as EPA efficiency standards phase in. Core loss specifications under 0.2 W/kg at 1.5T favor nanocrystalline laminations over conventional grain-oriented steel.
- Inductors:Server power supplies at 48V rack architectures adopt sub-20-micrometer ribbon for output filtering. Data center operators specify these cores to achieve 40% volume reduction against ferrite alternatives.
- Electric Motors:High-frequency motor laminations in EV auxiliary drives exploit low coercivity for reduced hysteresis losses.
- Sensors:Current transducers and magnetic field detectors leverage high permeability for signal fidelity.
Transformers dominate current procurement tonnage. Inductors are climbing the fastest as data center power density requirements tighten.
Form:
Manufacturing yield curves favor certain geometries over others in melt-spinning operations.
- Core:Toroidal and C-cores dominate transformer assembly. Japanese transformer OEMs contract 36-month indexed supply agreements directly with ribbon casters for core deliveries.
- Powder:Atomized and annealed particles serve pressed choke cores in automotive onboard chargers. Powder segments gain traction where three-dimensional magnetic path geometries are required.
- Sheet:Laminated constructions suit large power transformer stacked cores.
- Wire:Fine-gauge windings for specialized sensor and inductive component applications.
Core maintains production scale. Powder is gaining share fastest in automotive power electronics.
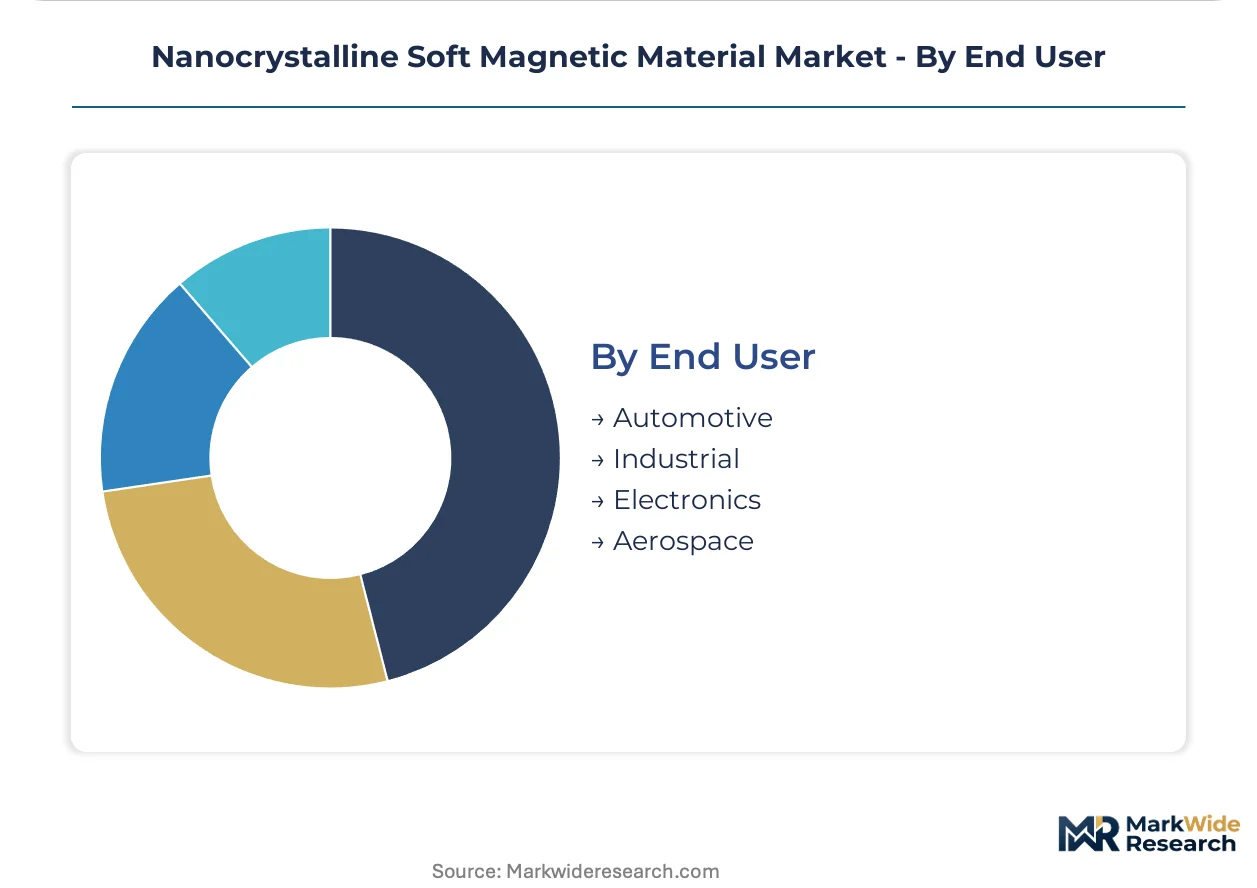
End User:
Customer concentration varies sharply by technical qualification requirements and contract structures.
- Automotive:EV powertrain manufacturers specify nanocrystalline common-mode chokes for onboard chargers. Power density targets above 50 kW per liter exclude ferrite from Tier 1 supplier designs.
- Industrial:Factory automation and renewable energy inverters drive demand for high-frequency magnetic components. German drive manufacturers source ribbon cores through direct mill relationships bypassing distributors.
- Electronics:Consumer power supply and telecommunications infrastructure consume standardized core geometries.
- Aerospace:Electromagnetic interference shielding and avionics power conditioning require certified alloy grades with full traceability.
Industrial holds established procurement volume. Automotive is expanding most quickly as EV platform volumes scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB 20052-2020 efficiency mandates that redirect transformer procurement toward nanocrystalline-qualified suppliers. Japan's METI Top Runner program and the EPA's amended DOE efficiency rules create parallel compliance pathways across three major manufacturing clusters.
China
Provincial grid companies in Jiangsu and Guangdong have incorporated GB 20052-2020 compliance verification into procurement scoring. The dual carbon goals issued by MEE accelerate substitution timelines for distribution transformer rebuilds. Qingdao and Shanghai anchor melt-spinning corridors where domestic ribbon producers scale annealing furnace capacity.
Japan
METI's Top Runner program sets efficiency benchmarks that OEMs must satisfy for domestic transformer tenders. Hitachi Metal maintains integrated melt-spinning operations in the Chubu region near Nagoya. Japanese transformer OEMs contract ribbon supply on 36-month indexed agreements that bypass regional metal traders.
Germany
VACUUMSCHMELZE leverages its German technical workforce to sustain leadership in ultra-thin ribbon manufacturing. The EU F-Gas Regulation phase-down favors natural ester and dry-type transformer designs that align with nanocrystalline thermal performance. The Hanau production complex concentrates qualified metallurgical engineering talent for annealing line operations.
United States
The 2027 phase-in of amended DOE efficiency rules for liquid-immersed and dry-type distribution transformers mandates maximum core loss thresholds. Grid operators face stranded asset risk from legacy silicon steel installations that cannot meet tightening EPA specifications. Transformer core procurement pivots toward ultra-low-loss materials through direct mill-to-OEM relationships.
India
The rural electrification program and renewable integration targets create latent demand for high-efficiency distribution transformers. CEA procurement guidelines increasingly reference core loss specifications that domestic silicon steel cannot satisfy. Manufacturing clusters in Maharashtra and Gujarat attract ribbon core assembly investments for regional transformer OEMs.
Nanocrystalline Soft Magnetic Material Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the nanocrystalline soft magnetic material market. German and Japanese manufacturers anchor the premium tier through metallurgical process control, while Chinese producers compete on cost-positioned core assemblies. Three archetypes dominate: integrated melt-spinning operators with captive annealing capacity, specialized ribbon casters serving transformer OEMs directly, and powder core fabricators for automotive power electronics. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualified engineering talent constraints limit organic growth velocity.
Among integrated operators, Hitachi Metal and VACUUMSCHMELZE exemplify technology-forward positioning through German and Japanese manufacturing heritage. Qingdao Yunlu occupies a cost-leadership position serving domestic transformer rebuild programs. These three anchors illustrate the geographic bifurcation between premium-tier metallurgical engineering and volume-tier procurement efficiency.
| Leading Market Players |
|---|
| Hitachi Metal |
| VACUUMSCHMELZE |
| Advanced Technology |
| Qingdao Yunlu |
| China Amorphous Technology |
| Henan Zhongyue |
| OJSC MSTATOR |
| Foshan Huaxin |
| Londerful New Material |
| Others |
Supply & Pricing Matrix
Annealing furnace utilization rates above 85% in Jiangsu and Chubu manufacturing corridors create scale economies that compress per-kilogram ribbon costs while simultaneously concentrating pricing power among integrated melt-spinning operators with captive heat-treatment capacity.
Pricing Analysis
Japanese-sourced ribbon commands 15-25% premiums over Chinese-origin material in transformer core procurement, reflecting METI Top Runner certification costs and VACUUMSCHMELZE's technical workforce scarcity premium. Three-tier pricing structure across aerospace-grade alloy, industrial transformer ribbon, and automotive powder core segments stratifies by niobium content and annealing precision. Cost compression in standard-grade ribbon intensifies as Qingdao Yunlu scales furnace capacity, eroding margins on domestic Chinese supply contracts. Automotive EV powertrain manufacturers exhibit lowest price sensitivity, prioritizing permeability consistency over unit cost in onboard charger specifications.
Supply Chain Analysis
Strategic stockpiling of niobium and copper master alloys dominates inventory strategy among German and Japanese ribbon casters, insulating against London Metal Exchange volatility that disrupts just-in-time procurement favored by Chinese core assemblers. Melt-spinning capacity concentrates in China, Japan, and Germany, with ribbon casting draws from Chubu-region integrated operations and Hanau technical complexes. Single-source vulnerability pervades ultra-thin ribbon below 18 micrometers, where qualified annealing line operators number fewer than 400 across European foundries. Distribution runs through direct mill-to-OEM contracts that bypass regional metal traders, concentrating procurement leverage with Hitachi Metal and VACUUMSCHMELZE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one transformer OEMs in Japan and Germany who negotiate 36-month indexed supply agreements, fragmenting distributor influence while compressing margin capture for secondary channel participants.
For Market Incumbents: Shield metallurgical process expertise through captive annealing capacity expansion in Jiangsu or Chubu corridors, insulating against amorphous metal substitution below 500 kVA distribution transformers. Deepen backward integration into niobium alloy masterbatch production to neutralize London Metal Exchange price volatility exposure on long-term supply contracts. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat manufacturing clusters where CEA procurement guidelines outpace domestic silicon steel capability, creating white-space for high-efficiency distribution transformer core assembly. Target wireless charging infrastructure resonant inductive coupling specifications, where permeability requirements exclude ferrite incumbents and qualified nanocrystalline suppliers remain scarce. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated melt-spinning operators with captive annealing lines and direct OEM contracting relationships, positioning these archetypes for sustained cash flow quality across the analysis window. Acquisition priorities center on German or Japanese technical teams with sub-20-micrometer ribbon yield optimization expertise. The signal to watch is EPA efficiency standard phase-in velocity, which would accelerate stranded asset risk for silicon steel-dependent transformer fleets and trigger step-function demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Annealing Furnace Capacity Expansion | Captures GB 20052-2020 compliance-driven substitution volume in Jiangsu procurement corridors. |
| Backward Integration into Niobium Supply | Neutralizes LME price volatility exposure compressing margin on indexed OEM contracts. |
| Direct Mill-to-OEM Contracting | Bypasses distributor channels where Hitachi Metal and VACUUMSCHMELZE concentrate leverage. |
| Sub-20-Micrometer Ribbon Yield Improvement | Displaces ferrite from 48V server power supply architectures at 100-500 kHz switching frequencies. |
| India Distribution Grid Partnership | Aligns with CEA procurement guidelines exceeding domestic silicon steel core loss specifications. |
Research Methodology
The analysis maps ribbon casting operations, powder core fabrication, and electromagnetic shield alloy supply, each validated through melt-spinning line operators, transformer OEM procurement directors, and automotive Tier 1 power electronics engineers. Primary fieldwork combined structured interviews with annealing furnace technicians, distribution transformer specification consultants, and grid operator material qualification officers. Secondary validation drew from MIIT capacity filings, METI Top Runner benchmark disclosures, EPA Federal Register efficiency rulemakings, and customs trade data for niobium alloy imports. Bottom-up ribbon production estimates triangulated against top-down transformer core demand projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by product form, application end-use, and regional regulatory cluster. CAGRs derived from installed capacity expansion timelines and efficiency mandate phase-in schedules. Forecast inputs incorporated melt-spinning yield curves for sub-20-micrometer ribbon and annealing furnace commissioning lead times.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA efficiency enforcement and Chinese dual carbon goal implementation; material deviation would warrant model refresh. Revision becomes warranted when amorphous metal substitution rates in sub-500 kVA transformers or niobium price volatility spikes cross thresholds that alter OEM material selection economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Global Soft Magnetic Materials Market