
 Ferroboron Market | 2026-2036
Ferroboron Market Size, Share, and Industry Trends Forecast 2026-2036
Ferroboron Market Insights
Chinese ferroboron smelter capacity is broadening across Liaoning and Shandong provinces, drawing downstream offtake from specialty steel mills. NIPPON DENKO CO., LTD. leverages captive boron sourcing from Japanese refineries to sustain premium-grade output for aerospace buyers. AMG Advanced Metallurgical Group anchors European supply through its German processing assets, while Gulf Chemical and Metallurgical Corporation competes on cost-positioned ferroboron flows into Middle Eastern alloy markets.
Ferroboron is an iron-boron master alloy typically containing 10-20% boron by weight, produced through aluminothermic reduction or electric furnace smelting and used primarily to enhance hardenability, creep resistance, and neutron absorption in steels and superalloys. Ferroboron 20% commands the dominant volume position in steel production applications where boron microaddition yields significant hardenability gains at low cost. Alloy Manufacturing represents the fastest-growing application segment as nickel-based superalloy producers seek tighter boron control for turbine blade castings.
China's MEE enforces GB emission standards on ferroalloy smelters, while REACH in Europe restricts hazardous substance releases from boron processing facilities, and India's BIS certification mandates compositional consistency for imported ferroboron used in critical infrastructure steels. These frameworks elevate compliance costs for marginal producers while advantaging integrated suppliers with in-house environmental controls. Stakeholders must monitor boron raw material concentration in Turkey and Kazakhstan, as upstream access increasingly determines alloy pricing and supply security.
Market Dynamics
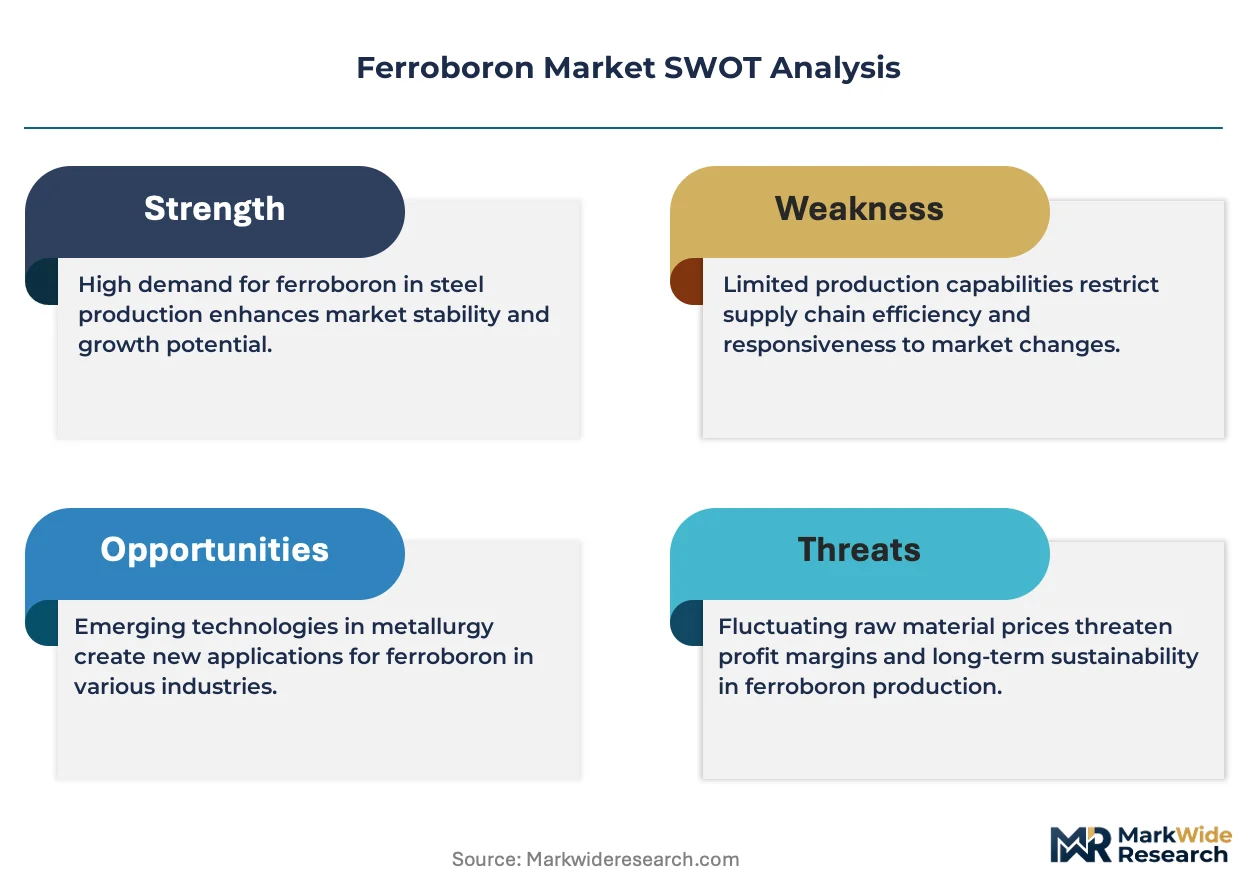
China's dual carbon goals and tightening GB emission standards are restructuring ferroboron supply economics, forcing capacity consolidation among Liaoning and Shandong smelters while advantaging integrated producers with captive boron sourcing and in-house environmental controls.
Growth Catalysts
- Automotive lightweighting mandates:High-strength boron-alloyed steels enable thinner gauge specifications in EV chassis and safety-critical components, expanding ferroboron microaddition rates at specialty mills.
- REACH compliance in Europe:Hazardous substance restrictions on boron processing are elevating entry barriers for marginal producers, concentrating volume among refiners with certified environmental management systems.
- Nuclear energy restart programs:Boron neutron absorption properties drive demand for ferroboron in control rod and shielding applications as France, Japan, and South Korea extend reactor lifecycles.
Market Restraints
- Upstream boron concentration:Over half of refined boron supply originates from Turkish and Kazakh deposits, creating geopolitical and logistics vulnerability for non-integrated alloy producers.
- Aluminothermic cost volatility:Ferroboron production depends on aluminum reductant pricing, which fluctuates with energy costs and alumina refining margins.
- Titanium diboride substitution:Advanced ceramic particulates compete with ferroboron in certain superalloy grain-refining applications where ultra-low oxygen content is critical.
Strategic Opportunities
- India infrastructure buildout:BIS certification requirements for critical infrastructure steels create a premium-grade ferroboron segment as domestic specialty alloy capacity expands.
- Additive manufacturing feedstock:Gas-atomized ferroboron powders for laser powder bed fusion of tool steels represent an emerging specification tier with pricing power.
- EU Green Deal carbon border adjustments:Embedded emissions accounting favors European ferroboron with documented low-carbon smelting energy, disadvantaging coal-intensive imports.
Industry Challenges
- Metallurgical technician scarcity:Electric furnace smelting of ferroboron requires precise temperature and slag chemistry control that experienced operators provide, with training pipelines insufficient across European and North American operations.
- Superalloy certification timelines:Aerospace and power generation turbine blade castings demand multi-year qualification protocols for any boron source change, locking suppliers into rigid supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferroboron Market |
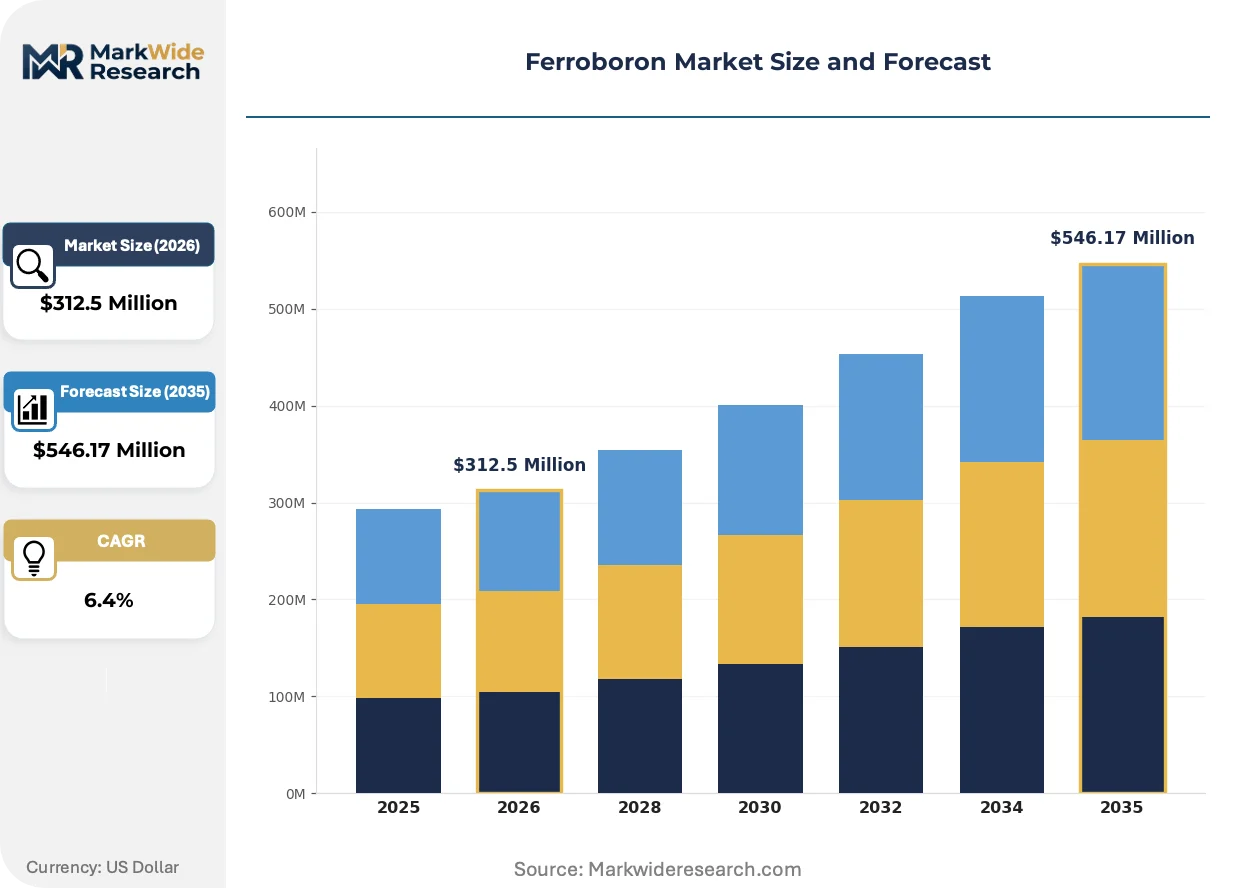
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferroboron 10%, Ferroboron 15%, Ferroboron 20%, Ferroboron 5% Application: Welding, Steel Production, Alloy Manufacturing, Chemical Synthesis End User: Automotive Industry, Aerospace Sector, Construction Companies, Electronics Manufacturers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | NIPPON DENKO CO., LTD., CRONIMET, AMG Advanced Metallurgical Group, Tennant Metallurgical Group Ltd, SB Boron, Liaoning Jinlong Group, Dandong Chemical Engineering Institute, Gulf Chemical and Metallurgical Corporation, Eti Maden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferroboron Market Trends and Innovations
Smelting technology, regulatory carbon accounting, and procurement centralization are converging to reshape how ferroboron is produced, priced, and purchased across steel and superalloy value chains.
Continuous electric furnace smelting is overtaking batch aluminothermic reduction as the dominant production pathway for ferroboron 20% grade. German and Japanese integrated metallurgical groups have retrofitted submerged arc furnaces with automated boron recovery systems, cutting unit energy consumption and enabling real-time composition adjustment. This process architecture compresses capital payback periods while tightening boron uniformity tolerances that aerospace superalloy casters demand.
REACH authorization requirements for boron compounds are forcing European ferroalloy refiners to document substance flow analysis across their supply networks. ECHA's 2023 updated guidance on reproductive toxicity classification has triggered reformulation investments at Dutch and German processing assets. Specialty steel mills in Italy and Spain now require ferroboron suppliers to provide extended safety data sheets with granular exposure scenario documentation.
Consolidated procurement by multinational steel groups is displacing fragmented spot-market purchasing for ferroboron microaddition. ArcelorMittal and Nippon Steel have implemented master alloy category management with three-year offtake frameworks, volume commitments, and technical service integration. This behavioral shift concentrates supplier relationships among three to four qualified vendors per region, compressing margins for transactional traders in Turkish and Chinese export markets.
Ferroboron Market Segmentation
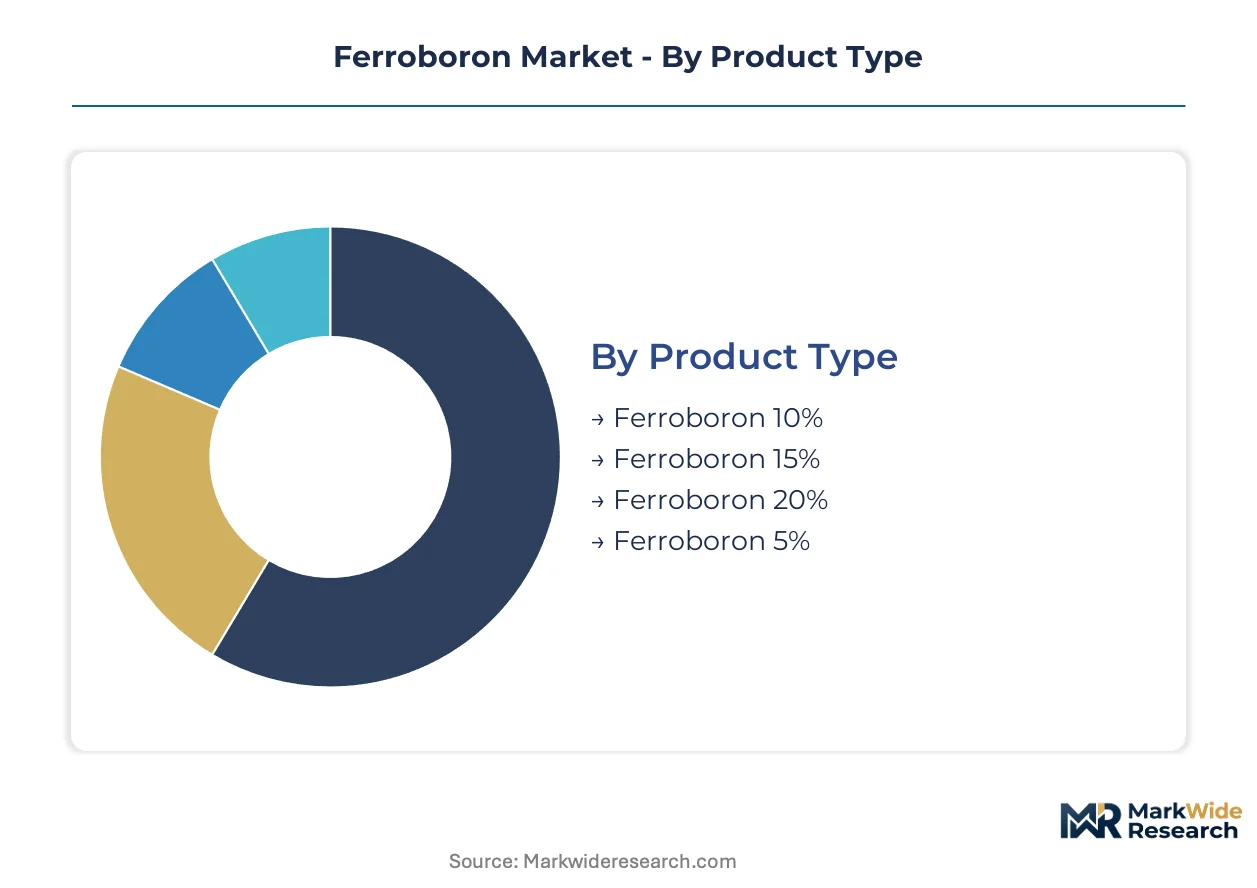
Ferroboron specifications vary dramatically across steelmaking, superalloy casting, and chemical processing end-uses. Grading precision, application chemistry, and supply chain access determine how buyers segment procurement and how suppliers configure metallurgical assets.
Product Type:
Standalone ferroboron grades serve discrete hardenability targets, while embedded boron microaddition systems integrate into continuous casting operations.
- Ferroboron 20%:This high-boron master alloy delivers maximum hardenability enhancement per kilogram of addition, concentrating demand at automotive specialty mills producing press-hardened boron steels for EV chassis. Chinese steelmakers in Liaoning province consume this grade at scale for high-strength automotive strip production.
- Ferroboron 10%:Lower boron concentration enables finer compositional control in nickel-based superalloy vacuum induction melting, where precise boron levels govern grain boundary carbide formation. Aerospace turbine blade casters in Japan and Germany specify this grade for creep-resistant alloys.
- Ferroboron 15%:Mid-range specification bridges cost and control for construction-grade structural steels requiring moderate hardenability gains.
- Ferroboron 5%:Dilute grade serves chemical synthesis applications and experimental alloy development where incremental boron introduction is preferred.
Ferroboron 20% leads volumes today; alloy manufacturing applications are gaining share fastest.
Application:
Application segmentation tracks boron functionality from structural reinforcement through chemical reactivity, with cost tiers separating commodity steel from certified superalloy consumption.
- Steel Production:Microaddition of ferroboron during ladle metallurgy transforms plain carbon steels into hardenable grades, enabling thinner automotive safety components without strength sacrifice. This application concentrates in East Asian flat-rolled steel mills supplying just-in-time automotive assembly plants.
- Alloy Manufacturing:Vacuum-melted superalloys for aerospace turbine castings demand ultra-low oxygen ferroboron with tight boron uniformity, commanding pricing premiums and multi-year supplier qualification protocols.
- Welding:Boron-containing filler metals enhance weld metal hardenability in high-strength structural fabrication.
- Chemical Synthesis:Ferroboron serves as boron source in specialty chemical production and materials research applications.
Steel production dominates absolute consumption; alloy manufacturing climbs the fastest.
End User:
Customer type segmentation reveals how certification requirements, volume scale, and technical service needs stratify the ferroboron supplier base.
- Automotive Industry:Press-hardened steel demand from EV manufacturers drives ferroboron consumption at specialty flat-rolled mills, with OEM lightweighting mandates accelerating boron-alloyed steel specifications for battery enclosure and chassis applications.
- Aerospace Sector:Turbine engine manufacturers enforce stringent boron source qualification, locking superalloy casters into rigid supply relationships with certified ferroboron refiners.
- Construction Companies:Infrastructure-grade structural steel producers consume standard ferroboron specifications for rebar and beam hardenability.
- Electronics Manufacturers:Neutron-absorbing ferroboron applications in semiconductor processing equipment represent a niche specification tier.
Automotive industry absorbs the largest volumes; aerospace sector expands most quickly.
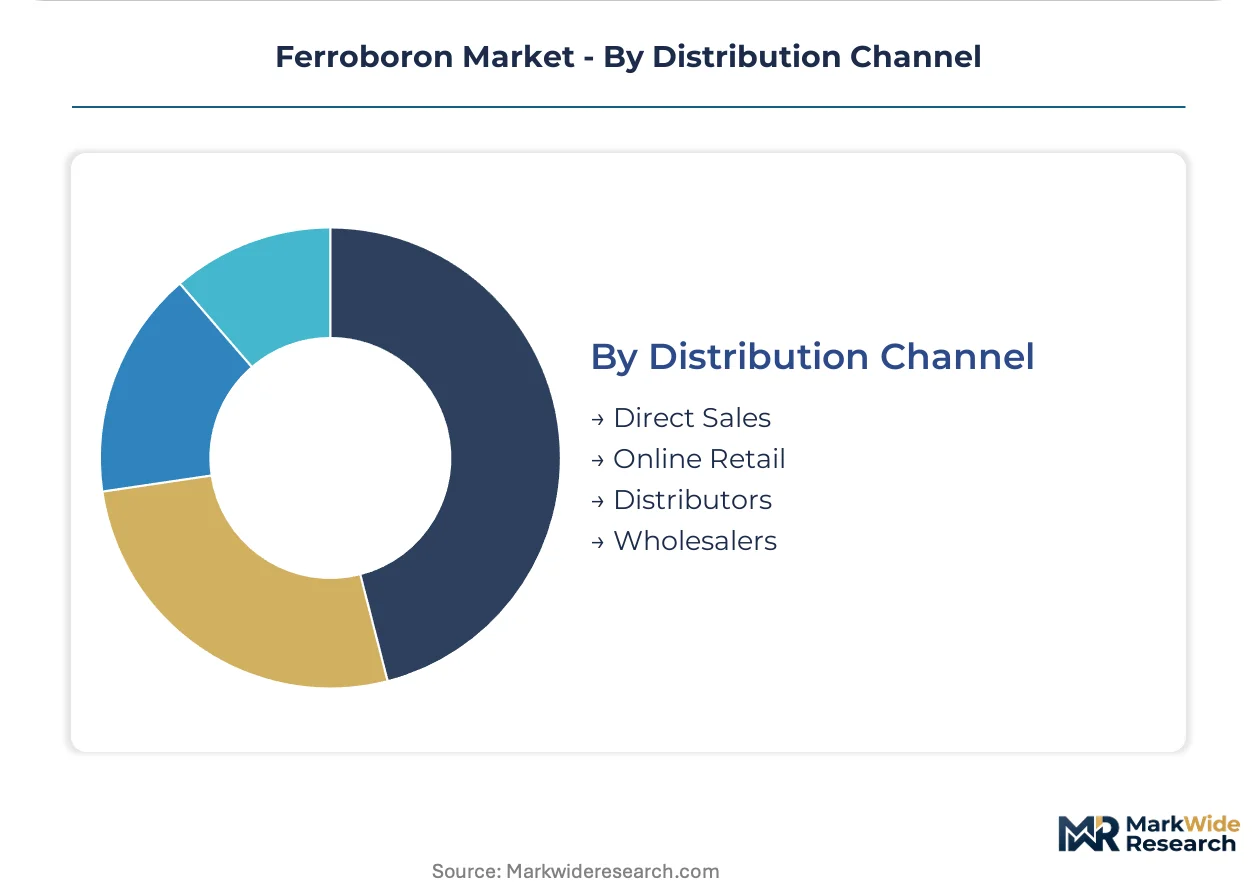
Distribution Channel:
Channel structure reflects procurement centralization trends and the technical service intensity required for qualified ferroboron supply.
- Direct Sales:Integrated steel groups and superalloy casters negotiate multi-year offtake agreements with ferroboron smelters, embedding technical service and inventory management into contractual frameworks.
- Distributors:Regional alloy distributors serve fragmented construction steel and welding consumable producers with standardized grades and shorter lead times.
- Wholesalers:Volume traders aggregate spot-market ferroboron flows for smaller metallurgical operations.
- Online Retail:Digital platforms facilitate research-grade and small-batch ferroboron procurement for experimental applications.
Direct sales channels command the largest share; distributor networks are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are reshaping ferroboron production geography. Chinese smelters absorb stricter MEE emission standards while Turkish and Kazakh boron miners leverage upstream integration to capture margin from European REACH compliance burdens.
China
Automotive lightweighting mandates from NEV manufacturers and dual carbon enforcement by MEE are accelerating ferroboron consumption. GB emission standards on ferroalloy smelters force capacity consolidation among Liaoning and Shandong producers. Shenyang specialty steel clusters now source captive ferroboron from retrofitted electric furnaces with automated boron recovery.
Germany
EU Green Deal carbon border adjustments and REACH authorization requirements for boron compounds elevate entry barriers for imported ferroboron. ECHA's 2023 reproductive toxicity classification updates trigger reformulation investments at Rhineland processing assets. Düsseldorf-based superalloy casters now demand extended safety data sheets with granular exposure documentation.
Japan
Aerospace turbine blade demand and nuclear reactor lifecycle extensions drive premium-grade ferroboron specifications. METI oversees industrial material standards while JIS certification governs boron uniformity tolerances. Nagoya superalloy foundries maintain rigid multi-year supplier qualification protocols with certified refiners.
United States
Defense aerospace programs and press-hardened steel adoption by Detroit automakers concentrate ferroboron demand. EPA hazardous substance tracking and OSHA workplace exposure limits elevate compliance costs for non-integrated processors. Ohio specialty steel corridors source qualified ferroboron through direct mill-to-smelter offtake frameworks.
Turkey
Upstream boron mining concentration at Eti Maden deposits creates supply security leverage for alloy producers. The country's national mining regulator enforces extraction quotas while infrastructure investments target refined boron output expansion. Bandırma processing clusters supply cost-positioned ferroboron flows into Middle Eastern alloy markets.
Ferroboron Market Competitive Landscape
East Asian producers anchor the volume tier; European specialists hold premium-grade positioning through certification depth. The vendor base stratifies across integrated mining-metallurgy groups, electric furnace operators with environmental controls, and regional distributors serving fragmented construction steel demand. Three archetypes dominate: upstream-integrated Turkish and Chinese smelters, German and Japanese quality-certification leaders, and Gulf-based cost-positioned exporters. Capacity consolidation and multi-year offtake contracting represent the dominant competitive moves.
Among Japanese integrated metallurgical groups, NIPPON DENKO CO., LTD. exemplifies captive boron sourcing architecture for aerospace-grade output. AMG Advanced Metallurgical Group occupies a position within European quality-tier supply through German processing assets. Gulf Chemical and Metallurgical Corporation anchors Middle Eastern export flows with cost-competitive positioning into regional alloy markets.
| Leading Market Players |
|---|
| NIPPON DENKO CO., LTD. |
| CRONIMET |
| AMG Advanced Metallurgical Group |
| Tennant Metallurgical Group Ltd |
| SB Boron |
| Liaoning Jinlong Group |
| Dandong Chemical Engineering Institute |
| Gulf Chemical and Metallurgical Corporation |
| Eti Maden |
| Others |
Pricing and Supply Chain Analysis
Aluminum reductant costs cascade from alumina refining margins through ferroboron smelter economics into three distinct pricing tiers for automotive, aerospace, and construction buyers. Turkish and Kazakh boron concentrate feedstock advantages translate into cost-positioned alloy flows that undercut European REACH-compliant refiners on spot markets.
Pricing Analysis
Distributor margins compress most severely at the standard-grade tier serving fragmented construction steel producers, while direct-to-OEM offtake frameworks for automotive press-hardened steel lock in volume commitments at thinner spreads. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified superalloy grades from automotive microaddition specifications and undifferentiated construction rebar alloys. Pricing pressure stems from aluminothermic cost volatility and energy price swings, with construction-grade buyers exhibiting highest price sensitivity and aerospace turbine casters least willing to switch on cost.
Supply Chain Analysis
Remanufacturing flows for ferroboron are negligible given the metallurgical consumption model, though boron recovery from steelmaking slag represents an emerging circularity pathway at retrofitted Chinese electric furnaces. Raw material concentration in Turkey and Kazakhstan creates single-source vulnerability for non-integrated alloy producers, while refined boron supply draws from Eti Maden deposits, Kazakh mining complexes, and captive Japanese refinery output. Distribution runs through direct mill-to-smelter offtake agreements for qualified automotive and aerospace volumes, with spot-market traders aggregating residual construction-grade flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities crystallize around carbon border adjustment differentials, where European REACH compliance burdens and EU Green Deal embedded emissions accounting elevate landed costs for coal-intensive Chinese imports against Turkish upstream-integrated supply.
For Market Incumbents: Anchor premium-grade positioning through JIS and aerospace certification depth against titanium diboride substitution threats in superalloy grain-refining applications. Defend margin structure by retrofitting submerged arc furnaces with automated boron recovery systems that compress energy unit costs and tighten composition tolerances. Prioritize three-year offtake frameworks with ArcelorMittal and Nippon Steel category management teams to displace transactional traders. For New Entrants and Emerging Players: Capture India infrastructure buildout white space as BIS certification requirements for critical infrastructure steels create premium-grade entry points alongside domestic specialty alloy capacity expansion. Target additive manufacturing feedstock specifications for gas-atomized ferroboron powders, where laser powder bed fusion tool steel demand outruns qualified supplier availability. Pursue technical service integration as primary go-to-market wedge against commodity traders. For Investors and Strategic Acquirers: Consolidation pressure builds where Chinese MEE emission standards force Liaoning and Shandong smelter capacity rationalization among subscale operators lacking environmental controls. Long-term viability favors upstream-integrated targets with captive boron sourcing or German/Japanese quality-certification depth that commands aerospace pricing premiums. Monitor Turkish mining regulator extraction quota announcements and EU carbon border adjustment implementation timing as inflection signals for regional cost-position shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Mining | Eti Maden and Kazakh deposit access secures feedstock cost advantage against spot-market volatility. |
| Electric Furnace Retrofit with Boron Recovery | German and Japanese smelters cut unit energy consumption while tightening aerospace-grade tolerances. |
| REACH Compliance Certification Investment | Dutch and German refiners document substance flow analysis to maintain European market access. |
| Long-term Automotive offtake Agreement | Three-year frameworks with Nippon Steel embed technical service and displace spot-market purchasing. |
| Gas-atomized Powder Specification Development | Additive manufacturing feedstock tier commands pricing power in laser powder bed fusion applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ferroalloy plant managers, specialty steel procurement leads, aerospace superalloy casting directors, and boron mining operations heads with secondary validation against customs trade data, SEC filings from listed metallurgical groups, GB standards documentation from China's MEE, and ECHA REACH authorization records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates across the analysis window.
Historical reference periods anchored the projection horizon to observed capacity utilization, emission standard implementation timelines, and automotive lightweighting specification adoption curves. Segmentation modeling tracked product grade tier, application chemistry requirements, end-user certification intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to bottom-up segment volumes, with boron raw material concentration indices and electric furnace technology diffusion rates serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; aerospace superalloy specifications carry tighter precision than construction-grade rebar applications due to qualification protocol visibility. Forecasts reflect documented assumptions regarding emission standard enforcement intensity, carbon border adjustment implementation scope, and nuclear reactor lifecycle extension commitments. Practitioners should monitor Turkish mining quota announcements, EU carbon border adjustment regulatory drafts, and titanium diboride ceramic particulate cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnet Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Flux Field Directional Material Market