
 Ferrite Magnet Market | 2026-2036
Ferrite Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrite Magnet Market Intelligence
Electric vehicle powertrain engineers are reorganizing supplier relationships toward ferrite-dominant motor architectures. Arnold Magnetic Technologies leverages its North American production footprint to serve automotive OEMs transitioning from rare earth dependencies. Hangzhou Permanent Magnet Group anchors volume supply for domestic Chinese EV platforms. BGRIMM Technology Group competes on vertically integrated ore-to-magnet processing across multiple ferrite grades.
Ferrite magnets are ceramic compounds of iron oxide combined with strontium or barium carbonate, sintered at temperatures exceeding 1,200°C to achieve coercivity values suitable for permanent magnet applications. These materials deliver cost-stable magnetic performance for motors, sensors, and speakers where high-temperature demagnetization resistance proves essential. Sintered ferrite occupies the dominant volume position across automotive traction motor auxiliary systems, while bonded ferrite captures specialized geometries in consumer electronics miniaturization. Hard ferrite maintains mature pricing structures in industrial machinery segments, and soft ferrite variants address high-frequency power conversion in renewable energy inverters.
China's MIIT enforces GB standards governing magnetic performance consistency and environmental compliance in ferrite manufacturing facilities. The EPA in the United States monitors particulate emissions from ceramic sintering operations, shaping plant location decisions for suppliers serving North American automotive customers. REACH registration requirements in Europe constrain barium and strontium compound handling protocols across the supply chain. Stakeholders must track regulatory divergence between jurisdictions to anticipate certification costs and qualify alternative material formulations before contract renewals.
Market Dynamics
Electric vehicle motor manufacturers are accelerating ferrite-dominant architectures as China's GB standards on rare earth substitution force reformulation across powertrain designs. Sintered ferrite procurement is reorganizing supplier relationships toward East Asian manufacturing clusters with captive ore processing.
Growth Catalysts
- Strontium ferrite substitution:Motor designers in automotive OEMs are replacing neodymium segments with high-coercivity ferrite cores in auxiliary traction systems to hedge rare earth price volatility.
- MIIT environmental compliance mandates:China's updated GB standards on magnetic performance consistency are accelerating facility upgrades that favor large-scale sintering operations with integrated emissions controls.
- Zhejiang manufacturing cluster expansion:Concentrated ferrite powder processing in Shaoxing and Ningbo is reducing logistics costs for bonded magnet compounders serving consumer electronics miniaturization.
Market Restraints
- Barium carbonate input cost volatility:Strontium and barium carbonate prices fluctuate with mining output from Guizhou and Hubei provinces, compressing margin structures for mid-grade ferrite compounders.
- Sintering energy intensity:Kiln operations exceeding 1,200°C require natural gas or electricity inputs that face carbon pricing pressure under China's dual carbon goals and EU CBAM border adjustments.
- Neodymium-iron-boron residual threat:High-performance traction motors in premium EV platforms retain rare earth architectures where ferrite cannot achieve equivalent torque density.
Strategic Opportunities
- India PLI scheme for EV components:Production-linked incentives for electric motor manufacturing are attracting ferrite core suppliers to establish sintering operations in Tamil Nadu and Gujarat.
- Soft ferrite-inverter convergence:Renewable energy power electronics manufacturers are specifying manganese-zinc ferrite cores for high-frequency switching in solar and wind inverters.
- Direct OEM contracting models:Automotive powertrain engineers are bypassing distributor tiers to negotiate multi-year ferrite core supply agreements with volume commitments and technical co-development clauses.
Industry Challenges
- Ceramic sintering process control expertise:Qualified kiln operators and magnetic property testing technicians are scarce in emerging manufacturing locations outside East Asia.
- REACH barium compound registration:European chemical handling protocols for strontium and barium carbonate require extended compliance timelines that delay market entry for new suppliers.
- Legacy motor design integration:Industrial machinery OEMs with established rare earth motor platforms face engineering friction retrofitting ferrite-compatible stator geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrite Magnet Market |
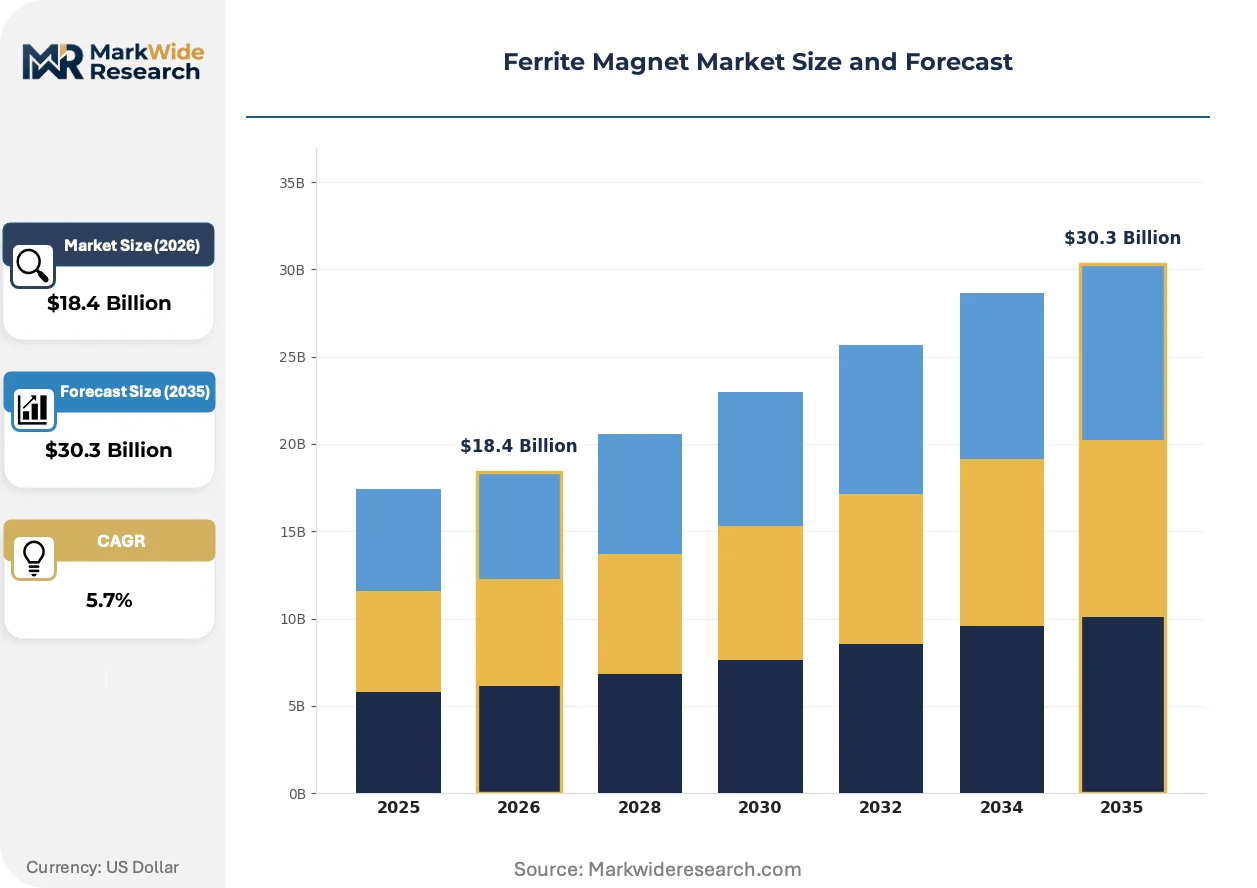
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sintered Ferrite, Bonded Ferrite, Hard Ferrite, Soft Ferrite Application: Automotive, Consumer Electronics, Industrial Machinery, Renewable Energy End User: Manufacturers, Distributors, OEMs, Retailers Distribution Channel: Direct Sales, Online Sales, Retail Outlets, Wholesale |
| Companies Covered | Mitsubishi Materials Trading Corporation, Ningbo Relay Magnetics Co., Ltd., Arnold Magnetic Technologies, Guangdong LingYI Co., Ltd., Hangzhou Permanent Magnet Group, Integrated Magnetics, BGRIMM Technology Group, Proterial, Ltd., TOKYO FERRITE MFG. CO. LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrite Magnet Market Strategic Shifts & Innovations
Magnetic material architectures are fragmenting across performance tiers as end-use specifications diverge between cost-optimized auxiliary systems and premium traction applications. Process innovation in powder metallurgy and regulatory pressure on rare earth supply chains are accelerating formulation experimentation.
Isotropic bonded ferrite compounding is fragmenting the traditional sintered ferrite volume position in consumer electronics. Miniaturized speaker and sensor manufacturers in South Korea and Taiwan are adopting injection-molded ferrite geometries that enable complex pole configurations impossible with conventional ceramic pressing. This technology is fragmenting procurement patterns as electronics OEMs dual-source between bonded compounders and sintered core specialists depending on magnetic flux density requirements.
REACH authorization requirements for barium compounds are tightening handling protocols across European ferrite magnet supply chains. ECHA's substance evaluation processes are extending lead times for strontium carbonate importers serving German and French motor manufacturers. Industrial machinery segments with legacy barium ferrite specifications are most affected, with some OEMs accelerating qualification of strontium-dominant formulations to preempt authorization uncertainty.
Automotive powertrain procurement is consolidating supplier tiers as EV platform engineers prioritize ferrite core consistency over price competition. Tier 1 motor manufacturers are negotiating direct ferrite powder supply agreements with integrated ore processors, displacing traditional magnet distributors in volume contracts. This pattern is most visible in China's Yangtze River Delta, where Zhejiang-based sintering operations are absorbing logistics functions previously handled by independent trading houses.
Ferrite Magnet Market Segmentation
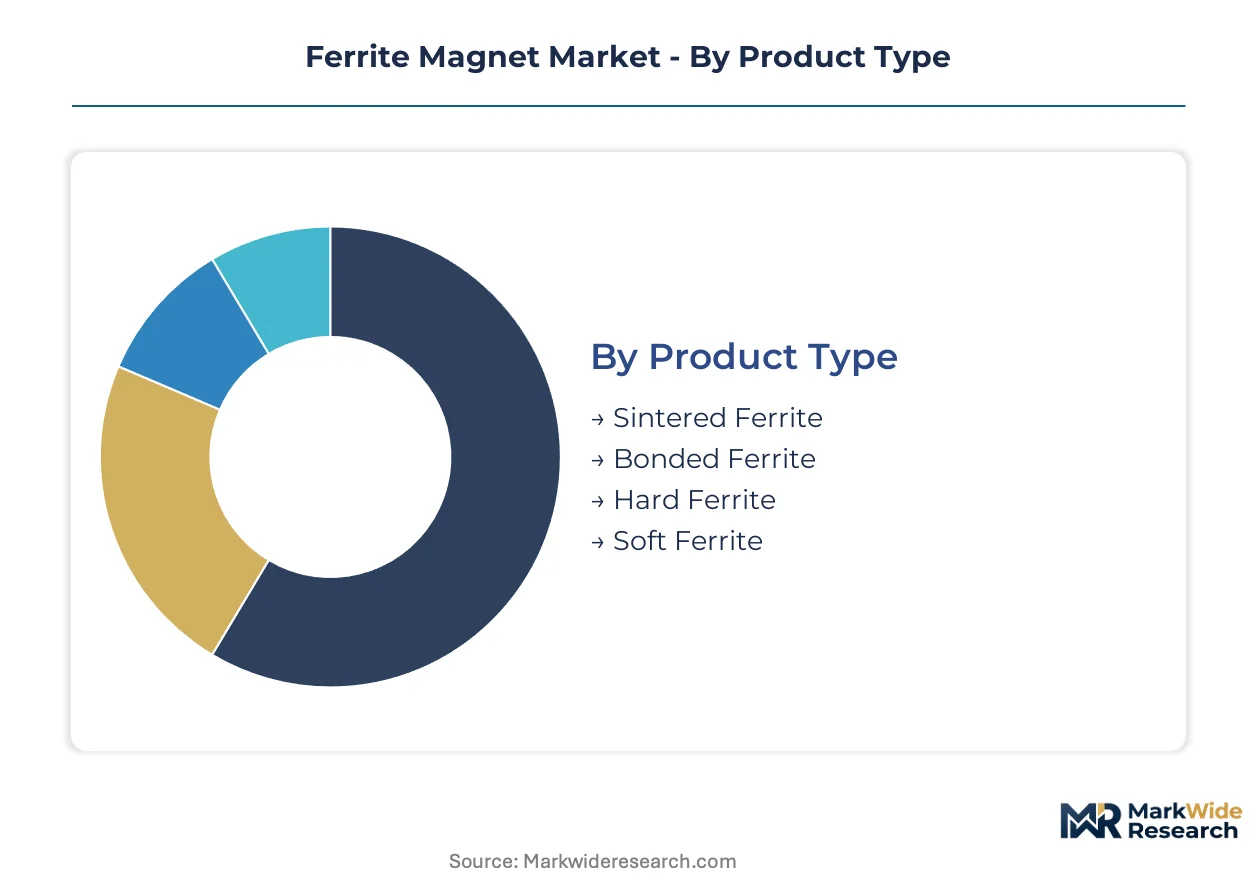
Ferrite magnet procurement patterns diverge sharply across product architectures and end-use specifications. Automotive powertrain engineers prioritize sintered cores for thermal stability, while consumer electronics designers favor bonded formulations for geometric flexibility.
Product Type:
Margin pools concentrate in sintered ferrite operations with captive powder processing and integrated kiln facilities.
- Sintered Ferrite:Ceramic compounds of iron oxide with strontium or barium carbonate, fired above 1,200°C to achieve coercivity values exceeding 3,000 Oersted. Demand concentrates in Zhejiang Province sintering clusters serving domestic Chinese EV auxiliary motor systems, where MIIT environmental compliance mandates favor large-scale operations with emissions controls.
- Bonded Ferrite:Isotropic magnetic powders compounded with polymer binders and injection-molded into complex pole geometries. South Korean and Taiwanese sensor manufacturers are adopting bonded formulations for miniaturized speaker applications where conventional ceramic pressing cannot achieve required dimensional tolerances.
- Hard Ferrite:High-coercivity ceramic magnets retaining magnetic properties under mechanical stress and elevated temperatures. Industrial machinery OEMs specify hard ferrite for conveyor systems and pump motors where operational reliability outweighs premium rare earth performance.
- Soft Ferrite:Manganese-zinc and nickel-zinc formulations optimized for high-frequency magnetic flux with minimal hysteresis loss. Renewable energy inverter manufacturers in Germany and China are specifying soft ferrite cores for switching frequencies above 100 kHz in solar and wind power conversion systems.
Sintered ferrite holds installed capacity across automotive auxiliary systems. Bonded ferrite is rotating up the share rankings in consumer electronics miniaturization.
Application:
Volume concentration tracks EV platform ramp schedules and renewable energy deployment cycles across East Asian manufacturing hubs.
- Automotive:Auxiliary traction motors, power steering systems, and sensor assemblies in electric vehicle architectures. Powertrain engineers at Chinese OEMs are replacing neodymium segments with ferrite cores in non-critical motor functions to hedge rare earth price volatility and comply with GB standards on magnetic material substitution.
- Consumer Electronics:Miniaturized speakers, vibration motors, and magnetic sensors in smartphones and wearables. Taiwan-based electronics contract manufacturers dual-source between bonded compounders and sintered specialists depending on flux density requirements and assembly automation compatibility.
- Industrial Machinery:Conveyor drives, pump motors, and automation equipment where mature pricing structures dominate procurement. German and Japanese machinery OEMs with legacy barium ferrite specifications face engineering friction retrofitting stator geometries for strontium-dominant alternatives.
- Renewable Energy:Power inverters, grid-tie converters, and energy storage system components. Soft ferrite cores address high-frequency switching requirements in solar and wind installations, with manganese-zinc formulations gaining specification in utility-scale inverter designs.
Automotive applications command premium pricing for thermal-grade sintered cores. Renewable energy is expanding most quickly as inverter manufacturers qualify ferrite alternatives to silicon steel laminations.
End User:
Procurement authority is consolidating toward direct OEM contracting models with multi-year volume commitments.
- Manufacturers:Tier 1 motor producers and magnetic component fabricators with in-house sintering or bonding capabilities. These entities negotiate directly with integrated ore processors in China's Yangtze River Delta, displacing traditional distributor tiers in volume ferrite powder agreements.
- Distributors:Independent trading houses and magnet specialists serving fragmented industrial machinery and replacement markets. Margin compression from direct OEM contracting is forcing distributors toward technical service differentiation and small-batch bonded ferrite compounding.
- OEMs:Automotive powertrain engineers and electronics designers with specification authority over magnetic material architectures. EV platform teams are bypassing Tier 1 motor manufacturers to negotiate ferrite core supply agreements with technical co-development clauses.
- Retailers:Industrial supply houses and electronics component distributors serving maintenance-repair-operations demand. These channels capture legacy barium ferrite replacement demand in industrial segments with extended equipment lifecycles.
OEMs are capturing specification authority fastest. Distributors retain relevance in fragmented machinery aftermarket channels.
Distribution Channel:
Channel economics reflect lot size requirements, technical specification complexity, and geographic proximity to sintering clusters.
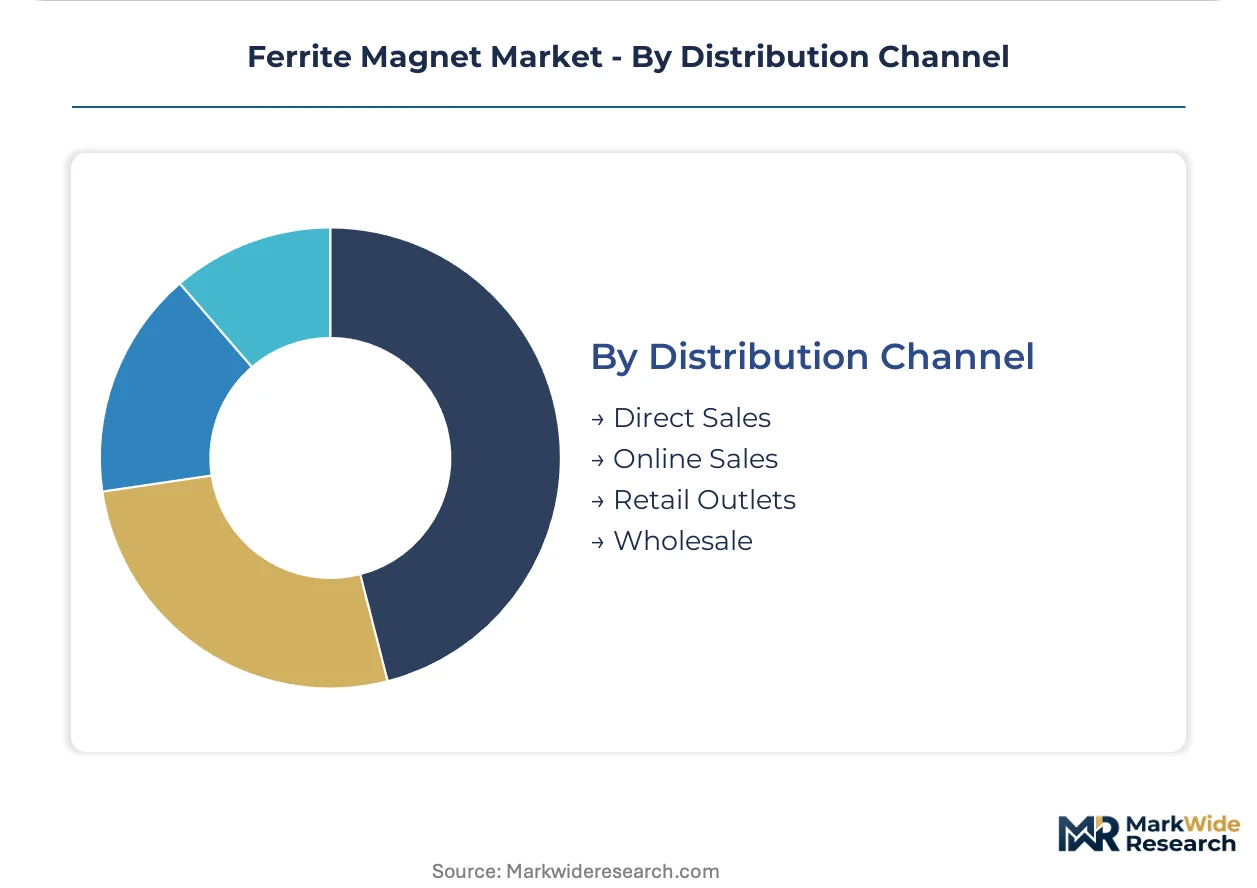
- Direct Sales:Long-term supply agreements between ferrite powder processors and Tier 1 motor manufacturers or automotive OEMs. These contracts incorporate volume commitments, price adjustment mechanisms tied to strontium carbonate indices, and joint development protocols for next-generation core geometries.
- Online Sales:E-procurement platforms and specialized magnet distributors serving research institutions, prototype builders, and small-batch industrial users. Digital channels capture standard-grade bonded ferrite compounds where technical consultation requirements are minimal.
- Retail Outlets:Physical industrial supply locations serving maintenance technicians and legacy equipment operators. These channels concentrate in manufacturing-intensive regions with established machinery installed bases.
- Wholesale:Aggregated purchasing arrangements for bonded ferrite compounders and consumer electronics assemblers. Wholesale tiers consolidate fragmented demand from regional speaker and sensor manufacturers in South Korea and Taiwan.
Direct sales holds contract value concentration. Online channels are gaining transaction volume in standard-grade specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex underwrites China's dominance in ferrite magnet trade, handling raw ore imports and finished magnet exports for the Yangtze River Delta manufacturing corridor. This maritime infrastructure anchors the supply chain for automotive and electronics OEMs sourcing sintered cores.
China
Electric vehicle production lines at BYD and CATL affiliate motor plants are absorbing strontium ferrite cores for auxiliary traction systems. MIIT enforces GB standards on magnetic performance consistency that favor large-scale sintering operations with integrated emissions controls. Shaoxing and Ningbo in Zhejiang Province concentrate captive ore-to-magnet processing facilities serving domestic EV platforms.
Japan
Automotive powertrain engineers at Toyota and Honda are qualifying ferrite-dominant architectures for hybrid vehicle auxiliary motors. METI monitors supply chain resilience for critical magnetic materials under the Economic Security Promotion Act. The Chubu region around Nagoya hosts specialized soft ferrite fabricators supplying power electronics manufacturers.
Germany
Industrial machinery OEMs in the Ruhr region face engineering friction retrofitting legacy barium ferrite stator geometries for strontium-dominant alternatives. ECHA's REACH authorization requirements for barium compounds extend lead times for strontium carbonate importers. Bavaria's automation equipment manufacturers are accelerating qualification of ferrite-compatible motor designs.
United States
EPA-monitored ceramic sintering operations in the Midwest are serving automotive OEMs transitioning from rare earth dependencies. The Inflation Reduction Act's domestic content provisions are reshaping procurement patterns for EV motor components. Arnold Magnetic Technologies leverages its North American production footprint to supply Tier 1 motor manufacturers.
India
Production-linked incentives under the PLI scheme for EV components are attracting ferrite core suppliers to establish sintering operations in Tamil Nadu and Gujarat. The Bureau of Indian Standards is developing magnetic material specifications aligned with automotive electrification targets. Chennai and Ahmedabad are emerging as manufacturing hubs for electric motor assembly with captive ferrite sourcing.
Ferrite Magnet Market Key Industry Players
Concentration sits with integrated ore processors possessing captive sintering capacity and direct OEM contracting relationships. The vendor base organizes around three archetypes: Chinese state-affiliated mining-to-magnet conglomerates with Zhejiang cluster dominance, Japanese precision ceramic specialists serving automotive quality tiers, and North American fabricators leveraging proximity to OEM engineering centers. Competitive moves center on backward integration into strontium carbonate processing and multi-year supply agreements with volume commitments and technical co-development clauses.
Among Japanese precision ceramic specialists, TOKYO FERRITE MFG. CO. LTD. and Proterial, Ltd. occupy positions defined by automotive quality certifications and power electronics specialization. Chinese state-affiliated mining-to-magnet conglomerates include BGRIMM Technology Group, which exemplifies vertically integrated ore processing across multiple ferrite grades. Arnold Magnetic Technologies represents the North American proximity-play archetype, serving automotive OEMs with domestic production footprint advantages. Hangzhou Permanent Magnet Group anchors volume supply relationships for domestic Chinese EV platforms. These named entities illustrate how competitive positioning fragments across geographic specialization, integration depth, and end-use certification requirements.
| Leading Market Players |
|---|
| Mitsubishi Materials Trading Corporation |
| Ningbo Relay Magnetics Co., Ltd. |
| Arnold Magnetic Technologies |
| Guangdong LingYI Co., Ltd. |
| Hangzhou Permanent Magnet Group |
| Integrated Magnetics |
| BGRIMM Technology Group |
| Proterial, Ltd. |
| TOKYO FERRITE MFG. CO. LTD. |
| Others |
Cost & Logistics Intelligence
Strontium carbonate substitution for barium formulations is redrawing procurement geography while compressing margin structures across mid-grade ferrite compounders. China's GB standards on rare earth substitution simultaneously concentrate supply authority in Zhejiang sintering clusters and intensify price competition for automotive auxiliary motor contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive thermal-grade sintered cores from industrial machinery specifications and consumer electronics bonded compounds. Price differentiation hinges on MIIT environmental compliance certification and captive ore processing integration. Cost compression in standard-grade sintered ferrite is intensifying because barium carbonate input volatility from Guizhou mining output feeds directly into contract renegotiations. Tier 1 motor manufacturers demonstrate lowest price sensitivity due to multi-year direct contracting models, while industrial machinery OEMs with legacy specifications face acute margin pressure.
Supply Chain Analysis
China and Japan anchor ferrite magnet production, with Zhejiang Province sintering clusters and Nagoya-area soft ferrite fabricators supplying distinct quality tiers. Raw material flows draw from strontium carbonate deposits in Guizhou and Hubei provinces, manganese-zinc formulations for high-frequency applications, and nickel-zinc compounds for power electronics. Single-source vulnerability concentrates in integrated ore-to-magnet processors with captive kiln operations. Distribution runs through direct sales agreements between powder processors and automotive OEMs, displacing traditional distributor tiers in volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified kiln operators and magnetic property testing technicians are scarce outside East Asian manufacturing corridors, constraining capacity expansion in emerging locations and amplifying acquisition premiums for operations with process control expertise.
For Market Incumbents: Shield margin structures by securing captive strontium carbonate processing capacity ahead of REACH authorization timelines for barium compounds. Prioritize emissions control upgrades at Zhejiang sintering facilities to maintain MIIT compliance certification as a competitive moat against mid-grade compounders facing carbon pricing pressure. For New Entrants and Emerging Players: Anchor in India's Tamil Nadu and Gujarat manufacturing corridors under PLI scheme incentives for EV motor components, where domestic sintering capacity lags projected demand. Target soft ferrite-inverter convergence applications in renewable energy power electronics, leveraging technical partnerships with German inverter manufacturers seeking supply diversification. For Investors and Strategic Acquirers: China's dual carbon goals reshaping energy-intensive manufacturing reshape the acquisition landscape toward processors with integrated emissions controls and renewable power sourcing. Five-to-ten-year viability favors vertically integrated ore-to-magnet operations with direct OEM contracting relationships. Monitor ECHA substance evaluation timelines for barium compound authorization as the signal indicating margin pressure inflection for legacy formulation-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strontium Carbonate Processing | Secures input cost stability against Guizhou mining output fluctuations for Zhejiang sintering operations. |
| MIIT Emissions Control Certification Investment | Qualifies facilities for automotive auxiliary motor contracts under China's updated GB standards. |
| Direct OEM Contracting Model Adoption | Bypasses distributor tiers to capture volume commitments from BYD and CATL affiliate motor plants. |
| Soft Ferrite-Inverter Technical Partnership | Positions manganese-zinc core suppliers for German renewable energy inverter qualification programs. |
| India PLI Scheme Manufacturing Footprint | Establishes sintering capacity in Tamil Nadu ahead of domestic EV platform ramp schedules. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with powertrain procurement directors at automotive OEMs, sintering plant managers in Zhejiang and Nagoya, magnetic materials R&D leads, and ferrite powder trading specialists. Secondary validation incorporated customs trade data for strontium carbonate flows, MIIT facility registration databases, ECHA REACH authorization filings, and SEC disclosures from listed magnet manufacturers. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish volume and value estimates.
Across the analysis window, forecasts segment by product architecture (sintered, bonded, hard, soft ferrite), end-use application (automotive, consumer electronics, industrial machinery, renewable energy), and geographic production cluster. CAGRs were derived from production capacity expansion schedules, EV platform ramp timelines, and inverter deployment cycles. Industry-specific inputs include strontium carbonate price indices, kiln energy cost trajectories under China's dual carbon policy framework, and REACH authorization timeline risk weightings.
Underlying assumptions cover sustained rare earth price volatility maintaining ferrite substitution economics, with deviation risk concentrated in neodymium-iron-boron technology breakthroughs or accelerated barium compound restrictions. Recalibration cycles align with material shifts in MIIT environmental enforcement intensity and ECHA substance evaluation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Cobalt Oxide Market