
 Strontium Nitrate Market | 2026-2036
Strontium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Strontium Nitrate Market Analytics
Chinese strontium carbonate-to-nitrate conversion capacity is consolidating around state-backed chemical zones in Chongqing and Shandong. Solvay leverages its European nitrate purification infrastructure to sustain high-purity output for defense and aerospace buyers. Sakai Chemical Industry anchors East Asian supply through integrated carbonate mining and nitrate finishing operations. American Elements competes on custom synthesis and rare-earth co-processing capabilities in North American specialty channels.
Strontium nitrate is an inorganic salt with the chemical formula Sr(NO₃)₂, typically produced through neutralization of strontium carbonate or strontium sulfide with nitric acid, yielding a white crystalline solid soluble in water and alcohol. The compound serves primarily as an oxidizer in pyrotechnic formulations, where it generates intense red flame coloration, and as a precursor in glass manufacturing and battery electrolyte research. Crystalline grades dominate volume shipments for fireworks manufacturing, while powder forms command premium positioning in precision pyrotechnics and military signaling applications. The defense sector represents the fastest-growing end-user channel as national stockpiling of red-flare munitions and aircraft countermeasure systems intensifies across multiple jurisdictions.
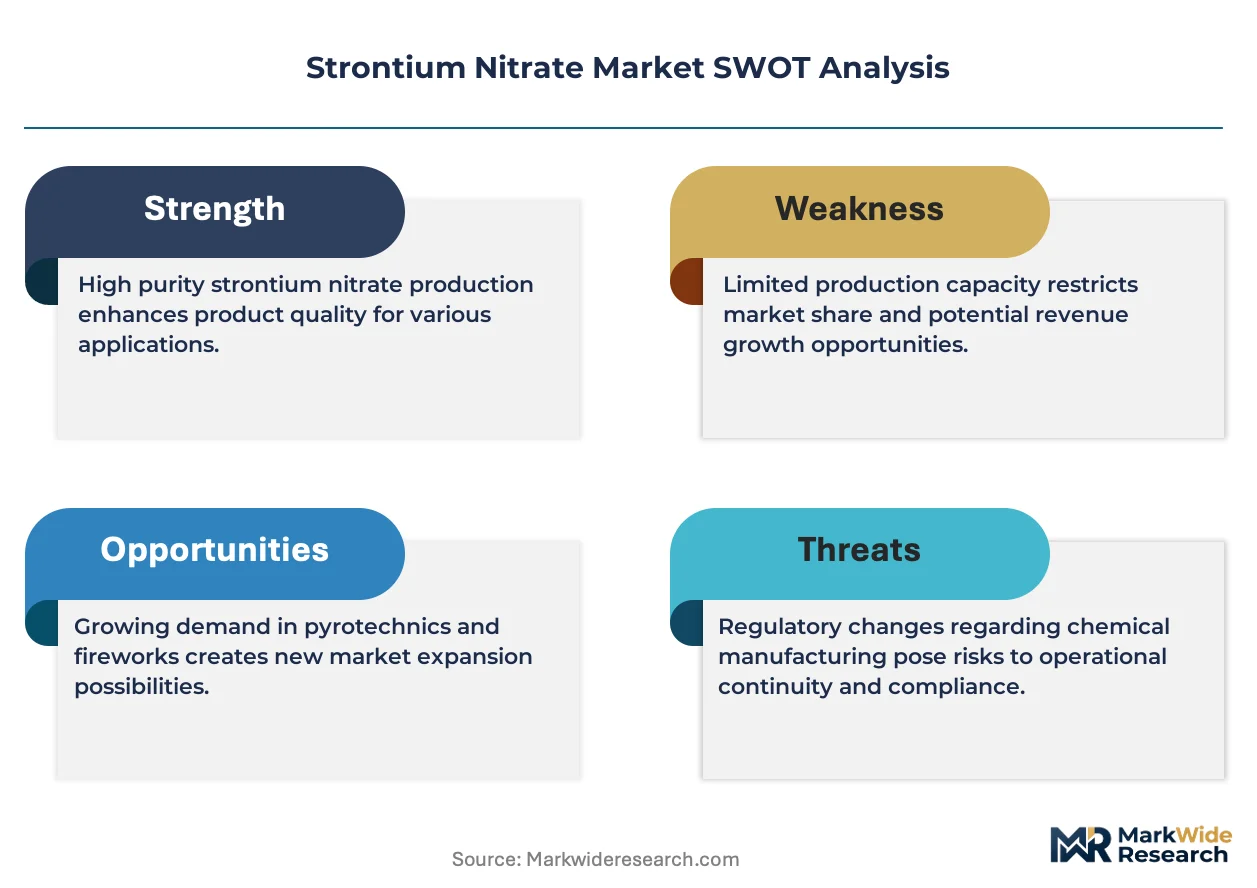
EPA hazardous waste classifications and OSHA permissible exposure limits shape North American handling protocols and facility siting decisions for strontium nitrate processors. REACH registration requirements and the EU Pyrotechnic Articles Directive impose full supply-chain traceability and stability-testing obligations on European importers and blenders. Stakeholders must monitor evolving fireworks safety standards in China and the United States, where municipal bans and shipping restrictions on oxidizer loads threaten traditional distribution architectures.
Market Dynamics
Defense stockpiling of red-flare munitions and aircraft countermeasures is compressing procurement timelines and reshaping capacity allocation across strontium nitrate conversion facilities worldwide.
Growth Catalysts
- Pyrotechnic Articles Directive:EU-mandated supply-chain traceability is forcing formalization of previously informal carbonate-to-nitrate channels, pulling volume into registered processing facilities.
- Countermeasure systems:Military aircraft decoy flares are absorbing crystalline-grade output as NATO and Asia-Pacific defense agencies rebuild depleted inventories.
- Chongqing chemical zones:State-backed consolidation of carbonate conversion capacity is lowering unit processing costs for export-grade material.
Market Restraints
- Strontium carbonate supply:Qinghai and Sichuan mining concentration exposes nitrate converters to single-source geological and licensing risks.
- REACH impurity thresholds:ECHA-mandated heavy metal limits are disqualifying legacy carbonate feedstocks from European pyrotechnic applications.
- Barium nitrate substitution:Green-flare formulations in certain signaling applications are displacing strontium-based red compositions in training munitions.
Strategic Opportunities
- Solid-state battery electrolytes:Strontium nitrate doping in sulfide-based electrolyte research is opening technical-grade demand outside pyrotechnics.
- India PLI scheme:Domestic fireworks manufacturing incentives are creating import-substitution potential for high-purity oxidizer supply.
- Direct-to-blender e-commerce:Specialty chemical platforms are shortening procurement chains for small-batch precision pyrotechnics producers.
Industry Challenges
- Dual-use export licensing:ITAR and national munitions list classifications are delaying shipments to legitimate civilian fireworks manufacturers.
- Stability-testing capacity:UN 1.3G and 1.4G transport certification backlogs are extending inventory holding periods for finished pyrotechnic articles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strontium Nitrate Market |
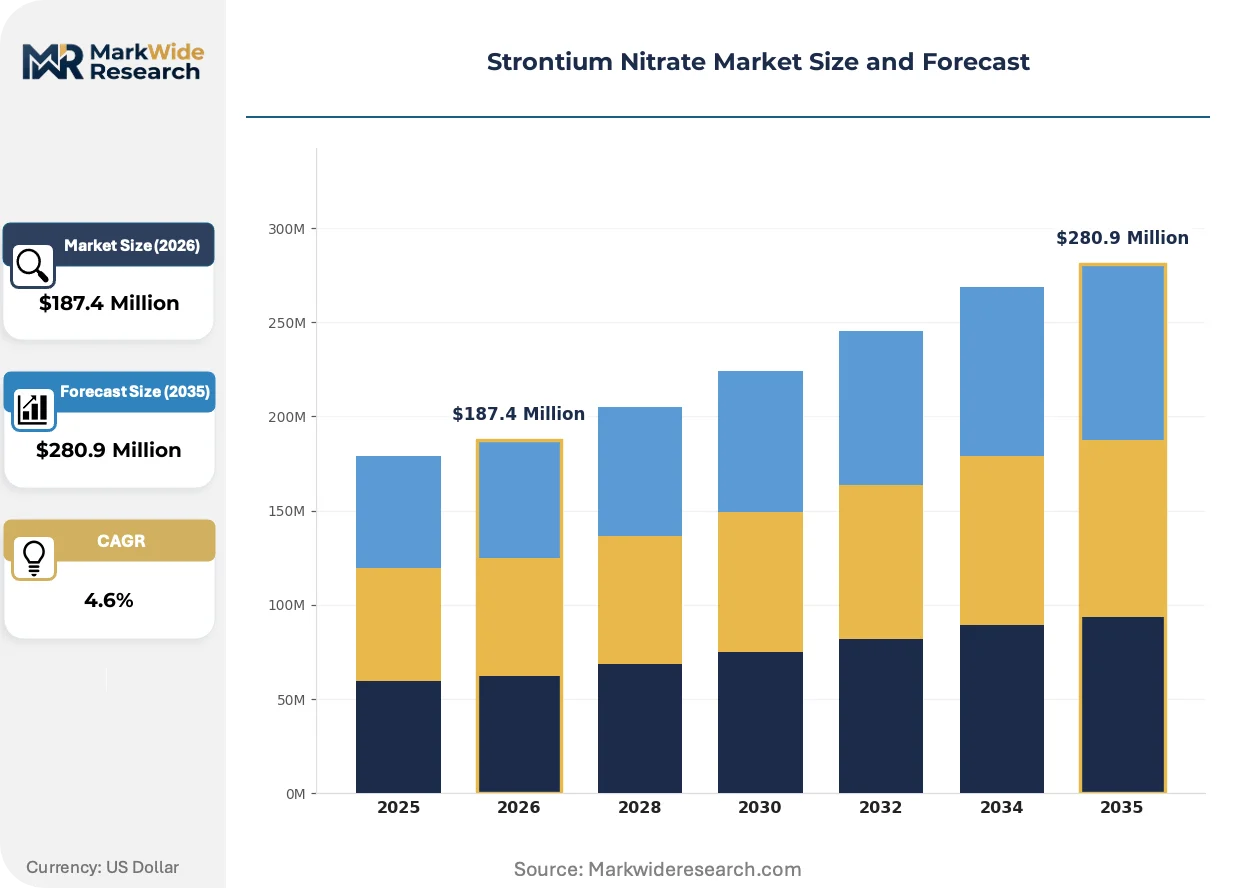
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline, Powder, Liquid, Granular Application: Pyrotechnics, Batteries, Glass Manufacturing, Abrasives End User: Manufacturers, Research Institutions, Educational Facilities, Defense Sector Grade: Technical, Reagent, Industrial, Analytical |
| Companies Covered | Solvay, Sakai Chemical Industry, American Elements, Quimicos Aragonesas, Jinyan Strontium Industry, Joyieng Chemical, Barium & Chemicals, Noah Technologies, ABASSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strontium Nitrate Market Evolving Landscape
Automation in crystallization control and real-time impurity monitoring is compressing batch-to-batch variation and enabling defense-grade certification at commercial-scale throughput.
Continuous-flow nitrate crystallization is automating particle-size distribution control that previously required manual operator intervention. Defense contractors and aerospace flare manufacturers are adopting these systems to meet ITAR-mandated production documentation. The technology is automating quality-assurance labor that formerly consumed 15-20% of conversion facility headcount.
REACH Annex XVII restrictions on lead and heavy metal impurities are forcing carbonate feedstock switching toward chemically precipitated rather than naturally mined strontium sources. European importers now require Certificates of Analysis for every batch crossing customs. Pyrotechnic blenders in Germany and France are absorbing 8-12 week qualification delays as they validate new supply chains.
Specification-driven procurement is consolidating buyer power among defense primes and multinational fireworks distributors. Small and mid-size blenders are losing direct carbonate converter relationships as volume guarantees shift toward annual offtake contracts. This concentration is most visible in the United States, where Phantom Fireworks and TNT Fireworks now dictate oxidizer purity tiers through master service agreements with nitrate finishers.
Strontium Nitrate Market Segmentation
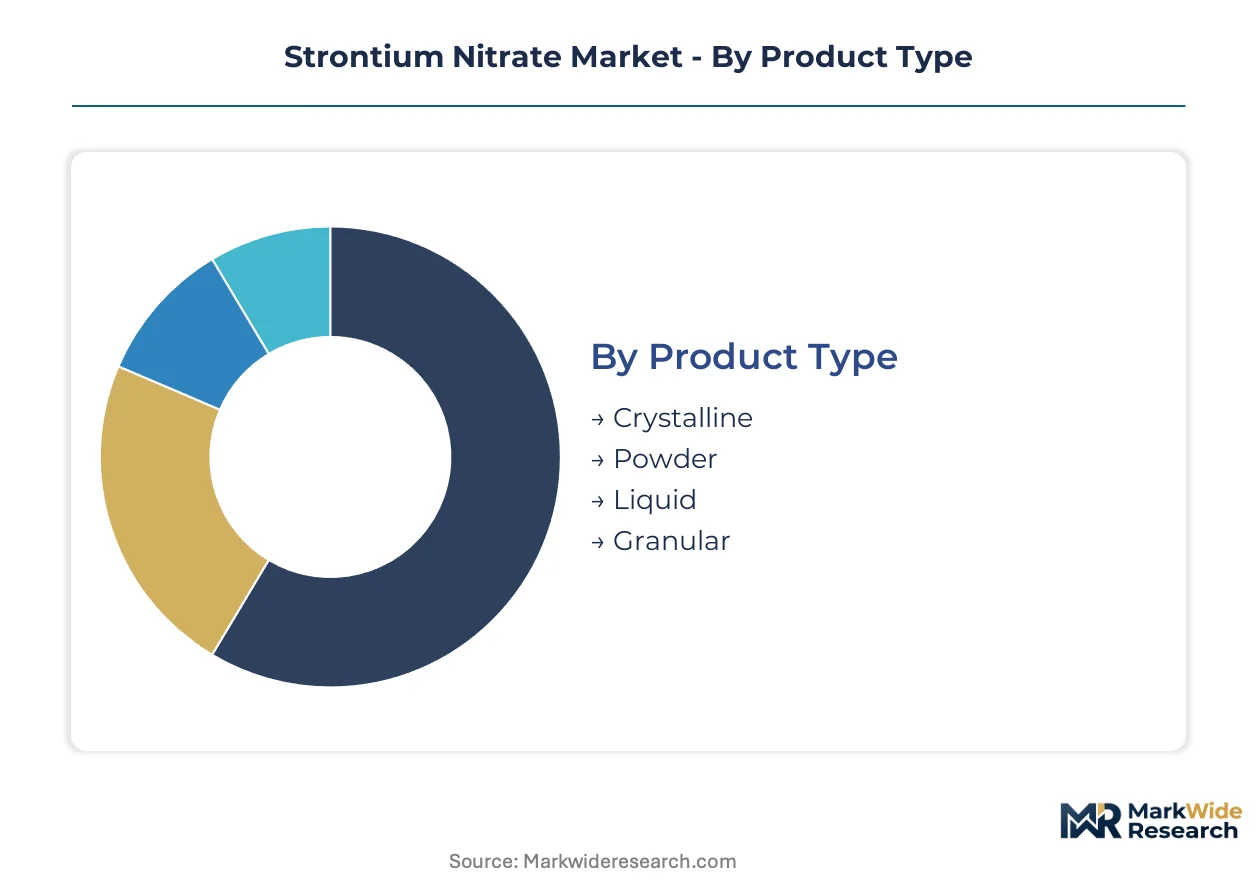
Strontium nitrate procurement patterns diverge sharply between bulk pyrotechnic oxidizer buyers and precision-grade consumers. Segmentation reveals how crystalline grades dominate fireworks manufacturing while powder forms capture defense premiums.
Product Type:
Crystalline grades operate as standalone commodity inputs for high-volume fireworks production, whereas powder and liquid forms embed into precision-mixed formulations requiring tighter particle control.
- Crystalline:Large monoclinic crystals with controlled particle size distribution serve as the primary oxidizer in consumer fireworks. Chinese converters in Chongqing and Shandong ship bulk volumes to Phantom Fireworks and TNT Fireworks under annual offtake contracts.
- Powder:Finely milled material below 100-micron particle size enables uniform dispersion in military flare compositions. NATO defense agencies and aircraft countermeasure manufacturers specify powder grades for ITAR-compliant decoy systems.
- Liquid:Aqueous solutions facilitate direct injection into continuous pyrotechnic mixing processes.
- Granular:Free-flowing agglomerated particles reduce dust exposure during handling operations.
Volume placements concentrate in Crystalline; the faster expansion belongs to Powder.
Application:
Cost-tier stratification separates commodity pyrotechnic oxidizer demand from specialty battery electrolyte and precision glass research applications.
- Pyrotechnics:Oxidizer function in red-flare formulations generates intense 600-620nm emission through strontium ion excitation. REACH-registered European blenders and Chinese export manufacturers absorb crystalline output under UN 1.3G transport certifications.
- Batteries:Dopant in sulfide-based solid-state electrolyte research programs at Samsung SDI and Toyota Battery divisions. Technical-grade nitrate enables controlled strontium incorporation without carbonate contamination.
- Glass Manufacturing:Precursor for strontium oxide in cathode ray tube faceplates and specialty optical glass.
- Abrasives:Controlled crystallization produces hardness-modifying additives for precision grinding compounds.
Pyrotechnics captures the largest volume share; Batteries climbs the fastest as solid-state research accelerates.
End User:
Customer-type concentration drives margin differentiation between defense primes with qualification requirements and educational buyers with minimal technical specifications.
- Manufacturers:Fireworks producers and pyrotechnic blenders purchase crystalline grades in bulk railcar quantities. Chinese state chemical zones and Solvay's European purification facilities compete on carbonate-to-nitrate conversion economics.
- Defense Sector:National stockpiling agencies and aircraft countermeasure primes demand powder-grade material with full batch traceability. ITAR and national munitions list classifications delay shipments and extend procurement timelines.
- Research Institutions:University and national laboratory buyers acquire reagent-grade material for electrolyte synthesis studies.
- Educational Facilities:Secondary and undergraduate chemistry programs use technical-grade material for demonstration experiments.
Manufacturers hold the dominant volume position; the Defense Sector expands most quickly through depleted inventory rebuilding.
Grade:
Maturity-stage divergence separates established industrial-grade channels from emerging analytical-grade specifications in battery research.
- Technical:Standard purity suitable for fireworks and general industrial applications. Chongqing chemical zone producers optimize conversion costs for export-grade technical material.
- Reagent:ACS-grade specifications for laboratory synthesis and quality control procedures. Sakai Chemical Industry and American Elements compete on impurity certification documentation.
- Industrial:Bulk quantities with relaxed heavy metal specifications for non-precision applications.
- Analytical:Ultra-high purity for reference standard preparation and trace analysis methods.
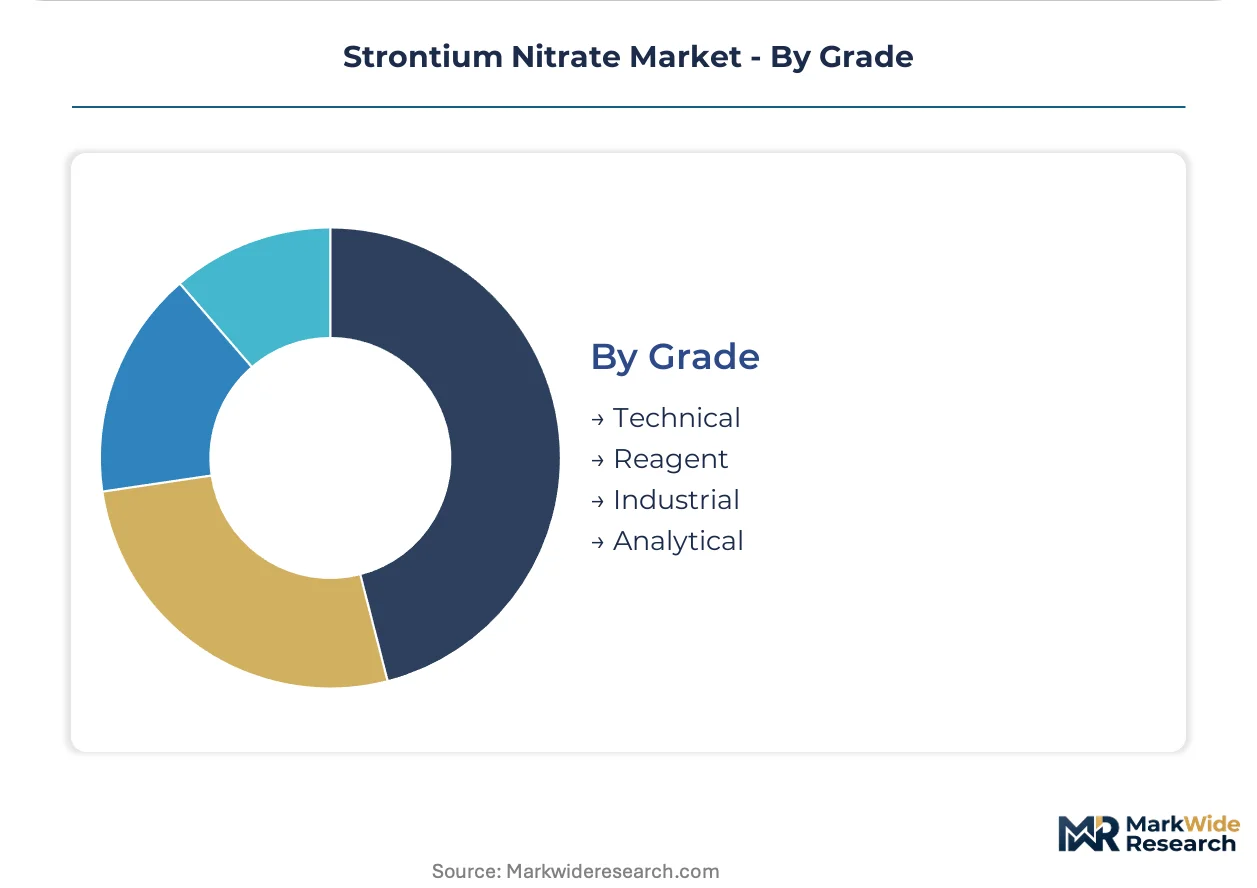
Industrial grade commands the highest shipment volumes; Analytical grade gains share fastest alongside solid-state battery research expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qinghai and Sichuan provinces anchor strontium carbonate mining, concentrating feedstock supply for downstream nitrate conversion across Asia-Pacific and European processing corridors.
China
Chongqing and Shandong chemical zones consolidate state-backed carbonate-to-nitrate conversion capacity for export-grade pyrotechnic oxidizer. MIIT dual carbon goals pressure processors toward emission-controlled crystallization infrastructure. Jinyan Strontium Industry and Joyieng Chemical anchor regional supply chains serving Phantom Fireworks and TNT Fireworks under annual offtake contracts.
United States
Defense stockpiling of aircraft countermeasure flares and red-flare munitions compresses procurement timelines for powder-grade material. EPA hazardous waste classifications and OSHA permissible exposure limits shape facility siting in pyrotechnic manufacturing corridors. Midwestern and southeastern chemical processing clusters absorb crystalline shipments for consumer fireworks distribution.
Germany
REACH-registered pyrotechnic blenders absorb high-purity nitrate for EU-compliant red-flare formulations under Pyrotechnic Articles Directive traceability mandates. ECHA-mandated heavy metal limits disqualify legacy carbonate feedstocks, forcing 8-12 week supply chain requalification delays. Industrial chemical zones in North Rhine-Westphalia and Bavaria host nitrate purification and stability-testing infrastructure.
Japan
Solid-state battery electrolyte research at Samsung SDI and Toyota Battery divisions generates technical-grade demand outside traditional pyrotechnics. METI industrial standards govern chemical purity specifications for defense and aerospace applications. Sakai Chemical Industry anchors East Asian supply through integrated carbonate mining and nitrate finishing operations.
Strontium Nitrate Market Competitive Landscape
Global majors compete with regional champions across purification technology and defense certification tiers. Market structure shows moderate consolidation around European chemical conglomerates and Chinese state-zone processors, with specialty synthesis boutiques occupying niche channels. Three archetypes dominate: integrated carbonate-to-nitrate converters, high-purity defense-grade finishers, and custom synthesis laboratories. Capacity expansion in Chongqing chemical zones and strategic partnerships for ITAR-compliant documentation represent the dominant competitive moves.
Among European-based chemical conglomerates, Solvay exemplifies the high-purity defense-grade finisher archetype through its nitrate purification infrastructure. Sakai Chemical Industry and American Elements occupy positions at opposite ends of the geographic and specialization spectrum—Japanese integrated mining-to-nitrates operations versus North American custom synthesis capabilities. These three represent the tiered competitive structure where carbonate integration, regulatory certification depth, and rare-earth co-processing capabilities differentiate positioning.
| Leading Market Players |
|---|
| Solvay |
| Sakai Chemical Industry |
| American Elements |
| Quimicos Aragonesas |
| Jinyan Strontium Industry |
| Joyieng Chemical |
| Barium & Chemicals |
| Noah Technologies |
| ABASSCO |
| Others |
Value Network & Pricing Analysis
Strontium carbonate spot pricing in Qinghai mining districts cascades through conversion economics into three distinct oxidizer tiers, with REACH-registered European finishers commanding premiums over Chongqing export-grade material and unregistered informal channels operating at suppressed cost baselines.
Pricing Analysis
Warranty and stability-testing bundling separates defense-grade powder pricing from crystalline commodity tiers, with ITAR-compliant documentation and UN 1.4G certification adding substantial service premiums. Three-tier pricing structure across premium, standard, and economy levels reflects grade purity, batch traceability depth, and after-sales technical support inclusion. Price erosion runs through technical-grade crystalline material as Chongqing state-zone capacity expansion intensifies export competition. Small-batch precision pyrotechnics blenders exhibit highest price sensitivity, while NATO defense agencies absorb premiums for qualified powder supply with minimal volume negotiation.
Supply Chain Analysis
Direct-to-blender e-commerce channels handle small-batch precision demand, while bulk railcar shipments serve high-volume fireworks manufacturers through annual offtake contracts. Geographic concentration centers on China, Germany, and Japan, with carbonate mining anchored in Qinghai and Sichuan provinces, purification infrastructure clustered in North Rhine-Westphalia, and integrated mining-to-nitrates operations based in Osaka prefecture. Raw material flows draw from strontium carbonate ore, nitric acid reagents, and precipitated carbonate feedstocks. Single-source vulnerability in Qinghai mining districts exposes converters to geological disruption and licensing suspension risks. Distribution runs through defense prime direct contracts, chemical distributor networks, and emerging specialty platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over carbonate mining licenses and ITAR-compliant finishing capacity determines margin capture, with state-backed Chinese zones and European defense-grade specialists competing on upstream access versus downstream certification depth.
For Market Incumbents: To counter barium nitrate substitution in green-flare training munitions, Solvay and Sakai Chemical Industry should deepen upstream control over chemically precipitated carbonate feedstocks that satisfy REACH Annex XVII heavy metal thresholds. Capacity addition in ITAR-documented powder finishing infrastructure protects defense prime relationships from emerging specialty synthesis competitors. For New Entrants and Emerging Players: Continuous-flow crystallization automation offers a technology-first entry path into defense-grade powder supply, bypassing legacy batch-process capital requirements. White-space targets include India PLI-scheme fireworks manufacturing clusters and solid-state battery electrolyte research programs at Samsung SDI and Toyota Battery divisions. Direct-to-blender e-commerce platforms provide the most penetrable go-to-market angle for small-batch precision pyrotechnics producers. For Investors and Strategic Acquirers: Distressed-cycle entries favor ITAR-registered powder finishers with established NATO defense agency contracts, particularly in Midwestern and southeastern US chemical processing corridors where facility siting constraints limit new entrant supply. Long-term viability hinges on dual-use export licensing navigation capability and carbonate feedstock qualification speed. The signal to watch is UN 1.3G and 1.4G transport certification backlog duration as an inflection indicator for inventory holding pressure and working capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbonate Mining | Qinghai and Sichuan mining licenses secure feedstock supply against geological disruption risks. |
| ITAR-Compliant Documentation Investment | NATO defense agencies mandate full batch traceability for aircraft countermeasure flare procurement. |
| Continuous-Flow Crystallization Deployment | Automation compresses particle-size variation and reduces quality-assurance labor headcount. |
| REACH-Registered Feedstock Switching | Chemically precipitated carbonate satisfies ECHA heavy metal limits for European pyrotechnic applications. |
| Direct-to-Blender E-Commerce Launch | Specialty chemical platforms shorten procurement chains for small-batch precision pyrotechnics producers. |
Research Methodology
Multi-period observation of carbonate spot pricing, defense procurement timelines, and REACH registration compliance rates anchored the trend analysis, supplemented by interviews with plant managers at nitrate conversion facilities, procurement leads at fireworks distributors, technical R&D directors at battery research divisions, and regulatory affairs specialists at pyrotechnic blenders. Secondary validation drew from customs and trade data, SEC 10-K filings of chemical conglomerates, ECHA registration databases, and UN transport certification records. Bottom-up volume modeling across crystalline, powder, liquid, and granular product types triangulated against top-down macroeconomic indicators.
Input-output matrices mapped strontium carbonate feedstock availability through conversion capacity utilization to finished nitrate output across the analysis window, segmented by grade tier, end-use application, and regional production hub. CAGRs were derived from regression analysis of historical shipment volumes and projected capacity expansion schedules. Industry-specific forecast inputs included MIIT dual carbon policy implementation timelines and NATO defense agency inventory rebuilding announcements.
Several conditions sit outside the modeled scope, including municipal fireworks ban enactments, single-source mining license suspensions, and dual-use export licensing moratoria. Forecasts reflect documented assumptions regarding carbonate supply continuity and defense procurement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Solketal Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Polyoxin Market