
 Plastic Bonded Magnet Market | 2026-2036
Plastic Bonded Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Bonded Magnet Market Analytics
Consolidation among automotive tier-one suppliers is repositioning procurement leverage toward high-volume bonded magnet contracts. Magnequench International leverages its rare earth supply chain integration to secure long-term OEM agreements. Arnold Magnetic Technologies sustains differentiation through specialized high-temperature grades for under-hood applications. VACUUMSCHMELZE anchors European demand with precision alloy expertise in thin-walled magnetic components.
Plastic bonded magnets are composite materials formed by embedding ferromagnetic powders—typically neodymium-iron-boron or ferrite—within thermoplastic or thermoset matrices, then shaping through injection molding, compression molding, or extrusion to achieve complex geometries with dimensional tolerances near ±0.05 mm. These bonded structures serve industries requiring net-shape magnetization without secondary machining, particularly in miniaturized motors and sensor assemblies where sintered alternatives would fracture or waste material. Injection molding dominates volume production for intricate automotive sensor housings and consumer electronics micro-motors, while compression molding occupies higher-performance segments demanding elevated magnetic energy products. Ferrite-based compounds lead unit economics in cost-sensitive home appliance applications, whereas neodymium formulations capture premium positioning in electric powertrain and industrial automation systems.
The EPA regulates rare earth processing emissions in the United States, while REACH and RoHS constrain heavy metal content in European-bound magnet assemblies; China's MEE enforces wastewater discharge standards that raise compliance costs for ferrite and neodymium powder producers. These overlapping frameworks fragment certification requirements across export destinations, compelling manufacturers to maintain parallel quality systems. Stakeholders must monitor evolving rare earth export licensing regimes and magnet recycling mandates to anticipate supply disruptions and qualify alternative feedstock sources.
Market Dynamics
Automotive electrification is concentrating procurement volumes among tier-one suppliers capable of certifying bonded magnet traceability under China's tightening GB standards on rare earth processing, compressing supplier qualification timelines and reshaping contract structures toward multi-year OEM agreements.
Growth Catalysts
- Sensor densification in electric powertrains:Each battery-electric vehicle deploys 40-60 bonded magnet assemblies for position sensing and motor control, creating sustained pull from automotive tier-one suppliers.
- China's NMPA traceability mandates:Mandatory rare earth origin documentation under GB/T standards is accelerating formalization of previously fragmented magnet supply chains into auditable supplier networks.
- Injection molding automation:Robotic cavity monitoring and real-time magnetic orientation control are cutting cycle times for complex geometries, expanding bonded magnet viability against sintered alternatives in miniaturized motor applications.
Market Restraints
- Neodymium price volatility:Rare earth oxide spot markets swing 30-50% annually, forcing bonded compounders to absorb margin compression or pass through costs to risk-averse automotive buyers.
- East Asian powder concentration:Over 80% of bonded magnet-grade NdFeB powder originates from Chinese smelters in Inner Mongolia and Jiangxi, creating single-source vulnerability for non-Chinese magnet fabricators.
- Magnetic energy density ceiling:Thermoplastic matrix dilution caps maximum (BH)max at roughly half sintered NdFeB levels, excluding bonded magnets from high-torque traction motor applications.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for electric vehicle subsystems are attracting magnet compounders to establish localized compounding operations in Tamil Nadu and Gujarat.
- Thermoset matrix hybridization:Epoxy-phenolic binders with glass fiber reinforcement are opening bonded magnet applications in 150°C continuous-duty industrial servomotors previously served by sintered rings.
- Magnet-to-stator modular supply contracts:Tier-one motor manufacturers are outsourcing complete magnetic rotor assemblies, creating integrated production slots for compounders with in-house magnetization and balancing capabilities.
Industry Challenges
- Rare earth metallurgist shortage:Bonded magnet formulation requires expertise in powder surface oxidation control and coupling agent chemistry that outstrips current vocational training pipeline output.
- Multi-jurisdiction certification stacking:Simultaneous compliance with EPA air emissions, REACH substance restrictions, and China's MEE wastewater standards extends qualification timelines for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Bonded Magnet Market |
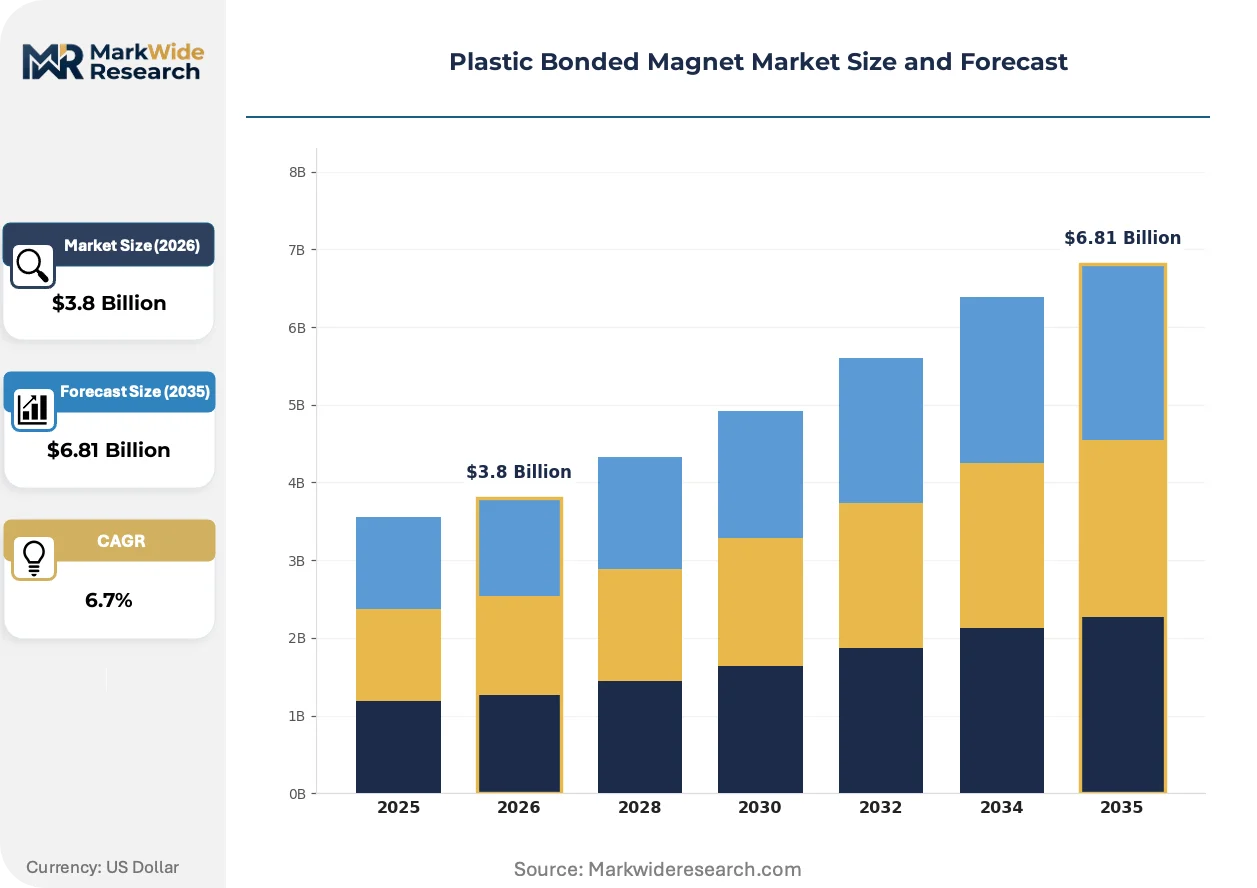
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Compression Molding, Extrusion, 3D Printing Component: Ferrite, Neodymium, Samarium Cobalt, Others Application: Automotive, Consumer Electronics, Industrial Automation, Home Appliances End User: Manufacturers, OEMs, Researchers, Distributors |
| Companies Covered | Magnequench International, Arnold Magnetic Technologies, Bunting Magnetics, Proterial Ltd., TDK Corporation, Ningbo Yunsheng, VACUUMSCHMELZE, MS-Schramberg GmbH & Co. KG, DMEGC Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Bonded Magnet Market Evolving Landscape
Magnet manufacturing is converging with polymer processing automation and AI-driven quality systems, compressing development cycles for application-specific magnetic compounds while regulatory pressure on rare earth traceability forces supply chain digitization.
Multi-cavity hot runner systems with embedded Hall-effect sensors are automating magnetic field alignment verification during injection molding cycles. Automotive sensor manufacturers in Germany and Japan are adopting these systems for volume production of crankshaft position sensors, cutting post-mold magnetization steps and reducing dimensional variation to ±0.03 mm. This automation is compressing the cost gap between bonded and sintered magnets in sub-5 gram magnetic components.
REACH Annex XVII restrictions on heavy metal content are compelling reformulation of ferrite-based bonded magnets for European consumer electronics. Compounders are substituting strontium ferrite for barium grades and eliminating cobalt dopants to maintain coercivity, affecting cost structures in home appliance motor segments. The European magnetic component industry is responding by qualifying alternative powder sources from Indian and Vietnamese ferrite producers.
Automotive OEMs are consolidating magnet procurement through direct long-term agreements with compounders, bypassing traditional distributor channels. This disintermediation concentrates volume commitments among suppliers with certified rare earth traceability and IATF 16949 quality systems. The shift is most visible in China's Yangtze River Delta, where electric vehicle manufacturers in Shanghai and Hefei are negotiating three-year bonded magnet supply contracts with fixed rare earth price escalators.
Plastic Bonded Magnet Market Segmentation
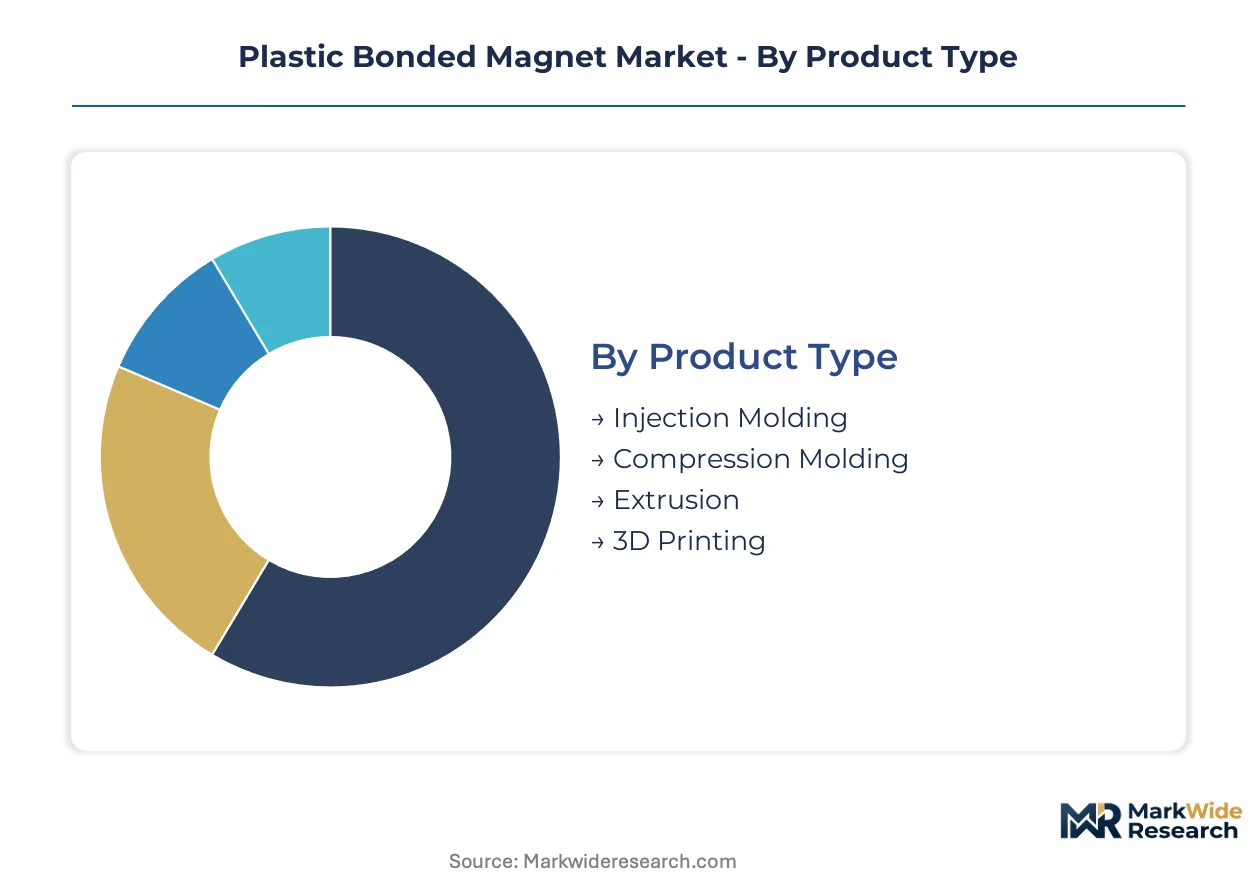
Segmentation in plastic bonded magnets separates high-volume automotive sensor contracts from specialized industrial automation orders, each demanding distinct magnetic energy densities and thermal tolerances. The report maps four intersecting dimensions—manufacturing process, magnetic powder chemistry, end-use application, and buyer type—that collectively determine pricing power and supplier qualification requirements.
Product Type:
Volume production concentrates in injection molding for complex geometries, while compression molding commands premium positioning through elevated magnetic properties.
- Injection Molding:Thermoplastic matrices—typically nylon 6 or PPS—receive NdFeB or ferrite powders before high-pressure cavity filling. Automotive tier-one suppliers in Germany and Japan deploy multi-cavity hot runner systems with embedded Hall-effect sensors for crankshaft position sensors, cutting dimensional variation to ±0.03 mm and eliminating post-mold magnetization.
- Compression Molding:Higher powder loading ratios achieve (BH)max values approaching 12 MGOe, serving industrial servomotors and aerospace actuators where magnetic energy density outweighs geometric complexity. Chinese compounders in Zhejiang province dominate this segment through rare earth supply chain integration.
- Extrusion:Continuous profile production generates bonded magnet strips for refrigerator door seals and linear motor tracks, with cost structures favoring high-volume ferrite formulations.
- 3D Printing:Emerging binder jet and material extrusion methods enable topology-optimized magnetic circuits for custom robotics end-effectors, though layer-wise magnetization alignment remains unresolved for production scaling.
Today's leader: Injection Molding. Tomorrow's challenger: 3D Printing.
Component:
Cost tier separation between commodity ferrite and performance neodymium powders defines supplier margin structures and geographic sourcing strategies.
- Ferrite:Strontium and barium hexaferrite powders blended with thermoplastic binders deliver 1.0-1.5 MGOe at unit costs below neodymium alternatives by an order of magnitude. REACH Annex XVII heavy metal restrictions are forcing European compounders to eliminate cobalt dopants and substitute barium grades, accelerating qualification of Indian and Vietnamese powder sources.
- Neodymium:NdFeB powders with epoxy or PPS matrices achieve 8-10 MGOe, capturing electric powertrain position sensors and miniaturized drone motors. Over 80% of bonded-grade powder originates from Chinese smelters in Inner Mongolia and Jiangxi, creating single-source vulnerability for non-Chinese fabricators.
- Samarium Cobalt:SmCo formulations tolerate continuous operating temperatures to 250°C, serving oil-well logging tools and military avionics where thermal stability overrides material cost.
- Others:Alnico and iron-chromium-cobalt powders occupy niche applications requiring corrosion resistance without rare earth content, primarily marine instrumentation and chemical process sensors.
Ferrite dominates unit economics; neodymium commands technology premiums.
Application:
Customer concentration varies sharply: automotive consolidates procurement among tier-one suppliers, while industrial automation fragments across specialty motor houses.
- Automotive:Each battery-electric vehicle deploys 40-60 bonded magnet assemblies for rotor position sensing, motor control, and transmission actuation. OEMs in Shanghai and Hefei negotiate three-year supply contracts with fixed rare earth price escalators, disintermediating traditional distributor channels.
- Consumer Electronics:Miniaturized vibration motors and acoustic transducers in smartphones and wearables demand sub-5 gram magnetic components with ±0.05 mm tolerances, where bonded magnets displace sintered alternatives through net-shape forming.
- Industrial Automation:Servomotors and linear actuators in factory automation systems require thermoset matrix hybrids for 150°C continuous duty, opening applications previously served by sintered rings.
- Home Appliances:Washing machine direct-drive motors and refrigerator compressor pumps consume ferrite-based bonded magnets in volumes exceeding other segments, though per-unit values remain lowest.
Automotive volumes anchor current revenue; industrial automation offers margin expansion.
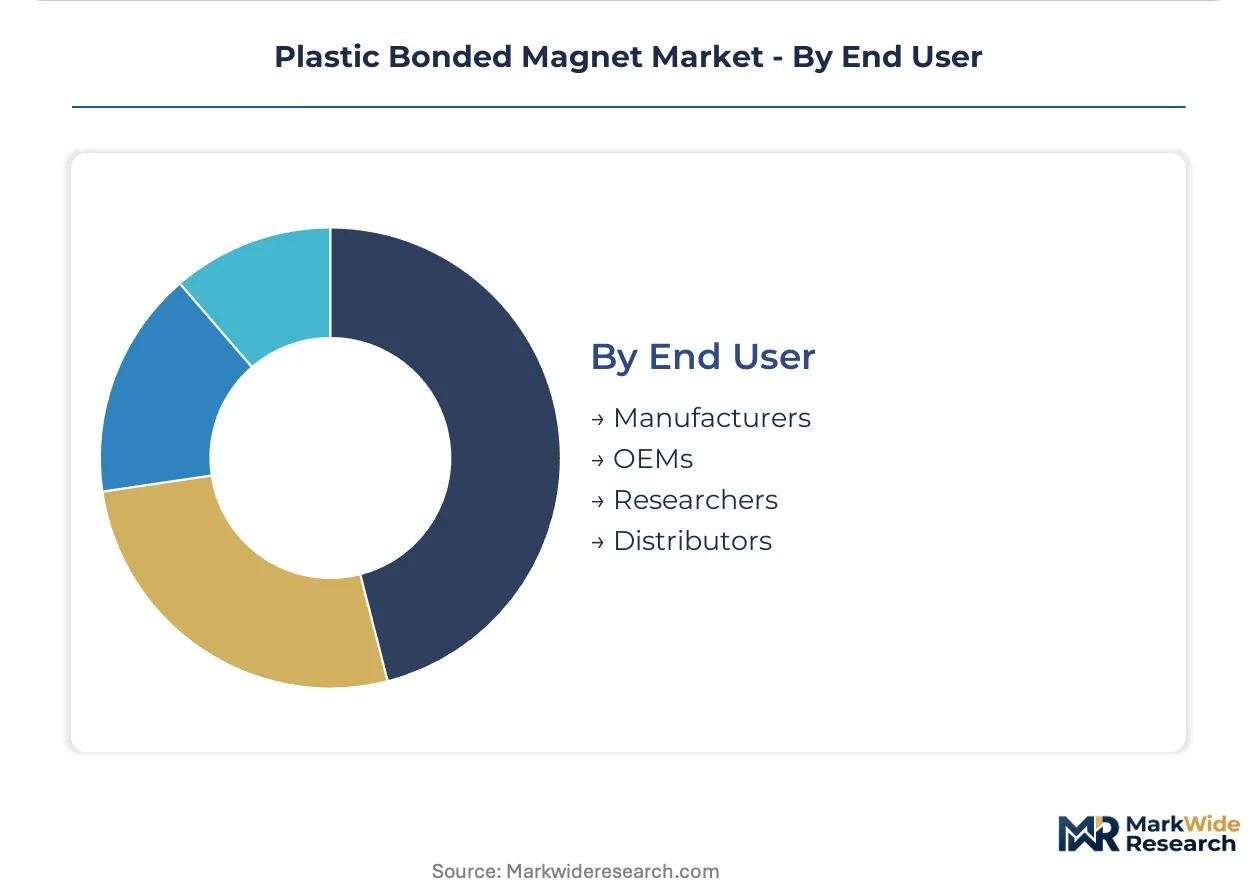
End User:
Procurement authority concentrates with OEMs and large-scale manufacturers, compressing distributor relevance in qualified supply chains.
- Manufacturers:Tier-one motor and sensor producers in Germany, Japan, and China's Yangtze River Delta maintain captive compounding operations or long-term supply agreements with certified rare earth traceability under GB/T standards.
- OEMs:Automotive and appliance original equipment manufacturers increasingly source bonded magnets directly, bypassing component distributors to secure IATF 16949 quality systems and documented supply chain provenance.
- Researchers:National laboratories and university materials science departments prototype novel matrix chemistries and magnetization alignment methods, though commercial volumes remain negligible.
- Distributors:Traditional stocking distributors retain relevance in fragmented industrial maintenance markets and geographic regions lacking qualified compounder presence, particularly Southeast Asia and Eastern Europe.
OEM direct procurement is displacing distributor intermediation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands bonded magnet fabrication capacity while Germany anchors European precision component demand, with both markets diverging sharply on regulatory compliance frameworks and rare earth sourcing strategies.
China
Electric vehicle manufacturers in Shanghai and Hefei negotiate multi-year bonded magnet contracts with fixed rare earth price escalators, bypassing traditional distribution channels. The NMPA enforces GB/T standards mandating documented rare earth origin traceability for all magnet assemblies entering automotive supply chains. Zhejiang and Jiangsu provinces concentrate over 70 percent of national bonded magnet compounding capacity, with Ningbo-based fabricators integrating powder metallurgy and injection molding operations.
Germany
Automotive tier-one suppliers deploy multi-cavity hot runner systems with embedded Hall-effect sensors for crankshaft position sensor production, achieving dimensional tolerances of ±0.03 mm. REACH Annex XVII restrictions on heavy metal content force reformulation of ferrite-based compounds, eliminating cobalt dopants and substituting barium grades. The Baden-Württemberg industrial corridor hosts precision magnetization equipment manufacturers serving both domestic automotive OEMs and export markets.
United States
EPA air emissions regulations constrain rare earth processing operations, raising compliance costs for domestic NdFeB powder production and encouraging reliance on imported bonded compounds. Defense and aerospace applications in California and Texas sustain demand for SmCo formulations tolerating continuous operating temperatures to 250°C. The Department of Defense qualifies alternative rare earth feedstock sources to reduce supply chain vulnerability.
Japan
METI industrial policy supports development of high-temperature thermoset matrix hybrids for 150°C continuous-duty servomotors previously served by sintered rings. Miniaturized vibration motor applications in consumer electronics demand sub-5 gram magnetic components with net-shape forming capabilities. The Nagoya industrial region concentrates precision injection molding operations for automotive sensor housings.
India
The PLI scheme for automotive components attracts magnet compounders to establish localized operations in Tamil Nadu and Gujarat, targeting electric vehicle subsystem manufacturing. BIS certification requirements for imported magnetic materials create qualification barriers for non-domestic suppliers. The Pune-Chennai manufacturing corridor emerges as a secondary sourcing hub for ferrite-based bonded magnets serving home appliance motor segments.
Plastic Bonded Magnet Market Competitive Landscape
Chinese producers anchor the high-volume tier through rare earth supply chain integration; European and Japanese specialists hold premium positioning through precision alloy expertise and IATF 16949 quality systems. The vendor base stratifies across three archetypes: vertically integrated rare earth compounders, specialized high-temperature grade developers, and regional ferrite-focused fabricators. Capacity expansion and multi-year OEM direct procurement agreements constitute the dominant competitive moves, compressing distributor relevance in qualified supply chains.
Among Japanese-anchored fabricators, TDK Corporation and Proterial Ltd. occupy positions within the precision component tier, while VACUUMSCHMELZE exemplifies European specialization in thin-walled magnetic components. These named entities represent archetypal positioning rather than exhaustive market coverage, with each sitting within distinct geographic and technological segments of the bonded magnet value chain.
| Leading Market Players |
|---|
| Magnequench International |
| Arnold Magnetic Technologies |
| Bunting Magnetics |
| Proterial Ltd. |
| TDK Corporation |
| Ningbo Yunsheng |
| VACUUMSCHMELZE |
| MS-Schramberg GmbH & Co. KG |
| DMEGC Magnetics |
| Others |
Value Network & Pricing Analysis
Rare earth oxide spot volatility propagates through bonded magnet pricing tiers, with neodymium powder cost swings compressing compounder margins before reaching automotive OEM contracts in China's Yangtze River Delta and Germany's Baden-Württemberg corridor.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for injection-molded ferrite compounds, while neodymium formulations maintain contract-based long-term offtake structures with fixed escalators. Three-tier pricing structure across premium neodymium, standard ferrite, and economy strontium grades separates IATF 16949-certified suppliers from uncertified fabricators. Cost compression in mid-tier ferrite runs through REACH-mandated cobalt elimination and alternative powder qualification. Tier-one automotive buyers exhibit lowest price sensitivity due to traceability requirements, while home appliance OEMs in India drive hardest bargaining on per-unit ferrite costs.
Supply Chain Analysis
Single-source vulnerability sits with Chinese smelters in Inner Mongolia and Jiangxi provinces, where over 80 percent of bonded-grade NdFeB powder originates. Raw material dependencies center on rare earth oxide concentrates, thermoplastic nylon 6 and PPS resins, and epoxy-phenolic coupling agents. Tariff exposure looms for European and North American fabricators sourcing powder through non-FTA channels. Distribution runs through direct OEM procurement agreements, bypassing traditional distributors in qualified automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic bonded magnet market functions as a stable compounder, with automotive electrification generating predictable volume pull through multi-year sensor and motor contracts.
For Market Incumbents: Lock in multi-year rare earth supply agreements with documented GB/T traceability before NMPA mandates tighten further. Defend position by qualifying alternative Indian and Vietnamese ferrite powder sources to offset REACH reformulation costs. Prioritize thermoset matrix R&D for 150°C industrial servomotor applications previously served by sintered rings. For New Entrants and Emerging Players: Launch via magnet-to-stator modular supply contracts with tier-one motor manufacturers outsourcing complete rotor assemblies. Target India's PLI-subsidized electric vehicle subsystem manufacturing in Tamil Nadu and Gujarat, where BIS certification barriers filter out established foreign suppliers. Penetrate through localized compounding operations serving home appliance motor segments with cost-optimized ferrite formulations. For Investors and Strategic Acquirers: Consolidation pressure builds where rare earth metallurgist scarcity constrains formulation capabilities across mid-tier compounders. Long-term viability favors targets with captive powder sourcing or backward integration into rare earth processing. Watch for inflection in China's export licensing regime, which would signal supply disruption premiums and alternative feedstock qualification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Rare Earth Supply Agreement | Locks in NdFeB powder access under NMPA traceability mandates for automotive OEM contracts. |
| Thermoset Matrix Hybridization | Opens 150°C continuous-duty industrial servomotor applications previously blocked by thermal limits. |
| Magnet-to-Stator Modular Production | Captures integrated rotor assembly slots with tier-one motor manufacturers outsourcing complete units. |
| India PLI Localization | Establishes compounding presence in Tamil Nadu to serve electric vehicle subsystem manufacturing incentives. |
| REACH-Compliant Ferrite Reformulation | Qualifies Indian and Vietnamese strontium powder sources eliminating cobalt dopants for European consumer electronics. |
Research Methodology
Coverage spans China, Germany, Japan, India, and the United States, with primary inputs from each market's bonded magnet fabrication clusters. The research combines interviews with automotive tier-one procurement directors, rare earth compounder plant managers, and magnetic materials R&D leads with secondary validation through customs trade data, SEC filings of listed magnet producers, EPA emissions disclosures, and NMPA regulatory filings. Bottom-up volume estimates from injection molding and compression molding capacity triangulate against top-down automotive sensor and motor deployment forecasts.
Granularity extends to manufacturing process, magnetic powder chemistry, end-use application, and buyer type dimensions across the projection horizon. The analytical framework models electric vehicle content per vehicle, industrial automation motor density, and consumer electronics miniaturization trends. CAGRs derive from segment-level volume trajectories reconciled with rare earth price elasticity assumptions and automotive OEM contract structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under neodymium oxide supply disruption or abrupt REACH substance restriction expansion. Forecasts reflect assumptions regarding NMPA enforcement consistency, PLI scheme renewal in India, and thermoset matrix adoption rates in industrial servomotors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
North America Magnet Market