
 Butyrate Additives Market | 2026-2036
Butyrate Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Butyrate Additives Market Insights
A capital-intensity divergence between integrated chemical producers and specialized feed additive formulators is rotating competitive advantage toward backward-integrated players with captive butyric acid supply. Kemin Industries leverages its global distribution network to sustain premium positioning across multiple geographies. Perstorp anchors its portfolio through proprietary esterification technology that differentiates its tributyrin offerings. BASF competes on manufacturing scale, operating large-volume fermentation and chemical synthesis assets that control unit economics.
Butyrate additives encompass salts and esters of butyric acid, typically formulated as sodium butyrate, calcium butyrate, or tributyrin with purity grades ranging from feed-grade to pharmaceutical-grade, manufactured through chemical synthesis or microbial fermentation for intestinal health modulation, preservation, and odor control. Tributyrin commands higher margin pools due to superior bioavailability and thermal stability in extruded feed processing. Sodium butyrate dominates volume throughput in animal feed applications, while calcium butyrate extends into agrochemical formulations where controlled release properties matter. The pharmaceutical application segment occupies a narrower but defensible niche with stringent purity requirements and longer qualification cycles.
The European Food Safety Authority and the EU Feed Additives Regulation govern market access and re-evaluation protocols for butyrate products in Europe, while the US Food and Drug Administration and Association of American Feed Control Officials shape ingredient definitions and label claims in North America. China's Ministry of Agriculture and Rural Affairs implements domestic feed additive catalog requirements that condition import eligibility and local production licensing. Stakeholders must monitor evolving maximum residue limits and microbiome health claims regulations that will determine which formulations retain commercial viability across jurisdictions.
Market Dynamics
The European Union's Feed Additives Regulation is compressing product registration timelines while elevating compliance documentation requirements, forcing suppliers to restructure their European market entry protocols around EFSA re-evaluation cycles.
Growth Catalysts
- Poultry gut health mandates:Commercial broiler operations in China are expanding sodium butyrate inclusion rates to reduce antibiotic dependency under Ministry of Agriculture and Rural Affairs guidance.
- EFSA re-authorization pathways:The European Food Safety Authority's streamlined microbiome health claim assessments are accelerating novel butyrate formulation approvals for swine nutrition.
- Tributyrin thermal stability:Extruded aquafeed processors in Vietnam and Indonesia are adopting tributyrin over sodium salts to preserve bioactivity through high-temperature pelleting.
Market Restraints
- Butyric acid supply concentration:Captive production of butyric acid feedstock clusters with integrated petrochemical complexes in Germany and China, limiting independent formulator margin control.
- Calcium butyrate substitution pressure:Agrochemical controlled-release applications face displacement from polymer-encapsulated alternatives with longer duration profiles.
- REACH registration costs:The European Chemicals Agency's substance data requirements impose six-figure compliance burdens on tributyrin importers seeking EU market access.
Strategic Opportunities
- Philippine aquaculture expansion:Untapped demand from tilapia and shrimp feed mills in Luzon and Visayas regions offers first-mover positioning for tributyrin suppliers.
- Precision fermentation platforms:Microbial butyric acid production converging with synthetic biology tools enables pharmaceutical-grade purity at feed-grade cost structures.
- US FDA Generally Recognized as Safe self-determination:The FDA's GRAS notification pathway allows faster market entry for novel esterified butyrate formats without pre-market approval delays.
Industry Challenges
- Cross-jurisdiction formulation alignment:Reconciling EFSA microbiome health claim evidence standards with FDA GRAS safety documentation requires duplicative toxicology studies.
- Extrusion thermal degradation mitigation:Feed mill engineering teams lack standardized protocols for butyrate salt recovery rates post-pelleting, complicating dosage verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyrate Additives Market |
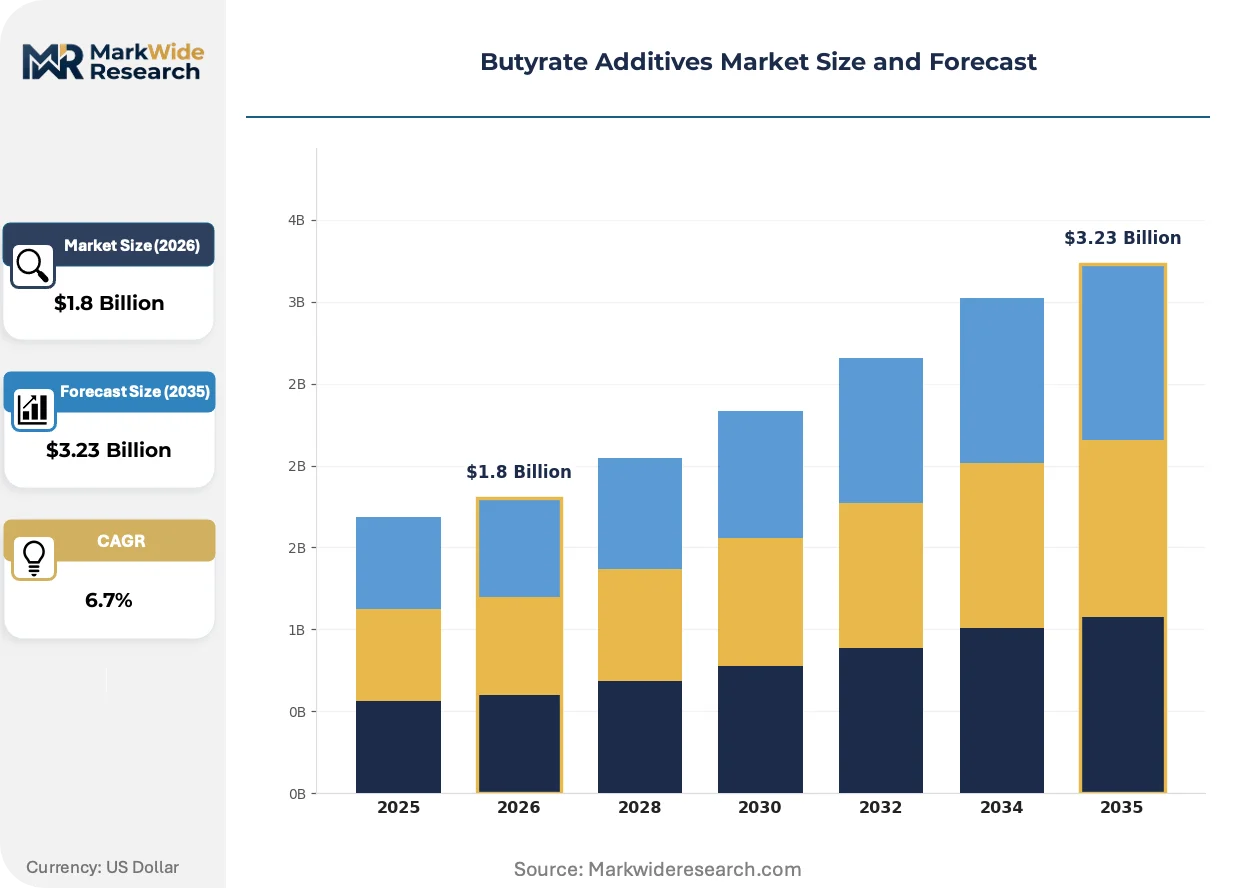
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Butyrate, Calcium Butyrate, Butyric Acid, Tributyrin Application: Animal Feed, Food Preservation, Pharmaceuticals, Agrochemicals End User: Feed Manufacturers, Food Processing Units, Pharma Companies, Crop Protection Firms Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Kemin Industries, Nutreco, Perstorp, Novus International, Palital Feed Additives, Innovad, BASF, Eastman Chemical Company, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyrate Additives Market Trends and Innovations
Microencapsulation technologies and precision fermentation platforms are redrawing the technical frontier for butyrate delivery systems, while regulatory divergence between major jurisdictions is fragmenting product development roadmaps.
Encapsulated sodium butyrate with lipid or polymer coatings is fragmenting the conventional unprotected salt market by enabling ileum-targeted release in monogastric species. Swine nutritionists in Denmark and the Netherlands are specifying coated grades for post-weaning diets despite 40-60% cost premiums. This coating arms race is compressing margins for commodity salt suppliers unable to license protective delivery IP.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon propellants is indirectly pressuring butyrate additive packaging choices by limiting certain aerosolized preservation formats. Manufacturers serving European pharmaceutical and feed-grade markets are pivoting toward nitrogen-flushed bulk containers and modified atmosphere packaging. Tributyrin liquid formats face the steepest packaging reconfiguration costs due to oxidation sensitivity.
Integrated feed compounders in Brazil and Mexico are consolidating procurement decisions at corporate headquarters, displacing decentralized mill-level purchasing. This buyer concentration is forcing additive suppliers to restructure sales organizations around technical account management rather than distributor networks. The shift is most visible in poultry-dense regions of São Paulo state and Jalisco province where three processors control 60% of volume.
Butyrate Additives Market Segmentation
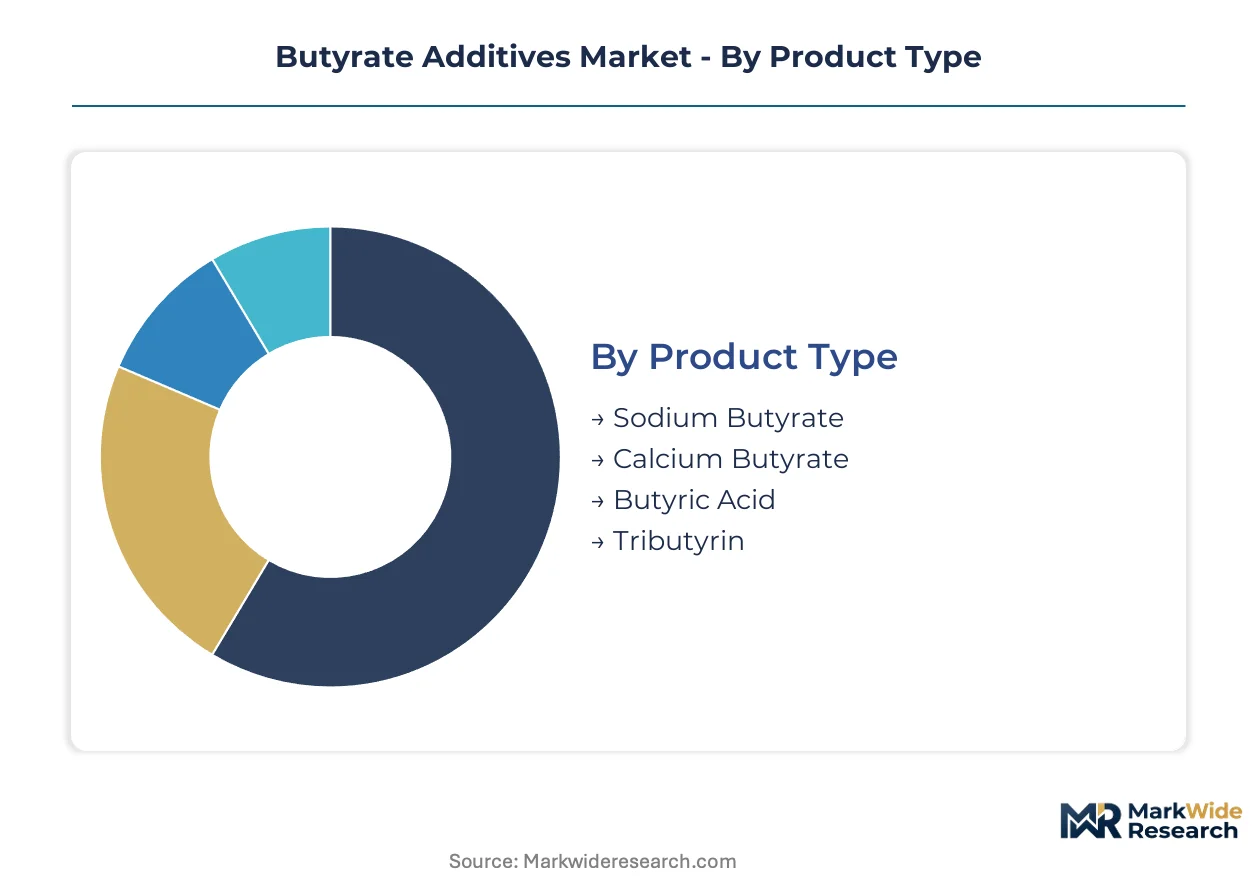
Butyrate additives fragment across four structural dimensions, each carrying distinct margin profiles and regulatory exposure. Product chemistry determines thermal stability and bioavailability thresholds, while application verticals impose divergent purity specifications and qualification cycles.
Product Type:
EFSA feed additive re-evaluations and FDA GRAS pathways impose divergent documentation burdens on salt versus ester chemistries, reshaping supplier R&D allocation.
- Sodium Butyrate:White crystalline salt with hygroscopic properties requiring moisture-resistant packaging. Feed manufacturers in China and Vietnam specify unprotected grades for mash diets, though extrusion losses drive coated variant procurement in Indonesia. EFSA's microbiome health claim assessments favor sodium salt toxicology datasets.
- Tributyrin:Triglyceride ester delivering three butyric acid molecules through enzymatic hydrolysis in the intestinal lumen. Aquafeed processors in Vietnam and Indonesia adopt liquid tributyrin for high-temperature pelleting where sodium salts degrade. FDA GRAS self-determination pathways accommodate novel esterified formats without pre-market delays.
- Calcium Butyrate:Divalent salt with controlled-release characteristics suited to agrochemical encapsulation.
- Butyric Acid:Free acid form requiring corrosion-resistant handling infrastructure and pH buffering in formulation.
Established volume favors sodium butyrate; emerging adoption favors tributyrin.
Application:
Cost tiers separate commodity feed inclusion from pharmaceutical-grade qualification cycles that absorb multi-year development timelines.
- Animal Feed:Poultry and swine gut health programs in China, Brazil, and Germany absorb the majority of sodium butyrate volume under antibiotic reduction mandates. The EU Feed Additives Regulation's streamlined re-authorization accelerates novel formulation market access.
- Pharmaceuticals:Enteric coating and prodrug applications demand pharmaceutical-grade purity with endotoxin limits below established thresholds. CDSCO in India and NMPA in China impose parallel but non-harmonized stability testing protocols.
- Food Preservation:Antimicrobial surface treatments and flavor modulation in fermented products.
- Agrochemicals:Controlled-release fertilizer coatings facing displacement from polymer-encapsulated alternatives.
Feed applications concentrate procurement volume; pharmaceutical pathways concentrate margin extraction.
End User:
Customer consolidation among integrated feed compounders in Brazil and Mexico is displacing decentralized mill-level purchasing, forcing additive suppliers to restructure sales organizations.
- Feed Manufacturers:Corporate headquarters in São Paulo state and Jalisco province now control 60% of volume procurement, demanding technical account management over distributor relationships.
- Pharma Companies:Multinational formulation houses with captive quality assurance teams driving pharmaceutical-grade specification premiums.
- Food Processing Units:Regional dairy and meat processors with variable HACCP implementation depth.
- Crop Protection Firms:Agrochemical formulators evaluating calcium butyrate against polymer-encapsulated controlled-release alternatives.
Procurement consolidation favors feed manufacturers; specification complexity favors pharma companies.
Packaging Type:
The EU F-Gas Regulation's hydrofluorocarbon phase-down indirectly pressures oxidation-sensitive liquid formats toward nitrogen-flushed bulk containers.
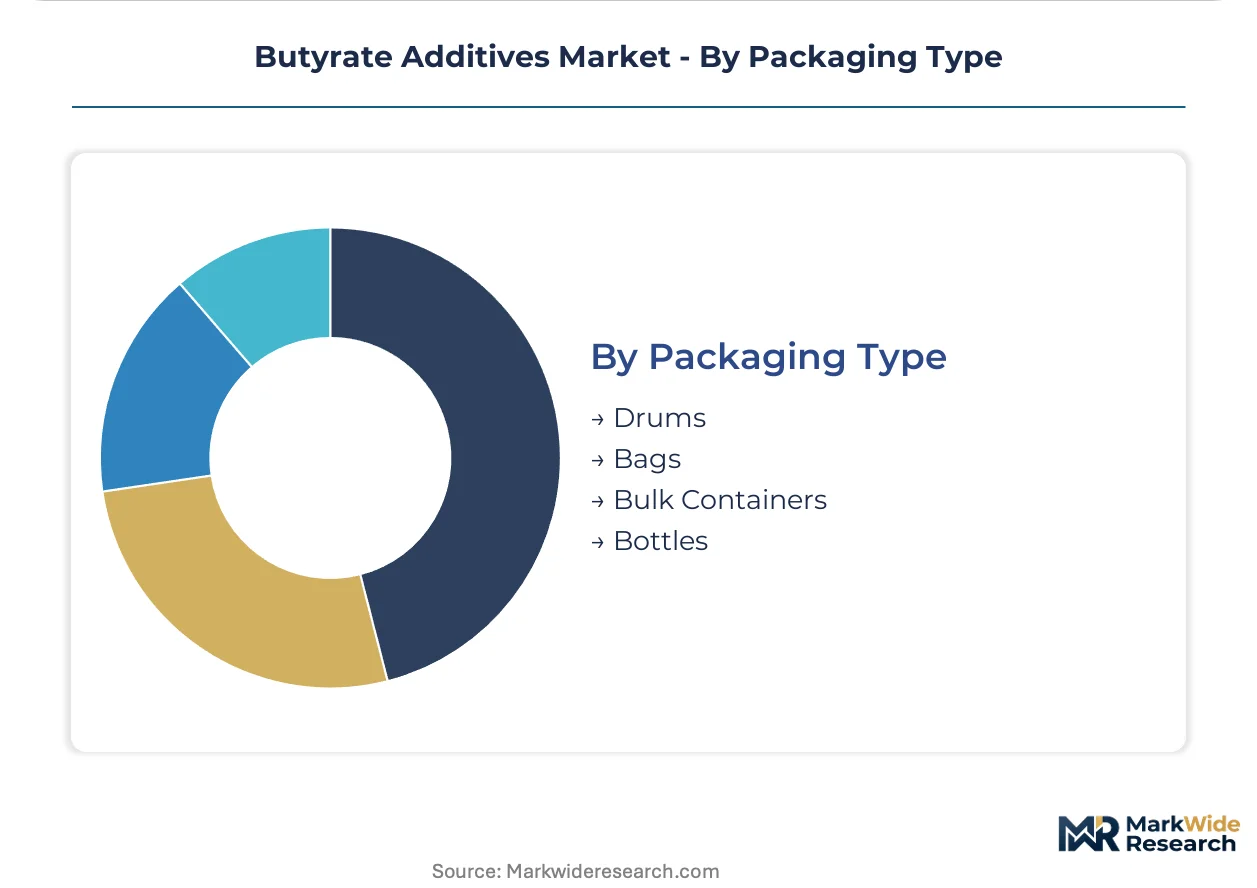
- Bulk Containers:Stainless steel totes and flexible intermediate bulk containers for integrated compounders with on-site blending infrastructure.
- Drums:Steel and HDPE formats for mid-volume processors lacking bulk handling systems.
- Bags:Multi-wall paper and woven polypropylene for sodium and calcium salt distribution.
- Bottles:Amber glass and fluorinated polymer for pharmaceutical-grade liquid tributyrin.
Scale economies favor bulk containers; regulatory compliance favors modified atmosphere alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland exceeds that in Vietnam and Indonesia by substantial margins, reflecting divergent regulatory burden structures and end-use specification intensity across geographies.
China
Poultry and swine gut health programs absorb sodium butyrate volume under Ministry of Agriculture and Rural Affairs antibiotic reduction guidance. The country's feed additive catalog conditions import eligibility and local production licensing for tributyrin suppliers. Yangtze River Delta feed compounders in Jiangsu and Zhejiang provinces are consolidating procurement decisions at corporate headquarters.
Germany
Integrated petrochemical complexes in the Rhine-Ruhr and Ludwigshafen clusters control captive butyric acid feedstock supply for downstream additive formulators. EFSA re-evaluation cycles and REACH registration requirements impose six-figure compliance burdens on market entrants. Bavarian swine nutritionists specify microencapsulated sodium butyrate grades for post-weaning diets despite substantial cost premiums.
United States
FDA GRAS self-determination pathways accelerate market entry for novel esterified butyrate formats without pre-market approval delays. The Association of American Feed Control Officials shapes ingredient definitions and label claims for sodium and calcium salt applications. Midwest poultry operations in Iowa and Arkansas are expanding butyrate inclusion rates to reduce antibiotic dependency.
Vietnam
Extruded aquafeed processors in the Mekong Delta adopt liquid tributyrin for high-temperature pelleting where sodium salts degrade. The country's national feed safety regulator implements parallel but non-harmonized stability testing protocols with ASEAN neighbors. Catfish and shrimp feed mills in Cần Thơ and An Giang provinces drive bulk tributyrin consumption growth.
Brazil
Integrated feed compounders in São Paulo state consolidate procurement decisions at corporate headquarters, displacing decentralized mill-level purchasing. ANVISA and the national agricultural ministry impose veterinary product registration timelines that compress supplier margin structures. Poultry-dense regions of São Paulo and Paraná states concentrate additive demand among three processors controlling the majority of volume.
Butyrate Additives Market Competitive Landscape
Concentration sits with backward-integrated chemical producers possessing captive butyric acid supply, while specialized feed additive formulators compete on delivery technology and technical service. The vendor base separates into three strategic archetypes: integrated petrochemical majors with fermentation and synthesis assets, mid-cap specialists with proprietary esterification or encapsulation IP, and regional distributors with formulation blending capabilities. Competitive moves center on capacity expansion in high-growth Asian markets and technology licensing agreements for microencapsulation delivery systems.
Among integrated chemical producers, BASF and Eastman Chemical Company occupy positions defined by manufacturing scale and global distribution infrastructure. Perstorp exemplifies the technology-specialist archetype through its proprietary esterification capabilities. Kemin Industries anchors the technical service and formulation tier with its global account management model for poultry and swine nutrition programs.
| Leading Market Players |
|---|
| Kemin Industries |
| Nutreco |
| Perstorp |
| Novus International |
| Palital Feed Additives |
| Innovad |
| BASF |
| Eastman Chemical Company |
| Celanese Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH registration requirements gate both supply qualification and price differentiation simultaneously, as six-figure compliance burdens filter out low-volume tributyrin importers while enabling registered suppliers to command certification premiums across European feed and pharmaceutical channels.
Pricing Analysis
Configured-to-order pricing for microencapsulated sodium butyrate commands substantial premiums over standard unprotected salt grades, with coating technology licensing fees and ileum-targeted release specifications driving differentiation. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and agrochemical-grade purity levels separates specification intensity, with endotoxin limits and thermal stability thresholds as key price drivers. Cost compression in commodity salt tiers is intensifying because Chinese domestic production scales and captive butyric acid supply from integrated petrochemical complexes compress independent formulator margins. Integrated feed compounders in Brazil and Mexico exhibit lowest price sensitivity due to procurement consolidation at headquarters level, while regional distributors in Southeast Asia face highest sensitivity due to fragmented mill-level purchasing.
Supply Chain Analysis
Strategic stockpiling of butyric acid feedstock dominates inventory strategy among integrated chemical producers in Germany and China, insulating downstream additive formulators from spot market volatility. Captive production clusters in the Rhine-Ruhr and Ludwigshafen regions of Germany alongside Yangtze River Delta facilities in China anchor global supply, drawing from petroleum-derived feedstocks and fermentation platforms respectively. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade tributyrin, where proprietary esterification technology limits qualified suppliers. Distribution runs through technical account management teams serving consolidated feed compounders, displacing traditional distributor networks in poultry-dense regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary encapsulation IP and captive butyric acid supply represent scarce capabilities that determine competitive viability, with technology licensing gaps separating defensible market positions from commodity exposure.
For Market Incumbents: Compound defensive positioning through backward integration into butyric acid feedstock production and accelerated EFSA re-evaluation cycle participation. Threats from precision fermentation platforms and novel esterified formats require capacity expansion in Vietnam and Indonesia aquafeed corridors, while microencapsulation IP licensing controls channel access against polymer-encapsulated substitutes. For New Entrants and Emerging Players: FDA GRAS self-determination pathways accelerate market entry timelines for novel butyrate formulations without pre-market approval delays. White-space targets include Philippine tilapia and shrimp feed mills in Luzon and Visayas regions, where tributyrin adoption lags Vietnamese benchmarks, and precision fermentation-derived pharmaceutical-grade production at feed-grade cost structures. Go-to-market execution should anchor on technical service partnerships with integrated compounders seeking antibiotic reduction compliance. For Investors and Strategic Acquirers: EFSA's streamlined microbiome health claim assessments reshape the acquisition landscape by elevating toxicology dataset value and accelerating novel formulation approval timelines. Long-term viability favors backward-integrated specialists with captive butyric acid supply and proprietary delivery technology, as commodity salt suppliers face margin compression from coating arms races. The signal to watch is Ministry of Agriculture and Rural Affairs catalog expansion for tributyrin import eligibility, which would unlock Chinese volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butyric Acid Feedstock | Captive supply from Rhine-Ruhr petrochemical complexes insulates margin control against independent formulator competition. |
| Microencapsulation Technology Licensing | Ileum-targeted release IP commands 40-60% cost premiums in Bavarian and Dutch swine post-weaning nutrition programs. |
| Precision Fermentation Platform Deployment | Synthetic biology-enabled pharmaceutical-grade purity at feed-grade cost structures disrupts incumbent manufacturing economics. |
| EFSA Re-Evaluation Cycle Participation | Streamlined microbiome health claim assessments accelerate novel sodium butyrate formulation market access across EU member states. |
| Technical Account Management Restructuring | Direct engagement with São Paulo and Jalisco corporate headquarters displaces distributor networks controlling 60% of Brazilian volume. |
Research Methodology
A standing panel of feed formulation directors, regulatory affairs specialists at EFSA and FDA, procurement leads at integrated compounders, and technical R&D directors at additive suppliers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Feed Additives Regulation re-evaluation dossiers, REACH registration databases, Ministry of Agriculture and Rural Affairs catalog amendments, and Association of American Feed Control Officials ingredient definition updates. Bottom-up volume modeling across product chemistry tiers and application verticals triangulated against top-down market sizing from petrochemical feedstock throughput and fermentation capacity disclosures.
Consistency checks against external benchmarks validated output plausibility across the projection horizon, with modeled dimensions spanning product type, application vertical, end-user concentration tier, and regional regulatory cluster. CAGRs were derived from segment-level volume trajectories weighted by price realization trends, incorporating butyric acid feedstock cost curves, extrusion thermal degradation recovery rates, and microbiome health claim approval timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable REACH registration cost structures and continued EFSA re-evaluation streamlining; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding antibiotic reduction mandate continuity in China and Brazil, tributyrin thermal stability adoption curves in Southeast Asian aquafeed, and precision fermentation platform commercialization timelines. Revision becomes warranted when EFSA microbiome health claim evidence standards diverge from FDA GRAS safety documentation requirements, forcing duplicative toxicology study burdens that compress supplier R&D allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Calcium Diglutamate Market
Additives
Global UV Stabilizers Market
Additives
Humectants Market
Additives
Middle East Feed Additives Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Sorbitan Laurate Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Bromine Derivatives Market
Additives
Inorganic Filler Market
Additives
Triazine UV Absorber Market
Additives
Conditioning Agent Market
Additives
India Feed Additives Market
Additives
North America Potassium Nitrate Market
Additives
Sodium Diacetate Market
Additives
Hydroxyethyl Cellulose Market
Additives
Gasoline Additives Market