
 Middle East and Africa Magnet Wire Market | 2026-2036
Middle East and Africa Magnet Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Magnet Wire Market Foresight
Renewable energy generator manufacturing is broadening the end-use vertical mix for magnet wire across the Middle East and Africa. Superior Essex anchors North African supply through its specialized enameled wire operations. Sumitomo Electric Industries leverages deep R&D intensity in high-temperature insulation systems. Southwire Company competes aggressively on manufacturing scale for transformer-grade conductors.
Middle East and Africa magnet wire consists of insulated electrical conductors, typically copper or aluminum, coated with polymer-based enamel films between 0.02 mm and 0.50 mm thick to enable tight winding in electromagnetic coils. These conductors transmit electrical energy into magnetic energy within motors, transformers, and inductive devices operating at frequencies from 50 Hz to several hundred kHz. Copper magnet wire dominates value pools due to superior conductivity and thermal performance in high-slot-fill applications. Specialty magnet wire, including corona-resistant and self-bonding grades, captures expanding margin pools as Gulf utilities upgrade grid infrastructure. Enameled magnet wire remains the volume backbone across electromotor and transformer applications.
Saudi Arabia's SFDA and the UAE's MOHAP enforce electrical equipment safety frameworks that shape product certification and import compliance for magnet wire assemblies. South Africa's NRCS applies SANS standards that mandate thermal class ratings and insulation integrity testing for industrial motor windings. Stakeholders must monitor evolving Gulf Cooperation Council harmonization efforts and local content requirements that will determine competitive access across the region's electrification projects.
Market Dynamics
Gulf utilities are accelerating grid modernization timelines, compressing procurement cycles for high-temperature magnet wire grades while South Africa's automotive sector demands tighter slot-fill tolerances in electrified powertrains.
Growth Catalysts
- SFDA Electrical Equipment Directives:Saudi Arabia's tightened certification frameworks are mandating thermal class upgrades for industrial motor windings, forcing replacement demand across petrochemical processing facilities.
- UAE Renewable Integration Targets:Dubai's clean energy strategy 2050 is electrifying generator manufacturing clusters in Jebel Ali, expanding addressable demand for corona-resistant magnet wire specifications.
- Copper Conductivity Premiums:High-frequency inverter applications in Gulf manufacturing zones are favoring oxygen-free copper magnet wire over aluminum alternatives in precision winding operations.
Market Restraints
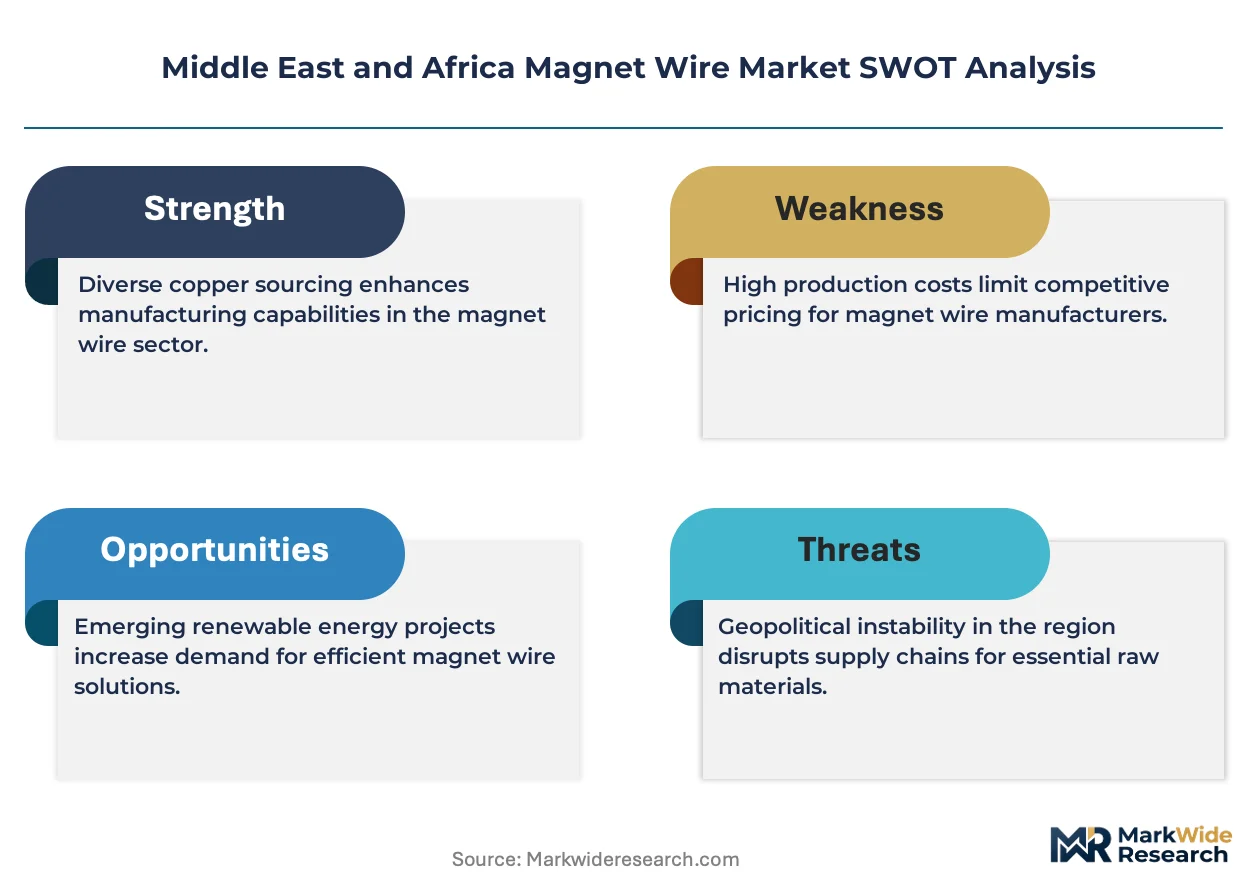
- LME Copper Volatility:Raw material cost swings are compressing margin buffers for transformer-grade conductor producers serving North African project markets.
- Specialty Insulation Concentration:Polyimide and polyamide-imide enamel supply clusters in East Asian chemical hubs expose MEA fabricators to extended lead times and currency mismatch risks.
- Aluminum Substitution Pressure:Weight-driven automotive specifications are displacing copper magnet wire in select auxiliary motor categories across South African vehicle assembly plants.
Strategic Opportunities
- Egyptian Manufacturing Zones:Suez Canal Economic Zone incentives are attracting magnet wire downstream processing capacity to serve Levant and East African electrification projects.
- Self-Bonding Wire Adoption:Coil-forming automation in UAE industrial corridors is converging with thermoplastic enamel technologies to eliminate post-winding varnish cycles.
- MOHAP Medical Device Harmonization:UAE healthcare equipment safety frameworks are creating certification pathways for MRI and imaging system magnet wire suppliers.
Industry Challenges
- Enamel Application Technician Scarcity:Thin-film coating expertise for sub-0.05 mm conductor specifications remains concentrated in East Asian and European technical institutes, constraining Gulf-based quality scaling.
- SANS Thermal Class Testing Bottlenecks:South Africa's NRCS accreditation timelines for revised insulation integrity protocols are extending product launch cycles by 4-6 months for industrial motor OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Magnet Wire Market |
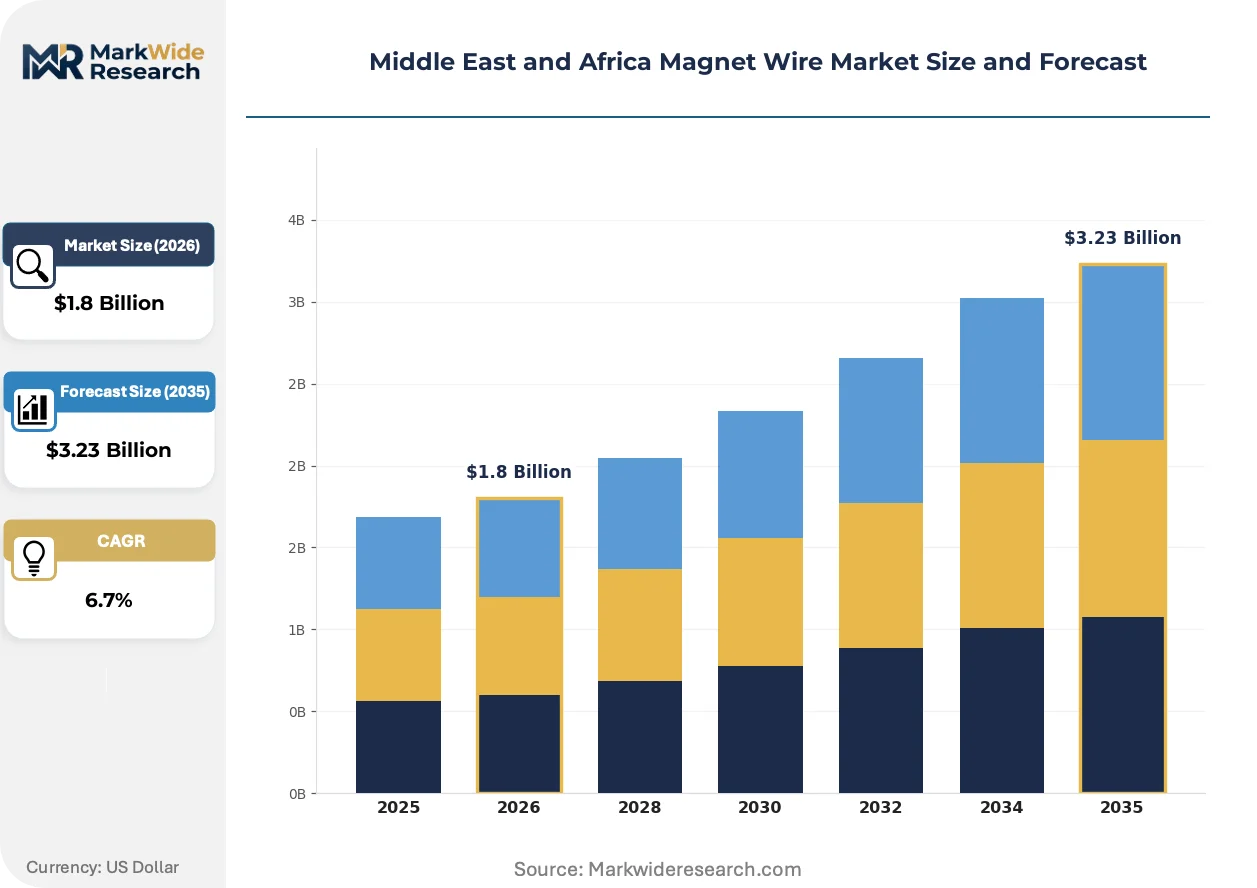
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Magnet Wire, Aluminum Magnet Wire, Specialty Magnet Wire, Enameled Magnet Wire Application: Electromotors, Transformers, Inductors, Generators End User: Electronics, Automotive, Aerospace, Industrial Machinery Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Sumitomo Electric Industries, Southwire Company, Superior Essex, Hitachi Metals, General Cable, Furukawa Electric, LS Cable & System, Elektrisola, Rea Magnet Wire Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Magnet Wire Market Shifts & Advancements
Polymer chemistry advances and coil manufacturing automation are compressing traditional specification boundaries between standard and specialty magnet wire grades across Middle East and Africa industrial demand centers.
Corona-resistant enameled wire formulations with nano-filled polymer matrices are electrifying high-voltage inverter-fed motor applications. Saudi petrochemical processors are specifying these grades for variable frequency drive retrofits in extruder and compressor duty cycles. The technology is electrifying competitive positioning for suppliers capable of IEC 60034-18-41 partial discharge resistance certification.
SFDA and UAE MOHAP electrical equipment safety convergence is mandating harmonized thermal index documentation across Gulf Cooperation Council import regimes. Industrial motor assemblers in Jebel Ali and Dammam are consolidating supplier pools to pre-qualified vendors with dual-jurisdiction certification coverage. High-temperature insulation system approvals now determine competitive access to Saudi Aramco and ADNOC maintenance contract frameworks.
Specification-driven procurement consolidation is compressing distributor tiers in South Africa's automotive wire harnessing sector. Tier-1 suppliers are bypassing regional trading houses to contract directly with enameled wire mills holding IATF 16949 credentials. The behavioral shift concentrates volume commitments with Superior Essex and Southwire Company technical service teams operating Johannesburg technical centers.
Middle East and Africa Magnet Wire Market Segmentation
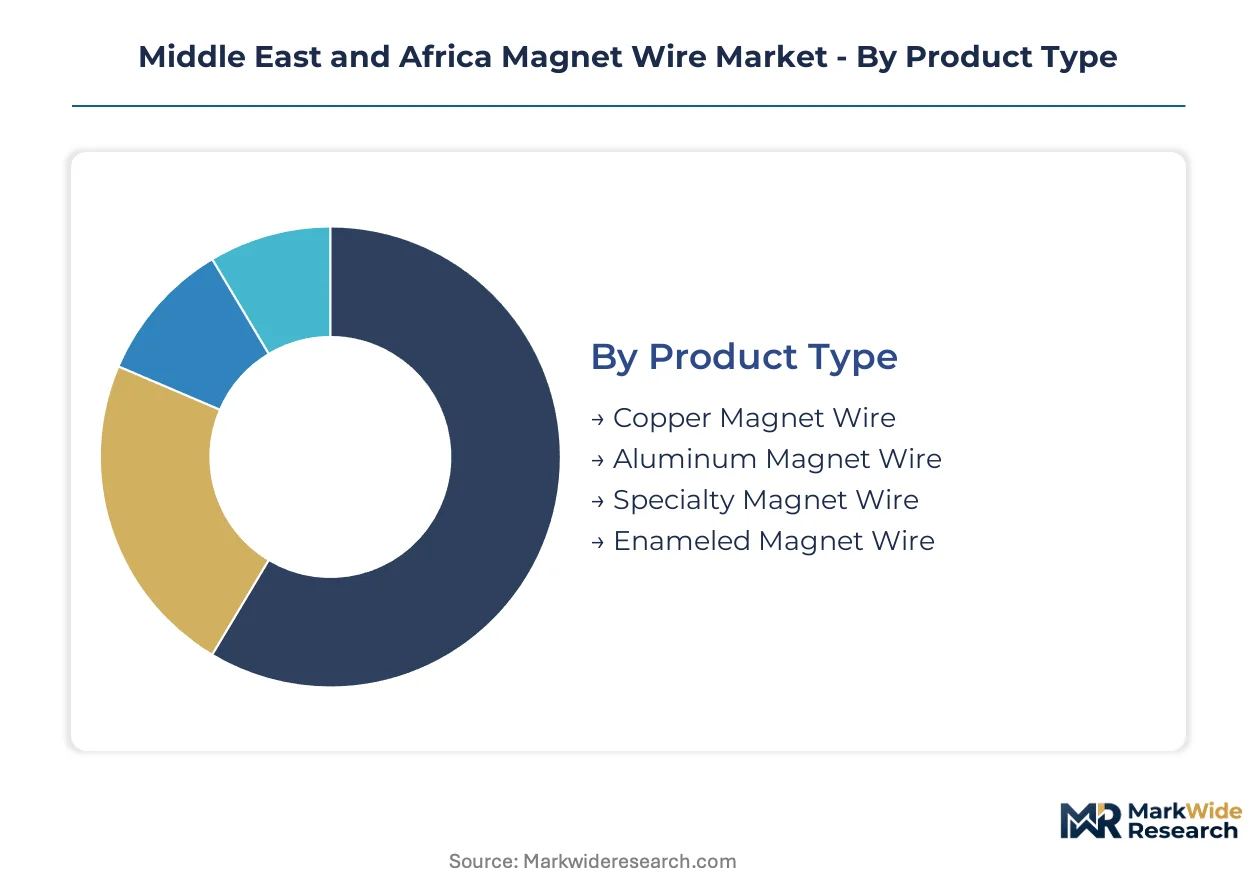
Magnet wire specifications diverge sharply across thermal class, conductor material, and insulation chemistry. Procurement patterns in Middle East and Africa industrial clusters favor copper grades for high-slot-fill motors while aluminum gains traction in weight-sensitive automotive auxiliary systems.
Product Type:
Insulation chemistry and conductor metallurgy define performance ceilings for electromagnetic coil applications across Gulf manufacturing zones and South African automotive plants.
- Copper Magnet Wire:Oxygen-free copper conductors with polymer enamel films between 0.02 mm and 0.50 mm thickness enable superior conductivity in high-frequency inverter applications. Saudi petrochemical processors specify these grades for variable frequency drive retrofits in extruder duty cycles where thermal class 180°C or higher is mandatory.
- Specialty Magnet Wire:Corona-resistant formulations with nano-filled polymer matrices and self-bonding thermoplastic enamel technologies address high-voltage inverter-fed motor specifications. Dubai's clean energy strategy is electrifying generator manufacturing clusters in Jebel Ali with demand for IEC 60034-18-41 partial discharge resistance certification.
- Aluminum Magnet Wire:Lighter conductor material with lower conductivity than copper, specified in weight-driven automotive auxiliary motor categories across South African vehicle assembly plants where cost and mass reduction outweigh efficiency premiums.
- Enameled Magnet Wire:Polymer-based enamel films applied through continuous coating processes remain the volume backbone for standard electromotor and transformer windings across North African electrification projects.
Mature deployment sits with Enameled Magnet Wire. Newer deployment is concentrated in Specialty Magnet Wire.
Application:
End-use equipment specifications determine thermal index requirements and insulation integrity testing protocols across Saudi Aramco and ADNOC maintenance contract frameworks.
- Electromotors:Industrial motor windings in Gulf petrochemical facilities demand thermal class upgrades under tightened SFDA certification frameworks. Slot-fill tolerances are compressing as Jebel Ali coil-forming automation converges with self-bonding wire technologies to eliminate post-winding varnish cycles.
- Transformers:Grid modernization timelines across Gulf utilities are compressing procurement cycles for high-temperature magnet wire grades. Transformer-grade conductors face margin pressure from LME copper volatility in North African project markets.
- Inductors:High-frequency inductive devices operating at several hundred kHz require precise enamel thickness control for tight winding geometries in electronics manufacturing.
- Generators:Renewable energy integration targets are broadening the end-use vertical mix, with corona-resistant specifications electrifying competitive positioning for suppliers serving Dubai's clean energy infrastructure.
Volume concentration remains heaviest in Electromotors. Steepest expansion trajectory is occurring in Generators.
End User:
Customer certification requirements fragment supplier access across IATF 16949 automotive credentials and dual-jurisdiction SFDA-MOHAP electrical equipment approvals.
- Automotive:Tier-1 wire harnessing suppliers in South Africa are bypassing regional trading houses to contract directly with enameled wire mills. Specification-driven procurement consolidation concentrates volume commitments with technical service teams operating Johannesburg technical centers.
- Industrial Machinery:Petrochemical processing facilities across Saudi Arabia are forcing replacement demand for thermal class upgrades in compressor and extruder motor windings under tightened certification frameworks.
- Electronics:Precision winding operations in UAE industrial corridors favor oxygen-free copper magnet wire for high-frequency inverter applications where conductivity premiums justify material cost.
- Aerospace:Specialized thermal and mechanical performance requirements apply to magnet wire assemblies in aircraft electrical systems, with certification pathways shaped by Gulf Cooperation Council harmonization efforts.
Procurement maturity is deepest in Industrial Machinery. Emerging specification intensity is greatest in Automotive.
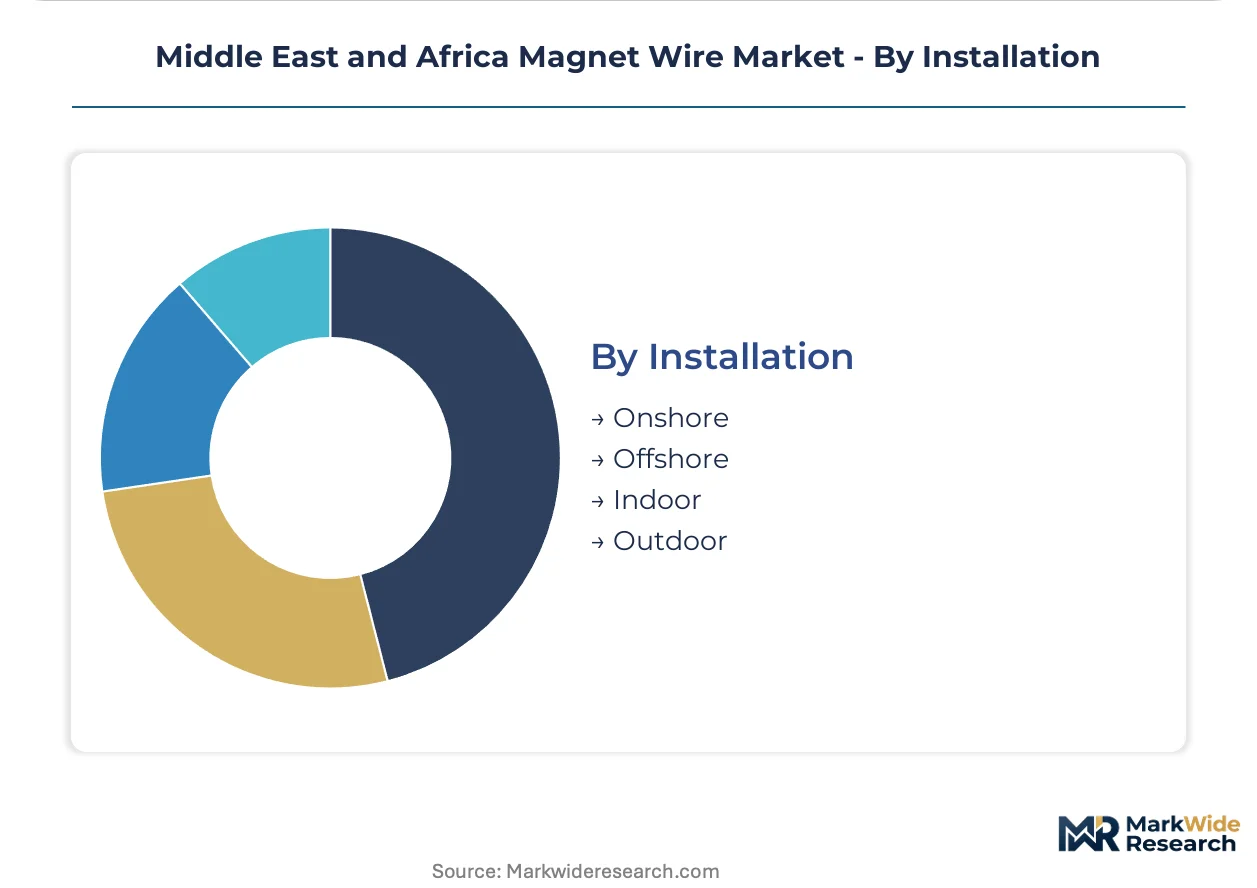
Installation:
Environmental exposure conditions determine insulation system selection for coil integrity in desert climates and offshore hydrocarbon facilities.
- Outdoor:Magnet wire assemblies in desert installations across Gulf Cooperation Council jurisdictions face thermal cycling and sand abrasion challenges requiring enhanced enamel durability.
- Indoor:Climate-controlled industrial motor windings in Jebel Ali and Dammam manufacturing corridors allow standard thermal class specifications.
- Onshore:Grid-connected transformer and generator installations across Egyptian manufacturing zones and Levant electrification projects drive volume demand.
- Offshore:Hydrocarbon platform electrical equipment demands specialized insulation integrity for salt spray and humidity exposure in Arabian Gulf production facilities.
Standard deployment dominates Indoor installations. Technical complexity is escalating fastest in Offshore applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suez Canal Economic Zone incentives are attracting magnet wire downstream processing capacity to serve Levant and East African electrification projects, concentrating industrial investment in specialized manufacturing corridors.
United Arab Emirates
Jebel Ali industrial corridor hosts expanding generator manufacturing clusters under Dubai's clean energy strategy 2050. MOHAP electrical equipment safety frameworks mandate harmonized thermal index documentation for import compliance. Coil-forming automation in Dubai and Abu Dhabi manufacturing zones is converging with self-bonding wire technologies.
Saudi Arabia
Petrochemical processing facilities are forcing replacement demand for thermal class upgrades in compressor and extruder motor windings. SFDA tightened certification frameworks mandate thermal class 180°C or higher for industrial equipment. Dammam manufacturing corridors are consolidating supplier pools to pre-qualified vendors with dual-jurisdiction certification coverage.
South Africa
Automotive wire harnessing sector demands tighter slot-fill tolerances in electrified powertrains. NRCS applies SANS standards mandating thermal class ratings and insulation integrity testing for industrial motor windings. Johannesburg technical centers concentrate volume commitments with enameled wire mills holding IATF 16949 credentials.
Egypt
Suez Canal Economic Zone incentives attract downstream processing capacity for Levant and East African electrification projects. The country's national electrical regulator enforces equipment safety frameworks shaping product certification requirements. Manufacturing zones near Port Said and Alexandria are scaling coil-winding operations for regional transformer and motor assembly.
Middle East and Africa Magnet Wire Market Competitive Landscape
Top-tier vendors anchor high-temperature insulation systems and corona-resistant formulations, while mid-tier fabricators compete on manufacturing scale for transformer-grade conductors. The vendor base stratifies across three tiers: multinational enameled wire specialists with Gulf technical service infrastructure, regional distributors holding dual-jurisdiction certification coverage, and emerging local processors in Egyptian manufacturing zones. Two dominant competitive moves are reshaping positioning: direct contracting between Tier-1 automotive suppliers and enameled wire mills bypassing regional trading houses, and backward integration into polymer enamel supply by Gulf-based fabricators seeking to compress lead times.
Among Japanese and North American specialists, Sumitomo Electric Industries and Southwire Company occupy positions exemplifying high-R&D-intensity and scale-driven archetypes respectively. Superior Essex anchors North African supply through specialized enameled wire operations serving regional electrification projects.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Southwire Company |
| Superior Essex |
| Hitachi Metals |
| General Cable |
| Furukawa Electric |
| LS Cable & System |
| Elektrisola |
| Rea Magnet Wire Company |
| Others |
Supply & Pricing Matrix
Dubai's clean energy strategy 2050 gates qualified supply and premium-tier pricing access for magnet wire producers serving Gulf generator manufacturing clusters. SFDA thermal class mandates and MOHAP electrical equipment frameworks compress procurement pools to pre-certified vendors, concentrating pricing power with dual-jurisdiction holders while spot buyers face extended lead-time premiums.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers in Middle East and Africa magnet wire procurement. Short lead-time premiums apply to corona-resistant and self-bonding grades serving Jebel Ali automation lines, while spot inventory discounts attract price-sensitive North African transformer project buyers. Price differentiation hinges on IEC 60034-18-41 certification status and volume scale commitments. Cost compression in standard enameled grades is intensifying because LME copper volatility erodes margin buffers for Egyptian and South African fabricators. Tier-1 automotive suppliers in Johannesburg exhibit lowest price sensitivity due to IATF 16949 qualification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Saudi Aramco and ADNOC maintenance frameworks, bypassing regional distributor tiers. Polymer enamel supply concentrates in East Asian chemical hubs, while copper cathode sourcing draws from Chilean and Zambian mining operations. Raw material dependencies rest on polyimide resin systems, oxygen-free copper rod, and nano-filled polymer matrices for corona-resistant grades. Single-source vulnerability in specialty insulation chemistry exposes Gulf fabricators to currency mismatch risks. Distribution runs through Johannesburg technical centers for South African automotive harnessing and Suez Canal Economic Zone processing nodes for Levant electrification projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East and Africa magnet wire is transitioning from conventional enameled grades to self-bonding and corona-resistant formulations. Nano-filled polymer matrix technologies are displacing legacy varnish-cycle coil manufacturing across Gulf industrial corridors.
For Market Incumbents: Hedge aluminum substitution pressure in South African automotive auxiliary motors by deepening captive enamel supply from Egyptian polymer processing nodes. SFDA thermal class escalation threatens stranded inventory in standard-grade stockpiles; accelerate IEC 60034-18-41 certification coverage for Saudi petrochemical retrofit demand. Backward integration into polyimide resin sourcing compresses lead-time exposure to East Asian chemical hub concentration. For New Entrants and Emerging Players: Self-bonding thermoplastic enamel expertise offers entry wedge into UAE coil-forming automation corridors where post-winding varnish elimination commands specification premiums. Egyptian manufacturing zones present most penetrable geography given Suez Canal Economic Zone incentive structures and underserved Levant electrification demand. Technical service partnerships with Johannesburg automotive Tier-1s provide go-to-market credibility absent IATF 16949 credentials. For Investors and Strategic Acquirers: NRCS SANS thermal class testing timeline extensions are the leading indicator that South African regulatory bottlenecks will concentrate procurement with pre-qualified incumbent mills. Long-term viability favors vertically integrated specialists controlling both conductor drawing and enamel application capabilities. Acquisition target archetype: mid-scale Egyptian processors with Port Said logistics access and latent polymer chemistry technical capacity. Watch for MOHAP-SFDA harmonization completion as certification consolidation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Enamel Supply | Compresses lead times from East Asian chemical hubs for Gulf fabricators serving ADNOC frameworks. |
| Dual-Jurisdiction Certification Investment | Unlocks Saudi Aramco and Dubai utility procurement pools under converging SFDA-MOHAP thermal index mandates. |
| Egyptian Manufacturing Zone Capacity Expansion | Captures Suez Canal Economic Zone incentives for Levant and East African electrification project supply. |
| Self-Bonding Wire Technology Licensing | Eliminates post-winding varnish cycles for Jebel Ali coil-forming automation lines demanding slot-fill precision. |
| Johannesburg Technical Center Establishment | Secures direct Tier-1 automotive contracts bypassing regional trading houses under IATF 16949 procurement consolidation. |
Research Methodology
Trade flow databases, customs import records, and Gulf Cooperation Council electrical equipment regulatory filings formed the secondary backbone of this analysis. Primary interviews with magnet wire plant managers, petrochemical facility maintenance directors, automotive Tier-1 procurement leads, and polymer enamel technical R&D directors validated demand assumptions across thermal class upgrade cycles. Bottom-up and top-down triangulation reconciled enameled wire shipment volumes with transformer and motor OEM production schedules.
Bottom-up modeling aggregated country-level demand by conductor material, insulation chemistry, and end-use equipment category across the analysis window. Segmentation dimensions included thermal class rating, installation environment, and certification tier alongside regional regulatory cluster alignment. CAGRs derived from fitted growth curves applied to base-year value pools, stress-tested against copper price scenario inputs and utility capital expenditure disclosure patterns.
Several conditions sit outside the modeled scope, including unannounced SFDA thermal class mandate accelerations and abrupt LME copper price dislocations. Forecasts reflect assumptions about Gulf grid modernization timeline execution and Egyptian manufacturing zone incentive continuity. Periodic stress-testing of base assumptions against NRCS accreditation backlog developments and Suez Canal logistics disruption events is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Magnet Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Gadolinium Market