
 Europe Ready-Mix Concrete Market | 2026-2036
Europe Ready-Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ready-Mix Concrete Market Foresight
Market Context
Asset-light leasing models for truck mixer fleets is reconfiguring capital barriers for mid-sized entrants across Europe. Heidelberg Materials leverages its vertically integrated cement-to-concrete network to sustain margin control in German and Benelux corridors. CRH anchors its position through dense ready-mix plant networks in Britain and Ireland, while Buzzi Unicem competes via limestone-rich quarry positions that reduce clinker transport costs.
Technical Definition and Segment Structure
Ready-mix concrete denotes batched concrete products manufactured in central plants and delivered in plastic state to construction sites, typically achieving compressive strengths from 20 MPa to over 80 MPa depending on mix design and admixture loading. Its primary purpose is to eliminate on-site batching variability while enabling just-in-time delivery for large-scale pours. Self-consolidating concrete commands premium positioning in dense rebar applications across Nordic infrastructure, while standard mixes dominate residential volumes where price sensitivity limits admixture inclusion. Infrastructure applications absorb the highest tonnage per project, though commercial segments generate superior margin pools through specification complexity and performance guarantees.
Regulatory Environment
The EU Green Deal and national implementations of the EU Emissions Trading System shape producer investment in carbon capture and alternative binders, while CE marking under the Construction Products Regulation governs structural conformity across member states. ECHA's REACH framework restricts certain chemical admixtures, forcing reformulation toward bio-based plasticizers. Stakeholders must monitor evolving carbon border adjustments and national building codes tightening embodied carbon thresholds for public procurement.
Market Dynamics
The EU Green Deal's carbon pricing architecture is compressing margins for clinker-intensive producers while creating first-mover advantages for operators with limestone-rich quarry positions and alternative binder capabilities.
Growth Catalysts
- EU Cohesion Fund disbursements:Transport and energy corridor investments across Poland, Romania, and Czechia are absorbing record tonnages of high-specification mixes for bridge decks and tunnel linings.
- Carbon capture retrofits:German and Benelux producers deploying oxyfuel combustion and amine scrubbing systems are securing preferential procurement status under national green public purchasing mandates.
- Urban densification:Paris, Berlin, and Vienna metro extensions are specifying self-consolidating concrete for 24-hour continuous pours in confined underground conditions.
Market Restraints
- Clinker cost volatility:EU Emissions Trading System allowance prices have tripled since 2021, transmitting directly to cement input costs for ready-mix batching operations.
- Admixture supply concentration:Bio-based plasticizer production centers on German and Dutch chemical clusters, creating bottleneck risks during REACH reformulation transitions.
- Transport radius economics:Concrete's two-hour workability window limits plant-to-site distances to 50 kilometers, constraining market addressable radius for rural batching facilities.
Strategic Opportunities
- Carbon-negative concrete formulations:Magnesium oxide binders and CO2 mineralization curing processes qualify for enhanced national tax credits under France's green industry acceleration framework.
- Digital twin integration:Real-time slump monitoring and predictive logistics algorithms are reducing rejection rates and enabling just-in-time delivery guarantees for infrastructure contractors.
- CEE secondary cities:Hungarian and Slovak urban ring roads bypassing EU congestion charging zones are generating greenfield demand from logistics and distribution developers.
Industry Challenges
- Admixture chemist shortage:Formulation expertise for low-clinker rheology control is concentrating among retiring specialists at major chemical suppliers, constraining producer technical service capacity.
- Batch plant electrification capex:Grid connection upgrades and kiln electrification pilots require capital allocations that mid-sized operators cannot access without asset-light leasing restructuring.
- CE marking timeline compression:Accelerated factory production control audits under revised Construction Products Regulation implementation are delaying new mix launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ready-Mix Concrete Market |
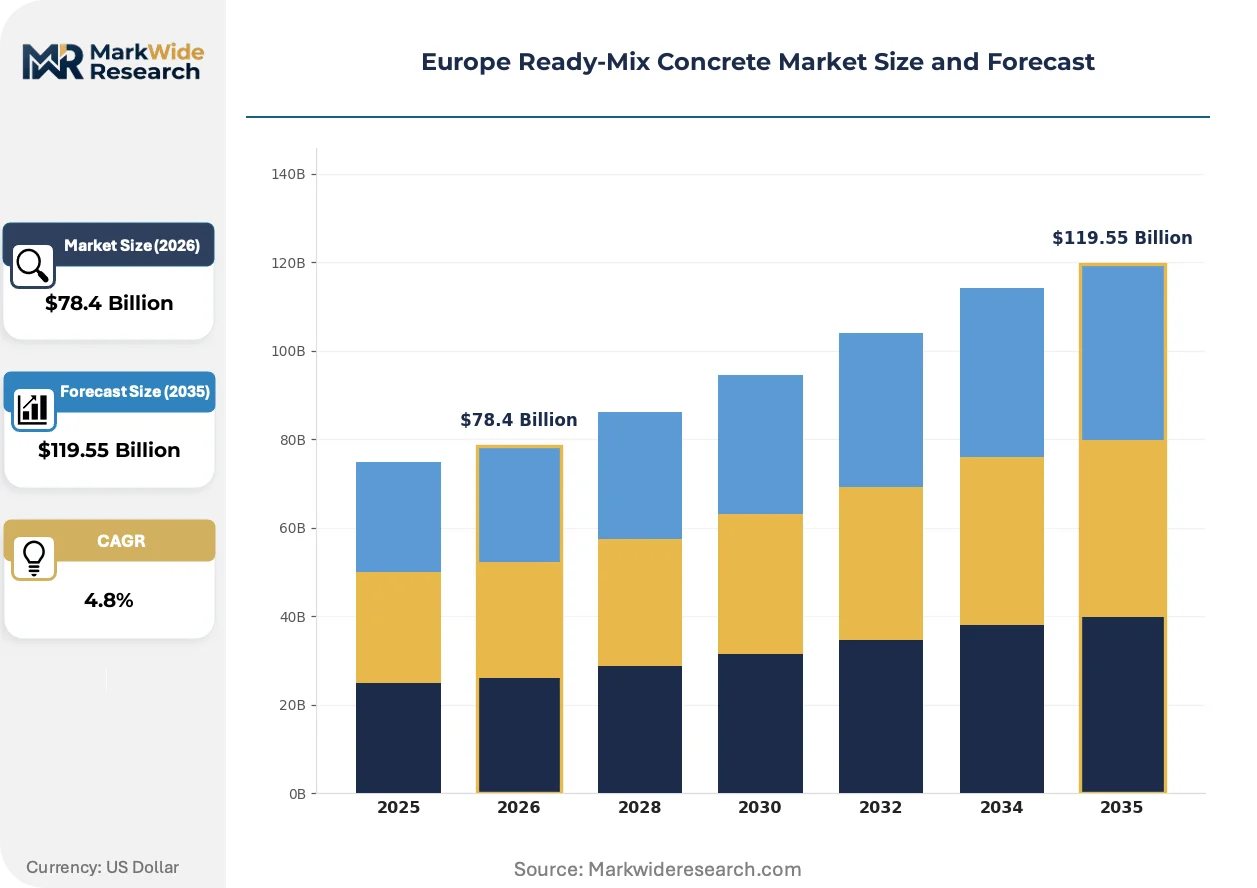
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High-Strength, Self-Consolidating, Lightweight Application: Residential, Commercial, Infrastructure, Industrial Delivery Mode: Truck Mixer, Trailer Mixer, Volumetric Mixer, Central Mix End User: Contractors, Builders, Architects, Developers |
| Companies Covered | LafargeHolcim, Buzzi Unicem, Heidelberg Materials, Cementir, Vicat, Holcim Group, Cemex, Saint-Gobain Construction Products, CRH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ready-Mix Concrete Market Shifts & Advancements
Decarbonization imperatives are restructuring technical specifications and procurement criteria across European construction value chains, with performance guarantees and embodied carbon disclosure becoming standard contract terms.
Calcined clay and limestone filler systems are migrating from niche Nordic infrastructure applications to mainstream commercial and residential specifications. German and Austrian contractors specifying 50% clinker reduction for public buildings are driving batch plant retrofits. This technology is migrating from premium infrastructure segments to volume residential markets as EPD verification costs decline and producer certification scales.
REACH restrictions on polycarboxylate ether superplasticizers are forcing reformulation toward bio-based alternatives derived from agricultural waste streams. ECHA's 2023 substance evaluation roadmap has accelerated substitution timelines for high-performance admixtures. Nordic and Alpine markets with stricter groundwater protection standards are experiencing fastest compliance-driven product turnover.
Performance-based procurement contracts are displacing traditional cubic-meter pricing for complex infrastructure pours. French and British water treatment and nuclear containment contractors now specify 100-year durability guarantees with penalty clauses for premature degradation. This contractual evolution is most advanced in Benelux corridors where public-private partnership frameworks embed lifecycle cost accounting.
Europe Ready-Mix Concrete Market Segmentation
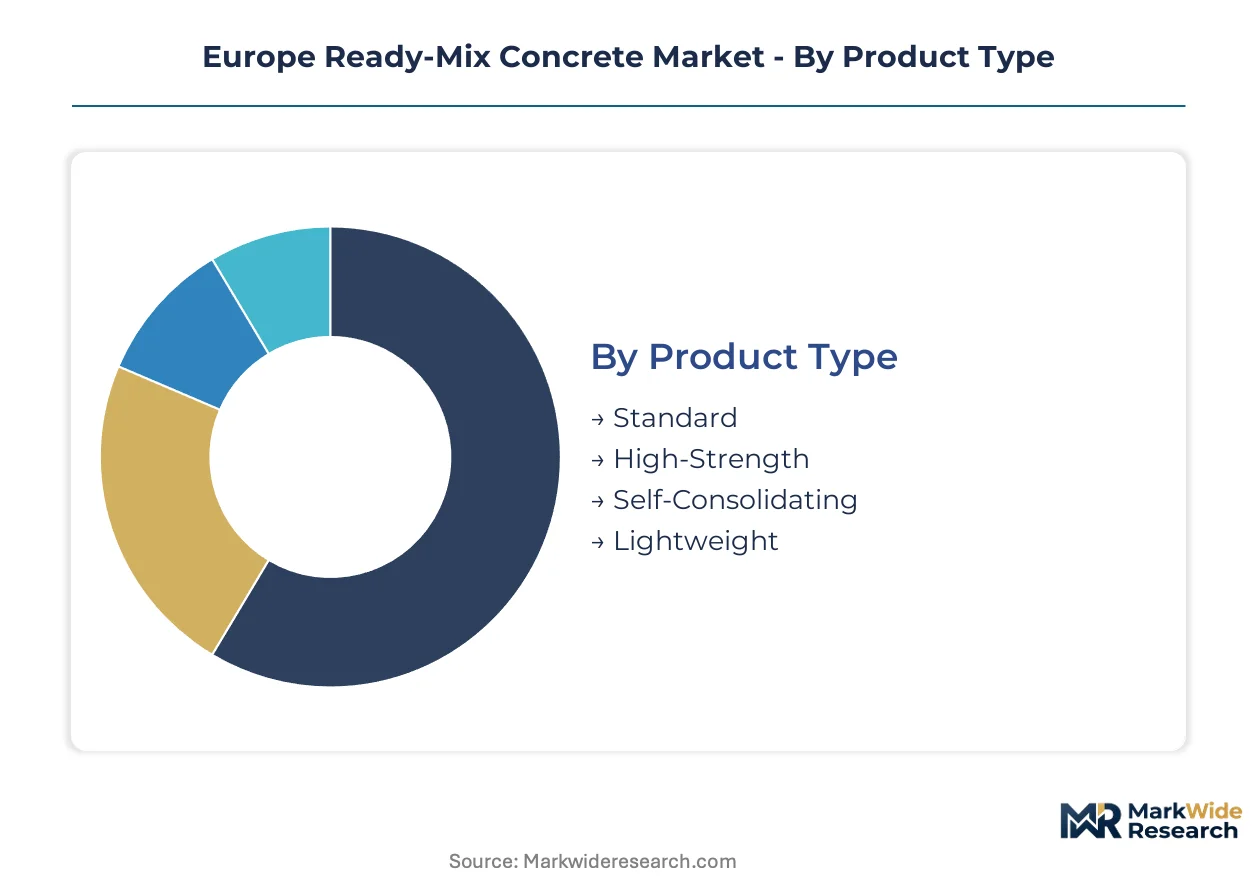
Segmentation in the Europe Ready-Mix Concrete Market reveals how specification complexity, delivery logistics, and procurement authority split value pools across distinct operational profiles. Producers must align batch plant capabilities, fleet composition, and technical service teams to the dominant segments within each category.
Product Type:
Use-case spectrum spans basic structural fills to precision infrastructure pours demanding rheological control and carbon-minimized formulations.
- Standard:Basic mixes with compressive strengths of 20-40 MPa dominate residential foundations and commercial slabs across Poland and Romania. Price sensitivity in these markets limits admixture loading, compressing margins but securing volume throughput for mid-sized batch plants.
- High-Strength:Formulations exceeding 60 MPa absorb premium pricing for German bridge decks and French nuclear containment structures. EU Green Deal procurement mandates are accelerating clinker reduction in these specifications without compromising performance envelopes.
- Self-Consolidating:Flowable mixes eliminating mechanical vibration command specification in dense rebar applications across Nordic metro extensions.
- Lightweight:Expanded aggregate systems reduce dead loads in high-rise construction clusters around Vienna and Berlin.
Established volume favors Standard; emerging adoption favors High-Strength.
Application:
Volume concentration versus margin extraction varies sharply by project scale and specification complexity across European construction corridors.
- Residential:Single-family and multi-unit housing drives batch plant utilization in suburban rings surrounding Budapest, Prague, and Warsaw. EU cohesion fund disbursements for social housing in Czechia and Slovakia are sustaining pour schedules despite interest rate sensitivity in private development.
- Commercial:Office, retail, and logistics specifications generate superior margin pools through performance guarantees and accelerated curing requirements. German and Benelux contractors increasingly embed 50-year durability clauses with penalty structures for premature degradation.
- Infrastructure:Transport and energy networks absorb record tonnages across Polish highway corridors and Romanian rail modernization.
- Industrial:Manufacturing floor slabs and process containment specifications demand chemical resistance certification under REACH-adjacent national frameworks.
Commercial commands margin concentration; Infrastructure dominates absolute volume absorption.
Delivery Mode:
Fleet configuration economics determine market addressable radius and capital intensity for entrants across rural-urban gradients.
- Truck Mixer:Rotating drum vehicles maintain plastic state during transport and remain the default for 90% of European deliveries. German producers are piloting electrified drum drives to reduce depot emissions under national carbon budget implementations.
- Trailer Mixer:Detachable units extend reach beyond 50-kilometer workability windows for remote infrastructure sites in Alpine and Nordic corridors.
- Volumetric Mixer:On-site batching from raw material compartments serves repair and small-pour markets with minimal waste.
- Central Mix:Stationary plant mixing with agitator truck transport addresses highest-volume continuous pours for French nuclear and British water treatment containment.
Truck Mixer anchors capital deployment; Volumetric Mixer gains traction in maintenance and retrofit segments.
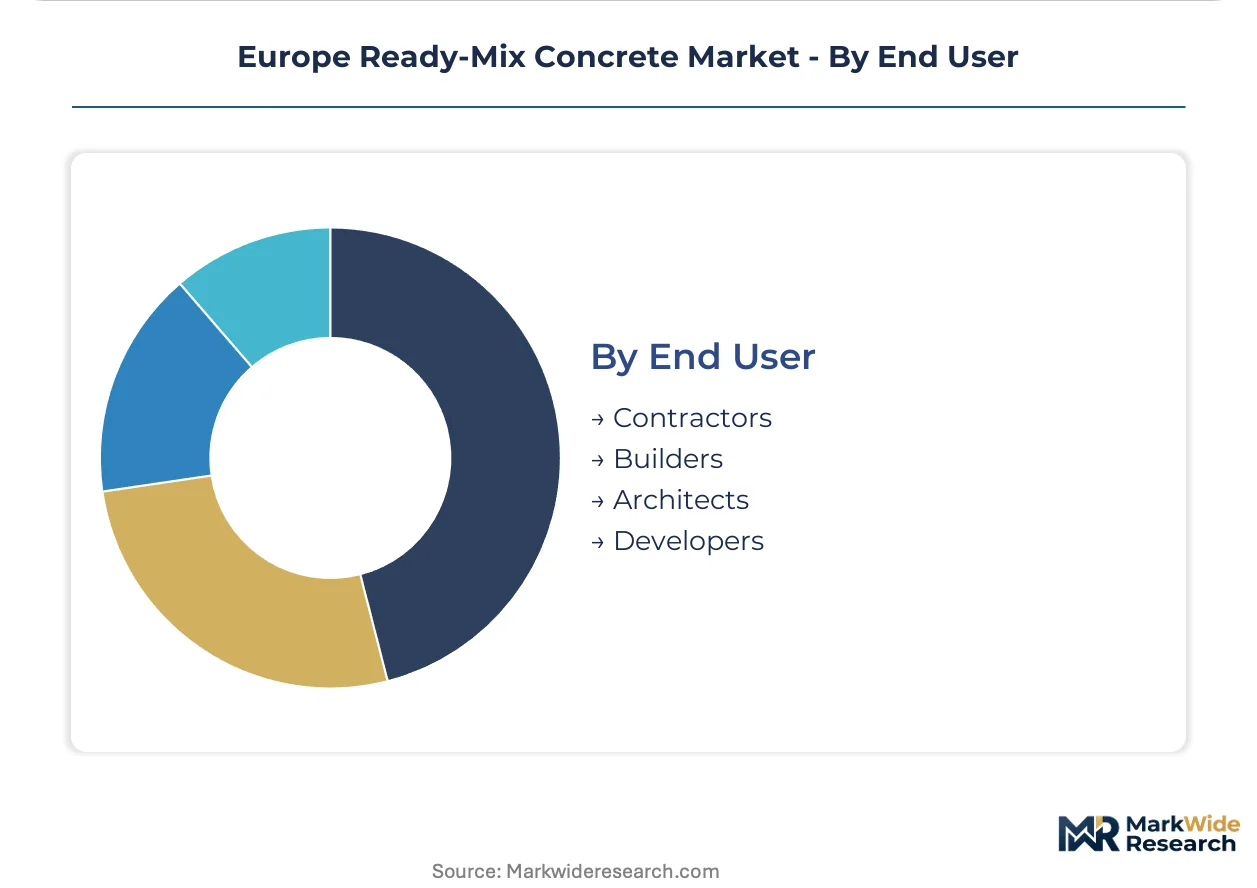
End User:
Procurement authority and technical specification control sit at different points in the construction value chain across European markets.
- Contractors:Direct pour execution gives these stakeholders scheduling leverage and just-in-time delivery requirements. French and British infrastructure contractors now specify real-time slump monitoring with rejection rights for out-of-specification loads.
- Builders:Volume aggregators for residential development drive standard mix procurement with price-per-cubic-meter benchmarking across Polish and Romanian markets.
- Architects:Aesthetic and sustainability specification authority shapes exposed aggregate and low-carbon mix selection in Austrian and Swiss commercial projects.
- Developers:Lifecycle cost accounting and green building certification requirements are embedding embodied carbon thresholds in German and Benelux procurement frameworks.
Contractors control operational specifications; Developers are ascending in sustainability-driven selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's ready-mix concrete trade flows reveal a net import dependency for specialized admixtures and clinker substitutes, while surplus production of standard-grade mixes concentrates near limestone-rich quarry belts in Central Europe. Cross-border procurement networks increasingly prioritize low-carbon certification over proximity sourcing.
Germany
Berlin-Brandenburg metro extensions and North Rhine-Westphalia industrial corridor upgrades absorb record tonnages of self-consolidating concrete. The EU Emissions Trading System compresses margins for clinker-intensive batching operations in Bavaria. Munich-based contractors now specify 50-year durability guarantees with real-time slump monitoring for nuclear containment pours.
France
Grand Paris Express tunnel linings and Île-de-France logistics hubs drive demand for high-strength low-clinker formulations. France's green industry acceleration framework grants enhanced tax credits to producers deploying carbon-negative magnesium oxide binders. Lyon-Rhône corridor batch plants are retrofitting for calcined clay systems to meet public procurement embodied carbon thresholds.
Poland
EU cohesion fund highway corridors and Baltic rail modernization absorb volume tonnage across Masovian and Silesian construction belts. National building code amendments align with EU Green Deal carbon budgeting for transport infrastructure. Warsaw suburban ring roads generate greenfield demand from logistics developers bypassing EU congestion charging zones.
United Kingdom
Thames Tideway and Hinkley Point containment specifications command premium pricing for performance-guaranteed mixes. CE marking under the Construction Products Regulation governs structural conformity for cross-border Irish Sea procurement. Manchester-Liverpool commercial development clusters embed 50-year durability clauses with penalty structures for premature degradation.
Netherlands
Randstad urban densification and North Sea wind farm foundation pours specify ultra-low carbon concrete with CO2 mineralization curing. REACH restrictions on polycarboxylate ether superplasticizers accelerate bio-based admixture reformulation at Rotterdam chemical clusters. Amsterdam metro contractors require real-time logistics algorithms with just-in-time delivery guarantees for 24-hour continuous operations.
Europe Ready-Mix Concrete Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated cement-to-concrete networks and limestone-rich quarry positions that compress clinker transport costs. Three strategic archetypes dominate: multinational building materials conglomerates with dense plant networks, mid-sized regional specialists with asset-light leasing models, and chemical-integrated admixture formulators. Competitive moves center on carbon capture retrofit partnerships and digital twin integration for predictive logistics.
Among the integrated materials conglomerates, LafargeHolcim and Heidelberg Materials exemplify archetypes combining quarry control with batch plant density, while CRH occupies a position representing network-scale operators in British and Irish corridors. Buzzi Unicem anchors the limestone-advantaged tier through captive quarry positions that reduce input cost volatility under EU carbon pricing. These groupings illustrate how supply-side configuration determines margin resilience when ETS allowance prices transmit directly to cement input costs.
| Leading Market Players |
|---|
| LafargeHolcim |
| Buzzi Unicem |
| Heidelberg Materials |
| Cementir |
| Vicat |
| Holcim Group |
| Cemex |
| Saint-Gobain Construction Products |
| CRH |
| Others |
Supply & Pricing Matrix
Undercapacity across German and Polish batching corridors is compressing supplier pricing power while amplifying cost pass-through to infrastructure contractors. EU Emissions Trading System allowance volatility feeds directly into cement input costs, forcing producers to choose between margin sacrifice and volume retention.
Pricing Analysis
Infrastructure contractors anchor project-based contract pricing across European corridors. Three-tier pricing structure across performance-guaranteed, standard-specification, and economy-grade levels stratifies by clinker content and carbon certification tier. Cost compression in economy residential mixes is intensifying because Polish and Romanian builders benchmark aggressively on per-cubic-meter rates. Volume aggregators for social housing exhibit highest price sensitivity; nuclear containment and metro extension contractors demonstrate lowest sensitivity due to performance guarantee requirements.
Supply Chain Analysis
Tariff exposure between EU member states and third-country clinker substitutes dominates supply chain risk calculus for Benelux and German producers. Raw material sourcing draws from limestone-rich quarry belts in Poland, limestone filler deposits in France, and calcined clay processing centers in Nordic corridors. Single-source vulnerability concentrates in German and Dutch bio-based plasticizer production clusters under REACH transition timelines. Distribution runs through vertically integrated cement-to-concrete networks with 50-kilometer radius constraints from batch plant to pour site.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers—real-time slump monitoring subscriptions, predictive logistics algorithms, and 100-year durability guarantee underwriting—are expanding faster than commodity concrete tonnage across European infrastructure corridors.
For Market Incumbents: Harden carbon capture retrofit partnerships with German and Benelux oxyfuel combustion specialists to secure preferential procurement status under national green public purchasing mandates. Deepen backward integration into calcined clay and limestone filler processing to insulate margin structures from EU ETS allowance volatility. Lock in long-term offtake agreements with Grand Paris Express and Berlin-Brandenburg metro contractors before alternative binder certification scales. For New Entrants and Emerging Players: Build out asset-light leasing models for electrified truck mixer fleets in Hungarian and Slovak urban ring road corridors where EU cohesion fund disbursements are greenfielding logistics demand. Target volumetric mixer deployment for repair and retrofit segments in Alpine and Nordic maintenance markets with minimal incumbent saturation. Lead with CO2 mineralization curing process differentiation to qualify for France's green industry acceleration tax credits. For Investors and Strategic Acquirers: Capital is best deployed toward limestone-advantaged regional specialists with captive quarry positions in Central European corridors, where clinker transport cost compression sustains margin resilience across carbon pricing cycles. Monitor German and Austrian batch plant electrification capex announcements as inflection signals for mid-sized operator distress and consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | Secures preferential procurement under German green public purchasing mandates. |
| Calcined Clay System Certification | Unlocks French and Benelux public infrastructure embodied carbon thresholds. |
| Real-Time Logistics Algorithm Deployment | Enables just-in-time delivery guarantees for Amsterdam 24-hour continuous operations. |
| Bio-Based Plasticizer Reformulation | Accelerates REACH compliance in Nordic groundwater protection markets. |
| Electrified Fleet Leasing Model | Reduces depot emissions under national carbon budget implementations. |
Research Methodology
A standing panel of batch plant operations managers, infrastructure contractor procurement leads, admixture formulation chemists, and EU ETS compliance officers provided ongoing calibration against primary fieldwork. Secondary validation drew from Construction Products Regulation implementation documents, ECHA REACH substance evaluation roadmaps, EU cohesion fund disbursement records, and national building code amendment filings. Bottom-up volume modeling across plant-level capacity utilization triangulated with top-down cement consumption forecasts.
Scenario bracketing around EU ETS allowance price bands, clinker substitution adoption curves, and REACH reformulation timelines shaped projection outputs across the analysis window. Segmentation dimensions modeled include product type tier, application complexity, delivery mode capital intensity, and end-user procurement authority. CAGRs were derived from trend extrapolation of historical batch plant utilization rates, EU infrastructure investment pipelines, and carbon pricing trajectory assumptions.
Stress conditions across EU ETS allowance volatility, bio-based plasticizer supply bottlenecks, and CE marking audit delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cohesion fund disbursement schedules and national green procurement mandate adoption. Material shifts in EU carbon border adjustment implementation or Construction Products Regulation revision timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
Concrete Densifier Market