
 North America Ceramic Tiles Market | 2026-2036
North America Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceramic Tiles Market Intelligence
The North America ceramic tiles market is consolidating around a sharp split between large-format porcelain commanding premium positioning and commodity glazed wall tile facing margin compression. Mohawk Industries leverages vertical integration across raw material sourcing and distribution to sustain cost advantages in porcelain production. Florida Tile anchors its competitive stance through specialized domestic manufacturing focused on commercial-grade specifications. Crossville Inc. differentiates via technology leadership in through-body porcelain and recycled content formulations.
Ceramic tiles are fired clay-based surfacing materials, typically composed of kaolin, feldspar, and silica, manufactured through dry-pressing or extrusion and fired at temperatures exceeding 1,100°C to achieve hardness and moisture resistance. Porcelain segments dominate value capture due to density and frost-resistance specifications that command specification in commercial flooring. Wall tile applications in hospitality renovation cycles represent the fastest-expanding demand pool. Retail distribution channels occupy mature margin structures while direct sales to large contractors concentrate in institutional and commercial project pipelines.
EPA Clean Air Act standards and OSHA silica exposure limits shape plant-level compliance investments across U.S. manufacturing facilities. California Title 24 and IECC energy codes in multiple states drive demand for thermal-mass and cool-roof tile specifications. Stakeholders must monitor evolving FTC green marketing guidelines and state-level extended producer responsibility frameworks as specification criteria for public procurement tighten.
Market Dynamics
Large-format porcelain specifications are compressing commodity glazed wall tile margins as housing corridors in Texas and Florida concentrate demand pull toward premium performance grades. EPA Clean Air Act compliance investments and California Title 24 thermal-mass requirements are reshaping manufacturing cost structures across domestic production bases.
Growth Catalysts
- Residential construction corridors:Metropolitan housing starts in Dallas-Fort Worth and Miami-Dade are pulling porcelain tile specifications for frost-resistant exterior applications.
- California Title 24 energy codes:Cool-roof and thermal-mass tile mandates are accelerating specification of high-density porcelain in commercial building envelopes.
- Renovation cycle compression:Hospitality sector refresh programs in Orlando and Las Vegas are shortening replacement intervals for commercial-grade flooring systems.
Market Restraints
- Natural gas price volatility:Kiln firing operations face input cost instability as regional pipeline constraints affect Texas and Louisiana manufacturing zones.
- Kaolin supply concentration:Domestic ceramic-grade clay deposits in Georgia and South Carolina create geographic dependency for body formulation consistency.
- OSHA silica exposure limits:Dry-cutting compliance requirements add operational friction to field installation workflows and contractor certification costs.
Strategic Opportunities
- Underpenetrated Canadian commercial specification:Toronto and Vancouver high-rise construction presents white space for through-body porcelain in mixed-use developments.
- Recycled content formulations:Post-industrial ceramic waste streams enable circular production claims aligned with evolving FTC green marketing guidelines.
- Direct contractor channels:Large institutional buyers in healthcare and education verticals are consolidating procurement away from traditional retail distribution.
Industry Challenges
- Specialized kiln operator scarcity:Temperature control expertise for large-format porcelain firing is concentrating among aging workforce cohorts in Tennessee and Alabama production facilities.
- Extended product certification timelines:ANSI A137.1 and ASTM C373 testing protocols create launch delays for novel surface finish innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceramic Tiles Market |
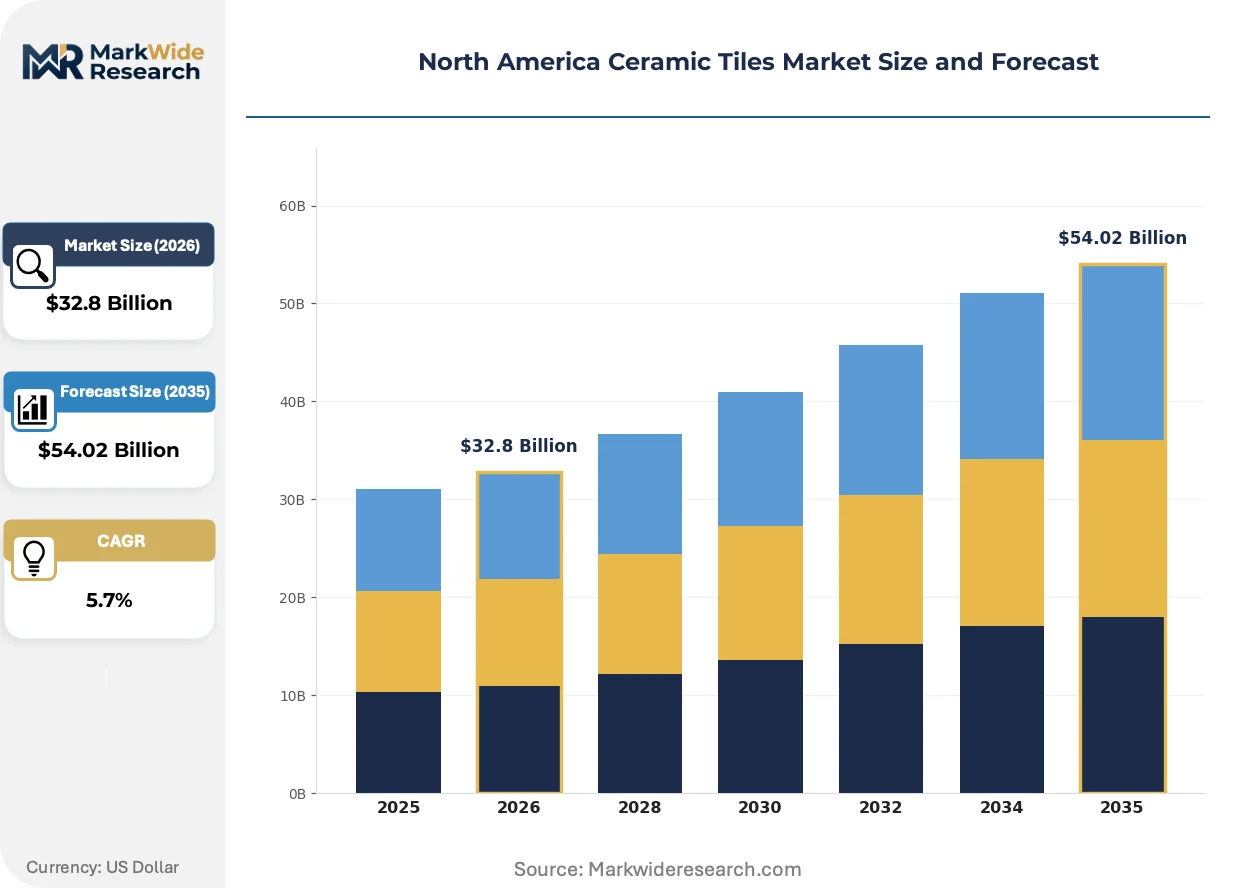
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Unglazed, Porcelain, Stoneware End User: Residential, Commercial, Institutional, Hospitality Application: Flooring, Wall Tile, Countertops, Backsplashes Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Florida Tile, Roca Tiles USA, Mohawk Industries, Vitromex USA, Emser Tile, Shaw Industries Group, Crossville Inc., Bedrosians Tile & Stone, Interceramic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceramic Tiles Market Strategic Shifts & Innovations
Digital inkjet decoration systems and thin-profile large-format panels are restructuring competitive positioning across residential and commercial specification tiers. Manufacturing technology investments are compressing batch-to-batch variation while enabling rapid pattern customization.
Thin large-format porcelain panels are consolidating specification share in commercial flooring and facade cladding applications. Hospitality and healthcare end-users are adopting these materials for seamless surface continuity and reduced grout maintenance. The technology is consolidating demand away from traditional thick-body tile in premium renovation projects.
EPA emissions standards under the Clean Air Act are tightening particulate matter limits for ceramic kiln operations. Manufacturing facilities in California and Texas are deploying advanced baghouse filtration and regenerative thermal oxidizers to maintain operating permits. Wet-process body preparation is gaining adoption as a compliance pathway in high-regulation states.
Large contractor procurement consolidation is compressing distributor margins and accelerating direct manufacturer relationships. Institutional buyers in education and municipal construction are unbundling specification, logistics, and installation services. This pattern is most visible in Texas and Florida metropolitan corridors where project scale supports dedicated supply agreements.
North America Ceramic Tiles Market Segmentation
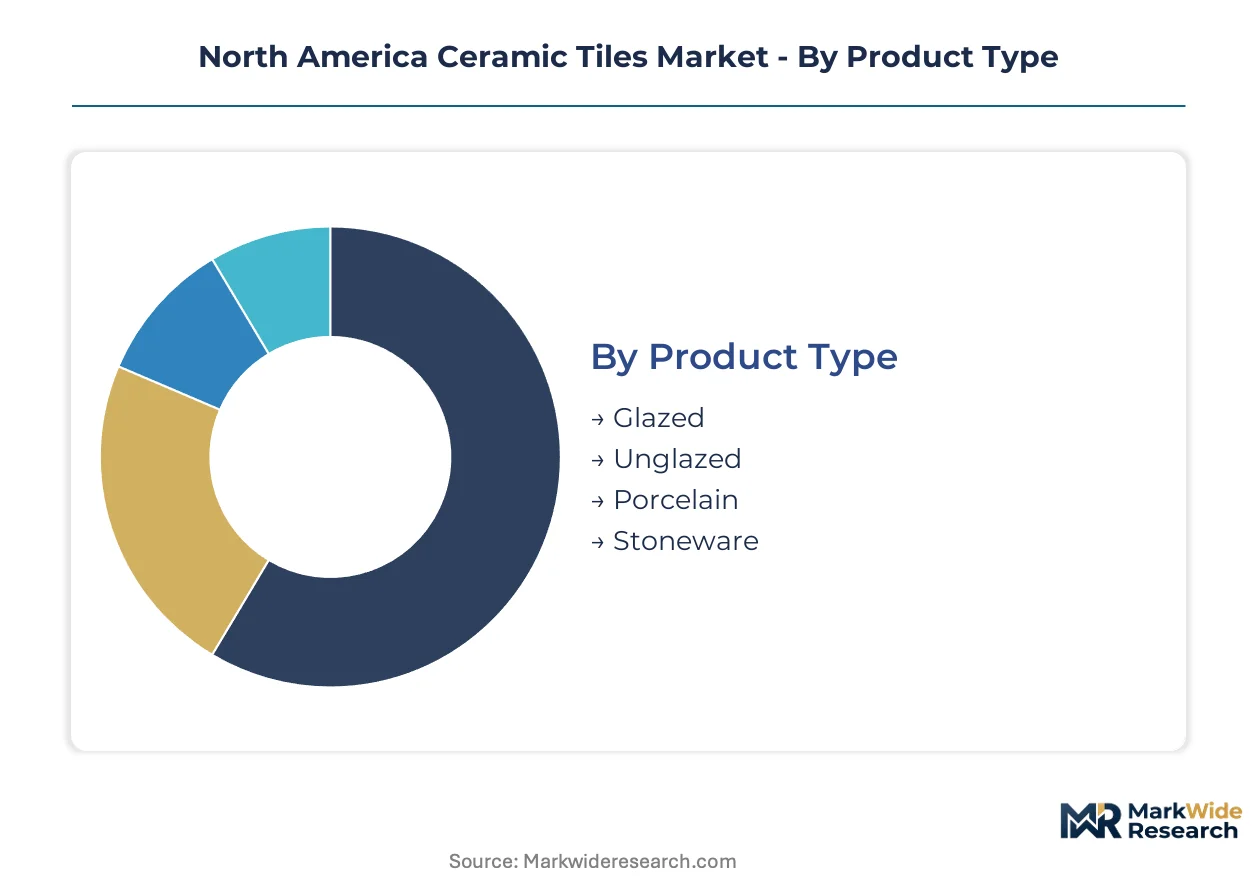
Ceramic tile segmentation in North America tracks how specification requirements diverge across construction verticals and renovation cycles. Upgrade decisions in flooring versus wall applications follow different trigger points—durability thresholds for commercial foot traffic versus aesthetic refresh timelines in residential kitchens.
Product Type:
Replacement-cycle intensity varies sharply by body density and surface finish durability, with exterior-grade specifications commanding longer intervals but higher per-project value.
- Glazed:Glass-based surface coatings fired onto clay bodies create color-stable, stain-resistant finishes for interior wall applications. Demand clusters in residential bathroom renovations across Florida and Texas metropolitan corridors where humidity resistance drives specification.
- Porcelain:Through-body density exceeding 0.5% water absorption delivers frost resistance and structural load capacity for exterior cladding and commercial flooring. Dallas-Fort Worth and Miami-Dade housing starts are pulling premium-grade porcelain for pool decks and high-traffic retail environments.
- Unglazed:Natural clay surfaces without vitreous coating rely on body color and texture for aesthetic effect, suited to rustic residential flooring and commercial slip-resistant applications.
- Stoneware:Intermediate density between earthenware and porcelain offers cost-positioned durability for light commercial and residential renovation budgets.
Volume placements concentrate in Glazed wall tile for residential refresh cycles; the faster expansion belongs to Porcelain as frost-resistant specifications penetrate exterior applications.
End User:
Cost-tier stratification separates specification authority—owner-occupied residential decisions prioritize installed cost while institutional procurement emphasizes lifecycle value and compliance documentation.
- Residential:Single-family and multifamily construction drives standard-grade porcelain and glazed ceramic for flooring and wet-area walls. Texas and Florida housing corridors account for disproportionate demand pull as new construction absorbs moisture-resistant specifications.
- Commercial:Retail, office, and mixed-use developments specify through-body porcelain for wear-layer performance and reduced maintenance intervals. Toronto and Vancouver high-rise construction presents specification white space for large-format panels in mixed-use envelopes.
- Institutional:Healthcare and education verticals consolidate procurement through direct manufacturer relationships, unbundling specification from installation services.
- Hospitality:Orlando and Las Vegas renovation cycles compress replacement intervals for guest room flooring and lobby surfacing, favoring rapid-install large-format formats.
Procurement scale favors Commercial direct agreements; Hospitality exhibits the steepest expansion trajectory as renovation cycles accelerate.
Application:
Margin structures diverge by installation complexity—flooring commands higher material value but faces contractor labor constraints, while wall applications allow faster production-to-installation velocity.
- Flooring:Structural load requirements and slip-resistance certifications (ANSI A137.1) filter specification toward porcelain and high-density stoneware. Commercial-grade installations in Texas healthcare and education facilities concentrate demand for 24x24 inch and larger formats.
- Wall Tile:Vertical surfacing emphasizes aesthetic range over structural performance, with digital inkjet decoration enabling rapid pattern customization for residential kitchen and bathroom renovations.
- Countertops:Thin large-format porcelain panels displace traditional thick-body tile and solid surfacing in premium residential and commercial food-service environments.
- Backsplashes:Small-format decorative tile and mosaic assemblies serve accent applications with shorter replacement cycles and lower per-project material intensity.
Revenue concentration sits with Flooring specifications; Countertops are climbing the fastest as thin-panel technology penetrates kitchen and bath renovations.
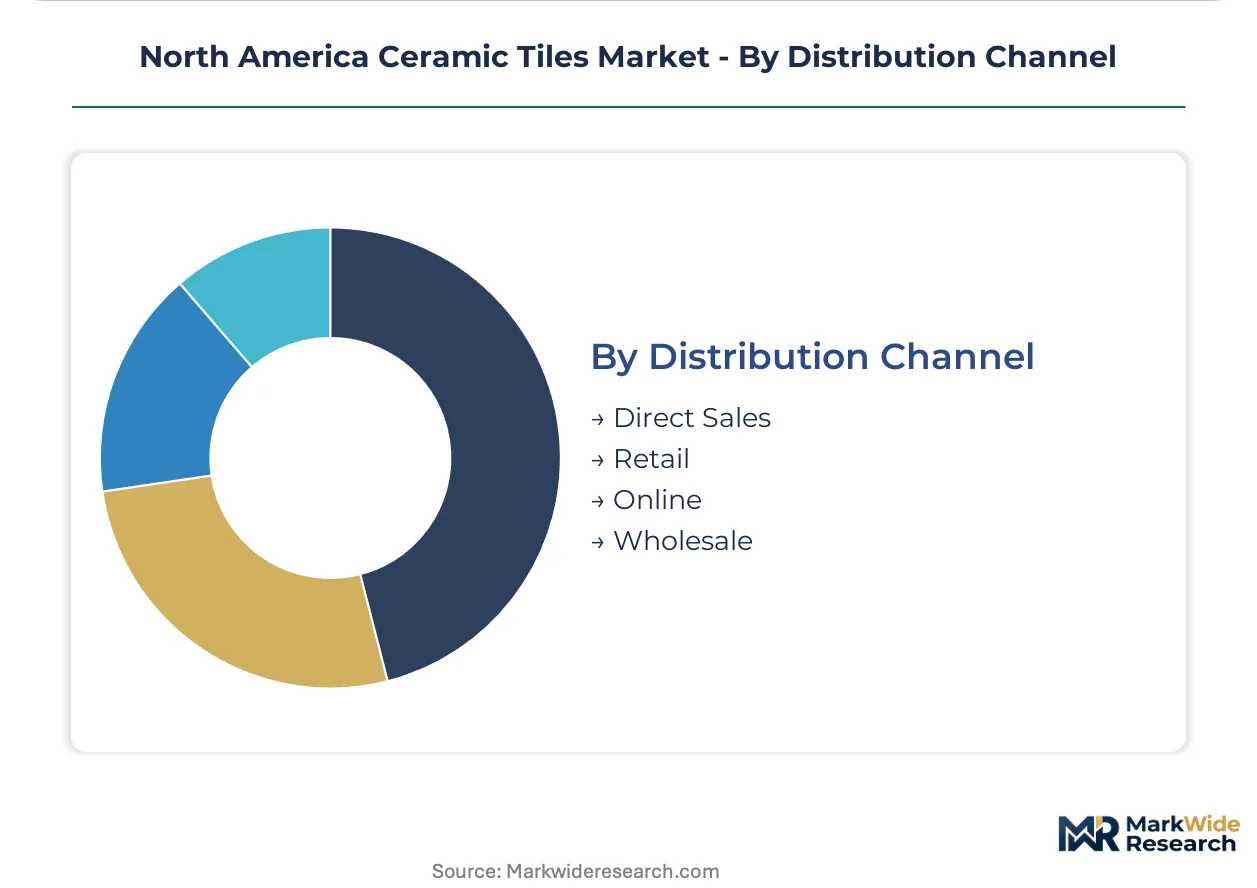
Distribution Channel:
Customer-type fragmentation separates project-scale procurement—large institutional buyers bypass retail margin layers while residential renovation relies on showroom specification support.
- Direct Sales:Manufacturer-to-contractor relationships consolidate around healthcare, education, and municipal construction verticals in Texas and Florida corridors where project scale supports dedicated supply agreements and logistics unbundling.
- Retail:Showroom-dependent residential specification maintains mature margin structures, with independent dealers and big-box channels competing on immediacy and installed-service bundling.
- Wholesale:Distributor intermediaries serve mid-tier commercial contractors with inventory pooling and credit terms, facing margin compression from direct manufacturer encroachment.
- Online:Digital procurement channels capture standard-grade residential replenishment and specification research, limited by tactile evaluation requirements for premium surface finishes.
Transaction volume flows through Retail showrooms; Direct Sales channels are gaining share fastest as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth and Miami-Dade metropolitan corridors concentrate porcelain tile demand as residential construction accelerates across Sun Belt housing markets. EPA Clean Air Act enforcement and California Title 24 energy codes are reshaping manufacturing investment patterns from Tennessee to Texas.
United States
Dallas-Fort Worth and Miami-Dade housing starts pull frost-resistant porcelain specifications for pool decks and exterior cladding. EPA emissions standards under the Clean Air Act force kiln operators in Tennessee and Alabama to deploy advanced baghouse filtration systems. Georgia and South Carolina kaolin deposits anchor domestic ceramic-grade clay sourcing for body formulation consistency.
Canada
Toronto and Vancouver high-rise mixed-use developments present specification white space for through-body porcelain in commercial envelopes. Health Canada building code harmonization with IECC thermal-mass requirements accelerates cool-roof tile adoption in British Columbia and Ontario. Quebec distribution channels serve Atlantic Canada renovation demand through Montreal-hub logistics consolidation.
Mexico
Nuevo León manufacturing zones near Monterrey leverage natural gas cost advantages for kiln-fired export production to Texas border markets. Mexican federal environmental standards under SEMARNAT tighten particulate emissions for ceramic operations in Guanajuato and Puebla. Bajío Region industrial parks attract U.S. tile distributors seeking nearshored supply chain resilience.
North America Ceramic Tiles Market Key Industry Players
Capital-heavy producers compete with asset-light designers as integrated manufacturers with captive raw material sourcing face off against specification-focused brands outsourcing production. The market consolidates around three tiers: vertically integrated multinationals controlling Georgia kaolin deposits, mid-scale domestic fabricators with specialized commercial-grade lines, and import-dependent distributors competing on pattern breadth. Dominant competitive moves include backward integration into raw material basins and direct-to-contractor channel bypass of traditional wholesale layers.
Within the integrated-manufacturer tier, Mohawk Industries and Florida Tile exemplify divergent strategic postures. Mohawk leverages Tennessee and Alabama production bases with captive supply chain control over clay formulation and distribution logistics. Florida Tile anchors its competitive stance through specialized domestic manufacturing focused on commercial-grade specifications rather than commodity residential lines. Crossville Inc. occupies a technology-leadership position among mid-scale specialists, differentiated through through-body porcelain expertise and recycled content formulations that align with tightening FTC green marketing guidelines.
| Leading Market Players |
|---|
| Florida Tile |
| Roca Tiles USA |
| Mohawk Industries |
| Vitromex USA |
| Emser Tile |
| Shaw Industries Group |
| Crossville Inc. |
| Bedrosians Tile & Stone |
| Interceramic |
| Others |
Cost & Logistics Intelligence
Large institutional buyers in Texas and Florida healthcare and education verticals command project-based contract pricing that compresses distributor margins and rewards direct manufacturer relationships with volume guarantees.
Pricing Analysis
Value-based pricing anchored to lifecycle durability and frost-resistance performance dominates commercial porcelain specifications. Pricing stratifies across premium through-body porcelain, standard glazed ceramic, and economy wall tile tiers based on ANSI A137.1 certification grade and body density. Cost compression in commodity glazed segments is intensifying because import competition from Mexican manufacturing zones erodes domestic producer margins. Residential renovation buyers exhibit highest price sensitivity, while institutional procurement teams prioritize total installed cost over unit pricing.
Supply Chain Analysis
Freight cost differentials between rail-served Tennessee production bases and truck-dependent Texas distribution hubs shape regional pricing spreads for large-format porcelain. Supply concentrates in the United States, Mexico, and China, with domestic manufacturing anchored in Georgia kaolin deposits and Tennessee-Alabama kiln corridors. Body formulation rests on ceramic-grade clay, feldspar fluxes, and silica fillers sourced from concentrated mineral basins. Single-source vulnerability in Georgia-South Carolina kaolin districts threatens formulation consistency during supply disruptions. Distribution runs through manufacturer-direct contractor channels for institutional buyers and retail showroom networks for residential specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions compliance investments and natural gas price volatility are forcing capital-constrained producers toward exit or acquisition, consolidating market control among integrated manufacturers with captive raw material access.
For Market Incumbents: Lock in kaolin supply agreements with Georgia and South Carolina deposit operators to secure body formulation consistency against import substitution threats. Expand direct sales infrastructure in Dallas-Fort Worth and Miami-Dade corridors where project scale supports dedicated logistics unbundling and long-term offtake contracts. For New Entrants and Emerging Players: Capture specification share in Toronto and Vancouver high-rise mixed-use developments where through-body porcelain penetration remains underdeveloped relative to U.S. Sun Belt markets. Lead with recycled content formulations and FTC-aligned green marketing claims to differentiate against established import-dependent distributors in Canadian commercial channels. For Investors and Strategic Acquirers: The window for entry favors mid-scale domestic fabricators with specialized commercial-grade lines and existing EPA compliance infrastructure. Target producers with captive Tennessee-Alabama kiln capacity and established contractor direct relationships. Monitor natural gas price stabilization and SEMARNAT enforcement intensity in Mexican manufacturing zones as inflection indicators for nearshoring cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Basins | Captive clay supply secures formulation consistency against Georgia-South Carolina deposit concentration risks. |
| Direct Contractor Channel Expansion | Bypasses wholesale margin layers in Texas and Florida institutional procurement consolidation. |
| Recycled Content Formulation Scale-Up | Aligns production with tightening FTC green marketing guidelines for public specification eligibility. |
| Large-Format Kiln Capacity Addition | Addresses specialized operator scarcity in Tennessee-Alabama production corridors for premium porcelain. |
| Canadian Distribution Partnership | Establishes specification presence in Toronto-Vancouver high-rise construction white space. |
Research Approach
Document review covered EPA Clean Air Act enforcement records, California Title 24 code amendments, and ANSI A137.1 certification databases, complemented by interviews with plant managers at Tennessee and Alabama manufacturing facilities, procurement leads at Texas healthcare systems, distribution channel partners in Florida metropolitan corridors, and technical R&D directors focused on through-body porcelain innovation. Secondary validation drew from SEC 10-K filings of integrated manufacturers, customs trade data for ceramic tile imports, and state-level housing start reports. Bottom-up demand modeling and top-down supply capacity assessment were triangulated against project pipeline data from institutional construction databases.
Market size and growth trajectory outputs reflect segmentation across product type, end user vertical, application surface, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of housing start correlations, renovation cycle intensity, and specification grade penetration curves. Industry-specific forecast inputs included natural gas price volatility scenarios for kiln operations and EPA emissions compliance cost trajectories for domestic production bases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California Title 24 code expansion into additional states, SEMARNAT enforcement intensity affecting Mexican export competitiveness, and OSHA silica exposure limit revisions impacting field installation costs. Forecasts reflect documented assumptions about housing construction cyclicality and regulatory harmonization patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market