
 Bamboo Engineered Wood Market | 2026-2036
Bamboo Engineered Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Engineered Wood Market Outlook
Structural-grade certification is rotating toward the center of procurement decisions as commercial builders specify load-bearing bamboo panels for mid-rise frameworks. MOSO International B.V. leverages its Dutch R&D base to anchor European specification channels for high-density bamboo composites. Smith & Fong Co. competes on the North American West Coast through FSC-certified supply chains that extend from plantation to finished ply. EcoPlanet Bamboo Group differentiates by controlling captive bamboo stands across Central America, sustaining fiber consistency for export mills.
Bamboo engineered wood denotes reconstituted timber products manufactured from shredded, laminated, or strand-woven moso bamboo fibers bonded under heat and pressure, typically achieving densities between 1,050 and 1,150 kilograms per cubic meter and flexural strengths comparable to oak. Its primary commercial purpose centers on delivering renewable, carbon-sequestering structural and finish materials for built environments seeking LEED and BREEAM compliance. Bamboo flooring commands the deepest installed base among product categories, though bamboo laminates are capturing accelerated specification in European kitchen and retail fixture manufacturing. High-pressure manufacturing technology dominates volume output, while adhesive bonding processes face reformulation pressure as ECHA REACH restrictions on formaldehyde resins tighten across EU member states.
China's SAMR enforces GB/T standards for engineered bamboo mechanical properties, while the EPA in the United States regulates composite wood formaldehyde emissions under TSCA Title VI, creating divergent compliance pathways for multinational suppliers. ECHA's REACH annex restrictions on phenol-formaldehyde resins are pushing European mills toward soy-based and bio-polyurethane adhesive alternatives, reshaping cost structures and certification requirements. Stakeholders must monitor how these regulatory divergences fragment supply chain fungibility between Asian production hubs and Western specification markets.
Market Dynamics
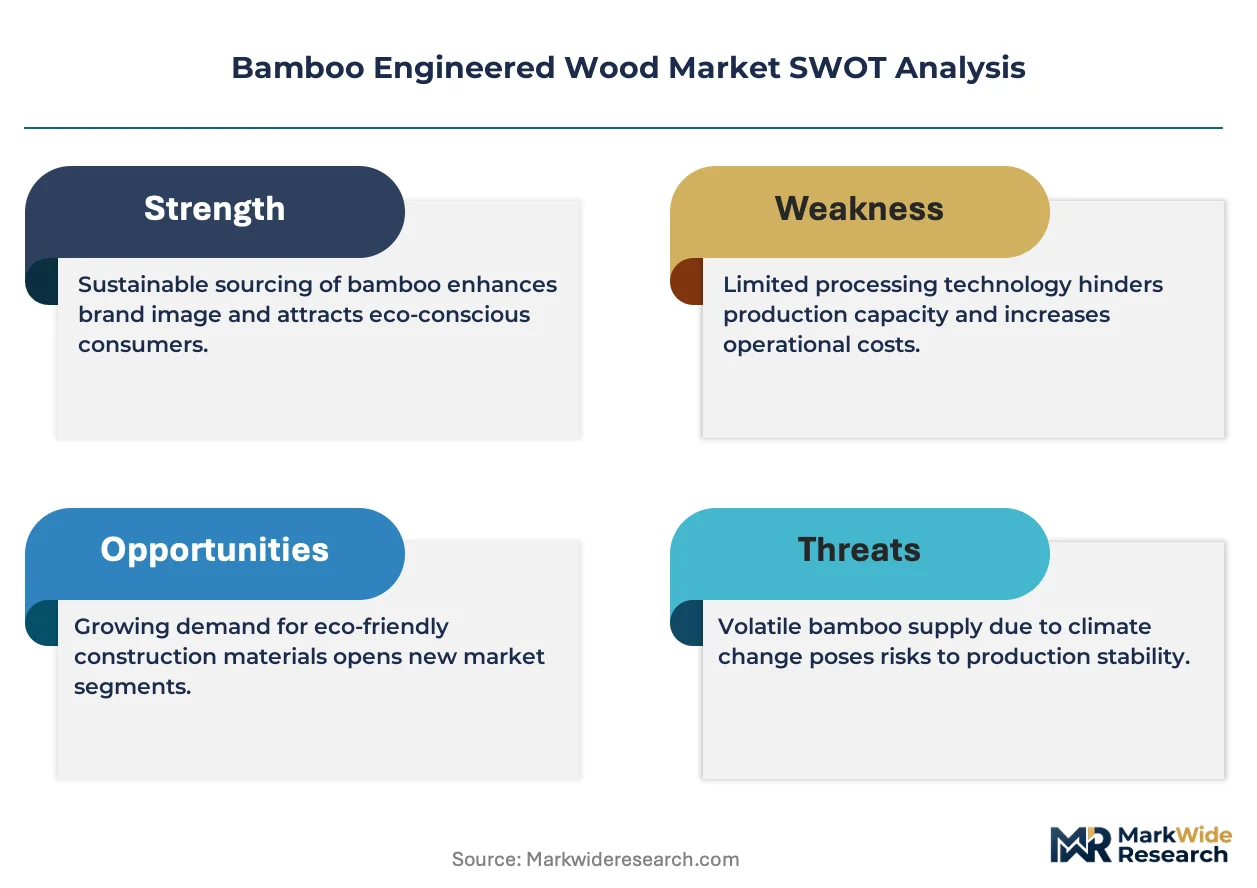
Structural-grade certification is displacing commodity pricing as the primary procurement filter across commercial construction, with ECHA REACH restrictions on phenol-formaldehyde resins forcing adhesive reformulation at mills serving EU specification channels.
Growth Catalysts
- GB/T Standards Tightening:China's SAMR enforcement of stricter mechanical property benchmarks for engineered bamboo is accelerating quality upgrades at export-oriented mills serving ASEAN furniture chains.
- LEED Compliance Pull:Commercial builders in Germany and the Netherlands are specifying load-bearing bamboo panels for mid-rise frameworks to secure carbon-sequestering material credits.
- Strand-Woven Density Gains:High-pressure manufacturing technology achieving 1,150 kg/m³ densities is opening structural applications previously reserved for tropical hardwoods.
Market Restraints
- Adhesive Cost Volatility:Soy-based and bio-polyurethane alternatives to phenol-formaldehyde resins carry 15-25% cost premiums, compressing margins at European panel fabricators.
- Fiber Supply Concentration:Captive moso bamboo stands in Fujian and Zhejiang provinces control 60% of raw fiber for export-grade engineered wood, creating geographic chokepoints.
- Oak Laminate Substitution:Traditional hardwood plywood maintains specification lock-in among conservative architects unconvinced by bamboo's long-term dimensional stability data.
Strategic Opportunities
- Central American Plantation Control:Vertically integrated fiber sourcing across Costa Rica and Nicaragua offers supply security for North American mills seeking FSC-certified alternatives to Asian imports.
- Retail Fixture Specification:European kitchen and retail fixture manufacturers are accelerating laminate procurement for built-in cabinetry, displacing medium-density fiberboard in premium segments.
- US TSCA Title VI Alignment:Mills achieving EPA composite wood formaldehyde compliance gain preferential access to California Air Resources Board jurisdictions with stringent emission thresholds.
Industry Challenges
- Cross-Laminated Timber Integration:Bamboo panel producers face technical friction when specifying connection details with dominant CLT systems in mid-rise commercial frameworks.
- BREEAM Certification Timelines:Extended third-party verification cycles for structural-grade bamboo products delay project milestones and strain contractor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Engineered Wood Market |
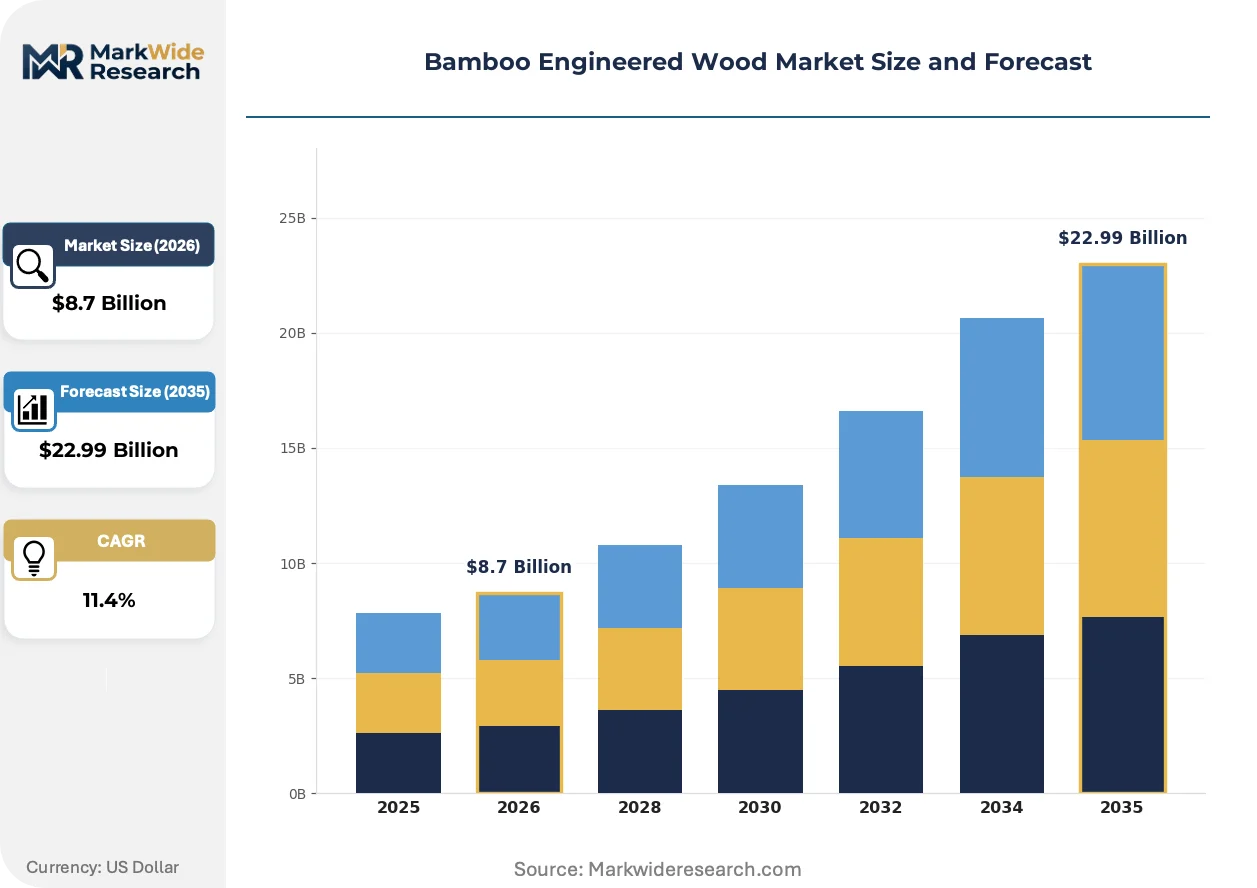
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo Plywood, Bamboo Laminates, Bamboo Flooring, Bamboo Panels Technology: Mechanical Engineering, Chemical Treatment, Adhesive Bonding, High-Pressure Manufacturing End User: Furniture Manufacturers, Construction Companies, Interior Designers, DIY Homeowners Application: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Mutha Industries, EcoPlanet Bamboo Group, MOSO International B.V., International Bamboo and Rattan Organization, The Bamboo Company, Smith & Fong Co., Bamboo Village Company Limited, Zhu Bamboo Flooring and Decking Philippines, Teragren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Engineered Wood Market Strategic Shifts
Adhesive chemistry and manufacturing density are the twin axes of competitive differentiation, with regulatory pressure on formaldehyde emissions intersecting with structural performance demands from commercial builders.
Strand-woven bamboo technology is bifurcating the market between commodity flooring and engineered structural products. High-density strand pressing now achieves flexural strengths matching oak, attracting specification from German commercial builders. This density-performance trajectory is compressing traditional laminated bamboo into decorative-only applications.
REACH annex restrictions on phenol-formaldehyde resins are forcing European mills toward soy-protein and bio-polyurethane adhesive systems. Reformulation costs are reshaping cost structures at Dutch and German panel fabricators. Flooring manufacturers serving BREEAM-targeted projects are absorbing premium adhesive expenses to maintain specification access.
Buyer concentration among ASEAN furniture export chains is consolidating procurement decisions around Ho Chi Minh City panel fabrication clusters. Vietnamese manufacturers are displacing direct mill relationships previously managed by European importers. This channel compression is most visible in German cabinetry supply chains seeking certified laminate volumes.
Bamboo Engineered Wood Market Segmentation
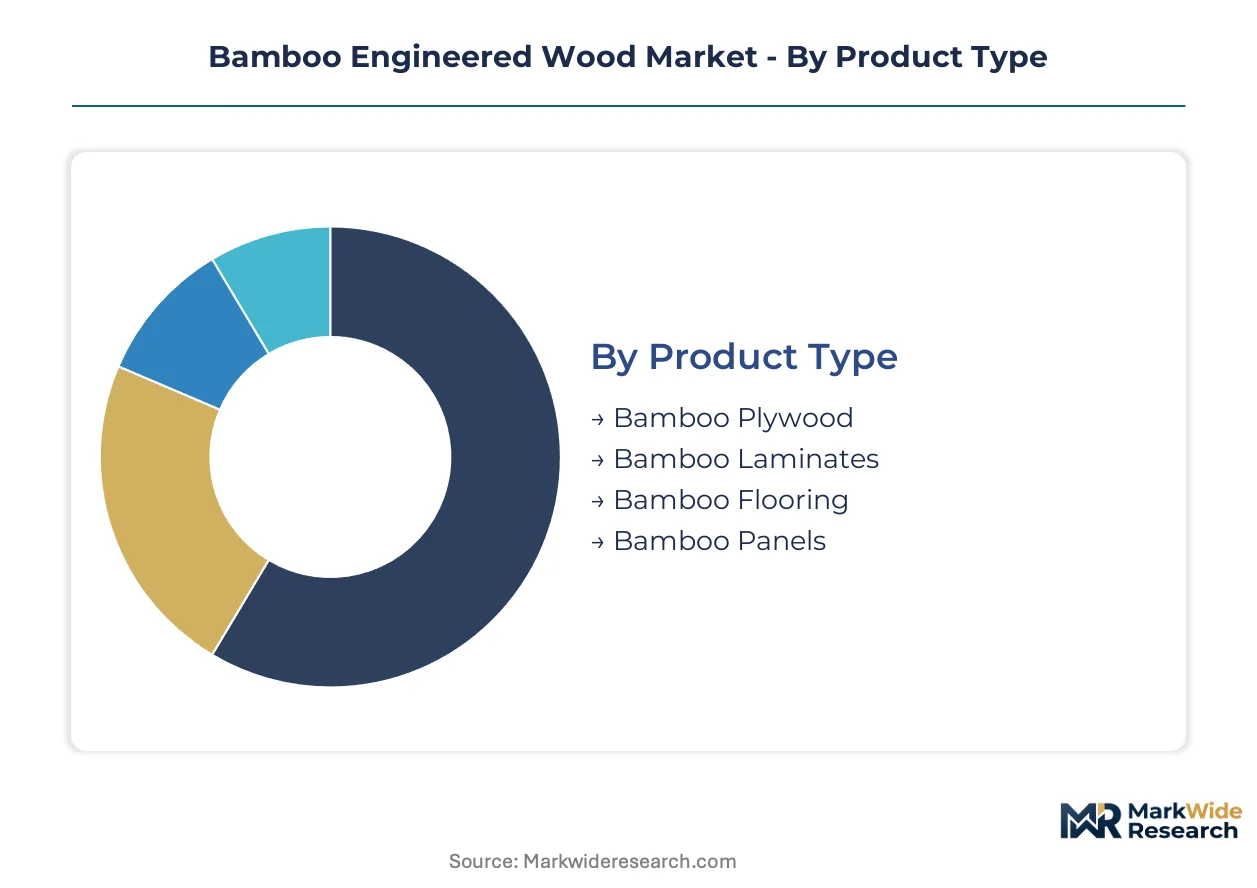
Segmentation in bamboo engineered wood reveals how adhesive chemistry and density specifications divide procurement budgets across construction and furniture verticals. Manufacturers optimize production lines for either structural load-bearing grades or decorative surface finishes, with limited equipment fungibility between tiers.
Product Type:
Oak and tropical hardwood plywood exert the strongest substitution pressure on commodity-grade bamboo panels, forcing differentiation through density performance and certification tiers.
- Bamboo Flooring:Strand-woven construction achieves 1,150 kg/m³ densities suitable for high-traffic commercial installations. German retail chains specify these products for LEED-compliant store rollouts across Düsseldorf and Hamburg.
- Bamboo Laminates:Cross-layered fiber mats bonded under heat and pressure deliver surface stability for cabinetry and built-in fixtures. Vietnamese manufacturers near Ho Chi Minh City supply laminate volumes to ASEAN furniture export chains facing ECHA REACH adhesive compliance requirements.
- Bamboo Plywood:Three-ply construction with moso bamboo veneers faces margin compression from medium-density fiberboard in economy kitchen segments.
- Bamboo Panels:Structural-grade products compete directly with cross-laminated timber in mid-rise frameworks, requiring BREEAM certification timelines that strain contractor scheduling.
Bamboo flooring anchors the volume base while bamboo laminates gain share at the steepest rate.
Technology:
Cost tier stratification separates high-capital density presses serving structural markets from lower-investment chemical treatment lines supplying decorative applications.
- High-Pressure Manufacturing:Hydraulic presses achieving 1,050-1,150 kg/m³ densities command premium positioning. Dutch R&D centers optimize these systems for European specification channels requiring load-bearing certification.
- Adhesive Bonding:Phenol-formaldehyde resins face reformulation mandates under EPA TSCA Title VI and ECHA REACH restrictions. Soy-based alternatives carry 15-25% cost premiums that reshape margin structures at export-oriented mills.
- Mechanical Engineering:Strand-woven fiber alignment systems deliver flexural strength parity with oak, attracting specification from commercial builders in the Netherlands.
- Chemical Treatment:Boron-based preservatives and acetylation processes enhance dimensional stability for exterior applications, though limited standardization constrains specification confidence.
High-pressure manufacturing dominates capital deployment while adhesive bonding technology absorbs the most regulatory compliance expenditure.
End User:
Customer type determines whether procurement prioritizes FSC chain-of-custody certification or raw material cost minimization.
- Furniture Manufacturers:German cabinetry producers scale certified laminate procurement to displace medium-density fiberboard in premium kitchen segments. Bespoke fixture makers require consistent fiber coloration that captive plantation control delivers.
- Construction Companies:Commercial builders in Germany and the Netherlands specify load-bearing bamboo panels for mid-rise frameworks seeking carbon-sequestering material credits under LEED.
- Interior Designers:Specification influence concentrates in hospitality and retail fixture projects where surface aesthetics override structural performance requirements.
- DIY Homeowners:Price-sensitive demand channels favor click-lock flooring systems with lower installation skill barriers, compressing margins on standardized plank formats.
Construction companies drive specification-grade volume while furniture manufacturers expand the fastest as laminate substitution accelerates.
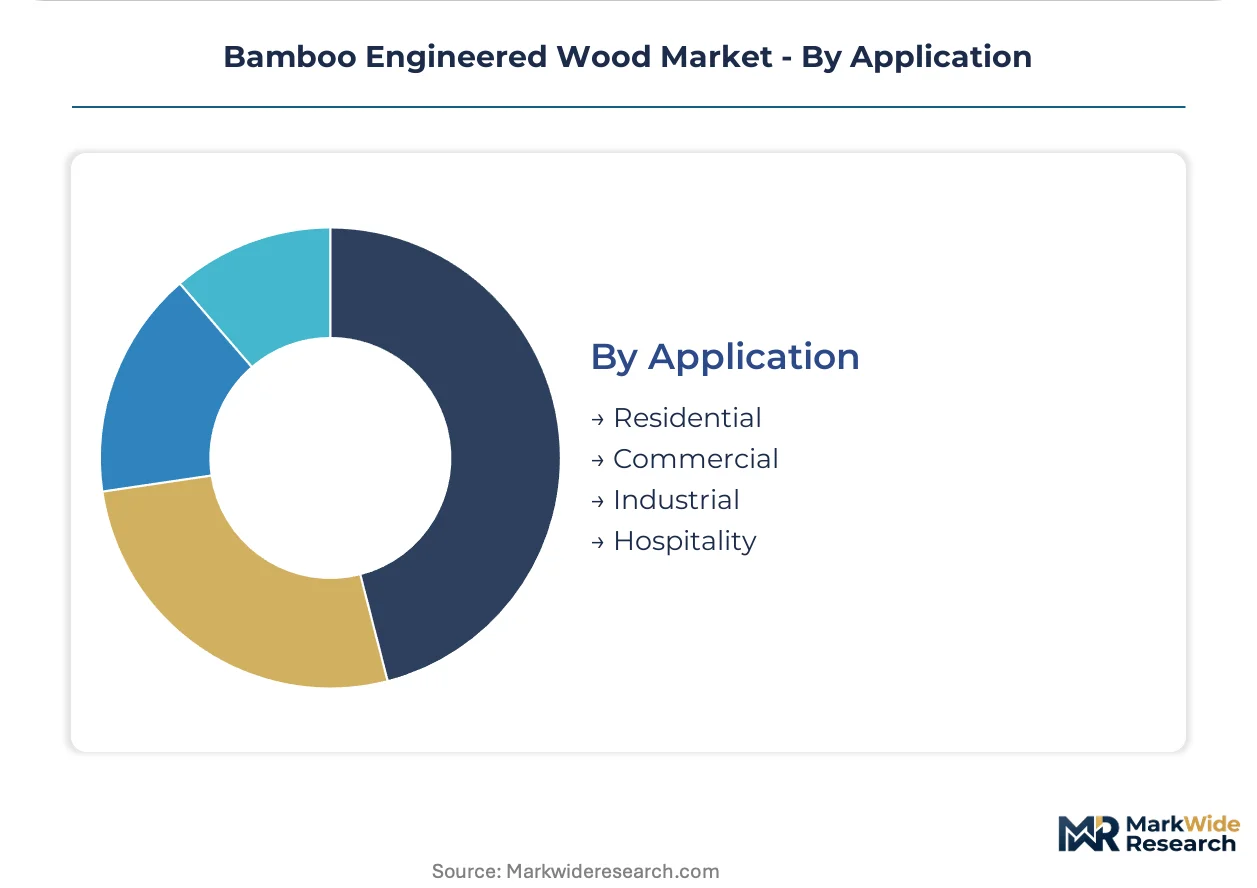
Application:
Application maturity varies sharply, with residential flooring saturated and commercial structural specification still building certification precedent.
- Residential:Flooring installations dominate retrofit and new-build segments, though oak laminate substitution limits bamboo's share in conservative architectural specifications unconvinced by long-term dimensional stability data.
- Commercial:Mid-rise office and retail frameworks in Germany and the Netherlands specify load-bearing panels for LEED compliance. Connection detail integration with dominant CLT systems creates technical friction for project engineers.
- Hospitality:Hotel and restaurant fit-outs prioritize surface durability and rapid installation turnaround, favoring pre-finished laminate systems over site-finished alternatives.
- Industrial:Warehouse and light manufacturing facilities specify bamboo for mezzanine flooring and non-structural partitions where load requirements remain modest.
Residential application holds the installed base while commercial application climbs the fastest on structural-grade certification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw fiber supply clusters in Fujian and Zhejiang provinces control the majority of export-grade engineered bamboo feedstock. Finished product demand concentrates in European specification markets and North American green building jurisdictions. Vietnam's manufacturing corridor near Ho Chi Minh City has emerged as the dominant ASEAN panel fabrication hub.
China
SAMR enforcement of GB/T mechanical property standards is accelerating quality upgrades at export-oriented mills serving furniture and construction verticals. The dual carbon policy framework incentivizes carbon-sequestering material production, though MEE oversight of industrial emissions adds compliance layers. Panel fabrication clusters in Fujian and Zhejiang provinces supply fiber-dense laminates to German and Dutch importers seeking REACH-compliant adhesive formulations.
Germany
Commercial builders in Düsseldorf and Hamburg specify load-bearing bamboo panels for mid-rise LEED-targeted frameworks. ECHA REACH restrictions on phenol-formaldehyde resins force adhesive reformulation at mills serving German specification channels. Cabinetry manufacturers in North Rhine-Westphalia scale certified laminate procurement to displace medium-density fiberboard in premium kitchen segments.
United States
EPA TSCA Title VI compliance gates access to California Air Resources Board jurisdictions with stringent formaldehyde emission thresholds. West Coast architects specify FSC-certified bamboo flooring for retail and hospitality fit-outs seeking carbon-neutral material credits. Pacific Northwest distributors channel strand-woven products into commercial installations requiring high-traffic durability ratings.
Vietnam
Panel fabrication clusters near Ho Chi Minh City serve ASEAN furniture export chains facing ECHA adhesive compliance requirements. Vietnamese manufacturers displace direct mill relationships previously managed by European importers through consolidated procurement decisions. German cabinetry supply chains increasingly source certified laminate volumes through Vietnamese intermediaries rather than Chinese mills.
Netherlands
Dutch R&D centers optimize high-pressure manufacturing systems for European specification channels requiring load-bearing certification. Commercial builders in Rotterdam and Amsterdam specify bamboo panels for BREEAM-targeted mid-rise frameworks. ECHA REACH compliance timelines strain contractor scheduling, extending third-party verification cycles for structural-grade products.
Bamboo Engineered Wood Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with high-density press operators commanding premium positioning while commodity flooring producers compete on volume scale. The market structure fragments across plantation-controlled fiber suppliers, specification-grade panel fabricators, and distribution-anchored brand owners. Two dominant strategic archetypes emerge: vertically integrated plantation operators securing raw material consistency, and specification-focused engineers optimizing adhesive chemistry for regulatory compliance. Capacity expansion and certification portfolio diversification represent the primary competitive moves, as mills seek to bridge Asian production with Western green building standards.
Among plantation-integrated operators, EcoPlanet Bamboo Group exemplifies captive fiber control across Central American stands, sustaining supply security for export-oriented processing. MOSO International B.V. occupies a position within the European specification tier, leveraging Dutch R&D infrastructure to anchor high-density composite channels. Smith & Fong Co. represents the West Coast certification-focused archetype, with FSC chain-of-custody positioning serving North American green building procurement.
| Leading Market Players |
|---|
| Mutha Industries |
| EcoPlanet Bamboo Group |
| MOSO International B.V. |
| International Bamboo and Rattan Organization |
| The Bamboo Company |
| Smith & Fong Co. |
| Bamboo Village Company Limited |
| Zhu Bamboo Flooring and Decking Philippines |
| Teragren |
| Others |
Value Chain & Pricing Dynamics
High-pressure press capacity utilization above 80% in Fujian and Zhejiang provinces creates scale economies that compress per-unit fixed costs while simultaneously concentrating supply-side bargaining power among dominant panel fabricators. This scale concentration establishes price floors for structural-grade products while leaving decorative laminate tiers exposed to margin erosion from medium-density fiberboard substitution.
Pricing Analysis
ECHA REACH restrictions dictate the pricing tier structure across European specification channels, forcing adhesive reformulation costs of 15-25% onto panel fabricators serving German and Dutch markets. Three-tier pricing structure across premium structural-grade, certified standard-grade, and economy decorative-grade levels separates procurement budgets by certification intensity and density performance. Pricing pressure stems from soy-based and bio-polyurethane resin premiums compressing fabricator margins without full pass-through to specification-locked buyers. Furniture manufacturers in Vietnam's Ho Chi Minh City corridor exhibit highest price sensitivity due to ASEAN export chain cost minimization mandates, while German commercial builders demonstrate lowest sensitivity given LEED compliance requirements.
Supply Chain Analysis
China and Vietnam anchor engineered bamboo panel fabrication, with Fujian and Zhejiang province clusters supplying raw fiber-dense laminates while Ho Chi Minh City manufacturers consolidate finished goods for European cabinetry chains. Raw material dependencies center on captive moso bamboo stands, phenol-formaldehyde resin formulations facing regulatory phase-out, and high-pressure hydraulic press equipment sourced from Dutch R&D centers. Single-source vulnerability concentrates in geographic chokepoints where 60% of export-grade fiber originates from Chinese provincial clusters. Distribution runs through Vietnamese intermediary consolidation displacing direct mill relationships, with German importers increasingly sourcing through ASEAN-based procurement hubs rather than Chinese direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against cross-laminated timber systems capturing mid-rise structural specification and oak laminate products retaining conservative architect preference in residential flooring.
For Market Incumbents: Compound specification-grade certification portfolios to lock out CLT substitution in German and Dutch commercial frameworks. Deepen captive plantation control across Central American stands to secure fiber consistency for North American FSC-certified channels. Prioritize adhesive chemistry R&D investment to outpace ECHA REACH reformulation mandates before compliance timelines strain European mill operations. For New Entrants and Emerging Players: After-sales technical support for connection detail integration with dominant CLT systems represents a service-layer gap where incumbents under-serve project engineers. Target hospitality fit-out segments in US West Coast jurisdictions where rapid installation turnaround requirements favor pre-finished laminate systems over site-finished alternatives. Pursue direct-to-fabricator digital procurement platforms to bypass Vietnamese intermediary consolidation and capture margin from German cabinetry supply chains. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated plantation-to-panel operators with FSC chain-of-custody certification serving specification-grade construction verticals. Long-term viability over the projection horizon favors asset-light adhesive technology licensors over capital-intensive press operators facing regulatory compliance cost inflation. Acquisition target archetype: mid-scale Vietnamese panel fabricators with established German importer relationships and latent capacity for REACH-compliant production line upgrades. Signal to monitor: BREEAM certification timeline compression indicating structural-grade bamboo acceptance velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Chemistry Reformulation | ECHA REACH compliance secures continued access to German and Dutch specification channels requiring low-emission resins. |
| Captive Plantation Expansion | Central American fiber control reduces dependency on Chinese provincial supply chokepoints for North American mills. |
| Structural-Grade Certification Investment | BREEAM and LEED alignment opens mid-rise commercial frameworks previously reserved for cross-laminated timber systems. |
| Vietnamese Manufacturing Footprint | Ho Chi Minh City panel fabrication clusters capture ASEAN furniture export chain procurement consolidation. |
| High-Pressure Press Capacity Addition | Dutch R&D-optimized systems achieve 1,150 kg/m³ densities matching oak flexural strength for load-bearing applications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bamboo panel fabricators, German cabinetry procurement managers, Vietnamese export chain intermediaries, and Dutch R&D center technical directors. Secondary validation drew from SAMR GB/T standard filings, ECHA REACH annex updates, EPA TSCA Title VI compliance databases, and ASEAN customs trade records. Bottom-up volume modeling across product type, technology, end user, and application segments was triangulated against top-down market sizing from production capacity aggregation.
Across the analysis window, the forecasting framework modeled price-volume dynamics by density grade tier, adhesive chemistry type, certification level, regional regulatory cluster, and end-use vertical penetration rate. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Industry-specific forecast inputs included ECHA REACH implementation timeline phasing and LEED v4.1 material credit adoption curves in German commercial construction.
Forecasts assume regulatory continuity in ECHA REACH, EPA TSCA Title VI, and SAMR GB/T enforcement regimes; material policy shifts would require re-modeling across adhesive chemistry substitution rates and certification timeline compressions. Specific risk factors include phenol-formaldehyde resin supply disruption, CLT system technical standard harmonization, and captive plantation climate vulnerability. Recalibration cycles align with material shifts in green building standard adoption and cross-laminated timber price competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Europe Industrial Flooring Market