
 China Concrete Superplasticizer Market | 2026-2036
China Concrete Superplasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
China Concrete Superplasticizer Market Intelligence
Shandong province is fragmenting as domestic chemical manufacturers expand polycarboxylate ether capacity to serve northern China's construction belt. BASF leverages its global R&D network to sustain premium positioning among multinational contractors operating in tier-one cities. Shandong Wanshan Chemical anchors supply relationships with provincial state-owned construction enterprises through backward integration into ethylene oxide feedstocks. Sika AG competes on technical service density, maintaining application laboratories in Chengdu and Shanghai to support specification-driven project wins.
Concrete superplasticizers are high-range water-reducing admixtures, typically formulated from polycarboxylate ether copolymers or sulfonated melamine condensates, that enable flowable concrete at water-cement ratios below 0.30 without segregation. These additives permit placement of self-consolidating concrete in dense reinforcement configurations while maintaining compressive strength targets above 60 MPa. Polycarboxylate ether products command the dominant share of value given their superior slump retention and compatibility with supplementary cementitious materials. Infrastructure applications represent the fastest-expanding demand pool as provincial governments prioritize durability specifications for hydropower and transportation assets. Ready-mix concrete channels absorb the majority of volume, though precast segments offer more stable pricing through long-term supply agreements with factory operators.
MIIT enforces GB 8076 standards governing superplasticizer performance in concrete, while MEE implements dual carbon goals that pressure manufacturers toward lower-energy synthesis routes and bio-based raw material sourcing. Provincial construction quality supervision stations in Jiangsu and Guangdong conduct batch testing of admixtures for chloride content and formaldehyde release, creating compliance barriers for unqualified suppliers. Stakeholders must monitor how China's evolving low-carbon building codes redefine acceptable chemistries before committing to capacity expansions or formulation portfolios.
Market Dynamics
Polycarboxylate ether chemistry is consolidating procurement power among infrastructure contractors who specify slump retention above 180 minutes for megaproject concrete pours. This molecular transition compresses margins for sulfonated melamine producers while elevating technical service requirements across the admixture supply base.
Growth Catalysts
- GB 8076 Durability Mandates:MIIT enforcement of updated performance standards for high-strength concrete is compelling provincial transportation departments to specify polycarboxylate ether admixtures in bridge and tunnel specifications.
- Hydropower Asset Expansion:Western China's cascade hydropower construction under the 14th Five-Year Plan is generating concentrated demand for sulfate-resistant concrete formulations with extended workability windows.
- Yangtze River Delta Clustering:Municipal governments in Jiangsu and Zhejiang are consolidating ready-mix procurement through state-owned platforms, creating volume anchors for qualified superplasticizer suppliers.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Polycarboxylate ether synthesis depends on ethylene oxide availability from petrochemical complexes concentrated in Shandong and Jiangsu, exposing margins to naphtha-cracking economics.
- Coastal Manufacturing Concentration:Over 60 percent of active superplasticizer capacity sits within 200 kilometers of Shanghai port, creating systemic disruption risk from typhoon-season logistics interruptions.
- Naphthalene Sulfonate Lock-In:Legacy precast concrete factories retain capital equipment optimized for sulfonated naphthalene chemistry, delaying conversion to polycarboxylate ether systems despite performance gaps.
Strategic Opportunities
- Western China Infrastructure Gap:Sichuan and Yunnan provinces lack localized polycarboxylate ether production, forcing contractors to absorb elevated logistics costs from coastal suppliers.
- Dual Carbon Synthesis Incentives:MEE low-carbon manufacturing credits reward producers adopting bio-based polyether backbones and solvent-free polymerization routes.
- Digital Admixture Batching:IoT-enabled dosing systems in ready-mix plants are creating data-rich relationships between suppliers and contractors, embedding superplasticizer vendors in quality-control workflows.
Industry Challenges
- Application Engineering Shortage:Qualified concrete technologists who can optimize polycarboxylate ether dosage for complex supplementary cementitious material blends remain scarce outside tier-one cities.
- Provincial Certification Lag:Construction quality supervision stations in interior provinces maintain inconsistent testing protocols for chloride content and formaldehyde release, delaying product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Concrete Superplasticizer Market |
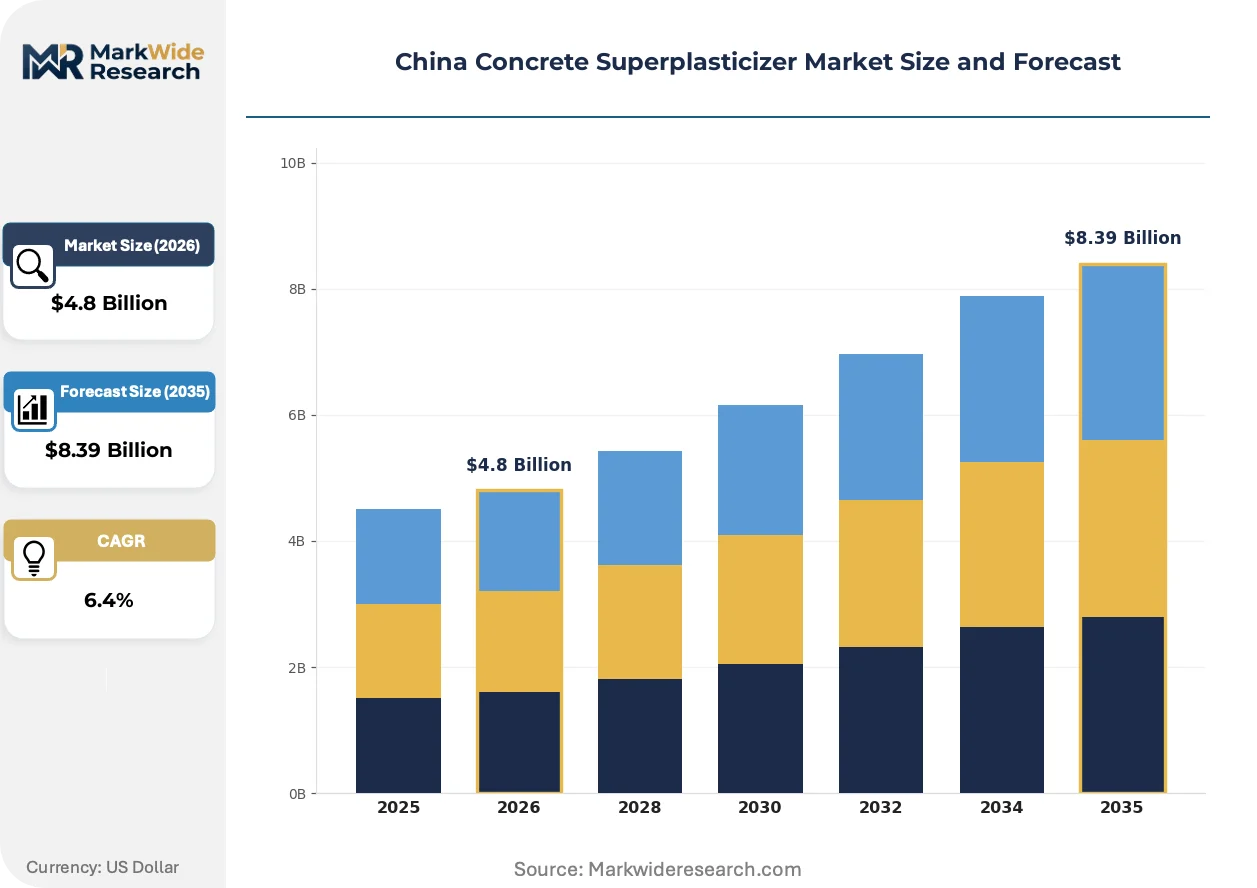
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylate Ether, Sulfonated Melamine Formaldehyde, Naphthalene Sulfonate, Others End User: Residential Construction, Commercial Construction, Infrastructure, Industrial Projects Distribution Channel: Online Sales, Direct Sales, Distributors, Retailers Application: Ready-Mix Concrete, Precast Concrete, Shotcrete, Self-Consolidating Concrete |
| Companies Covered | BASF, Arkema, Shandong Wanshan Chemical Co., Ltd., Fosroc, Inc., Kao Corporation, Zhejiang LanYa Concrete Admixture Inc., MAPEI S.p.A., Hangzhou Lans Concrete Admixture, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Concrete Superplasticizer Market Strategic Shifts & Innovations
Formulation chemistry and procurement digitization are converging to reshape how concrete contractors source and deploy high-range water reducers. Three developments are compressing legacy business models while opening technical differentiation pathways.
Hybrid polycarboxylate ether-graft architectures with tailored side-chain densities are rendering obsolete conventional slump-retention strategies that relied on separate retarder additions. Infrastructure contractors in Guangdong and Fujian are specifying these integrated systems for continuous pours exceeding 12 hours. The technology is compressing the supplier base toward polymer synthesis capabilities that in-house laboratories cannot replicate.
MEE enforcement of dual carbon goals is tightening energy-intensity thresholds for chemical manufacturing licenses. Polycarboxylate ether producers must document carbon footprints across ethylene oxide procurement and polymerization stages to maintain operating permits. Shandong-based manufacturers are responding by retrofitting plants with combined heat-and-power systems and sourcing bio-ethylene oxide from ethanol dehydration units.
Specification-driven procurement through provincial state-owned construction group platforms is displacing spot-market purchasing in ready-mix channels. Long-term framework agreements now bundle superplasticizer supply with technical service commitments and performance guarantees. This shift is most visible in Jiangsu, where Nanjing and Suzhou municipal infrastructure bureaus mandate approved vendor lists for admixture categories.
China Concrete Superplasticizer Market Segmentation
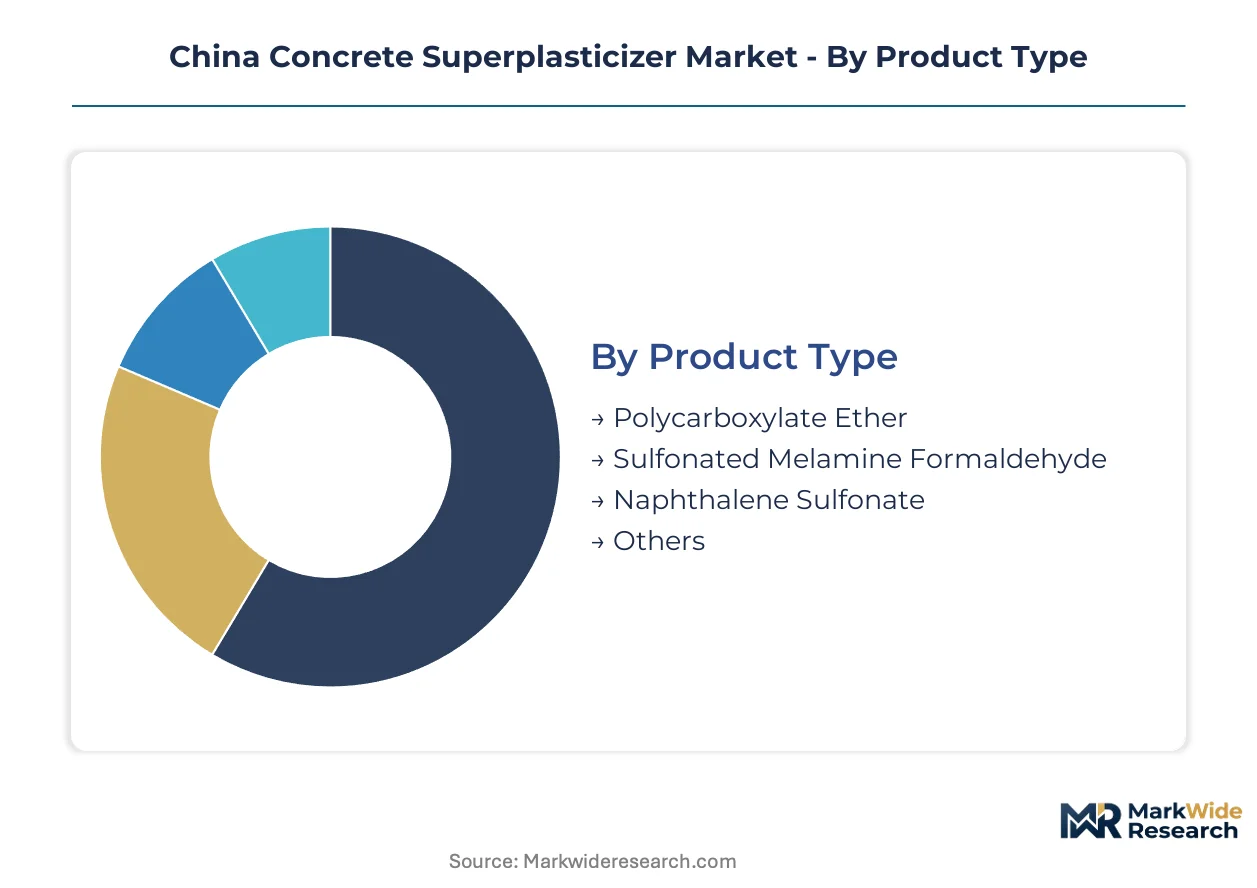
Superplasticizer segmentation in China reveals distinct technical service requirements across molecular chemistries and placement methods. Procurement patterns diverge sharply between infrastructure contractors demanding extended slump retention and precast factories prioritizing batch-to-batch consistency.
Product Type:
After-sales intensity varies dramatically by chemistry — polycarboxylate ether formulations demand on-site dosage optimization and compatibility testing with local cement sources, while legacy chemistries require minimal technical intervention.
- Polycarboxylate Ether:Copolymer architectures with tunable side-chain densities enable water reduction above 30 percent at low dosages. Yangtze River Delta infrastructure contractors specify these systems for continuous pours exceeding six hours, though ethylene oxide feedstock volatility compresses margins during petrochemical price spikes.
- Sulfonated Melamine Formaldehyde:Condensate polymers retain niche positioning in precast applications where rapid strength development outweighs slump retention needs. Northern China's legacy concrete factories maintain equipment calibrated for these chemistries, delaying conversion despite performance gaps with polycarboxylate alternatives.
- Naphthalene Sulfonate:Sulfonated naphthalene formaldehyde condensates dominate cost-sensitive ready-mix segments in interior provinces with less stringent GB 8076 enforcement.
- Others:Lignosulfonate and amino-sulfonate formulations serve specialty applications requiring retarding or air-entrainment compatibility.
By volume, naphthalene sulfonate leads. By growth pace, polycarboxylate ether is expanding most quickly.
End User:
Cost tier stratification separates specification-driven procurement from price-sensitive spot purchasing across construction verticals.
- Infrastructure:Provincial transportation departments enforce GB 8076 durability mandates for bridges, tunnels, and hydropower assets. Western China's cascade dam construction under the 14th Five-Year Plan concentrates demand for sulfate-resistant formulations with 180-minute slump retention.
- Commercial Construction:High-rise developments in tier-one cities specify self-consolidating concrete for dense reinforcement zones, requiring superplasticizer suppliers to maintain application laboratories for dosage calibration.
- Residential Construction:Volume-driven ready-mix procurement through municipal platforms dominates this segment, with price competition intensifying among Shandong-based manufacturers.
- Industrial Projects:Petrochemical and power generation facilities demand specialized formulations resisting aggressive chemical exposure and thermal cycling.
Infrastructure commands premium pricing. Residential construction absorbs the greatest tonnage.
Distribution Channel:
Customer type determines channel selection — multinational contractors favor direct relationships with technical service commitments, while regional ready-mix operators rely on distributor networks for logistics coverage.
- Direct Sales:Framework agreements with provincial state-owned construction groups bundle superplasticizer supply with performance guarantees and on-site technical support. BASF and Sika AG compete primarily through this channel in tier-one cities.
- Distributors:Regional chemical distributors serve interior provinces where localized inventory buffers against logistics disruption from coastal manufacturing concentration.
- Online Sales:Digital procurement platforms are emerging for standardized naphthalene sulfonate grades in price-transparent spot markets.
- Retailers:Limited to small-volume admixture sales for repair and renovation contractors.
Direct sales capture the highest margins. Distributors move the largest volumes.
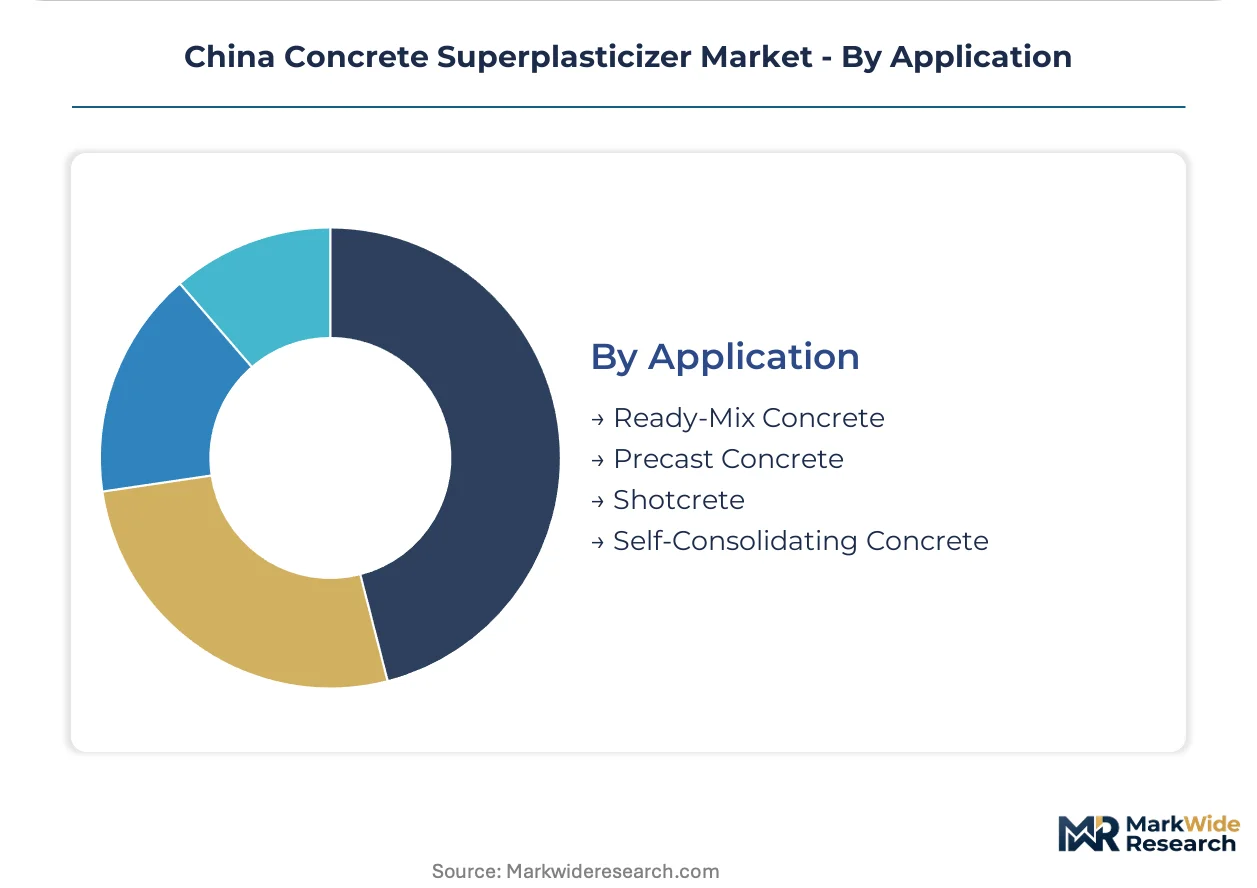
Application:
Volume concentration and margin structure diverge across placement technologies, with ready-mix channels offering scale and precast segments providing pricing stability.
- Ready-Mix Concrete:Municipal consolidation of procurement through state-owned platforms in Jiangsu and Zhejiang creates volume anchors for qualified suppliers. IoT-enabled batching systems are embedding vendors in quality-control workflows.
- Precast Concrete:Factory-based production enables long-term supply agreements with stable pricing, though legacy naphthalene sulfonate equipment delays polycarboxylate ether adoption.
- Self-Consolidating Concrete:Flowable formulations for dense reinforcement require high-performance polycarboxylate ether systems with viscosity-modifying compatibility.
- Shotcrete:Accelerated setting demands specialized admixture blends combining superplasticizers with alkali-free accelerators for tunnel and mining applications.
Ready-mix concrete dominates volume. Self-consolidating concrete shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB 8076 standards enforcement across China's provincial construction quality supervision stations anchors demand geography in the Yangtze River Delta and Shandong Peninsula, where infrastructure durability mandates concentrate procurement of high-performance polycarboxylate ether admixtures.
Yangtze River Delta
Jiangsu and Zhejiang provincial transportation departments specify polycarboxylate ether systems for bridge and tunnel applications exceeding 180-minute slump retention. Municipal governments consolidate ready-mix procurement through state-owned platforms, creating volume anchors for qualified suppliers. Nanjing and Suzhou infrastructure bureaus mandate approved vendor lists for admixture categories, embedding technical service requirements in long-term framework agreements.
Shandong Peninsula
Domestic chemical manufacturers expand polycarboxylate ether capacity to serve northern China's construction belt. Ethylene oxide feedstock availability from regional petrochemical complexes supports backward integration strategies among local producers. Qingdao and Yantai industrial zones concentrate manufacturing assets within 200 kilometers of coastal logistics infrastructure.
Beijing-Tianjin-Hebei
MEE dual carbon goals pressure manufacturers toward lower-energy synthesis routes and bio-based raw material sourcing. Provincial construction quality supervision stations conduct batch testing for chloride content and formaldehyde release. Tianjin port facilities handle import volumes for multinational contractors operating in tier-one infrastructure projects.
Sichuan-Chongqing
Western China's cascade hydropower construction under the 14th Five-Year Plan generates concentrated demand for sulfate-resistant concrete formulations. Localized polycarboxylate ether production remains absent, forcing contractors to absorb elevated logistics costs from coastal suppliers. Chengdu hosts application laboratories supporting specification-driven project wins.
Pearl River Delta
Guangdong and Fujian infrastructure contractors specify hybrid polycarboxylate ether-graft architectures for continuous pours exceeding 12 hours. Provincial construction quality supervision stations enforce stricter GB standards for durable concrete in coastal megacity applications. Shenzhen and Guangzhou municipal platforms bundle superplasticizer supply with performance guarantees.
China Concrete Superplasticizer Market Key Industry Players
Multinational chemical conglomerates and domestic petrochemical specialists split the market along technical service intensity and feedstock integration vectors. Tier-one city infrastructure contractors favor specification-driven procurement relationships requiring application laboratory support. Three archetypes dominate: global R&D-led formulators with premium positioning, Shandong-based ethylene oxide-integrated manufacturers competing on cost, and regional technical service specialists anchoring provincial state-owned construction relationships. Competitive moves concentrate on backward integration into ethylene oxide feedstocks and geographic expansion into western China infrastructure gaps.
Among global R&D-led formulators, BASF leverages its worldwide research network to sustain premium positioning among multinational contractors. Sika AG competes through technical service density, maintaining application laboratories in Shanghai and Chengdu. Within the domestic integrated tier, Shandong Wanshan Chemical Co., Ltd. exemplifies feedstock-backward strategies, anchoring supply relationships through captive ethylene oxide production. These three occupy distinct competitive positions without overlapping core customer segments.
| Leading Market Players |
|---|
| BASF |
| Arkema |
| Shandong Wanshan Chemical Co., Ltd. |
| Fosroc, Inc. |
| Kao Corporation |
| Zhejiang LanYa Concrete Admixture Inc. |
| MAPEI S.p.A. |
| Hangzhou Lans Concrete Admixture |
| Sika AG |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port freight corridors transmit ethylene oxide feedstock cost volatility directly into polycarboxylate ether pricing tiers, compressing margins for coastal manufacturers while amplifying geographic price spreads between Shandong-integrated suppliers and inland distributors serving western China infrastructure projects.
Pricing Analysis
Coastal-to-interior price spreads exceed 15 percent for polycarboxylate ether formulations, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade under MIIT GB 8076 standards and volume-scale procurement through provincial state-owned construction platforms. Price differentiation rests on ethylene oxide backward integration and technical service bundling, with Shandong-based manufacturers driving cost compression in the economy tier through captive feedstock supply. Margins are tightening due to naphtha-cracking economics and petrochemical price cycles. Residential construction buyers exhibit highest price sensitivity, while infrastructure contractors prioritize slump retention performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Shandong Wanshan Chemical, Zhejiang LanYa Concrete Admixture, and Hangzhou Lans Concrete Admixture, which collectively anchor polycarboxylate ether synthesis capacity within 200 kilometers of Shanghai and Qingdao port infrastructure. Geographic supply concentrates in Shandong, Jiangsu, and Zhejiang provinces, drawing from ethylene oxide, naphtha, and methanol feedstock streams. Single-source vulnerability runs through coastal manufacturing clustering exposed to typhoon-season logistics interruption. Distribution runs through provincial state-owned construction group platforms and regional chemical distributors serving interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where MIIT GB 8076 certification entrenchment and switching costs embedded in long-term framework agreements protect qualified suppliers from price-only competition.
For Market Incumbents: Insulate market position by deepening ethylene oxide backward integration in Shandong petrochemical corridors and securing provincial construction quality supervision station certifications ahead of formaldehyde release standard tightening. Threats from sulfonated melamine substitute technologies in legacy precast segments demand accelerated polycarboxylate ether conversion programs. Priority lever: application laboratory expansion into Sichuan-Chongqing hydropower zones.
For New Entrants and Emerging Players: Establish a beachhead in Yunnan and Guizhou provinces where localized polycarboxylate ether production remains absent and contractors absorb elevated logistics premiums from coastal suppliers. White-space targets include sulfate-resistant formulations for cascade dam construction and bio-based polyether backbones qualifying for MEE dual carbon manufacturing credits. Go-to-market angle: technical service partnerships with western China provincial transportation departments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ethylene oxide-integrated domestic manufacturers with captive feedstock and established provincial state-owned construction relationships over multinational R&D-led formulators facing margin compression. Long-term viability across the projection horizon rests on dual carbon compliance infrastructure and western China geographic expansion. Acquisition target archetype: Shandong-based producers with unutilized polymerization capacity. Signal to watch: MEE low-carbon manufacturing credit allocation rates as inflection indicator for regulatory cost advantage shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply from Shandong petrochemical complexes insulates margin compression during naphtha price spikes. |
| Western China Application Laboratory Expansion | Chengdu and Chongqing technical facilities anchor specification-driven wins in cascade hydropower construction. |
| Bio-Based Polyether Backbone Transition | Ethanol-dehydration-derived ethylene oxide qualifies for MEE dual carbon manufacturing credits and operating permits. |
| Provincial State-Owned Platform Framework Agreements | Nanjing and Suzhou municipal infrastructure bureaus mandate approved vendor lists embedding long-term supply relationships. |
| Hybrid Polycarboxylate Ether-Graft Architecture Development | Integrated slump-retention systems displace separate retarder additions for Guangdong continuous pours exceeding 12 hours. |
Research Approach
A standing panel of concrete technologists, provincial transportation department procurement directors, ready-mix plant operations managers, and petrochemical feedstock traders provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT GB standard filings, MEE environmental compliance disclosures, provincial construction quality supervision station batch testing records, and China Customs ethylene oxide import-export data. Bottom-up capacity modeling and top-down demand triangulation from 14th Five-Year Plan infrastructure project pipelines converged on segment-level outputs.
Scenario-bracketing framed analytical approach across the analysis window, with polycarboxylate ether adoption curves, naphthalene sulfonate conversion lag estimates, and ethylene oxide price elasticity as core sensitivity inputs. Segmentation dimensions modeled included molecular chemistry tier, end-use vertical, distribution channel structure, and provincial regulatory cluster. CAGRs derived from elasticity-adjusted volume projections and value-per-ton pricing trajectories tied to feedstock cost indices.
Sensitivities concentrate around ethylene oxide supply disruptions from Shandong petrochemical maintenance cycles, typhoon-season logistics interruptions, and MEE dual carbon threshold revisions that could accelerate bio-based feedstock mandates. Forecasts reflect documented assumptions on infrastructure project execution rates and provincial GB 8076 enforcement intensity. Quarterly review of MEE manufacturing credit allocation rates and provincial construction quality supervision station certification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Latex Caulk Market