
 Warm Mix Asphalt Market | 2026-2036
Warm Mix Asphalt Market Size, Share, and Industry Trends Forecast 2026-2036
Warm Mix Asphalt Market Analytics
Consolidation among state transportation departments and national highway authorities is repositioning procurement leverage toward fewer, larger contracts with stringent environmental riders. Martin Marietta Materials leverages its vertically integrated aggregate-to-paving network to secure multi-year department of transportation agreements. CRH Americas Materials, Inc. anchors its position through dense terminal networks across the southeastern United States. Colas competes on technical service depth, embedding engineers directly into client specification committees.
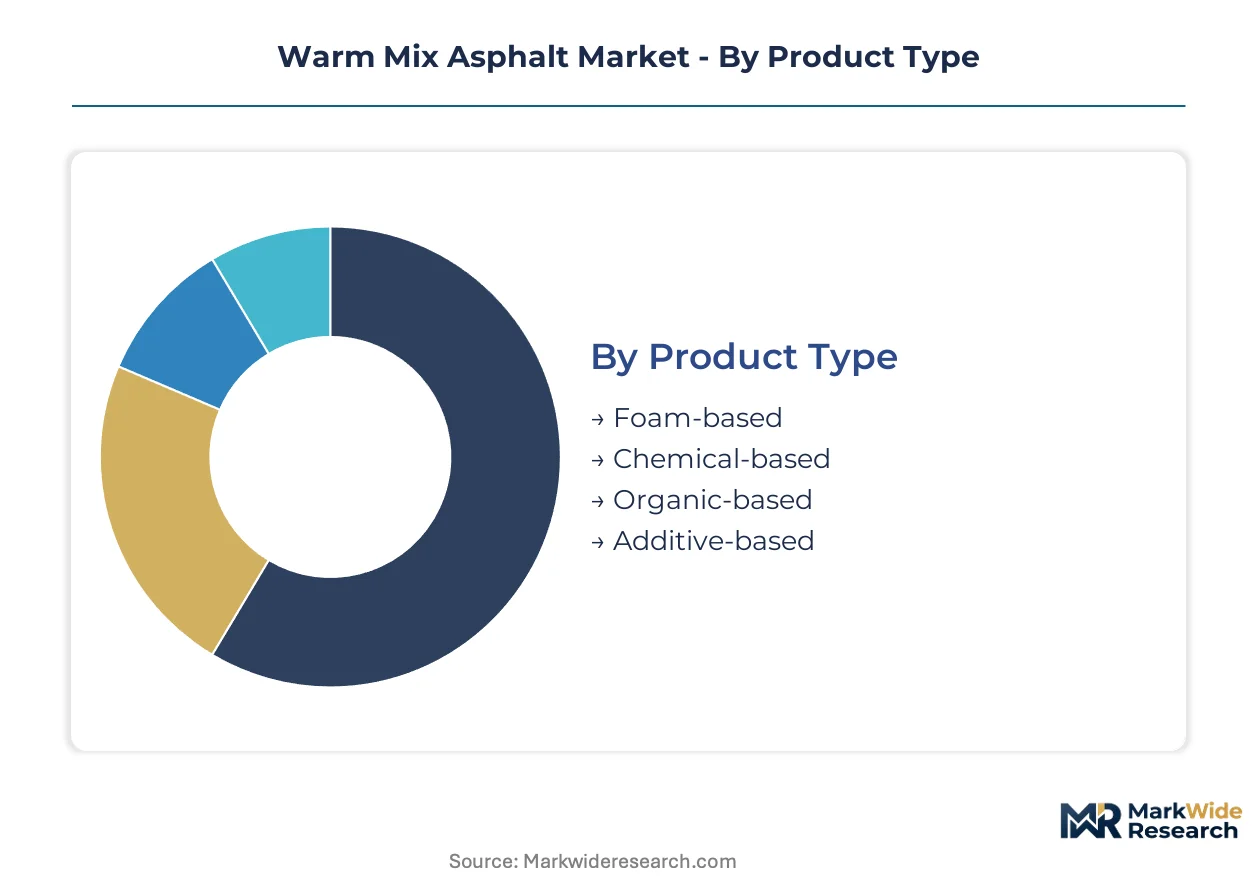
Warm mix asphalt denotes bituminous pavement material produced and placed at temperatures 20–40°C below conventional hot mix, achieved through foaming processes, chemical surfactants, or organic wax additives that reduce binder viscosity. The lower production temperature cuts fuel consumption by approximately one-third while suppressing volatile organic compound and carbon dioxide emissions at the plant stack. Foam-based formulations currently occupy the largest share of installed capacity due to minimal additive cost and equipment retrofit simplicity, though chemical-based systems are extending fastest in urban air-quality non-attainment zones where emissions budgets constrain project permitting. Additive-based segments dominate margin pools because proprietary surfactant packages command technical premiums and lock in recurring formulation supply.
The EPA enforces National Ambient Air Quality Standards that directly cap asphalt plant emissions, while the EU Green Deal and F-Gas Regulation tighten embodied carbon thresholds for publicly funded infrastructure. State-level departments of transportation in the US increasingly mandate warm mix compliance for federal-aid highway projects, effectively making specification adherence a condition of market access. Stakeholders must monitor how evolving lifecycle assessment protocols redefine competitive advantage away from first-cost bidding toward verified carbon intensity per lane-mile.
Market Dynamics
Federal and state transportation departments are consolidating procurement authority around lifecycle carbon accounting, forcing asphalt producers to retool plant configurations and additive sourcing strategies to meet emissions-tied contract eligibility.
Growth Catalysts
- EPA National Ambient Air Quality Standards:These emission caps mandate stack reductions at asphalt plants, compelling operators to adopt foaming and chemical additive systems that cut production temperatures by 20–40°C.
- Germany's federal highway program specifications:The country's transport ministry embeds warm mix compliance into road construction tenders, creating guaranteed demand volumes for compliant material suppliers.
- Foam-based formulation technology:Low-cost equipment retrofits and minimal additive requirements accelerate adoption among mid-sized paving contractors seeking regulatory compliance without capital-intensive plant rebuilds.
Market Restraints
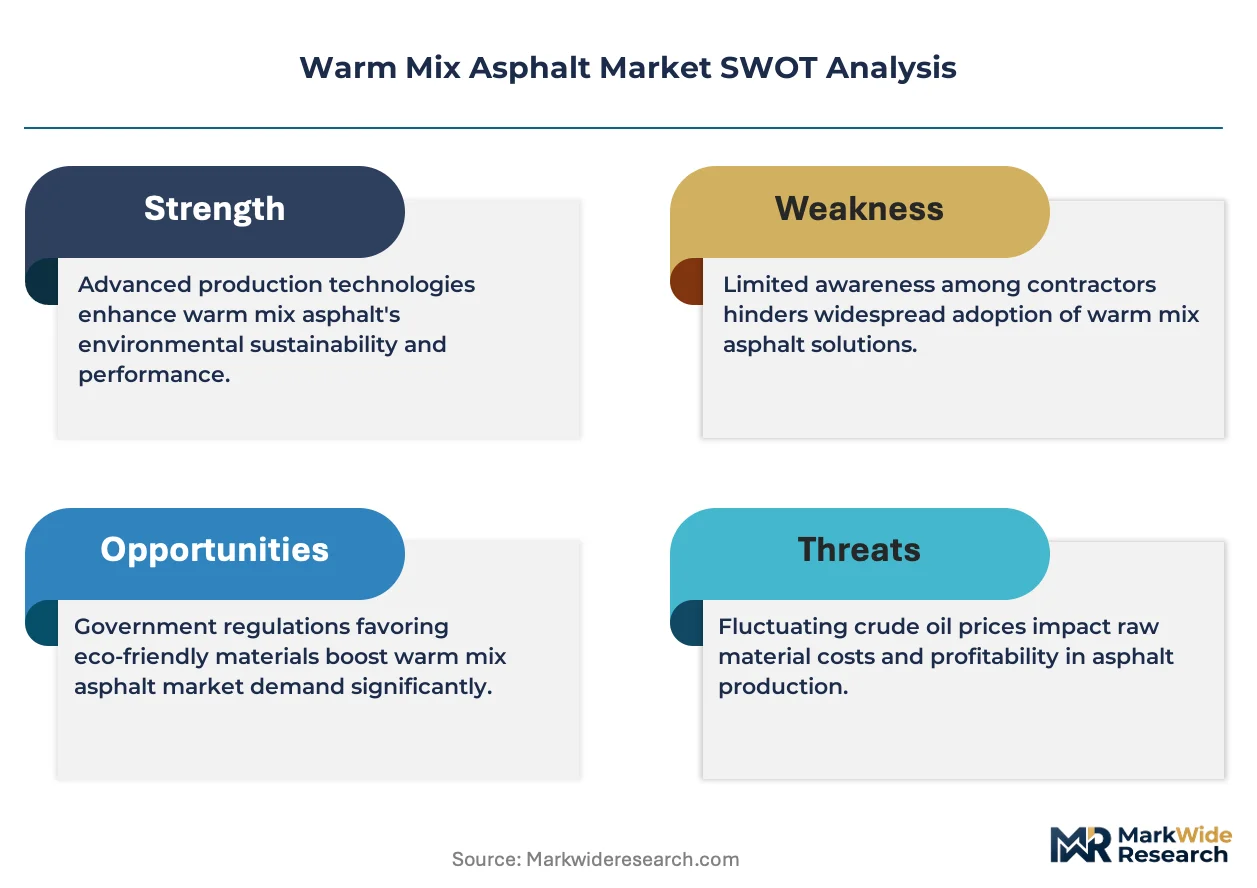
- Bitumen price volatility:Crude oil fluctuations directly compress margins on binder-intensive warm mix formulations, particularly for producers lacking long-term supply contracts with refiners.
- Performance validation gaps:Limited long-term rutting and moisture damage data for some chemical surfactant packages creates specification hesitation among risk-averse state DOT engineers.
- Hot mix asphalt substitution threat:Established paving crews and plant operators resist workflow changes required for lower-temperature material handling and compaction timing.
Strategic Opportunities
- India's National Highways Authority:Federal infrastructure spending targets create entry points for additive suppliers capable of technical training and localized formulation adaptation.
- Urban air-quality non-attainment zones:Metropolitan areas facing EPA attainment deadlines present concentrated demand for chemical-based systems with superior emissions profiles.
- Lifecycle assessment integration:Emerging carbon accounting protocols reward verified lane-mile carbon intensity, enabling premium positioning for producers with third-party certified supply chains.
Industry Challenges
- Materials engineering talent scarcity:Formulation chemists with simultaneous expertise in binder rheology and surfactant chemistry command premium compensation, constraining R&D expansion at mid-tier producers.
- Multi-jurisdictional certification complexity:State DOTs maintain non-harmonized warm mix approval protocols, forcing suppliers to duplicate testing and documentation across overlapping regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warm Mix Asphalt Market |
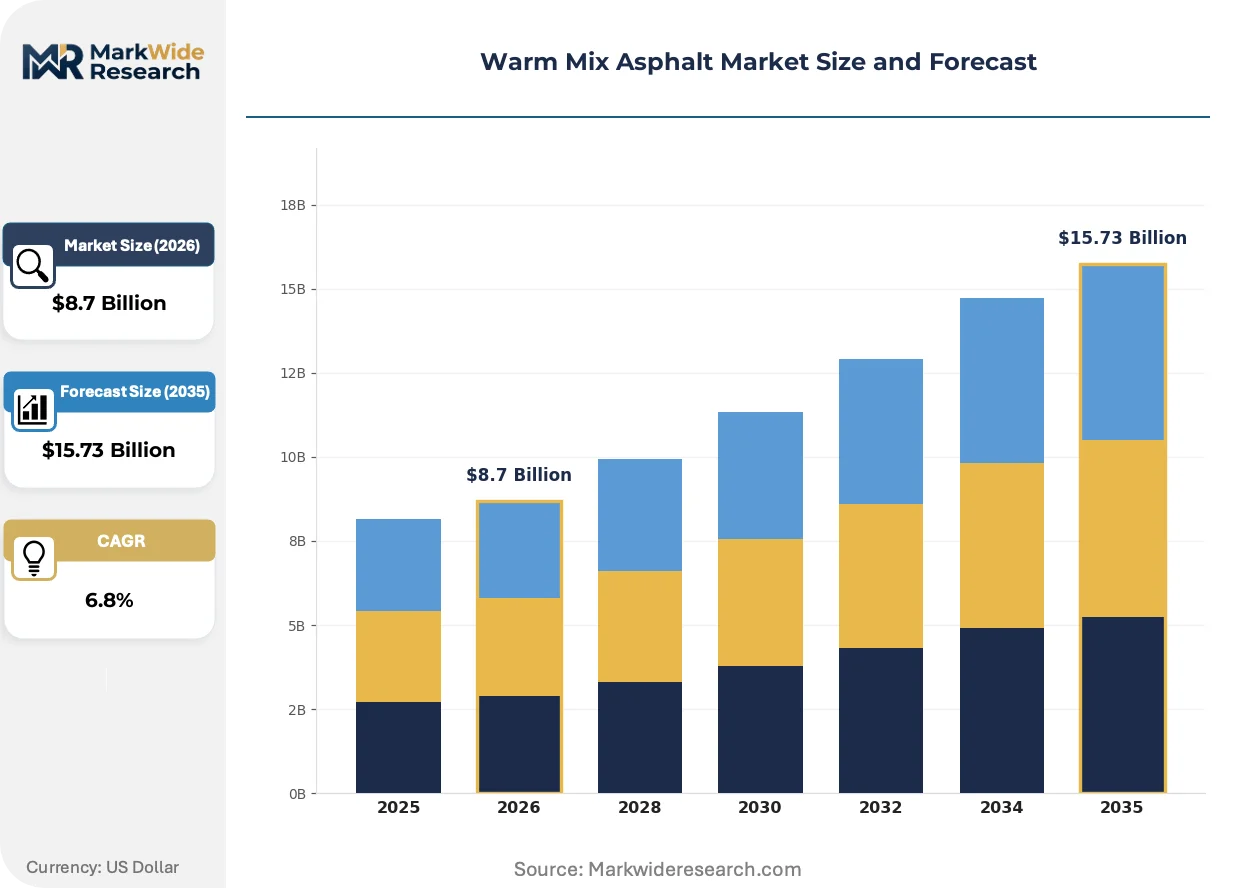
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam-based, Chemical-based, Organic-based, Additive-based Application: Road Construction, Airport Runways, Parking Lots, Recreational Areas End User: Public Sector, Private Contractors, Infrastructure Developers, Construction Companies Technology: Warm Mix Technologies, Conventional Technologies, Recycled Asphalt Technologies, Sustainable Technologies |
| Companies Covered | Martin Marietta Materials, Reeves Construction Co., PJ Keating, CRH Americas Materials, Inc., Aggregate Industries, Colas, Blue Diamond Asphalt, CEMEX, BAOLIRUS International Investment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warm Mix Asphalt Market Evolving Landscape
Active experimentation with bio-based binder modifiers and plant digitization is compressing the gap between laboratory formulation and field performance validation, reshaping how producers demonstrate specification compliance.
Zeolite-based organic wax additives are electrifying warm mix production by enabling sub-120°C placement temperatures without compromising binder adhesion properties. Municipal paving departments in Germany and the Netherlands are piloting these systems for urban resurfacing contracts with strict nighttime noise restrictions. The technology is electrifying competitive positioning by allowing smaller contractors to bid on emission-sensitive projects previously reserved for capital-intensive chemical formulation specialists.
The EU Green Deal's embodied carbon thresholds for publicly funded infrastructure now explicitly reference asphalt production temperatures in procurement scoring algorithms. Contractors bidding on Trans-European Transport Network projects must document verified fuel consumption reductions or face automatic technical disqualification. French and Spanish regional authorities have accelerated warm mix mandate timelines by 18–24 months ahead of baseline compliance deadlines.
State DOTs in the United States are unbundling material supply from placement services, creating direct procurement relationships with additive manufacturers rather than relying on contractor intermediaries. This disintermediation concentrates specification influence among a narrower set of technical buyers who prioritize documented emissions performance over historical supplier relationships. California and Texas transportation departments now require real-time plant telemetry disclosure as a contract condition, shifting competitive advantage toward digitally integrated supply chains.
Warm Mix Asphalt Market Segmentation
Warm mix asphalt producers face divergent technical and commercial requirements across product formulations, project types, and buyer categories. Segmentation reveals where margin pools concentrate and which upgrade cycles are accelerating plant retooling decisions.
Product Type:
Replacement cycles for plant equipment and additive injection systems vary sharply by formulation chemistry, with some technologies requiring complete rebuilds while others demand only peripheral retrofit.
- Foam-based:Water injection systems create binder expansion through controlled foaming, achieving 20–30°C temperature reduction with minimal additive cost. Demand concentrates among mid-sized US paving contractors seeking EPA compliance without capital-intensive plant modifications, though performance validation gaps persist in high-rutting corridors.
- Chemical-based:Proprietary surfactant packages reduce binder viscosity through molecular adhesion modification, enabling precise temperature control for urban air-quality non-attainment zones. Germany's federal highway program specifications drive procurement volume here, where emissions budgets constrain project permitting and technical premiums justify recurring formulation supply contracts.
- Organic-based:Paraffin wax and fatty acid amide additives lower viscosity through crystalline phase change mechanisms.
- Additive-based:Zeolite and synthetic polymer packages command technical premiums through locked-in supply arrangements with certified producers.
Foam-based formulations sit at the top of the volume ranking, with chemical-based systems climbing the fastest.
Application:
Project scale and specification stringency create tiered pricing structures across surface types, with federal-aid highway work commanding premium compliance documentation.
- Road Construction:Federal and state transportation departments mandate warm mix compliance for highway resurfacing and new alignment projects, making specification adherence a condition of contract eligibility. India’s National Highways Authority and US state DOTs drive concentrated procurement volumes where lifecycle carbon accounting now influences award decisions.
- Airport Runways:Strict Federal Aviation Administration friction and compaction standards limit warm mix penetration, though European hubs are piloting zeolite-based systems for nighttime noise-restricted maintenance windows.
- Parking Lots:Municipal procurement favors low-temperature placement for urban resurfacing with traffic disruption constraints.
- Recreational Areas:Trail and pathway applications prioritize aesthetic finish and odor suppression over structural performance metrics.
Road construction commands the dominant share of installed capacity, while airport runway applications are gaining share fastest as certification protocols mature.
End User:
Buyer sophistication and specification influence vary dramatically across public and private procurement channels, reshaping how additive suppliers structure technical service relationships.
- Public Sector:State transportation departments and national highway authorities consolidate procurement leverage around multi-year framework agreements with stringent environmental riders. California and Texas DOTs now require real-time plant telemetry disclosure as a contract condition, shifting competitive advantage toward digitally integrated supply chains.
- Private Contractors:Mid-sized paving firms prioritize equipment retrofit simplicity and minimal workflow disruption over technical performance optimization.
- Infrastructure Developers:Build-operate-transfer concessionaires incorporate lifecycle cost models that favor verified carbon intensity reductions.
- Construction Companies:General contractors face disintermediation pressure as state DOTs unbundle material supply from placement services.
The public sector dominates contract value, with infrastructure developers expanding their share fastest through concession-based procurement.
Technology:
Plant digitization and automation investments are compressing validation timelines and reshaping competitive positioning across technology generations.
- Warm Mix Technologies:Foaming, chemical, and organic additive systems collectively define the core market, with equipment retrofits and formulation supply creating recurring revenue streams for technology licensors. EU Green Deal embodied carbon thresholds now explicitly reference production temperatures in procurement scoring algorithms.
- Conventional Technologies:Hot mix asphalt retains installed base dominance among established paving crews resistant to workflow changes for lower-temperature material handling and compaction timing.
- Recycled Asphalt Technologies:Reclaimed asphalt pavement integration with warm mix binders addresses circular economy mandates in French and Spanish regional tenders.
- Sustainable Technologies:Bio-based binder modifiers and electrified plant configurations target net-zero construction pathways.
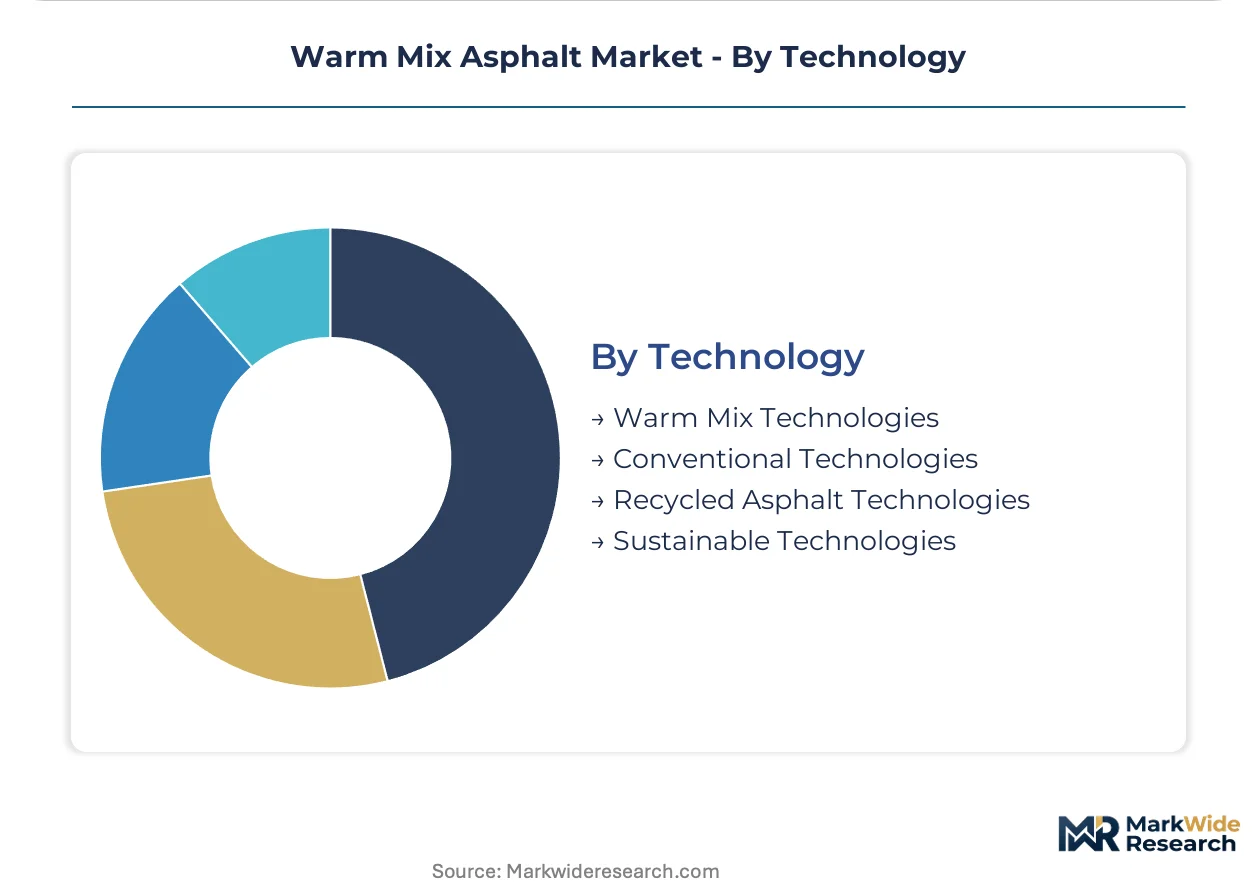
Warm mix technologies hold the volume lead, with sustainable technologies posting the steepest expansion trajectory as carbon accounting protocols harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's federal highway program generates procurement volumes that exceed India's National Highways Authority by a narrower margin than raw infrastructure spending figures suggest, reflecting the EU Green Deal's stringent embodied carbon thresholds.
United States
State transportation departments in California and Texas now mandate real-time plant telemetry disclosure as a contract condition for federal-aid highway projects. The EPA enforces National Ambient Air Quality Standards that cap asphalt plant emissions, compelling operators to adopt foaming and chemical additive systems. The southeastern United States hosts dense terminal networks where mid-sized paving contractors seek EPA compliance without capital-intensive plant modifications.
Germany
The federal transport ministry embeds warm mix compliance into road construction tenders, creating guaranteed demand volumes for compliant material suppliers. EU Green Deal and F-Gas Regulation thresholds tighten allowable production temperatures for asphalt binders, explicitly referencing production temperatures in procurement scoring algorithms. Municipal paving departments in the Netherlands and Germany pilot zeolite-based organic wax additives for urban resurfacing contracts with strict nighttime noise restrictions.
India
The National Highways Authority drives concentrated procurement volumes where federal infrastructure spending targets create entry points for additive suppliers capable of technical training and localized formulation adaptation. The country's national highway regulator mandates lifecycle carbon accounting for publicly funded road projects. Western and southern states concentrate paving contractor activity where mid-sized firms prioritize equipment retrofit simplicity.
France
Regional authorities have accelerated warm mix mandate timelines by 18–24 months ahead of baseline EU compliance deadlines. The EU Green Deal's embodied carbon thresholds for publicly funded infrastructure require contractors bidding on Trans-European Transport Network projects to document verified fuel consumption reductions. French and Spanish regional tenders now integrate reclaimed asphalt pavement with warm mix binders to address circular economy mandates.
United Kingdom
Department for Transport specifications increasingly reference warm mix compliance for strategic road network maintenance contracts. The country's national environmental regulator enforces emissions budgets that constrain project permitting in urban air-quality non-attainment zones. Greater London and the Midlands concentrate paving contractor networks where specification adherence determines contract eligibility for publicly funded infrastructure.
Warm Mix Asphalt Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels reshaped by state DOT consolidation. The market structure tilts toward vertically integrated aggregate-to-paving networks that secure multi-year framework agreements with stringent environmental riders. Three archetypes dominate: capital-intensive chemical formulation specialists, equipment-agnostic foaming system providers, and terminal-dense regional materials distributors. Competitive moves concentrate on strategic partnerships with additive licensors and geographic expansion through brownfield plant retrofits.
Among North American materials conglomerates, Martin Marietta Materials and CRH Americas Materials, Inc. occupy positions exemplifying terminal network density and vertically integrated supply chain control. Colas represents the technical service depth archetype, embedding engineering resources directly into client specification committees. These three entities anchor competitive positioning across public sector procurement channels where multi-year department of transportation agreements concentrate contract value.
| Leading Market Players |
|---|
| Martin Marietta Materials |
| Reeves Construction Co. |
| PJ Keating |
| CRH Americas Materials, Inc. |
| Aggregate Industries |
| Colas |
| Blue Diamond Asphalt |
| CEMEX |
| BAOLIRUS International Investment Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Bitumen cost volatility cascades through warm mix asphalt pricing tiers, with crude oil-linked binder expenses compressing margins for producers lacking long-term refinery contracts while chemical additive specialists capture technical premiums in EU Green Deal-compliant procurement channels.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for foam-based formulations, where water injection systems enable mid-sized contractors to bid EPA-compliant projects without capital-intensive plant rebuilds. Three-tier pricing structure across premium chemical surfactants, standard foaming systems, and economy-grade organic wax additives reflects certification grade and emissions documentation depth. Pricing pressure stems from bitumen cost volatility tied to crude oil fluctuations, squeezing margin pools for binder-intensive formulations. State DOT procurement officers exhibit lowest price sensitivity, prioritizing verified lifecycle carbon intensity over first-cost bidding, while private paving contractors face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with specialized surfactant chemical suppliers concentrated in Germany and the Netherlands, where proprietary formulation packages lock in recurring supply arrangements with certified warm mix producers. Raw material dependencies span bitumen from regional refineries, zeolite additives from controlled mineral deposits, and synthetic polymer packages from petrochemical hubs. Supply chain risk centers on multi-jurisdictional certification complexity, as state DOTs maintain non-harmonized approval protocols forcing duplicate testing across overlapping regional markets. Distribution runs through vertically integrated aggregate-to-paving networks and dense terminal systems anchored by multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warm mix asphalt functions as a regulatory compounder, with EU Green Deal embodied carbon thresholds and EPA National Ambient Air Quality Standards creating structural demand acceleration for lower-temperature paving materials.
For Market Incumbents: Acquire brownfield plant assets in urban air-quality non-attainment zones to preempt competitor entry where emissions budgets constrain project permitting. Secure backward integration into surfactant chemical supply or captive zeolite additive production to defend margin pools against bitumen price volatility and proprietary formulation lock-in by rivals. For New Entrants and Emerging Players: Begin with technical training partnerships in India, where the National Highways Authority's federal infrastructure spending creates white-space entry for additive suppliers capable of localized formulation adaptation. Target mid-sized paving contractors in the southeastern United States seeking EPA compliance through minimal-equipment-retrofit foaming systems, using equipment-agnostic technology licensing as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where state DOTs unbundle material supply from placement services, concentrating procurement influence among digitally integrated additive manufacturers with real-time plant telemetry disclosure capabilities. Target acquisition archetypes include chemical formulation specialists with locked-in recurring supply contracts and terminal-dense regional materials distributors. The signal to watch is accelerated warm mix mandate timelines in French and Spanish regional authorities ahead of baseline EU compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Plant Retrofit | Enables rapid EPA compliance without greenfield capital deployment in non-attainment zones. |
| Backward Integration into Additives | Captures surfactant margin pools and secures supply continuity against chemical price volatility. |
| Real-Time Telemetry Integration | Satisfies California and Texas DOT contract conditions for digitally integrated supply chains. |
| Localized Formulation Partnership | Unlocks India's National Highways Authority procurement through technical training capabilities. |
| Lifecycle Certification Investment | Positions for EU Green Deal procurement scoring algorithms favoring verified carbon intensity. |
Research Methodology
Multiple input streams — primary interviews with asphalt plant managers, state DOT specification engineers, and chemical additive procurement leads; secondary validation through EPA emissions filings, EU tender databases, and state transportation department contract disclosures; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation to construct segment-level volume and value estimates.
Data-stream reconciliation applied analytical frameworks across the projection horizon, modeling warm mix asphalt demand by formulation chemistry, application type, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of state DOT mandate adoption curves, EU Green Deal implementation timelines, and India National Highways Authority spending patterns, cross-referenced against fuel consumption reduction verification protocols and plant retrofit cycle assumptions.
Caveats apply where bitumen price volatility, unresolved performance validation gaps for novel chemical surfactants, or accelerated hot mix substitution in cost-sensitive corridors could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Rebars Market