
 Global Forensic Engineering Services Market | 2026-2036
Global Forensic Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Forensic Engineering Services Market Analysis
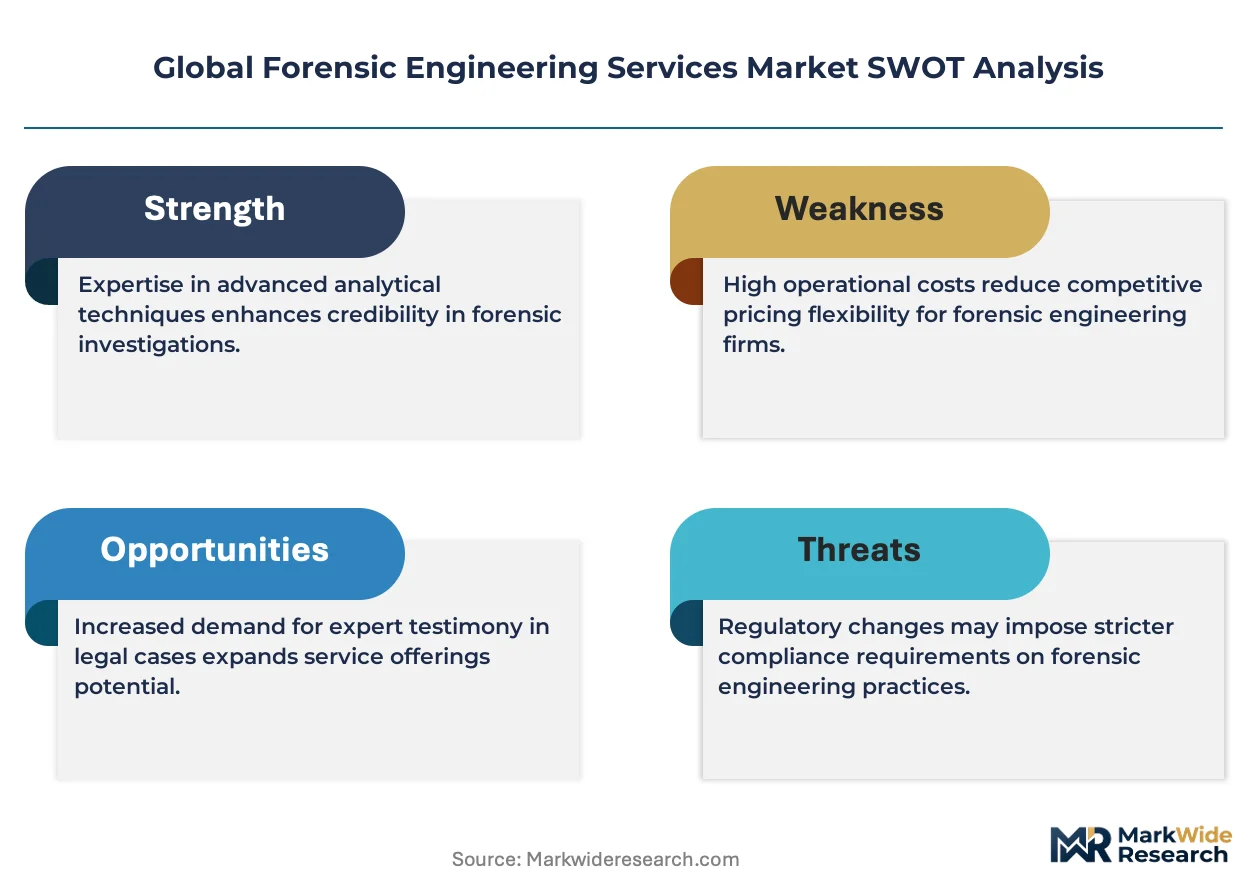
A shortage of licensed structural engineers with dual expertise in litigation support and advanced simulation tools is collapsing project throughput at mid-sized firms. Exponent, Inc. leverages its multidisciplinary staff model to sustain premium pricing on complex failure investigations. Envista Forensics competes through rapid deployment capabilities across catastrophic event zones. Thornton Tomasetti, Inc. anchors its forensic practice on deep reserves of computational modeling talent built through decades of building design work.
Forensic engineering services encompass the scientific investigation of structural failures, material defects, and accident causation using load testing, metallurgical examination, and finite element analysis to determine liability and prevent recurrence. Practitioners apply ASTM standards for concrete core sampling and ISO guidelines for evidence chain of custody to produce court-admissible findings for insurance disputes and regulatory enforcement. Structural analysis commands the largest revenue share due to persistent aging infrastructure exposure across developed economies, while accident reconstruction grows fastest as automotive electrification introduces novel battery fire investigation protocols. Failure analysis retains concentrated margin pools in aerospace and energy sectors where metallurgical expertise carries scarcity premiums.
OSHA workplace safety directives and FAA accident investigation protocols in the United States, alongside ECHA substance restriction frameworks under REACH in Europe, mandate documented engineering review before liability determination or product recall authorization. These frameworks elevate demand for third-party forensic verification that withstands adversarial legal scrutiny. Stakeholders must monitor how evolving AI evidence standards and cross-border data privacy requirements reshape the admissibility of digitally derived engineering conclusions.
Market Dynamics
Insurance carriers now mandate forensic engineering assessments before large liability settlements, tightening loss-verification protocols across North America and Europe. Digital twin technology and drone-based structural scanning compress investigation timelines from weeks to days.
Growth Catalysts
- FAA accident investigation protocols:Mandated engineering review before liability determination elevates demand for third-party forensic verification in aviation incidents across the United States.
- Aging infrastructure exposure:Persistent structural deterioration in developed economies sustains demand for failure analysis and expert testimony services in civil engineering disputes.
- Automotive electrification:Novel battery fire investigation protocols create specialized demand for forensic engineers with thermal runaway expertise.
Market Restraints
- Licensed structural engineer shortage:Dual expertise in litigation support and advanced simulation tools remains scarce, collapsing project throughput at mid-sized firms.
- Computational modeling talent concentration:Deep reserves of finite element analysis specialists cluster at established building design firms, limiting independent practice formation.
- Evidence chain of custody complexity:ISO guidelines for forensic documentation create procedural friction that extends engagement timelines and elevates compliance costs.
Strategic Opportunities
- India infrastructure buildout:Rapid urbanization and construction volume expansion creates underpenetrated demand for failure investigation services in commercial and residential sectors.
- EU AI Act evidence standards:Evolving admissibility frameworks for digitally derived engineering conclusions create first-mover positioning for firms with validated algorithmic methodologies.
- Drone-based structural scanning:Aerial LiDAR and photogrammetry convergence enables rapid deployment capabilities across catastrophic event zones previously inaccessible to ground crews.
Industry Challenges
- Simulation software certification timelines:Court acceptance of finite element analysis outputs requires extensive validation protocols that delay service commercialization.
- Cross-border data privacy requirements:GDPR and emerging national frameworks restrict transnational evidence sharing, complicating multi-jurisdictional failure investigations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Forensic Engineering Services Market |
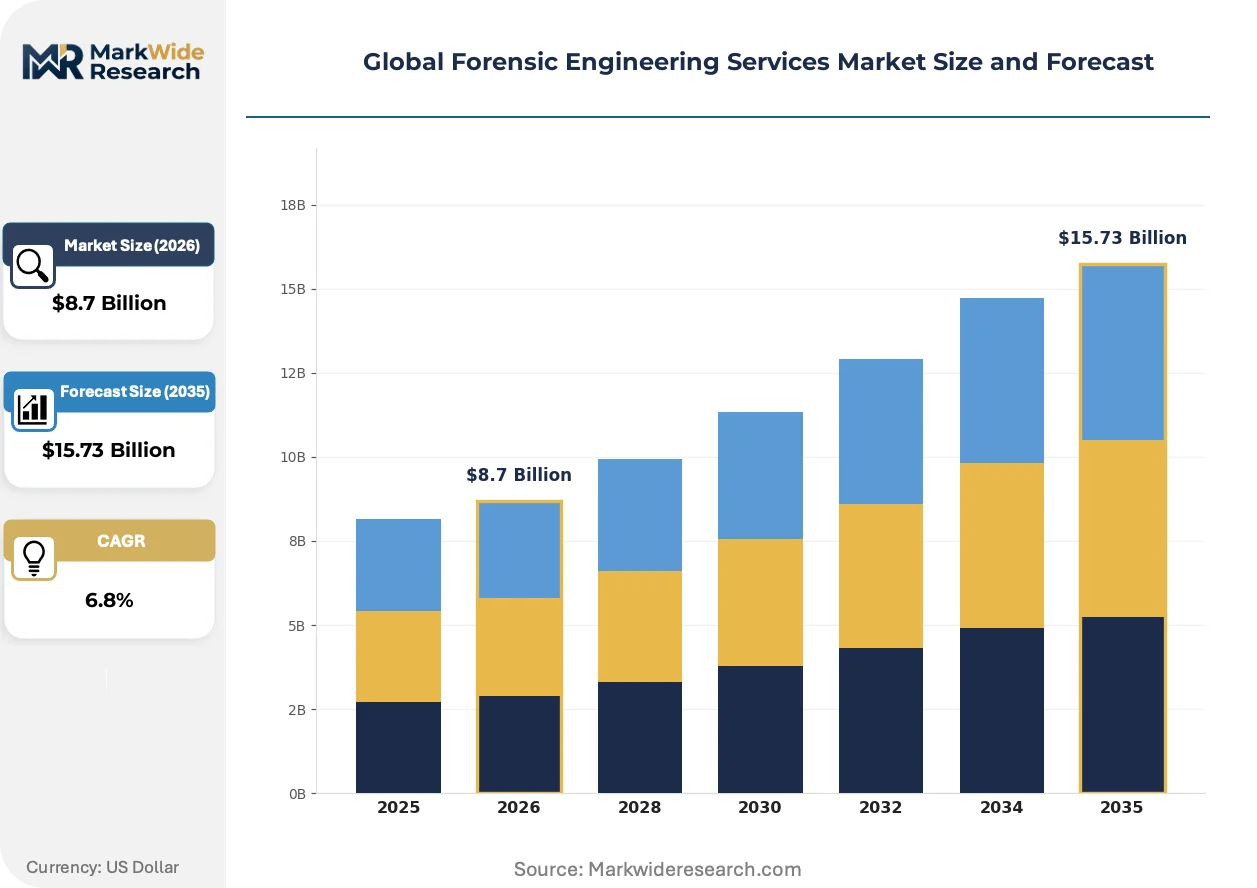
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accident Reconstruction, Structural Analysis, Failure Analysis, Expert Testimony Industry Vertical: Construction, Automotive, Aerospace, Insurance End User: Corporations, Legal Firms, Government Agencies, Insurance Companies Technology: 3D Modeling, Simulation, Imaging, Data Analysis |
| Companies Covered | Exponent, Inc., Envista Forensics, Intertek, Jensen Hughes, Rimkus Consulting Group, Inc., Thornton Tomasetti, Inc., Wiss, Janney, Elstner Associates, Inc., O'Donnell Consulting Engineers, Jesse Garant Metrology Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Forensic Engineering Services Market Emerging Trajectories
Digital evidence methodologies are actively reshaping how forensic engineers establish causation and liability. Three developments dominate current service evolution.
Drone-based photogrammetry is decomposing traditional site inspection workflows. Insurance carriers and litigation teams now deploy aerial scanning for structural damage assessment within hours of catastrophic events. This compression from weeks to days is decomposing the competitive advantage of established firms with legacy ground-based inspection protocols.
REACH substance restriction frameworks under ECHA mandate documented material analysis before product recall authorization in Europe. Industrial consequence includes elevated metallurgical examination demand for imported components. Aerospace and energy sectors face the steepest compliance burden, driving third-party verification outsourcing.
Buyer procurement patterns favor rapid-deployment forensic teams over traditional retainer relationships. Catastrophic event response contracts now specify 24-hour mobilization clauses. This shift is most visible in United States coastal regions exposed to hurricane and flood damage concentration.
Global Forensic Engineering Services Market Segmentation
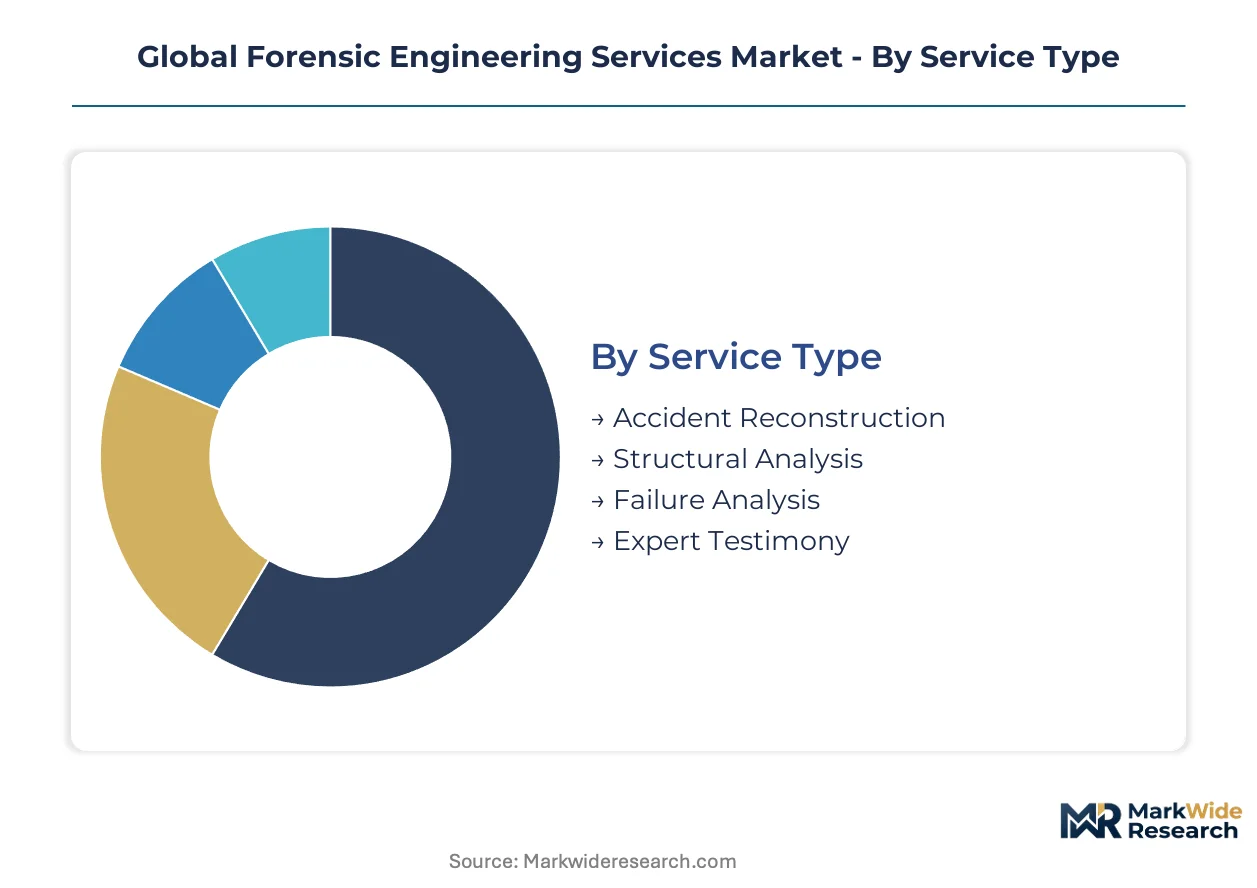
Forensic engineering services fragment across service specializations, industry applications, and technological methodologies that each carry distinct liability exposure profiles and pricing power. Understanding these segment boundaries reveals where substitute technologies threaten incumbent service models and where specialized expertise commands sustained premiums.
Service Type:
Drone-based inspection platforms and AI-assisted damage assessment tools exert substitution pressure most acutely on standardized visual investigation services, while complex analytical disciplines retain defensive moats through regulatory certification requirements.
- Structural Analysis:Load testing, stress modeling, and deterioration assessment of buildings, bridges, and industrial facilities using finite element analysis and material sampling protocols. Demand concentrates in the United States where aging infrastructure exposure and litigation volume create sustained need for court-admissible failure documentation. ASTM standards for concrete core sampling and masonry evaluation elevate compliance barriers that protect established practitioners from automation displacement.
- Accident Reconstruction:Vehicle dynamics modeling, collision sequence mapping, and injury causation analysis using physical evidence and telemetry data interpretation. Automotive electrification in Germany, Japan, and the United States generates specialized thermal runaway investigation demand that outpaces generalist capability development. NHTSA protocols and FAA investigation frameworks mandate engineering review before liability determination, insulating this segment from pure software substitution.
- Failure Analysis:Metallurgical examination, fracture surface interpretation, and root cause determination for component defects across industrial equipment.
- Expert Testimony:Litigation support services delivering sworn engineering opinions for insurance disputes and regulatory enforcement proceedings.
Structural Analysis anchors the volume base while Accident Reconstruction gains share at the steepest rate.
Industry Vertical:
Cost tier stratification separates capital-intensive sectors with long investigation cycles from high-velocity industries where rapid deployment commands premium pricing.
- Construction:Commercial, residential, and civil infrastructure failure investigations spanning foundation defects, structural collapse, and code compliance disputes. United States urban centers with pre-1980 building stock generate concentrated demand for seismic and deterioration assessments. OSHA workplace safety directives mandate documented engineering review before liability determination, embedding third-party verification into standard claims workflows.
- Insurance:Loss verification, subrogation support, and reserve estimation services delivered under carrier-directed investigation protocols. Catastrophic event response contracts in United States coastal regions now specify 24-hour mobilization clauses that favor rapid-deployment specialists over traditional retainer relationships. Carrier consolidation across North America and Europe is concentrating procurement volume with preferred forensic engineering panels.
- Automotive:Crashworthiness assessment, defect investigation, and autonomous system failure analysis for OEMs and tier suppliers.
- Aerospace:Component failure investigation, maintenance error analysis, and airworthiness directive support for manufacturers and operators.
Construction dominates absolute revenue contribution while Insurance demonstrates the most aggressive procurement consolidation trajectory.
End User:
Customer type determines engagement structure, with retained relationships yielding predictable throughput and event-driven contracts capturing scarcity premiums during demand spikes.
- Insurance Companies:Carrier-directed investigations for liability determination, subrogation recovery, and settlement validation across property and casualty lines. Mandated forensic assessment protocols before large liability settlements in the United States and Germany tighten verification standards and extend engagement scopes. Digital twin technology adoption compresses investigation timelines from weeks to days, reshaping vendor selection criteria toward technology-enabled firms.
- Legal Firms:Plaintiff and defense counsel engagement for expert testimony, discovery support, and trial preparation in civil litigation. Adversarial legal scrutiny in United States federal and state courts demands rigorous chain of custody documentation that elevates compliance costs and extends preparation timelines.
- Corporations:Internal investigation, product recall support, and regulatory response services for manufacturers and facility operators.
- Government Agencies:Regulatory enforcement support, accident investigation, and infrastructure safety assessment for federal and state authorities.
Insurance Companies anchor the volume base while Legal Firms expand most quickly as litigation finance growth extends plaintiff-side engineering budgets.
Technology:
Supply concentration among specialized software vendors and equipment manufacturers shapes competitive differentiation and margin structure across service delivery models.
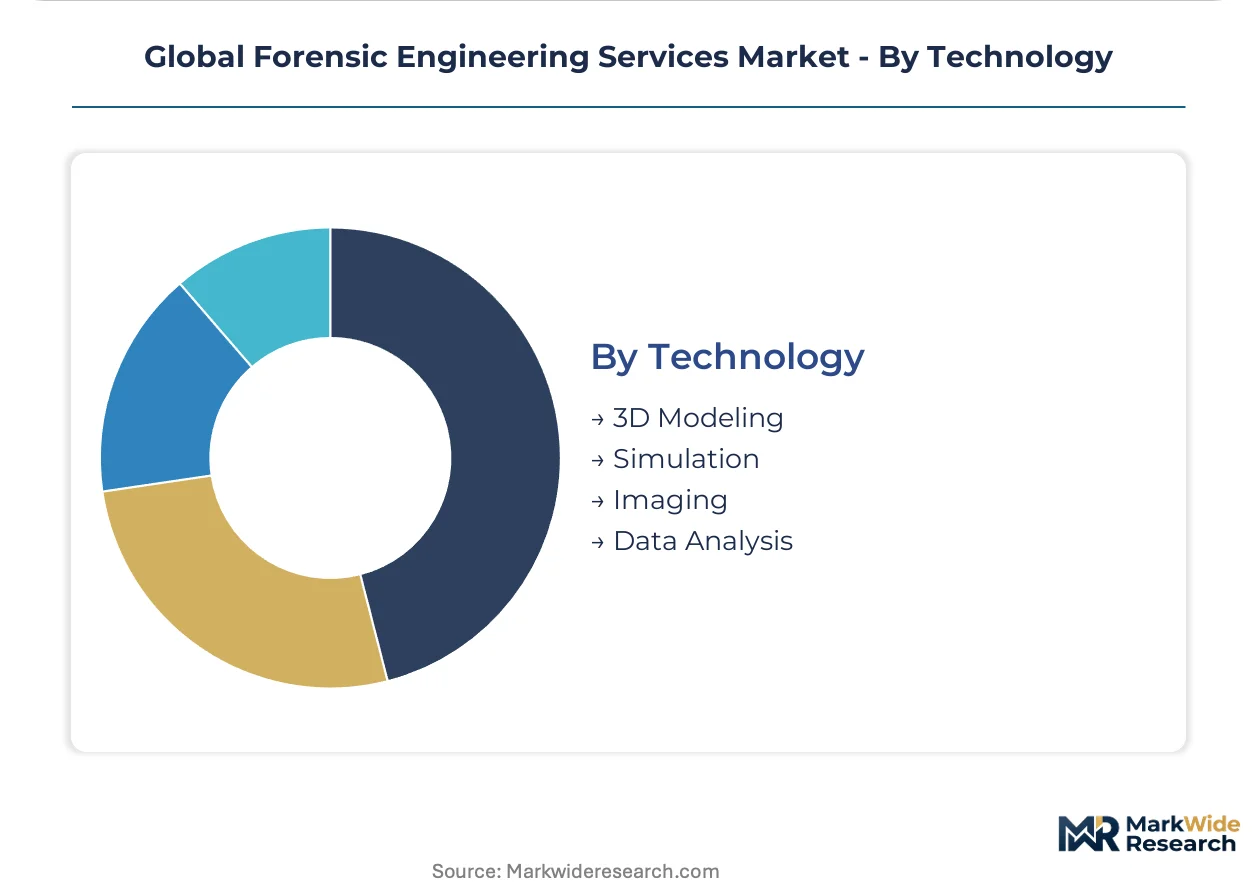
- Simulation:Finite element analysis, computational fluid dynamics, and multi-physics modeling for stress, thermal, and dynamic load prediction. Deep reserves of modeling talent cluster at established building design firms in the United States and United Kingdom, limiting independent practice formation. Court acceptance of simulation outputs requires extensive validation protocols that delay service commercialization and protect incumbent specialists.
- 3D Modeling:Digital reconstruction, parametric modeling, and visualization for evidence presentation and failure sequence demonstration.
- Imaging:Photogrammetry, thermography, and non-destructive testing for surface and subsurface defect detection.
- Data Analysis:Telemetry interpretation, statistical pattern recognition, and predictive modeling for trend identification and anomaly detection.
Simulation commands the highest margin tier while Imaging expands most quickly through drone-based deployment convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forensic engineering consumption patterns diverge sharply by geography: the United States prioritizes litigation-driven expert testimony, Germany emphasizes industrial failure analysis for manufacturing quality assurance, and India concentrates on construction-phase risk mitigation amid rapid urban buildout.
United States
Pre-1980 building stock deterioration and hurricane-exposed coastal infrastructure sustain demand for structural failure documentation. OSHA workplace safety directives and FAA accident investigation protocols mandate third-party engineering review before liability determination. Catastrophic event response contracts in Florida and Gulf Coast states specify 24-hour mobilization clauses that favor rapid-deployment specialists.
Germany
Automotive electrification and industrial machinery density generate specialized thermal runaway and metallurgical examination demand. ECHA substance restriction frameworks under REACH mandate documented material analysis before product recall authorization. Stuttgart and Munich industrial clusters concentrate finite element analysis talent serving OEM supplier networks.
United Kingdom
Insurance carrier consolidation and litigation finance growth extend plaintiff-side engineering budgets for complex disputes. GDPR cross-border data privacy requirements restrict transnational evidence sharing, complicating multi-jurisdictional investigations. London and Southeast England host concentrated panels serving Lloyd's syndicate verification protocols.
India
Rapid urbanization and construction volume expansion create underpenetrated demand for failure investigation in commercial and residential sectors. BIS building code enforcement and CEA electrical safety directives elevate compliance documentation requirements. Maharashtra and Karnataka urban corridors exhibit concentrated demand from high-rise structural risk assessments.
Japan
Seismic resilience verification and aging civil infrastructure sustain demand for structural analysis and deterioration assessment. METI industrial safety guidelines and JIS standards for material testing embed third-party verification into manufacturing quality workflows. Kanto and Kansai metropolitan areas concentrate specialist firms serving dense industrial facility networks.
Global Forensic Engineering Services Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multidisciplinary staff models sustaining premium pricing on complex investigations. The vendor base organizes around three strategic archetypes: rapid-deployment catastrophic response specialists, computational modeling-heavy building design affiliates, and litigation-focused expert testimony practices. Competitive dynamics center on M&A consolidation of regional specialists and technology licensing partnerships for drone-based inspection platforms.
Within the integrated leader tier, Exponent, Inc. and Thornton Tomasetti, Inc. exemplify divergent capability accumulation strategies. Exponent occupies a position emphasizing multidisciplinary staff breadth across scientific disciplines, while Thornton Tomasetti sits within the computational modeling specialist cluster leveraging decades of building design talent reserves. Envista Forensics represents the rapid-deployment archetype, anchoring competitive positioning on catastrophic event zone mobilization speed.
| Leading Market Players |
|---|
| Exponent, Inc. |
| Envista Forensics |
| Intertek |
| Jensen Hughes |
| Rimkus Consulting Group, Inc. |
| Thornton Tomasetti, Inc. |
| Wiss, Janney, Elstner Associates, Inc. |
| O'Donnell Consulting Engineers |
| Jesse Garant Metrology Center |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at specialized finite element analysis software vendors and drone equipment manufacturers concentrates pricing power among a handful of suppliers serving forensic engineering practices in the United States, Germany, and the United Kingdom. This scale concentration elevates fixed cost absorption thresholds for mid-sized firms while compressing margin flexibility on standardized inspection services.
Pricing Analysis
Project-based contracting dominates engagement structures, with catastrophic event response contracts commanding 40-60 percent premiums over standard retainer rates due to 24-hour mobilization clauses. Price differentiation separates rapid-deployment specialists with validated drone platforms from generalist practitioners relying on ground-based protocols. Cost compression in standardized visual inspection services is intensifying because AI-assisted damage assessment tools displace manual documentation. Insurance carriers demonstrate the highest price sensitivity, while aerospace OEMs accept premium pricing for metallurgical expertise carrying FAA investigation credentials.
Supply Chain Analysis
Strategic stockpiling of LiDAR sensors and thermal imaging equipment characterizes leading forensic practices preparing for hurricane season concentration in Florida and Gulf Coast states. Hardware sourcing concentrates in the United States, Germany, and Japan for precision measurement instruments. Computational modeling talent draws from university pipelines and building design firm alumni networks. Single-source vulnerability sits with specialized finite element analysis software vendors whose validation protocols require 18-24 month court acceptance timelines. Distribution runs through direct vendor relationships with equipment manufacturers and software licensors rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of engineers credentialed for both litigation support and advanced simulation tools has transformed talent acquisition into the primary constraint on service expansion, favoring firms with established training pipelines over pure-play competitors.
For Market Incumbents: Fortify talent retention through captive certification programs and exclusive simulation software partnerships that lock in finite element analysis specialists. Deepen backward integration into drone-based inspection platform development to defend margin position against rapid-deployment specialists. Prioritize M&A of regional metallurgical laboratories to secure scarce fracture surface interpretation expertise before competitor consolidation. For New Entrants and Emerging Players: Fast-track certification through ASTM concrete core sampling and ISO evidence chain of custody protocols offers the most penetrable entry vector for litigation support services in India and Southeast Asia. Target underpenetrated commercial construction failure investigation in Maharashtra and Karnataka urban corridors where BIS code enforcement is elevating compliance documentation requirements. Lead with 48-hour mobilization guarantees and fixed-fee structures to differentiate against incumbent hourly billing models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors computational modeling-heavy affiliates with validated algorithmic methodologies ahead of EU AI Act evidence standard implementation. Long-term viability hinges on court acceptance protocols for digitally derived engineering conclusions rather than pure headcount scale. Acquisition candidates should demonstrate established FAA or NHTSA investigation credentials and recurring carrier panel relationships. Watch for inflection when insurance procurement consolidation reaches critical mass in North American coastal regions.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Modeling Talent Acquisition | Secures scarce finite element analysis specialists clustered at established building design firms in the United States and United Kingdom. |
| Drone-Based Inspection Platform Integration | Compresses structural damage assessment timelines from weeks to days for hurricane-exposed coastal infrastructure. |
| Metallurgical Laboratory Backward Integration | Captures margin pools in aerospace and energy sectors where fracture surface interpretation carries scarcity premiums. |
| EU AI Act Evidence Standard Validation | Positions first-mover advantage for algorithmic methodologies in digitally derived engineering conclusions. |
| Catastrophic Event Response Contract Expansion | Captures 24-hour mobilization premiums in Florida and Gulf Coast states with concentrated hurricane exposure. |
Methodological Framework
Initial hypotheses were tested against primary input from forensic engineering principals, insurance carrier claims directors, litigation support coordinators, and regulatory affairs specialists at FAA and OSHA, and refined through secondary validation against ASTM standards documentation, ISO guideline repositories, SEC 10-K disclosures from publicly traded engineering firms, and ECHA REACH substance restriction frameworks. Bottom-up service line estimates were triangulated against top-down macroeconomic infrastructure spending indicators.
Variance decomposition across the projection horizon isolates growth contributions from structural analysis, accident reconstruction, failure analysis, and expert testimony segments, with additional dimensional modeling across technology deployment modes including simulation, 3D modeling, imaging, and data analysis. CAGRs were derived from fitted trend extrapolation validated against historical litigation volume and infrastructure age distributions. Industry-specific inputs include FAA accident investigation protocol changes, automotive electrification thermal runaway incident frequencies, and insurance carrier panel consolidation trajectories.
Underlying assumptions cover sustained infrastructure deterioration rates, stable regulatory enforcement intensity, and continued carrier mandate expansion for forensic verification, with deviation risk concentrated in AI evidence standard adoption timelines and cross-border data privacy restriction evolution. Revision becomes warranted when litigation finance growth crosses thresholds that fundamentally alter plaintiff-side engineering budget availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
United States (US) MEP Services Market
Engineering Services
Seismic Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
United States Engineering Services Market
Engineering Services
Architectural Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
MEP Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market