
 North America Cross-Laminated Timber Market | 2026-2036
North America Cross-Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cross-Laminated Timber Market Intelligence
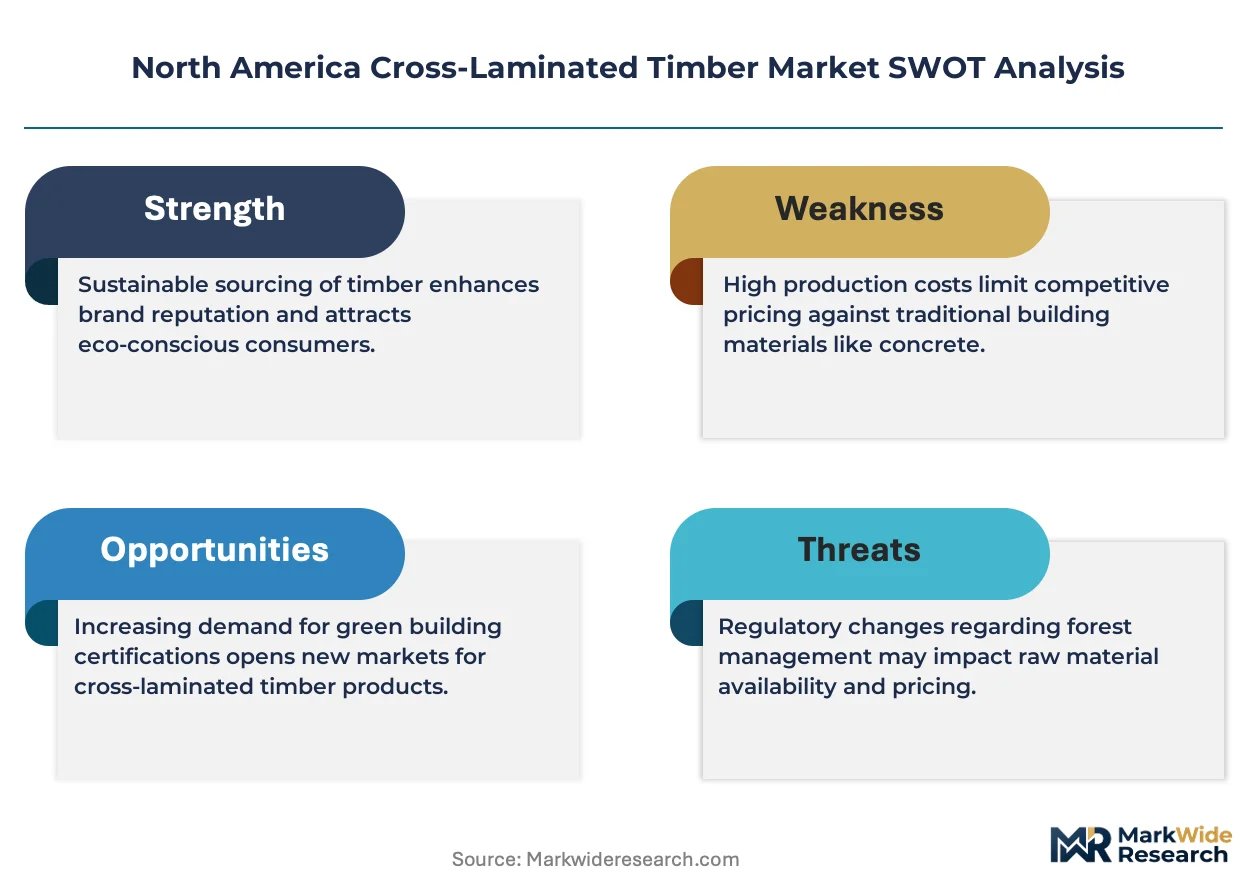
The price-performance gap between premium certified panels and commodity-grade imports is hardening across project bids. Structurlam leverages its British Columbia manufacturing base to anchor supply chains for high-rise developments in Vancouver and Seattle. SmartLam North America competes through specialized architectural-grade finishes that command specification loyalty from design firms. Stora Enso sustains R&D intensity in bonded-wood engineering that extends product performance beyond baseline fire-rating thresholds.
Cross-laminated timber consists of dimension lumber layers stacked perpendicular to one another and bonded under hydraulic pressure, typically achieving panel thicknesses from 60mm to 500mm with three to nine layers. This engineered-wood system delivers structural diaphragm capacity for floors, walls, and roofs while sequestering biogenic carbon across building lifecycles. Structural panels dominate current volume as code-compliant standardization reduces engineering redundancy for mid-rise repetitive framing. Architectural panels represent the fastest-growing category as facade-exposed finishes capture premium positioning in commercial and institutional specifications. Custom panels concentrate margin pools where project-specific dimensions and cutouts reduce field labor for complex geometries.
The International Code Council's Tall Wood Building provisions, adopted variably across US states and Canadian provinces, directly shape permissible building heights and fire-safety testing requirements for CLT assemblies. The US Forest Service's Wood Innovation Grant program and Natural Resources Canada's investments in mass timber demonstration projects channel public capital toward supply-chain maturation and workforce training. Stakeholders must monitor divergent state-level adoption timelines for the International Building Code's mass timber appendix, as jurisdictions like Oregon and Washington accelerate ahead of slower-moving Midwestern states.
Market Dynamics
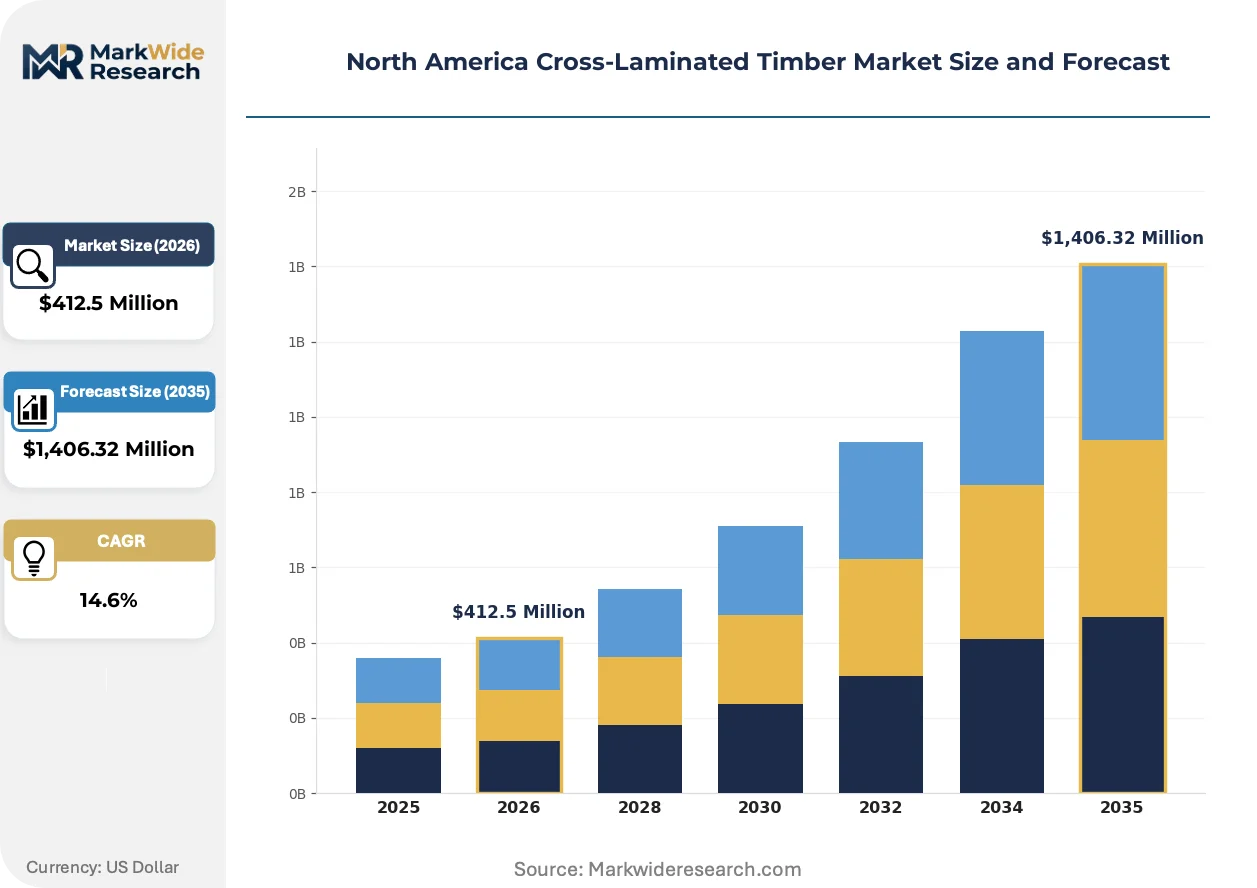
Building code harmonization across US states and Canadian provinces is compressing adoption timelines for mass timber construction, with the International Building Code's Tall Wood Building provisions creating direct pathways for mid-rise and high-rise structural applications.
Growth Catalysts
- EPA Carbon Recognition:The US Environmental Protection Agency's formal acknowledgment of mass timber as a lower-carbon alternative to steel and concrete accelerates regulatory alignment across federal procurement guidelines.
- Multi-Story Residential Pipeline:Pacific Northwest developers are specifying CLT for five-to-twelve-story housing projects where repetitive framing reduces engineering redundancy and accelerates construction schedules.
- British Columbia Mill Capacity:Regional sawmill clustering around Vancouver supplies dimension lumber feedstock with short-haul logistics to Seattle and Portland metropolitan construction sites.
Market Restraints
- Adhesive Cost Volatility:Polyurethane and melamine resin prices fluctuate with petrochemical feedstock markets, compressing panel manufacturer margins during energy price spikes.
- Design Expertise Concentration:Structural engineering competence for mass timber assemblies clusters in Oregon, Washington, and British Columbia, leaving other jurisdictions dependent on remote consultants.
- Steel and Concrete Substitution:Established supply chains for conventional materials maintain contractor familiarity and financing institution comfort levels that slow CLT penetration in risk-averse projects.
Strategic Opportunities
- Midwestern State Adoption Lag:Jurisdictions slower to adopt the International Building Code's mass timber appendix present first-mover advantages for code advocacy and demonstration projects.
- Institutional Building Facades:Architectural-grade panels with exposed timber finishes command premium positioning in university, museum, and civic building specifications seeking biogenic carbon credentials.
- US Forest Service Grants:The Wood Innovation Grant program channels public capital toward supply-chain maturation, workforce training, and manufacturing facility expansion in timber-producing regions.
Industry Challenges
- Mass Timber Installer Shortage:Carpentry trades require retraining for panel lifting, connection hardware installation, and moisture protection protocols distinct from conventional framing.
- Fire-Rating Certification Timelines:Project-specific testing for assembly configurations extends pre-construction schedules by four to eight months relative to prescriptive steel or concrete approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cross-Laminated Timber Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,406.32 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Panels, Architectural Panels, Custom Panels, Prefabricated Elements Application: Residential Construction, Commercial Construction, Industrial Buildings, Infrastructure Projects End User: Contractors, Architects, Builders, Developers Distribution Channel: Direct Sales, Distributors, Online Retail, Dealers |
| Companies Covered | Structurlam, Stora Enso, SmartLam North America, Element5, Binderholz, Timberlab, KLH Massivholz, Kalesnikoff, Katerra, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cross-Laminated Timber Market Strategic Shifts & Innovations
Digital fabrication and predictive engineering are compressing design-to-installation cycles while regulatory recognition of biogenic carbon storage reshapes material specification criteria across public and private procurement.
Building information modeling is converging with automated CNC cutting systems to enable project-specific panel dimensions and complex geometric cutouts that reduce field labor. Design firms in Vancouver and Seattle are specifying these digitally fabricated assemblies for institutional projects with irregular facades. This convergence is compressing the traditional separation between architectural design and manufacturing execution, enabling just-in-time panel delivery that reduces site inventory requirements.
The International Code Council's Tall Wood Building provisions are variably adopted across North American jurisdictions, with Oregon and Washington implementing height allowances ahead of Midwestern states. This regulatory divergence creates competitive positioning advantages for developers in early-adopter states while fragmenting manufacturer sales strategies across inconsistent code environments. British Columbia maintains alignment with US provisions through provincial building code updates that preserve cross-border project standardization.
Public procurement departments are embedding embodied carbon thresholds into material selection criteria, with municipal and state agencies in California, Washington, and British Columbia mandating disclosure of biogenic carbon storage. General contractors are responding by pre-qualifying mass timber suppliers with environmental product declarations and chain-of-custody certification. This specification shift is most visible in civic building portfolios where political accountability drives visible sustainability commitments.
North America Cross-Laminated Timber Market Segmentation
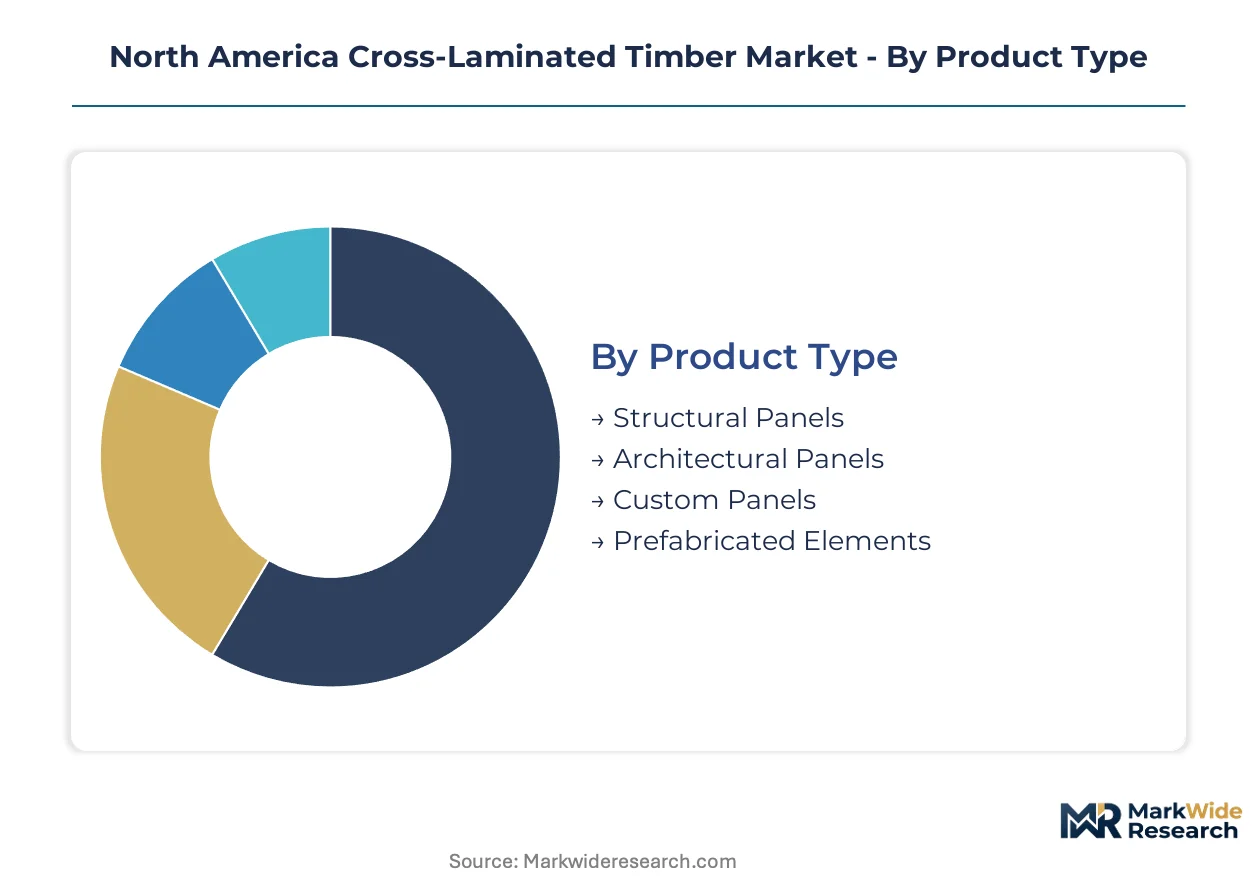
Cross-laminated timber procurement decisions cascade through multiple dimensions: structural performance requirements shape product selection, project scale determines channel preferences, and end-user sophistication influences specification depth. Understanding how these segments intersect reveals where margin pools concentrate and where competitive positioning shifts.
Product Type:
Cost tier differentiation separates commodity-grade specification from premium architectural positioning across North American project bids.
- Structural Panels:Code-standardized assemblies with three to nine perpendicular lumber layers deliver diaphragm capacity for floors, walls, and roofs. Demand concentrates in Pacific Northwest mid-rise residential developments where repetitive framing reduces engineering redundancy and accelerates construction schedules.
- Architectural Panels:Exposed-grade finishes with precise aesthetic grading command specification loyalty from design firms seeking biogenic carbon credentials for civic and institutional facades. British Columbia and Oregon developers specify these for university and museum projects where visible timber surfaces carry political accountability.
- Custom Panels:Project-specific dimensions and CNC-cut geometries reduce field labor for complex institutional envelopes.
- Prefabricated Elements:Pre-cut wall and floor cassettes with integrated connection hardware streamline installation for contractor crews.
Volume sits with structural panels; growth tilts toward architectural panels.
Application:
Project type determines fire-rating requirements, moisture protection protocols, and the economic viability of mass timber substitution against steel and concrete.
- Residential Construction:Five-to-twelve-story multifamily housing in Seattle and Vancouver leverages CLT's speed-to-market advantages where land costs pressure construction timelines. Oregon and Washington building codes permit taller wood structures than Midwestern states, concentrating developer interest in early-adopter jurisdictions.
- Commercial Construction:Office and retail specifications prioritize rapid enclosure for tenant fit-out schedules, with general contractors pre-qualifying suppliers holding environmental product declarations for municipal procurement mandates.
- Industrial Buildings:Warehouse and manufacturing facilities utilize CLT for roof diaphragms where long spans reduce column interference.
- Infrastructure Projects:Bridge decks and pedestrian overpasses test durability in exposed exterior conditions.
Residential commands current volume; commercial specifications are expanding most quickly.
End User:
Professional role dictates whether procurement emphasizes installed cost, design flexibility, or schedule certainty.
- Contractors:Field crews prioritize panel lifting logistics, connection hardware familiarity, and moisture protection sequencing distinct from conventional framing.
- Architects:Vancouver and Seattle design firms drive specification for exposed timber finishes and complex geometric assemblies requiring digital fabrication.
- Builders:Production homebuilders in British Columbia integrate prefabricated elements for repetitive mid-rise typologies.
- Developers:Risk-capital sponsors in Portland and Seattle evaluate mass timber against steel and concrete on total project cost and financing institution comfort levels.
Contractors handle current volume; architects steer specification toward higher-margin categories.
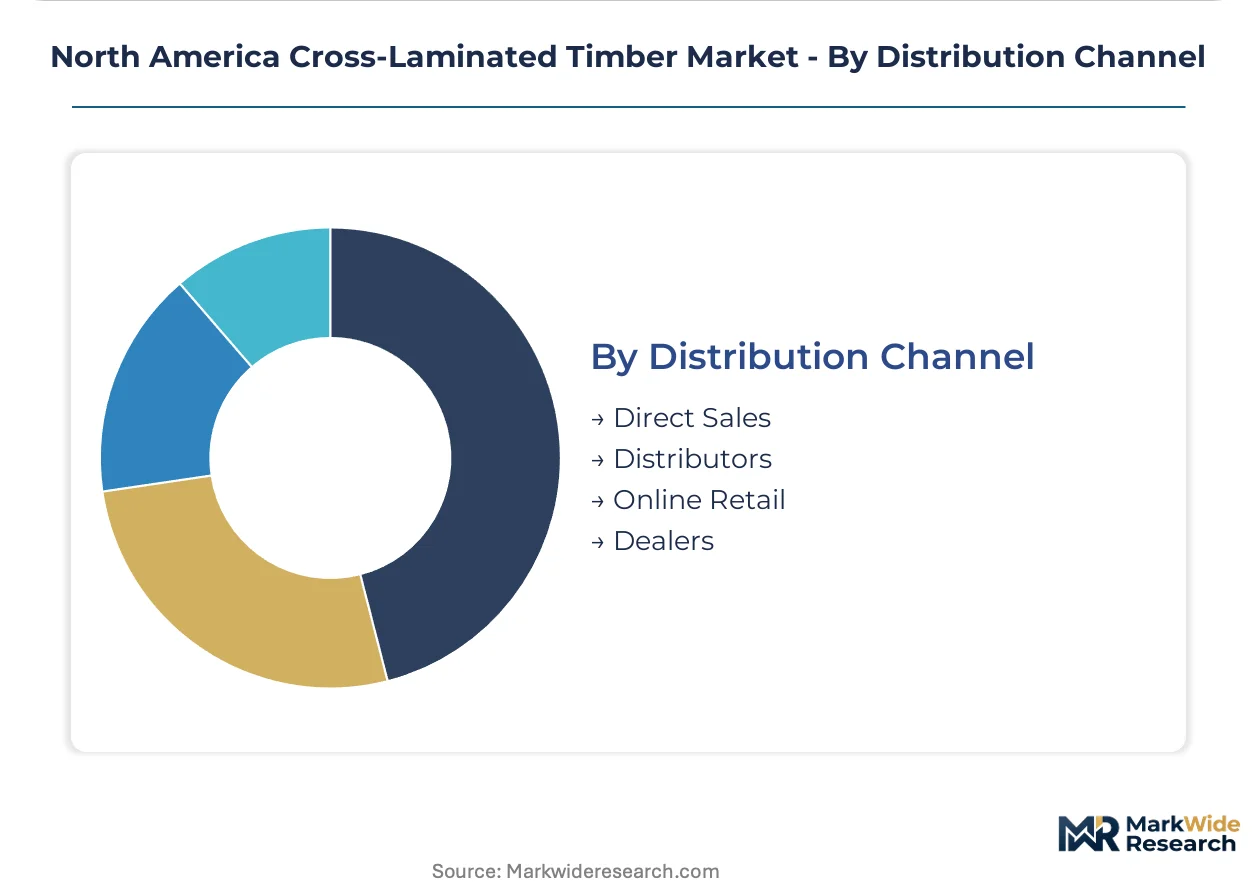
Distribution Channel:
Channel selection reflects project scale, geographic proximity to manufacturing, and the need for technical support during pre-construction.
- Direct Sales:British Columbia manufacturers like Structurlam anchor supply chains for Vancouver and Seattle high-rise developments through mill-direct relationships with general contractors.
- Distributors:Regional lumber wholesalers extend reach into Midwestern states where mass timber adoption lags and design expertise concentrates remotely.
- Online Retail:Small-project builders access standard panel dimensions through digital platforms for single-family and accessory dwelling unit construction.
- Dealers:Local building material outlets serve renovation and light commercial contractors requiring immediate availability.
Direct sales dominate large-project volume; distributor networks gain share fastest in underpenetrated geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vancouver anchors North American mass timber demand through its concentration of high-rise CLT projects, design firms, and regional sawmill capacity serving Pacific Northwest construction corridors.
United States
Seattle and Portland developers specify CLT for five-to-twelve-story multifamily housing where land costs pressure construction timelines. The US Environmental Protection Agency's carbon recognition accelerates federal procurement alignment for mass timber. Oregon and Washington building codes permit taller wood structures than Midwestern states, concentrating developer interest in early-adopter jurisdictions.
Canada
British Columbia maintains alignment with US Tall Wood Building provisions through provincial code updates that preserve cross-border project standardization. Natural Resources Canada channels investment toward mass timber demonstration projects and workforce training. Regional sawmill clustering around Vancouver supplies dimension lumber feedstock with short-haul logistics to metropolitan construction sites.
Mexico
Mass timber adoption remains nascent as building codes lack equivalent tall wood provisions and regional design expertise concentrates remotely. The country's national construction regulator has not yet harmonized with International Building Code mass timber appendix standards. Industrial timber processing clusters in Chihuahua and Durango states supply conventional lumber products without CLT manufacturing infrastructure.
North America Cross-Laminated Timber Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and architectural-finish dimensions. The vendor base separates into three tiers: vertically integrated manufacturers with captive lumber supply, specialized fabricators focusing on architectural-grade finishes, and emerging entrants building regional capacity. Consolidation pressures concentrate among mid-scale operators lacking backward integration into timber assets. Dominant competitive moves include geographic expansion into underpenetrated jurisdictions and portfolio diversification toward prefabricated building systems.
Within the integrated-manufacturer tier, Structurlam and Stora Enso exemplify archetypes combining regional sawmill access with high-rise project execution capability. SmartLam North America occupies a position representing specialized architectural-grade positioning. These three entities anchor competitive dynamics across the Pacific Northwest corridor where design expertise and code permissiveness concentrate.
| Leading Market Players |
|---|
| Structurlam |
| Stora Enso |
| SmartLam North America |
| Element5 |
| Binderholz |
| Timberlab |
| KLH Massivholz |
| Kalesnikoff |
| Katerra |
| Others |
Cost & Logistics Intelligence
Captive sawmill ownership across British Columbia and the Pacific Northwest anchors both feedstock security and pricing power for integrated CLT manufacturers serving high-rise developments. This backward integration into dimension lumber production insulates premium-panel producers from commodity price spikes while concentrating margin capture among vertically integrated players.
Pricing Analysis
Outcome-based pricing tied to fire-rating certification and carbon-sequestration credentials anchors premium positioning for architectural-grade panels specified in civic and institutional facades. Three-tier pricing structure across premium certified, standard structural, and economy-grade imports separates specification loyalty in design firms from cost-driven contractor procurement. Pricing pressure stems from adhesive cost volatility as polyurethane and melamine resin prices fluctuate with petrochemical feedstock markets. Production homebuilders exhibit highest price sensitivity, while university and museum developers prioritize certified biogenic carbon credentials over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from general contractors pre-qualifying mass timber suppliers with environmental product declarations and chain-of-custody certification are reshaping supplier qualification protocols. Feedstock concentration centers on British Columbia, Oregon, and Washington where regional sawmill clustering supplies dimension lumber with short-haul logistics to metropolitan construction sites. Adhesive resins, precision CNC cutting equipment, and certified engineering labor constitute critical input dependencies. Single-source vulnerability concentrates in specialized connection hardware and fire-rating certification testing capacity. Distribution runs through mill-direct relationships for large projects and regional lumber wholesalers for underpenetrated Midwestern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CLT manufacturing is consolidating around vertically integrated players with captive timber assets, as adhesive cost volatility and fire-rating certification timelines force mid-scale operators lacking backward integration toward exit or acquisition.
For Market Incumbents: Lock in specification loyalty by deepening architectural-grade finish capabilities and securing multi-project offtake agreements with Pacific Northwest developers. Threat from commodity-grade imports compresses margins in standard structural panels; counter by investing in CNC digital fabrication capacity for complex geometric custom panels that command premium positioning and reduce field labor for contractor crews. For New Entrants and Emerging Players: The price-point gap between premium certified architectural panels and economy-grade imports opens white-space targeting for mid-tier structural panels in Midwestern states where mass timber adoption lags behind Oregon and Washington. Target institutional building facades in university and museum segments where political accountability drives visible sustainability commitments and biogenic carbon disclosure mandates. Go-to-market angle: partner with regional lumber distributors to extend technical support capabilities into jurisdictions lacking local design expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated forest products companies seeking mass timber manufacturing capability and Tall Wood Building code expertise. Long-term viability favors operators with captive sawmill supply, established fire-rating certification relationships, and mill-direct relationships with repeat high-rise developers. Signal to watch: state-level adoption timelines for the International Building Code's mass timber appendix, as acceleration in Midwestern jurisdictions would inflect addressable market expansion materially.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sawmill Assets | Captive lumber supply from British Columbia and Pacific Northwest mills insulates margin from commodity price volatility. |
| Fire-Rating Certification Investment | Established testing relationships with ICC-ES and UL compress pre-construction schedules relative to project-specific assembly approvals. |
| CNC Digital Fabrication Capacity | Automated cutting systems enable complex geometric panels that reduce field labor and command specification loyalty from Seattle and Vancouver design firms. |
| Regional Distributor Partnership | Lumber wholesaler alliances extend technical support into Midwestern states where mass timber adoption lags and design expertise concentrates remotely. |
| Architectural-Grade Finish Development | Precise aesthetic grading and exposed timber surfaces capture premium positioning in university and museum procurement mandates. |
Research Approach
Document review covered building code adoption filings, environmental product declaration databases, and Wood Innovation Grant program disbursement records, complemented by interviews with mass timber manufacturers, structural engineering firms, and general contractors. Primary fieldwork included discussions with plant managers at British Columbia sawmill operations, procurement leads at Pacific Northwest developers, and technical directors at certification testing laboratories. Secondary validation drew from International Code Council Tall Wood Building provision adoption tracking, US Forest Service grant documentation, and Natural Resources Canada demonstration project records. Bottom-up project pipeline analysis triangulated against top-down manufacturing capacity estimates.
Cross-referencing historical construction permit data against panel manufacturer shipment records informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application category, end-user professional role, and distribution channel structure, with additional weighting for state-level code adoption status. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific forecast inputs incorporated adhesive resin price indices and Tall Wood Building provision adoption timelines.
Inputs from ICC-ES certification databases and provincial building code update records were available through the study window; gaps in project-specific fire-rating test completion dates introduce uncertainty bands around near-term volume estimates. Deviation in Midwestern state adoption timelines for the International Building Code's mass timber appendix would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Residential and Commercial Smart Glass Market