
 Skirting Board Market | 2026-2036
Skirting Board Market Size, Share, and Industry Trends Forecast 2026-2036
Skirting Board Market Analytics
Specialist building-product distributors is narrowing across Europe as online channels and direct-to-contractor platforms capture specification influence. Egger leverages its integrated wood-based panel supply chain to sustain cost leadership in MDF skirting production. Dollken Profiles GmbH anchors German manufacturing scale while competing on extruded PVC and polymer formulations. Orac Decor differentiates through design-forward polyurethane profiles that command premium positioning in architect-specified interiors.
Skirting boards are decorative and protective moldings installed at the junction of walls and floors, typically manufactured from timber composites, thermoplastics, or foamed polymers in heights ranging from 50 mm to 200 mm with thickness tolerances critical to flush wall alignment. These components shield wall bases from impact damage, conceal flooring expansion gaps, and provide a finished aesthetic transition in residential and commercial fit-outs. MDF skirting dominates volume in European markets due to cost efficiency and paint-ready surfaces, while PVC and polyurethane segments capture growth in moisture-prone applications and ornate restoration projects where traditional plaster details prove impractical. Installation method preferences increasingly favor clip-based systems in commercial retail fit-outs for rapid disassembly during tenant churn.
REACH regulations enforced by ECHA restrict phthalate plasticizers in PVC formulations, compelling reformulation across continental European supply chains. CE marking requirements under the EU Construction Products Regulation mandate declared performance for fire reaction and dimensional stability, shaping product development priorities for exporters. BSI Kitemark and British Standards Institution testing protocols in the United Kingdom impose additional compliance layers for suppliers accessing specification channels. Stakeholders must monitor evolving embodied-carbon disclosure rules under the EU Green Deal as these will soon filter into public procurement criteria for interior fit-out materials.
Market Dynamics
REACH chemical restrictions are forcing wholesale reformulation of PVC skirting compounds across European manufacturing bases, compressing margins while accelerating low-VOC finish adoption. This regulatory pressure intersects with moisture-resistant MDF demand from German residential renovation and clip-based installation preferences in UK commercial retail fit-outs.
Growth Catalysts
- Moisture-resistant MDF adoption:German residential renovation activity drives specification of engineered timber composites in bathrooms and kitchens where traditional softwood deteriorates.
- REACH low-VOC mandates:ECHA enforcement of phthalate restrictions in PVC formulations compels manufacturers to develop compliant polymer alternatives.
- Clip-based installation systems:UK commercial retail fit-outs favor rapid-disassembly skirting for tenant churn scenarios, accelerating mechanical fixing adoption over adhesive methods.
Market Restraints
- Timber input cost volatility:Baltic softwood supply fluctuations and energy-intensive MDF production expose manufacturers to margin compression during raw material spikes.
- Regulatory friction from CE marking:EU Construction Products Regulation mandates for fire reaction and dimensional stability impose testing burdens on smaller exporters.
- Substitution threat from integrated flooring:Luxury vinyl tile and laminate systems with built-in wall-base profiles eliminate separate skirting procurement in new-build segments.
Strategic Opportunities
- Underpenetrated French renovation stock:Pre-1990s housing in Lyon and Marseille retains obsolete plaster skirting, creating retrofit demand for lightweight polymer profiles.
- Embodied-carbon procurement mandates:EU Green Deal disclosure rules filtering into public fit-out tenders favor suppliers with verified EPDs and bio-based material content.
- Direct-to-contractor platforms:Digital specification tools are capturing architect and installer influence previously held by specialist building-product distributors.
Industry Challenges
- Fire-reaction certification timelines:CE marking testing for Class B-s1,d0 performance in commercial applications extends product development cycles by 4-6 months.
- Skill gaps in polymer extrusion:Shortage of technicians experienced in co-extrusion tooling for multi-layer PVC profiles limits capacity expansion at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skirting Board Market |
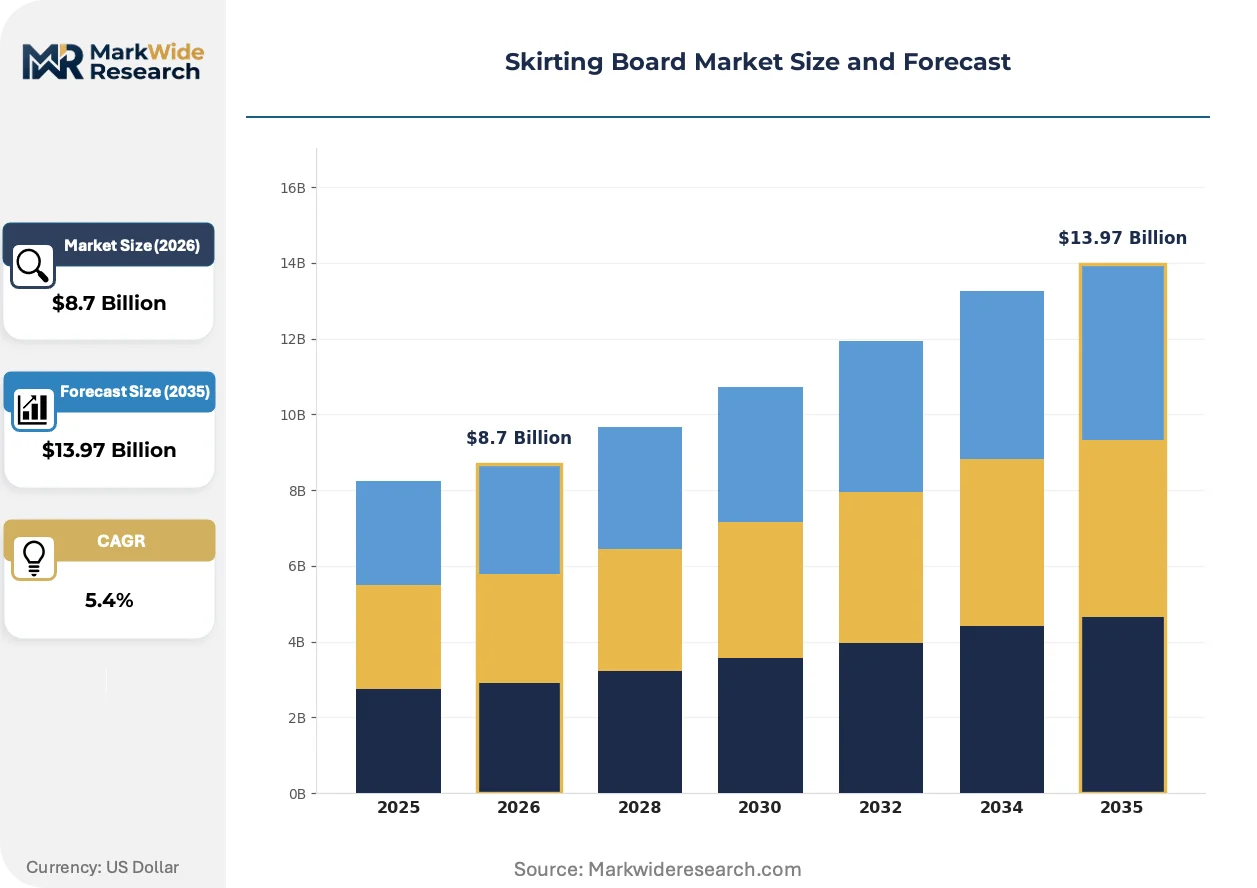
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, MDF, PVC, Polyurethane Installation Method: Glue, Nails, Clips, Screws End User Segment: Residential, Commercial, Industrial, Retail Design Style: Modern, Traditional, Rustic, Minimalist |
| Companies Covered | Orac Decor, Egger, Dollken Profiles GmbH, Skirting World, Arbiton, Parador GmbH, Osmo Holz und Color, Skirting4U, Profilpas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skirting Board Market Evolving Landscape
Digital specification platforms and low-carbon material disclosure are restructuring how skirting products reach commercial and residential buyers. Three intersecting developments are compressing traditional distribution hierarchies while elevating performance transparency.
Building information modeling (BIM) libraries for interior moldings are virtualizing the specification workflow between architects and manufacturers. Large UK housing developers now embed parametric skirting objects directly into digital twin models, compressing the traditional sample-request-to-order cycle from weeks to days. This virtualization is displacing physical showroom visits and reducing distributor influence over product selection.
EU Green Deal embodied-carbon disclosure requirements are mandating environmental product declarations for public procurement above defined thresholds. ECHA guidance on construction material footprints is filtering into BSI Kitemark testing protocols, forcing suppliers to document cradle-to-gate emissions. German manufacturers with integrated panel supply chains hold advantage in generating verified EPDs for MDF skirting lines.
Installer preference for mechanical fixing systems is fragmenting procurement patterns across commercial and residential segments. Clip-based profiles specified by UK retail fit-out contractors enable rapid disassembly during tenant turnover, while adhesive-free installation appeals to German renovation clients concerned with future reversibility. This behavioral shift concentrates volume with suppliers offering compatible subfloor channel systems rather than standalone molding products.
Skirting Board Market Segmentation
Skirting board procurement patterns diverge sharply across material grades, fixing systems, and end-use environments. Specification influence concentrates with architects in commercial segments and contractors in residential renovation, creating distinct channel requirements for each segmentation axis.
Material Type:
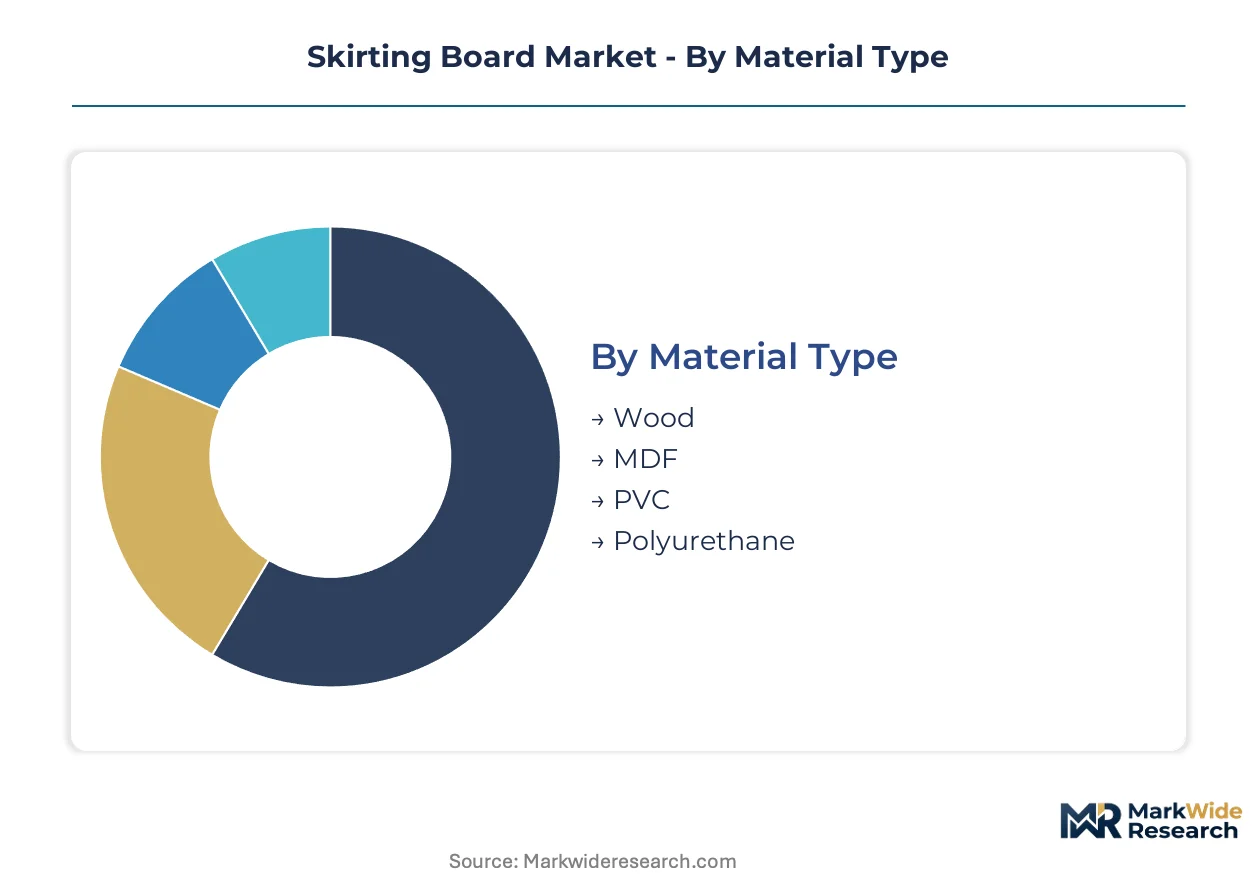
Cost tier determines margin structure and regulatory exposure across the four material categories, with engineered composites commanding volume leadership and premium polymers capturing specification-driven niches.
- Wood:Solid timber profiles in oak, pine, and hardwood grades serve heritage restoration and high-end residential specifications where natural grain aesthetics justify premium positioning. UK listed-building renovations and German Bauhaus-period restorations specify FSC-certified European oak for dimensional stability and patina development over decades.
- MDF:Medium-density fiberboard dominates European volume through paint-ready surfaces and uniform machining tolerances. German residential renovation activity specifies moisture-resistant grades for bathroom and kitchen perimeters where traditional softwood suffers swelling degradation.
- PVC:Extruded thermoplastic formulations capture moisture-prone applications and commercial retail fit-outs requiring impact resistance. REACH phthalate restrictions enforced by ECHA compel reformulation toward bio-based plasticizers and calcium-zinc stabilizer systems.
- Polyurethane:High-density foamed polymer profiles enable ornate cornice-replication with fractional weight of traditional plaster. French restoration contractors specify Orac Decor and comparable design-forward brands for Lyon and Marseille pre-1990s housing retrofits where structural load limits prohibit heavy moldings.
MDF holds installed capacity. Polyurethane is rotating up the share rankings.
Installation Method:
Application environment dictates mechanical versus chemical fixing preferences, with tenant-churn scenarios and renovation reversibility requirements fragmenting procurement patterns across commercial and residential segments.
- Glue:Adhesive bonding delivers seamless aesthetic transitions in premium residential finishes where nail visibility compromises visual continuity. German renovation clients favor solvent-free MS polymer adhesives compatible with future substrate removal.
- Nails:Pneumatic pinning remains standard for softwood and MDF installations in new-build housing where speed outweighs disassembly requirements. UK volume housebuilders specify 50mm brad nails for 15mm skirting thicknesses across standard-height profiles.
- Clips:Mechanical channel systems enable rapid disassembly without substrate damage, capturing specification from UK commercial retail fit-out contractors managing tenant turnover cycles. B&Q and Wickes distribution channels stock proprietary clip-compatible profiles for this expanding segment.
- Screws:Structural fixing through pre-drilled countersinks provides maximum pull-out resistance for heavy hardwood profiles and high-traffic commercial corridors. Industrial warehouse specifications in Germany's logistics hubs mandate screw-fixed 25mm oak skirting for forklift impact zones.
Clip-based systems are climbing the fastest in commercial specification channels. Glue methods retain dominance in premium residential finishing.
End User Segment:
Customer type segments by project scale, decision-maker identity, and procurement cycle length, with residential renovation offering fragmented volume and commercial retail delivering concentrated specification opportunities.
- Residential:Single-family and multi-unit housing drives MDF volume through cost-sensitive new-build and renovation procurement. German bathroom and kitchen renovations specify moisture-resistant engineered composites over traditional softwood.
- Commercial:Office fit-outs and hospitality interiors balance durability requirements with design flexibility, favoring polyurethane profiles for brand-differentiated reception areas. Clip-based systems reduce reinstatement costs between lease events.
- Industrial:Manufacturing and logistics facilities prioritize impact resistance and chemical cleaning compatibility, specifying PVC or hardwood grades for wash-down compliance. German automotive supplier campuses mandate screw-fixed profiles for forklift traffic zones.
- Retail:High-turnover tenant environments in UK shopping centers and high-street chains drive specification of rapid-disassembly skirting systems. Digital specification platforms capture architect and contractor influence previously held by specialist distributors.
Residential commands absolute volume. Retail is gaining share fastest through specification platform capture.
Design Style:
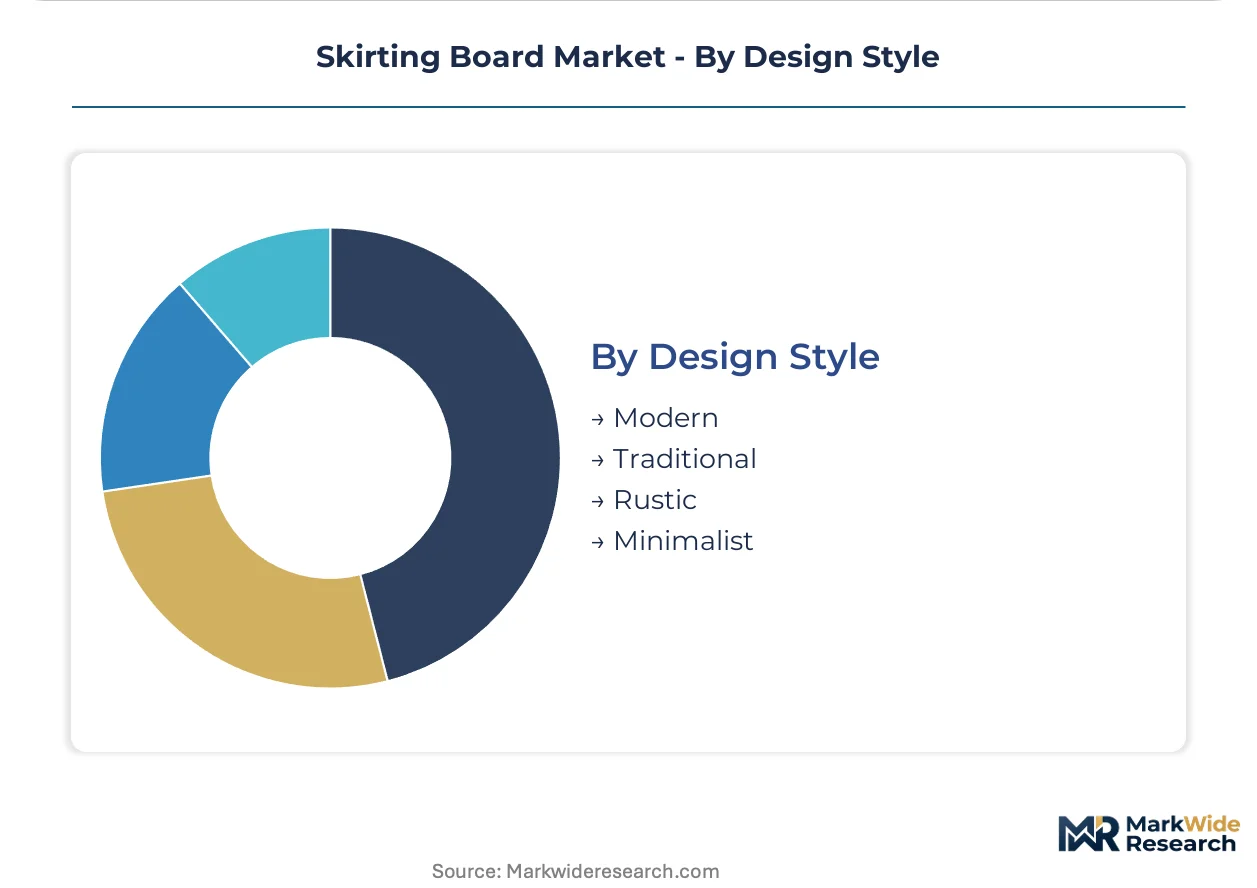
Maturity of aesthetic preference correlates with regional architectural heritage and renovation age-profile, with modern and minimalist profiles displacing traditional ornamentation in new-build segments while restoration demand sustains classic categories.
- Modern:Clean-lined profiles with square edges and minimal projection align with contemporary residential and commercial interiors. UK new-build housing developers specify 70mm-100mm heights with pencil-round or chamfered tops for cost-efficient paint finishing.
- Traditional:Ogee, torus, and lamb's tongue profiles replicate Victorian and Edwardian architectural vocabulary for period-appropriate restoration. French pre-1990s housing stock in Lyon and Marseille generates retrofit demand for ornate polymer reproductions.
- Rustic:Hand-finished or distressed surfaces in solid timber grades serve farmhouse and countryside aesthetic specifications. German rural renovation projects favor brushed oak with visible grain and tonal variation.
- Minimalist:Shadow-gap and flush-to-wall systems eliminate visible skirting entirely, requiring precise drywall finishing and recessed floor channels. Architect-specified commercial interiors in London and Berlin adopt this approach for gallery and flagship retail environments.
Traditional profiles hold installed capacity in restoration stock. Modern styling is rotating up the share rankings in new-build specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers capture pricing power through integrated MDF supply chains, while UK distributors face margin compression from direct-to-contractor digital platforms. This asymmetry reflects divergent channel structures across European skirting markets.
Germany
Residential renovation in Bavaria and North Rhine-Westphalia drives moisture-resistant MDF specification for bathroom and kitchen perimeters. REACH enforcement by ECHA compels reformulation of PVC compounds toward bio-based plasticizers. The Egger integrated panel supply chain in Bavaria sustains cost leadership through captive resin and fiber sourcing.
United Kingdom
New-build housing volume concentrates specification influence with national developers adopting clip-based installation for tenant churn scenarios. BSI Kitemark testing protocols impose additional compliance layers beyond baseline CE marking. Greater London retail fit-out contractors specify rapid-disassembly profiles through digital platforms that displace specialist distributor influence.
France
Pre-1990s housing stock in Lyon and Marseille generates retrofit demand for lightweight polyurethane profiles replacing obsolete plaster moldings. ANSM oversight of indoor air quality standards shapes low-VOC finish requirements. The Provence-Alpes-Côte d'Azur corridor anchors restoration contractor networks specifying design-forward polymer reproductions.
Italy
Heritage restoration in Lombardy and Veneto sustains demand for FSC-certified solid timber profiles in period-appropriate specifications. CE marking under the EU Construction Products Regulation mandates declared fire-reaction performance for commercial exports. Milan architect-specified interiors favor minimalist shadow-gap systems in gallery and flagship retail environments.
Poland
MDF production clusters near Baltic softwood supply sources serve export markets across Central Europe. Polish manufacturers face margin pressure from energy-intensive fiberboard processing during raw material spikes. Warsaw-based distributors intermediate between German panel suppliers and Eastern European renovation contractors.
Skirting Board Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply. The vendor base fragments across MDF panel producers, extruded PVC compounders, and design-forward polyurethane formulators. Three archetypes dominate: integrated wood-based panel manufacturers, specialized polymer extrusion houses, and premium decorative molding brands. Competitive moves concentrate on backward integration into resin and fiber supply, plus digital specification platform partnerships that compress traditional distribution hierarchies.
Among German-based manufacturers, Egger and Dollken Profiles GmbH anchor distinct strategic positions. Egger exemplifies the integrated panel archetype with captive supply chain control over MDF substrate production. Dollken Profiles GmbH occupies the specialized extrusion tier, competing on polymer formulation capabilities. Orac Decor represents the premium design-forward segment, commanding architect-specified positioning through ornate polyurethane profiles. These three companies illustrate how material specialization and channel strategy segment competitive terrain.
| Leading Market Players |
|---|
| Orac Decor |
| Egger |
| Dollken Profiles GmbH |
| Skirting World |
| Arbiton |
| Parador GmbH |
| Osmo Holz und Color |
| Skirting4U |
| Profilpas |
| Others |
Value Network & Pricing Analysis
Bavarian MDF panel clusters anchor European supply capacity through Egger's integrated fiberboard operations, translating captive resin sourcing into downstream pricing power for moisture-resistant skirting grades. This geographic concentration shapes how manufacturers negotiate Baltic softwood volatility and energy-intensive production cycles.
Pricing Analysis
Configured-to-order pricing for ornate polyurethane profiles commands substantial premiums over standard MDF extrusions, with three-tier pricing structure across premium, standard, and economy levels stratifying by certification grade and installation complexity. CE marking under the EU Construction Products Regulation and BSI Kitemark testing protocols create price differentiation between compliant and baseline offerings. Cost compression in PVC compounds is intensifying because REACH-mandated phthalate reformulation adds formulation R&D burdens. Volume housebuilders exhibit highest price sensitivity, while architect-specified restoration projects demonstrate lowest elasticity.
Supply Chain Analysis
Export-control regime angles for timber products remain minimal, though ECHA REACH restrictions on chemical inputs functionally constrain compound flows into continental European extrusion plants. Manufacturing concentrates in Germany, Poland, and the United Kingdom, with Polish clusters drawing from Baltic softwood feedstocks and German facilities leveraging captive fiber supply. Raw material dependencies center on urea-formaldehyde resins, softwood pulp, and calcium-zinc stabilizer systems replacing restricted phthalates. Single-source vulnerability persists in specialized co-extrusion tooling for multi-layer PVC profiles. Distribution runs through specialist building-product distributors facing displacement from direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated flooring systems with built-in wall-base profiles threaten separate skirting procurement, forcing incumbents to demonstrate irreplaceable value in renovation and restoration segments where substrate conditions demand adaptable solutions.
For Market Incumbents: Harden specification influence through BIM library partnerships that embed parametric skirting objects directly into architect workflows, countering distributor disintermediation. Deepen backward integration into bio-based resin formulations to preempt REACH compliance cost pass-through. Prioritize fire-reaction certification investment for Class B-s1,d0 commercial grades, as extended testing timelines create defensive moats against smaller competitors. For New Entrants and Emerging Players: Mid-market commercial retail fit-outs in French secondary cities represent the most penetrable entry point, where pre-1990s housing stock demands lightweight polyurethane retrofits and incumbent coverage remains patchy. Target clip-based installation system compatibility as the go-to-market anchor, leveraging rapid-disassembly specifications from UK tenant-churn contractors to bypass established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated panel manufacturers with captive MDF supply chains and verified EPD portfolios qualifying for EU Green Deal procurement mandates. Long-term viability hinges on embodied-carbon disclosure capabilities filtering into public tender requirements. Monitor ECHA guidance evolution on construction material footprints as the critical inflection signal for valuation repricing across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Egger's captive supply chain demonstrates how in-house resin production insulates margin from REACH reformulation shocks. |
| BIM Library Partnership | Orac Decor's parametric object placement compresses specification cycles from weeks to days for architect-led projects. |
| Fire-Reaction Certification Investment | Class B-s1,d0 testing timelines extend product development by 4-6 months, creating defensive positioning in commercial segments. |
| Direct-to-Contractor Platform Launch | Digital specification tools capture installer influence previously held by Wickes and B&Q distribution channels. |
| EPD Verification Program | Environmental product declarations qualify suppliers for EU Green Deal public procurement thresholds above defined contract values. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at MDF extrusion facilities, procurement leads at UK housing developers, and technical R&D directors at polymer compounders; plus secondary validation through customs and trade data, SEC 10-K filings of listed building-product manufacturers, and BSI Kitemark certification databases. Bottom-up volume modeling triangulated against top-down construction spend allocation across residential renovation and commercial fit-out segments.
Forecast inputs considered material-grade segmentation by MDF, PVC, polyurethane, and solid timber categories alongside installation-method differentiation across adhesive, mechanical, and clip-based systems. Modeled variables included REACH compliance cost pass-through, Baltic softwood supply fluctuations, and clip-system adoption curves in UK retail fit-outs. CAGRs were derived from regression analysis of historical construction output correlations and regulatory implementation timelines across the projection horizon.
Practitioners should monitor ECHA enforcement intensity and EU Green Deal procurement threshold adjustments for early signals of competitive repositioning requirements. Forecasts reflect assumptions regarding stable CE marking protocols and continued softwood fiber availability from Baltic sources. Material shifts in embodied-carbon disclosure mandates or single-use plastic restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Spray Foam Market