
 Foldable Container House Market | 2026-2036
Foldable Container House Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Container House Market Insights
REACH compliance in Europe is expanding material certification burdens for steel and insulation suppliers entering the foldable container house value chain. SG Blocks leverages its modular fabrication expertise to anchor North American project pipelines. Royal Wolf sustains dominant fleet scale across Australasian rental markets. Quick Smart House Co., Ltd competes on rapid-assembly engineering for remote worksite contracts in Asia.
A foldable container house is a prefabricated dwelling system built from corrugated steel shells with hinged or telescoping frames that collapse for transport and expand on-site, typically achieving floor areas of 15–40 square meters when deployed. The primary purpose is to deliver rapid-installation shelter for populations or workforces in locations where conventional construction proves impractical or prohibitively slow. Single-unit containers dominate current volume owing to their compatibility with standard ISO shipping logistics and minimal foundation requirements. Multi-unit configurations and modular units are gaining traction in tourist accommodation and semi-permanent housing where stacked or clustered layouts multiply usable space. Portable units command premium positioning in research stations and emergency response fleets where air-transport weight limits dictate specifications.
FEMA guidelines in the United States, the EU Construction Products Regulation, and BIS structural steel standards in India collectively shape product safety benchmarks, thermal performance thresholds, and market access conditions for manufacturers. Compliance with these frameworks determines eligibility for government tenders and disaster-relief procurement channels. Stakeholders must monitor evolving energy-efficiency addendums and local wind-load amendments that will soon differentiate certified suppliers from marginal entrants.
Market Dynamics
Cold-formed steel framing innovations are compressing unit weights by nearly one-third while preserving load-bearing capacity, fundamentally altering logistics economics and expanding deployable geographies for foldable container housing systems.
Growth Catalysts
- Disaster resilience mandates:Southeast Asian government agencies are scaling emergency shelter procurement following updated building codes that prioritize rapid-deployment structures in seismic and cyclone zones.
- Archipelago logistics:Indonesia's dispersed island geography and constrained construction material flows are concentrating foldable container deployment at remote worksites and coastal installations.
- ISO shipping compatibility:Single-unit containers leverage existing intermodal infrastructure, eliminating dedicated transport fleets and reducing mobilization timelines for humanitarian and workforce housing.
Market Restraints
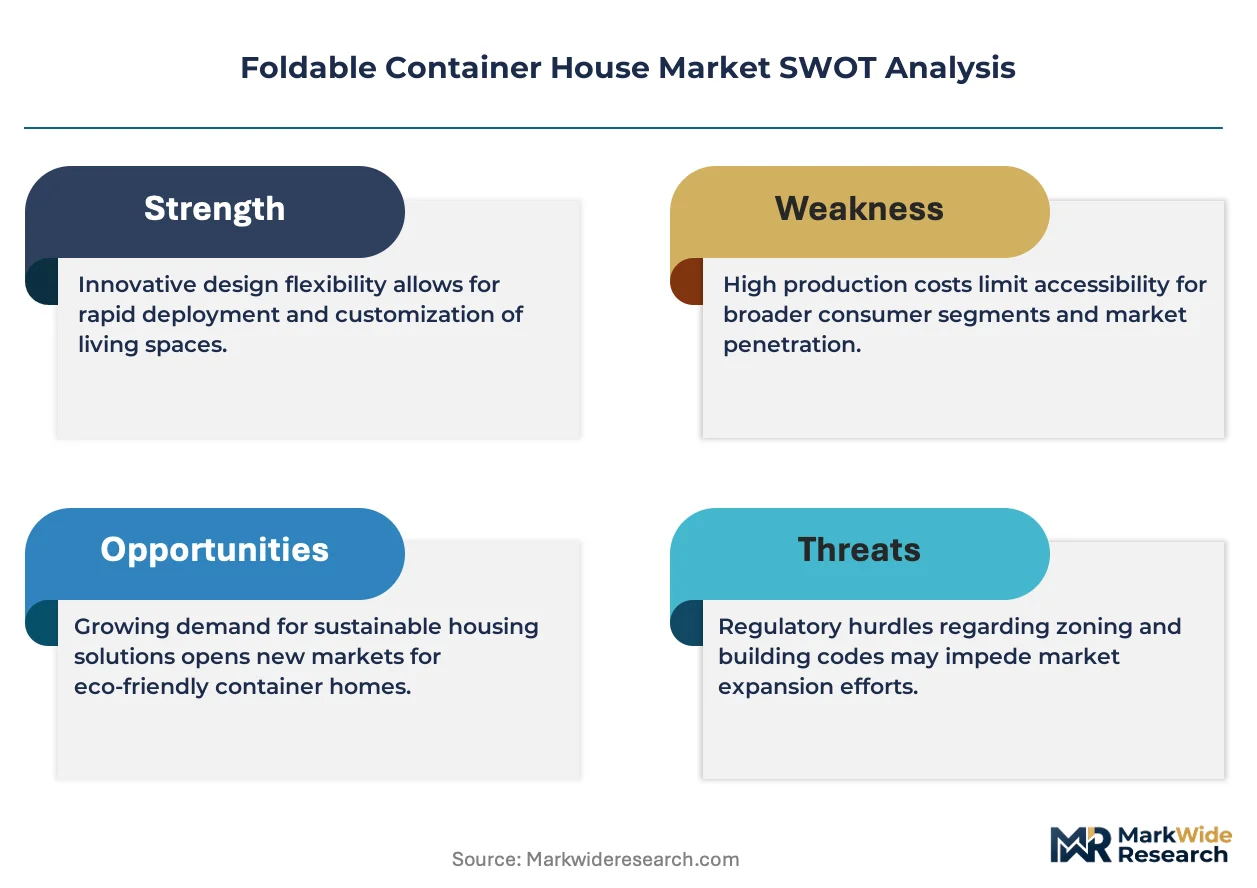
- Steel input volatility:Corrugated steel shell costs fluctuate with raw material pricing, compressing margins for fabricators without long-term supply agreements or captive rolling capacity.
- REACH certification burdens:European material compliance requirements for insulation and coating suppliers are extending qualification timelines and raising entry costs for value chain participants.
- Foundation adaptation limits:Permafrost and expansive soil conditions in northern latitudes constrain standard anchoring systems, requiring site-specific engineering that erodes the speed advantage.
Strategic Opportunities
- Tourist accommodation pivot:Multi-unit configurations and modular clustering are penetrating eco-lodge and glamping segments where stacked layouts multiply usable space without permanent foundations.
- Air-transport premium tier:Portable units specified for research stations and rapid-response fleets command pricing advantages where weight limits below standard ISO thresholds dictate aluminum or composite framing.
- EU Green Deal alignment:Energy-efficiency addendums to the Construction Products Regulation are creating certified-supplier preference windows for manufacturers meeting thermal performance thresholds.
Industry Challenges
- Welding certification scarcity:Qualified cold-formed steel fabricators capable of meeting BIS structural standards and FEMA wind-load requirements remain concentrated in limited manufacturing clusters.
- Multi-standard harmonization:Reconciling EU Construction Products Regulation, Indian BIS steel standards, and US FEMA guidelines for cross-border project execution extends engineering timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Container House Market |
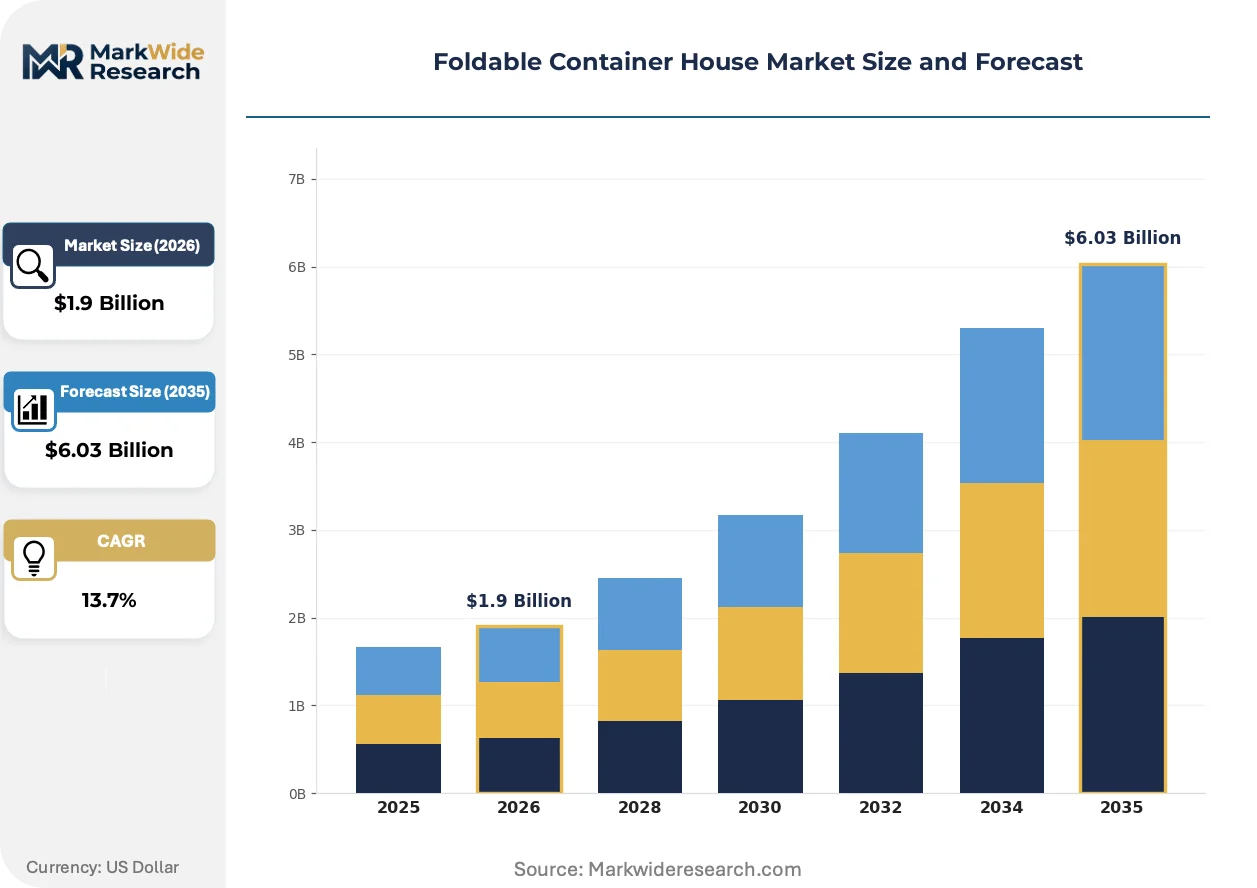
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $6.03 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Unit Containers, Multi-Unit Containers, Modular Units, Portable Units Application: Temporary Housing, Emergency Shelters, Tourist Accommodation, Remote Worksites End User: Construction Firms, Government Agencies, Hospitality Providers, Research Stations Deployment: Urban Installations, Rural Setups, Coastal Areas, Mountain Locations |
| Companies Covered | HONOMOBO, SG Blocks, Backcountry Containers, Rhino Cubed, Expandable Container Homes, Royal Wolf, Quick Smart House Co., Ltd, Anderco, Revolution Precrafted, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Container House Market Trends and Innovations
Material science advances and procurement model evolution are compressing deployment timelines while regulatory frameworks differentiate certified suppliers from marginal market entrants.
Telescoping frame mechanisms with integrated corner castings are overtaking hinged panel systems as the dominant folding architecture. Mining camp operators and disaster-response agencies are specifying these units for their reduced labor requirements during expansion. The technology is overtaking conventional assembly methods by enabling two-person deployment of forty-square-meter footprints within four hours.
REACH compliance expansions are extending material certification obligations to insulation foam and anti-corrosion coating suppliers entering the European foldable container value chain. Industrial consequences include supplier consolidation as smaller chemical formulators exit rather than absorb registration costs. Manufacturers targeting EU government tenders are responding by qualifying captive coating facilities or securing exclusive supply partnerships with pre-registered chemical distributors.
Outcome-based rental contracts are displacing unit purchase models in Australasian workforce housing markets. Construction and resources firms are contracting for bed-nights rather than capital equipment, transferring utilization risk to fleet operators. This shift concentrates most visibly in Queensland and Western Australia mining corridors where project duration uncertainty previously generated stranded asset risk for camp owners.
Foldable Container House Market Segmentation
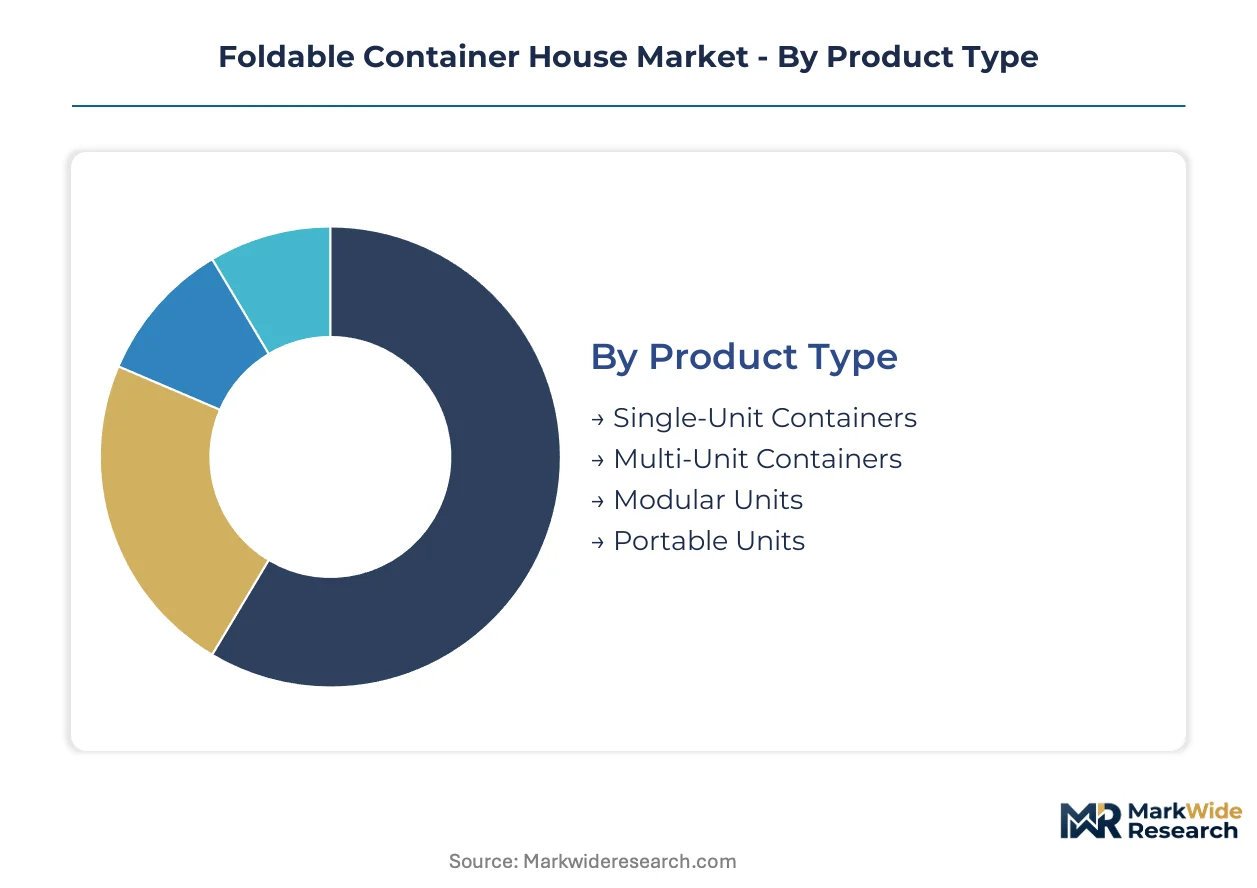
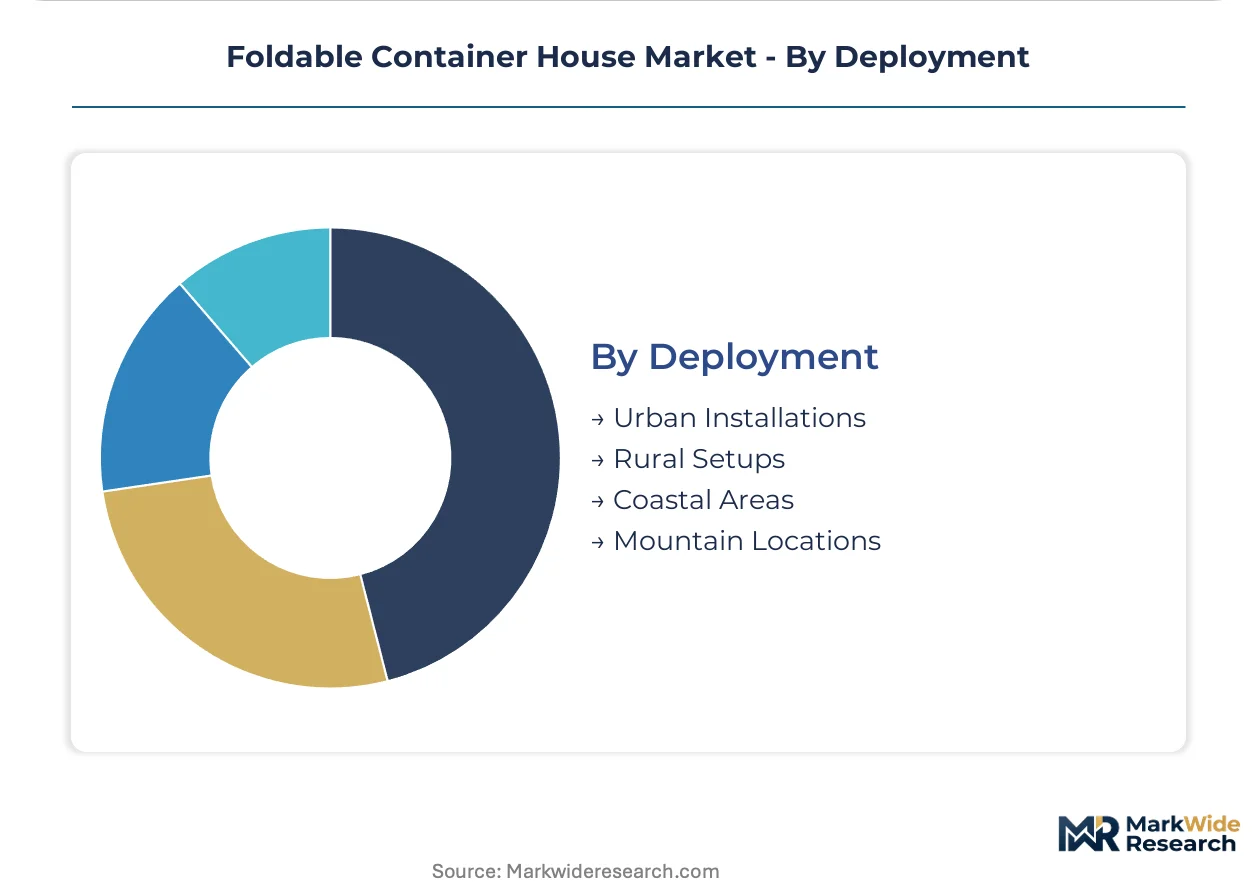
Segmentation in foldable container housing reveals distinct procurement patterns across product architectures and deployment contexts. Each category maps to specific logistics constraints, regulatory thresholds, and end-user risk profiles that determine supplier qualification requirements.
Product Type:
Standalone single-unit containers dominate procurement volumes, while modular and portable configurations embed into specialized systems requiring integration engineering.
- Single-Unit Containers:Corrugated steel shells with hinged end frames collapse to ISO standard dimensions for intermodal transport. Demand concentrates in Indonesia's remote worksites where archipelago logistics and disaster-response budgets prioritize compatibility with existing shipping infrastructure.
- Multi-Unit Containers:Interconnecting shells with shared structural nodes enable clustered layouts up to 120 square meters. Tourist accommodation operators in Queensland and Western Australia specify these for eco-lodge deployments where stacked configurations multiply usable space without permanent foundations.
- Portable Units:Aluminum or composite framing achieves air-transport weight thresholds below standard ISO limits. Research stations in Antarctic and high-altitude locations command premium positioning for rapid-response fleet specifications.
- Modular Units:Factory-integrated MEP systems reduce on-site connection labor for semi-permanent housing clusters. Government agencies in Southeast Asia specify these for extended-duration emergency shelter contracts.
Single-unit containers lead volumes today; multi-unit configurations are gaining share fastest.
Application:
Cost tier differentiation separates high-volume temporary housing from premium-priced emergency response deployments.
- Temporary Housing:Standard cold-formed steel units with basic insulation serve workforce rotation cycles in mining and construction corridors. Outcome-based rental contracts in Australasia transfer utilization risk from construction firms to fleet operators.
- Emergency Shelters:Telescoping frame mechanisms with integrated corner castings enable two-person deployment of forty-square-meter footprints within four hours. FEMA guidelines and EU Construction Products Regulation compliance determine eligibility for government tenders in seismic and cyclone zones.
- Tourist Accommodation:Glamping and eco-lodge operators specify multi-unit clusters with elevated finishes and climate control. REACH compliance expansions extend material certification obligations to insulation foam suppliers serving European hospitality markets.
- Remote Worksites:Single-unit containers with modified anchoring systems address permafrost and expansive soil constraints in northern latitudes. Site-specific engineering requirements erode speed advantages where standard foundation adaptation proves insufficient.
Temporary housing commands the largest procurement volumes; tourist accommodation is climbing the fastest.
End User:
Customer type determines contract structure, with government agencies favoring certified-supplier frameworks and private operators prioritizing deployment speed.
- Construction Firms:Capital equipment purchasers in resources sectors face stranded asset risk from project duration uncertainty. Queensland and Western Australia mining corridors show pronounced shift toward bed-night rental contracts.
- Government Agencies:Updated building resilience mandates across Southeast Asia are scaling emergency shelter procurement. BIS structural steel standards in India and FEMA wind-load requirements in the United States shape supplier qualification protocols.
- Hospitality Providers:Eco-lodge operators prioritize aesthetic customization and thermal performance thresholds. EU Green Deal alignment creates certified-supplier preference windows for manufacturers meeting energy-efficiency addendums.
- Research Stations:Antarctic and high-altitude programs specify portable units with composite framing for air-transport weight compliance. Premium pricing reflects limited qualified fabricator capacity.
Construction firms represent the largest addressable base; government agencies are expanding most quickly.
Deployment:
Geography dictates foundation engineering requirements and logistics economics, with coastal and mountain locations imposing specialized anchoring and transport constraints.
- Urban Installations:Standard ISO-compatible units deploy on prepared pads with minimal site adaptation. REACH certification burdens for European material suppliers extend qualification timelines for urban infill projects.
- Rural Setups:Dispersed geography in Indonesia's archipelago concentrates foldable container deployment where conventional construction material flows remain constrained. Single-unit containers leverage existing intermodal infrastructure.
- Coastal Areas:Cyclone-zone specifications require enhanced wind-load resistance per FEMA guidelines and updated Southeast Asian building codes. Telescoping frame mechanisms reduce labor requirements in remote coastal installations.
- Mountain Locations:Permafrost and expansive soil conditions constrain standard anchoring systems. Site-specific engineering transfers utilization risk to project owners where speed advantages erode.
Urban installations dominate current deployment volumes; coastal areas are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabricator talent clusters in Indonesia, Australia, and the United States anchor production capacity for foldable container systems. Cold-formed steel specialists concentrate near port infrastructure to optimize export logistics. Government procurement programs in Southeast Asia and mining corridor demand in Australasia drive regional deployment patterns.
Indonesia
Archipelago logistics constraints and disaster-response budgets concentrate foldable deployment at remote worksites across Java and Sulawesi. Updated building resilience mandates prioritize rapid-deployment structures in seismic and cyclone zones. Surabaya fabricators supply government tenders for coastal installations where conventional construction material flows remain interrupted.
Australia
Queensland and Western Australia mining corridors generate sustained demand for workforce rotation housing. Outcome-based rental contracts displace unit purchase models, transferring utilization risk to fleet operators. Perth-based fabricators serve resources firms contracting for bed-nights rather than capital equipment.
United States
FEMA guidelines shape supplier qualification protocols for emergency shelter procurement in seismic and hurricane zones. Cold-formed steel framing innovations compress unit weights while preserving load-bearing capacity. Texas fabricators anchor North American project pipelines serving disaster-response agencies and remote construction camps.
India
BIS structural steel standards determine eligibility for government tenders and semi-permanent housing contracts. Cold-formed steel fabricators capable of meeting wind-load requirements remain concentrated in limited manufacturing clusters. Gujarat and Maharashtra industrial zones host qualified suppliers targeting extended-duration emergency shelter programs.
Germany
REACH compliance expansions extend material certification obligations to insulation foam and coating suppliers entering the European value chain. EU Construction Products Regulation thermal performance thresholds create certified-supplier preference windows. Bavarian fabricators qualify captive coating facilities to meet energy-efficiency addendums for government tenders.
Foldable Container House Market Competitive Landscape
The competitive structure tilts toward fabrication specialists with modular expertise and fleet-scale rental operators. Cold-formed steel fabricators compete on deployment speed and certification breadth, while rental operators differentiate through utilization risk transfer. Two strategic archetypes dominate: ISO-compatible single-unit specialists and multi-unit configuration engineers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure pre-registered chemical distributor relationships for European market access.
Among Asia-Pacific fabricators, Quick Smart House Co., Ltd and Revolution Precrafted occupy positions within rapid-assembly engineering tiers, while Royal Wolf anchors fleet-scale rental operations across Australasian markets. SG Blocks exemplifies the North American modular fabrication archetype. These three companies represent distinct strategic postures: rapid-deployment engineering, outcome-based rental contracting, and project pipeline anchoring.
| Leading Market Players |
|---|
| HONOMOBO |
| SG Blocks |
| Backcountry Containers |
| Rhino Cubed |
| Expandable Container Homes |
| Royal Wolf |
| Quick Smart House Co., Ltd |
| Anderco |
| Revolution Precrafted |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators concentrated in Surabaya and Perth anchor cold-formed steel supply for foldable container systems, translating operational continuity into pricing discipline that resists volatility in corrugated steel input markets.
Pricing Analysis
Bundled deployment services separate from unbundled unit sales across procurement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification breadth—FEMA-compliant emergency shelters command premiums against basic workforce housing units. Cost compression in standard-grade segments is intensifying because steel input volatility compresses fabricator margins without long-term rolling agreements. Construction firms contracting bed-nights exhibit highest price sensitivity; research stations specifying air-transportable composite units show least.
Supply Chain Analysis
Dual-sourcing requirements from government agencies in Indonesia and Australia mandate multi-supplier qualification for steel shell and insulation foam inputs. Geographic supply concentrates in Indonesia, Australia, and the United States for fabrication; China and South Korea anchor cold-formed steel coil production. Raw material dependencies rest on corrugated steel shells, polyurethane insulation foam, and anti-corrosion coatings. Single-source vulnerability in REACH-registered chemical distributors creates procurement risk for European market access. Distribution runs through intermodal shipping infrastructure with fleet operators managing downstream rental logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foldable container house market functions as a stable compounder, with disaster resilience mandates across Southeast Asian jurisdictions delivering steady procurement pipelines independent of cyclical construction spending.
For Market Incumbents: Anticipate margin pressure from telescoping frame mechanism commoditization by securing exclusive supply partnerships with pre-registered REACH chemical distributors. Deepen backward integration into captive coating facilities to defend certification-bundled pricing tiers against emerging rapid-assembly specialists.
For New Entrants and Emerging Players: Begin with eco-lodge and glamping accommodation clusters in Queensland and Western Australia, where outcome-based rental contracts transfer utilization risk and lower capital barriers. Penetrate through modular configuration engineering partnerships with hospitality operators seeking stacked layouts without permanent foundations.
For Investors and Strategic Acquirers: Construction and resources firms with stranded camp asset exposure are the most active acquirer in this space, seeking fleet-scale rental operators to transfer balance-sheet risk. Target mid-cap fabricators with FEMA and BIS certification breadth for long-term viability. Watch for EU Green Deal thermal performance threshold acceleration as inflection indicator for certified-supplier preference windows.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Qualification | Captive coating facilities secure European government tender eligibility against chemical distributor consolidation. |
| Telescoping Frame Patent Portfolio | Deployment speed advantages differentiate rapid-response fleet specifications from hinged panel competitors. |
| Outcome-Based Rental Contract Scaling | Bed-night contracting transfers utilization risk from construction firms to fleet operators in mining corridors. |
| Multi-Unit Configuration Engineering | Stacked layouts multiply usable space for eco-lodge operators without permanent foundation requirements. |
| Air-Transport Weight Reduction | Composite framing achieves Antarctic research station specifications below standard ISO limits. |
Research Methodology
Bottom-up emergency shelter and workforce housing modeling reconciled against top-down cold-formed steel fabrication tracking forms the analytical core. Primary interviews with disaster-response procurement officers, mining camp logistics directors, cold-formed steel plant managers, and eco-lodge development leads combined with secondary validation against FEMA guideline amendments, BIS structural steel standard updates, EU Construction Products Regulation addendums, and Indonesian government tender databases. Triangulation across supply-side capacity assessments and demand-side procurement pipeline analysis ensures dimensional consistency.
Input-output matrices map cold-formed steel coil consumption through corrugated shell fabrication to deployed unit volumes across the projection horizon. Segmentation dimensions include product architecture, application context, end-user contract structure, and deployment geography. CAGRs derive from elasticity-adjusted demand projections and capacity-constrained supply trajectories. Industry-specific forecast inputs incorporate archipelago logistics cost indices and cyclone-zone wind-load specification evolution.
Several conditions sit outside the modeled scope, including abrupt REACH chemical registration moratoriums, sovereign debt constraints on Indonesian disaster-response budgets, and breakthrough composite material cost parity. Forecasts reflect documented assumptions on steel input price stabilization and certification harmonization timelines. Deviation in EU Green Deal thermal performance threshold acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Cement Roofing Sheets Market