
 North America Precision Turned Product Manufacturing Market | 2026-2036
North America Precision Turned Product Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Precision Turned Product Manufacturing Market Analytics
The US EPA's tightened machining coolant discharge rules is repositioning the competitive landscape for precision turned product manufacturers. Sorenson Engineering Inc leverages its vertical integration to absorb environmental compliance costs without outsourcing. Camcraft Inc anchors its position through deep specialization in tight-tolerance aerospace components. Cox Manufacturing Company competes by sustaining ISO-certified quality systems that satisfy defense and medical auditors.
Precision turned product manufacturing produces cylindrical components through subtractive processes such as CNC turning, Swiss machining, and multi-spindle operations, typically achieving tolerances of ±0.0005 inches for critical applications. These components serve as mechanical interfaces, fasteners, shafts, and housings across industries where dimensional repeatability directly affects system safety and performance. Automotive Components represent the largest volume segment, though margin pools concentrate in Medical Devices where lot traceability and FDA validation requirements deter commoditized competition. Aerospace Parts command premium pricing due to AS9100 certification barriers and material pedigree documentation. CNC Machining dominates technology adoption while Additive Manufacturing displaces conventional turning only in prototyping and complex geometries.
The US EPA regulates coolant discharge and air emissions from metalworking facilities, while OSHA enforces permissible exposure limits for metalworking fluids. The FDA's Quality System Regulation shapes medical device component standards, and the FAA's production approval requirements govern aerospace supplier qualification. Mexico's environmental enforcement through SEMARNAT and Canada's Environment and Climate Change Canada add cross-border compliance layers. Stakeholders must monitor how evolving PFAS restrictions in metalworking fluids and potential US reshoring incentives reshape supplier geography and capital allocation priorities.
Market Dynamics
The US EPA's tightened machining coolant discharge rules are compressing margins for small-batch operators while rewarding scaled manufacturers with captive wastewater treatment infrastructure. This regulatory wedge is accelerating consolidation across Michigan's automotive supplier corridor and California's medical device cluster.
Growth Catalysts
- Aerospace Fastener Demand:Mexican aerospace OEMs are scaling titanium fastener orders for narrowbody assembly programs. AS9100-certified suppliers capture recurring multi-year contracts with material pedigree documentation requirements.
- Medical Device Cluster Expansion:FDA's Quality System Regulation mandates lot traceability for implantable components. California's precision machining ecosystem benefits from proximity to FDA-designated device innovators requiring validated production lines.
- Reshoring Policy Incentives:US domestic content requirements in defense procurement are redirecting fastener and shaft orders from Asian suppliers to ISO-certified North American facilities with ITAR compliance.
Market Restraints
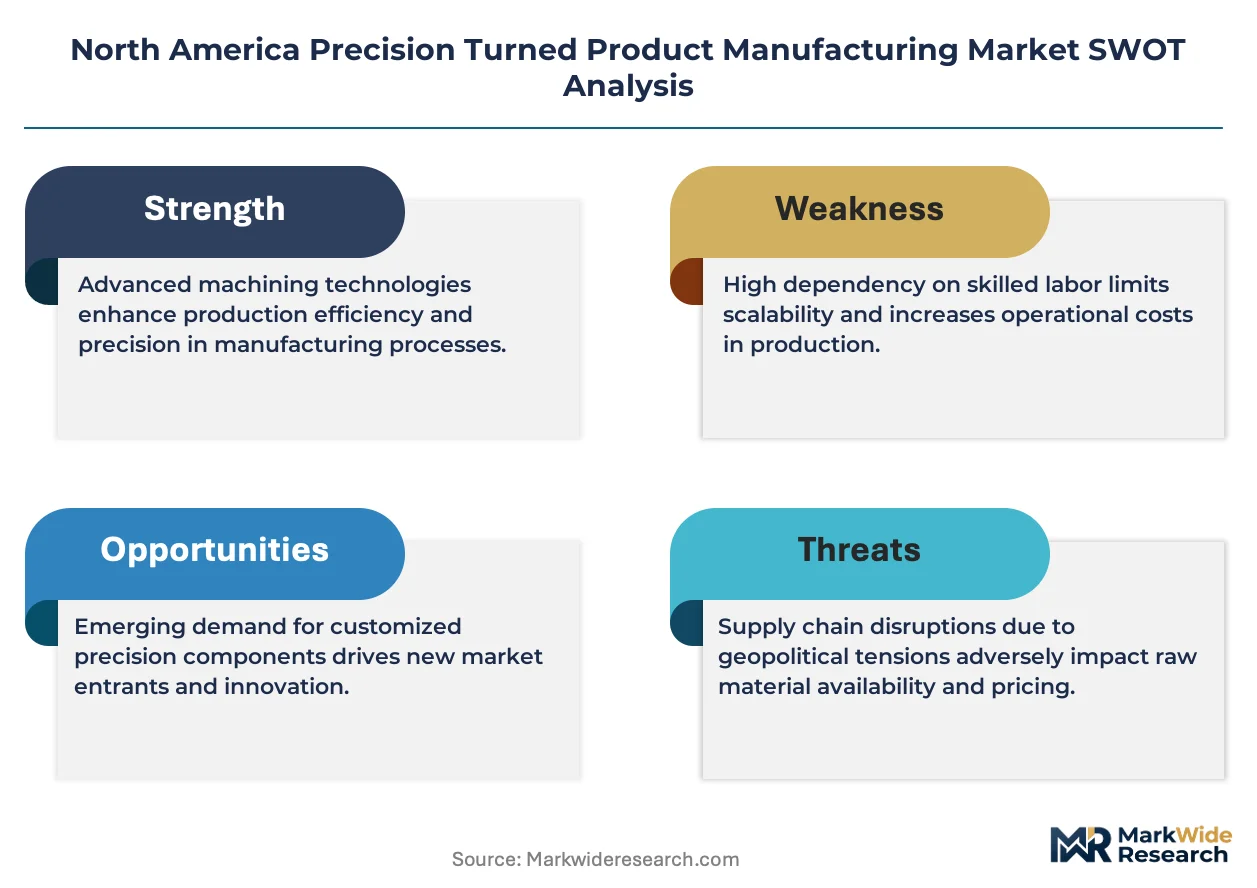
- Titanium Input Volatility:Sponge titanium prices fluctuate with aerospace build rates, compressing margins for long-term fixed-price contracts in fastener manufacturing.
- Coolant Chemistry Substitution Costs:Pending PFAS restrictions in metalworking fluids force reformulation of established coolant systems, raising R&D burdens for mid-cap operators without chemical engineering depth.
- Labor Concentration Risk:Swiss machinist expertise concentrates in upper Midwest states, creating wage pressure and turnover vulnerability for facilities outside established training pipeline regions.
Strategic Opportunities
- Mexico Aerospace Corridor:Querétaro and Baja California assembly plants lack sufficient local fastener supply, creating white space for AS9100-certified greenfield investments with SEMARNAT environmental pre-approval.
- Additive-Conventional Hybrid Workflows:Near-net-shape additive preforms finished by CNC turning reduce titanium waste in aerospace structural brackets. Early adopters in defense applications secure sole-source positions.
- Canada Medical Device Export Hub:Health Canada's alignment with FDA quality standards enables dual-registered facilities to serve US demand while accessing European markets through MDR equivalence pathways.
Industry Challenges
- Multi-Axis Programming Talent Scarcity:Complex Swiss machining operations require CAM proficiency that outpaces vocational training output in Michigan and Ohio manufacturing regions.
- AS9100 Certification Timelines:Aerospace supplier qualification cycles extend 18-24 months, freezing out capital-constrained operators from defense and commercial aviation contract pools.
- Legacy ERP Integration Friction:Medical device lot traceability requirements clash with decades-old shop floor data systems, forcing expensive MES overlays or full replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Precision Turned Product Manufacturing Market |
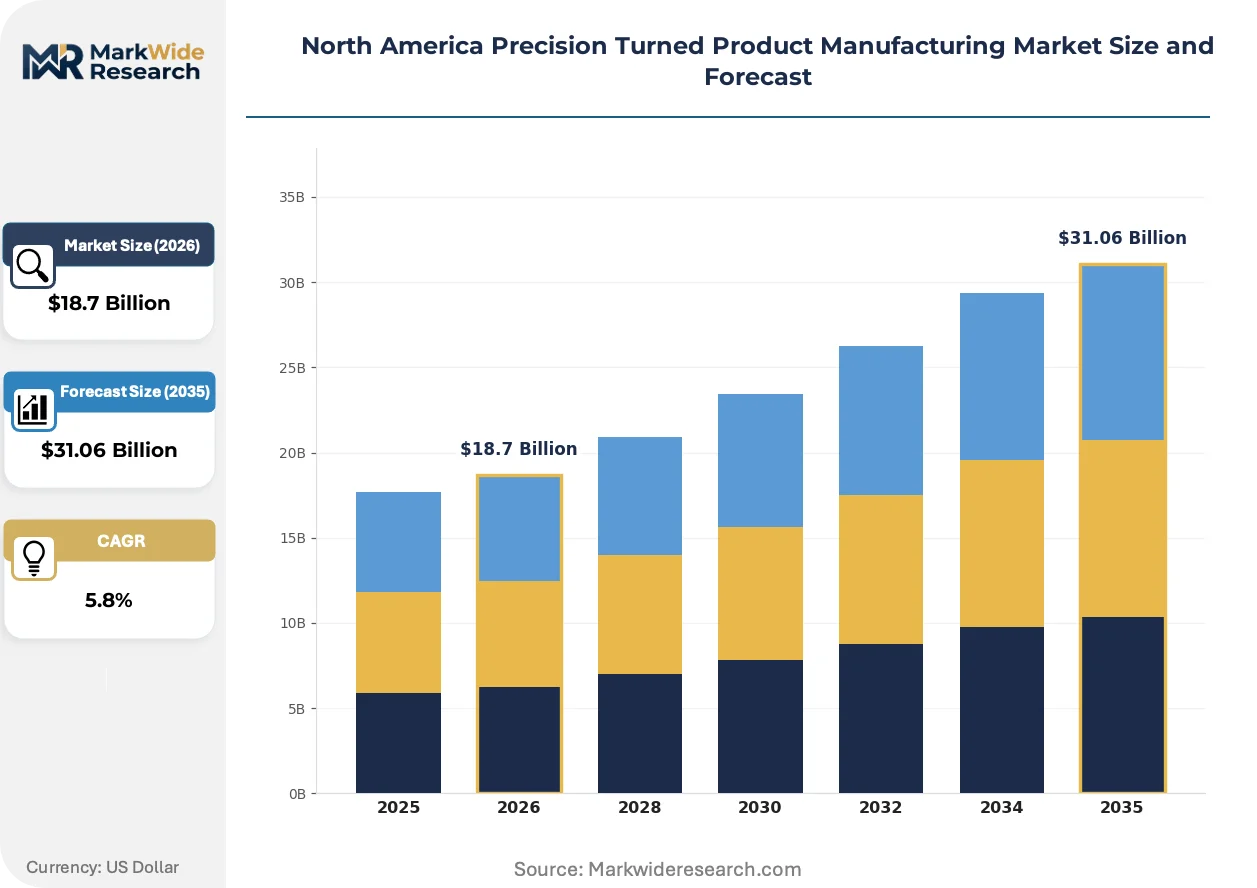
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Components, Aerospace Parts, Medical Devices, Electrical Connectors End User: Automotive OEMs, Aerospace Manufacturers, Medical Equipment Firms, Electronics Industry Technology: CNC Machining, Laser Cutting, Additive Manufacturing, Conventional Turning Material: Aluminum Alloys, Stainless Steel, Titanium, Plastic Compounds |
| Companies Covered | Sorenson Engineering Inc, Nook Industries LLC, Premier Farnell Corp, Camcraft Inc, Creed-Monarch Inc, Melling Tool Co, Cox Manufacturing Company, M & W Industries Inc, Kamatics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Precision Turned Product Manufacturing Market Evolving Landscape
Digital thread integration across design-to-inspection workflows is compressing first-article approval cycles. This connectivity shift is redrawing competitive advantage around data infrastructure rather than machine count alone.
Multi-spindle Swiss machining platforms with live tooling and sub-spindle capabilities are expanding into complex medical device components previously requiring milling centers. Orthopedic implant manufacturers in Warsaw, Indiana and Memphis, Tennessee are adopting these platforms to consolidate operations and reduce work-in-process inventory. The technology is expanding into lot sizes below 500 units, eroding the traditional volume threshold that separated turning from milling economics.
OSHA's pending reduction in permissible exposure limits for metalworking fluids is forcing mist collection upgrades across US facilities. Small-batch operators in Ohio and Pennsylvania face disproportionate capital burdens relative to revenue base, triggering contract manufacturing consolidation. Medical device subcontractors with existing cleanroom infrastructure absorb these costs more readily than general industrial shops.
Buyers in defense and aerospace are consolidating supplier bases around vertically integrated partners capable of heat treatment, passivation, and NDT in-house. Tier-1 OEMs in Connecticut and Washington state are trimming approved vendor lists from dozens to handfuls, awarding multi-year agreements to facilities with captive special process capabilities. This concentration is most visible in titanium fastener supply chains where material pedigree and process documentation requirements exceed fragmented vendor capacity.
North America Precision Turned Product Manufacturing Market Segmentation
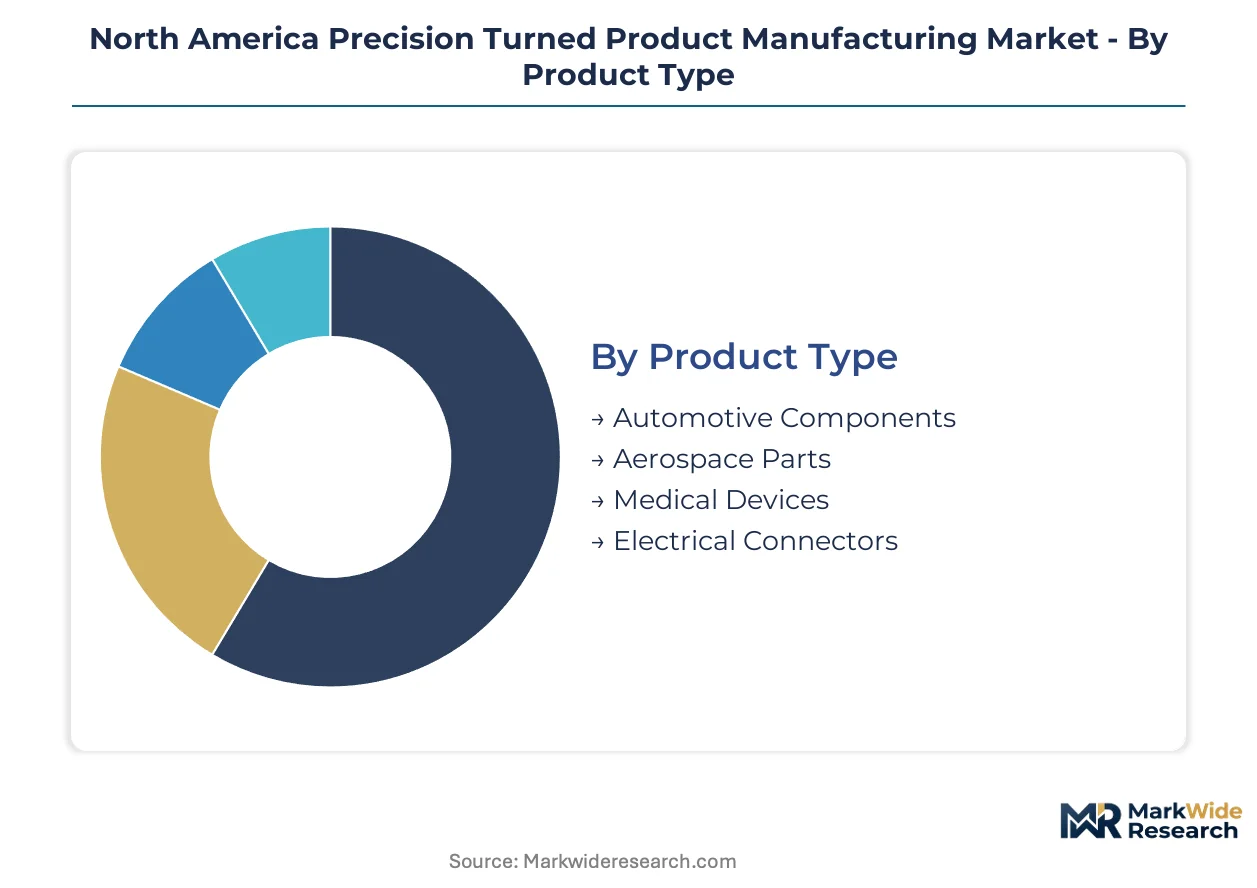
Segmentation in precision turned product manufacturing reveals how buyer priorities diverge across regulatory environments, certification barriers, and supply chain proximity requirements. Understanding these splits exposes where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Buyers select product categories based on certification burden tolerance and lot traceability requirements rather than unit cost alone.
- Automotive Components:High-volume shafts, fasteners, and valve train components dominate unit economics. Michigan's supplier corridor absorbs the bulk of demand as EV powertrain redesigns refresh component specifications.
- Aerospace Parts:Titanium fasteners and structural brackets require AS9100 certification and material pedigree documentation. Mexican narrowbody assembly programs are scaling orders for certified suppliers with captive heat treatment.
- Medical Devices:Implantable-grade components demand FDA lot traceability and validated production lines. Warsaw, Indiana and Memphis, Tennessee clusters concentrate orthopedic machining demand.
- Electrical Connectors:Precision-machined contacts and housings serve datacenter and EV charging infrastructure. California and Texas electronics corridors drive specification evolution.
Automotive Components leads on scale; Medical Devices leads on momentum.
End User:
End user selection hinges on procurement consolidation patterns and approved vendor list reduction trends.
- Automotive OEMs:Tier-1 suppliers face relentless annual cost-down targets while maintaining PPAP documentation. Detroit Three electrification programs are respecifying thermal management components.
- Aerospace Manufacturers:Boeing and Airbus tier-1s are trimming supplier bases from dozens to handfuls. Connecticut and Washington state OEMs award multi-year agreements to vertically integrated partners.
- Medical Equipment Firms:Device innovators in California's FDA-designated clusters require validated production lines with MES-enabled lot traceability.
- Electronics Industry:Datacenter and telecom equipment makers prioritize connector precision over material pedigree, opening competition to general industrial shops.
Automotive OEMs command the largest contract volumes; Aerospace Manufacturers are climbing the fastest on reshoring tailwinds.
Technology:
Technology adoption tracks capital intensity thresholds and programming talent availability across regional labor markets.
- CNC Machining:Multi-axis turning centers with live tooling dominate production economics. Swiss machining platforms with sub-spindle capabilities are eroding traditional volume thresholds that separated turning from milling.
- Laser Cutting:Tube and sheet pre-processing for turned component blanks serves high-mix, low-volume job shops. Ohio and Pennsylvania operators deploy this for rapid prototype turnaround.
- Additive Manufacturing:Near-net-shape titanium preforms finished by CNC turning reduce aerospace material waste. Defense applications are securing sole-source positions for hybrid workflows.
- Conventional Turning:Manual and cam-driven equipment persists in legacy automotive supply agreements and developing Mexico operations. Labor cost arbitrage sustains this tier.
CNC Machining anchors current output; Additive Manufacturing is gaining share fastest on titanium waste reduction economics.
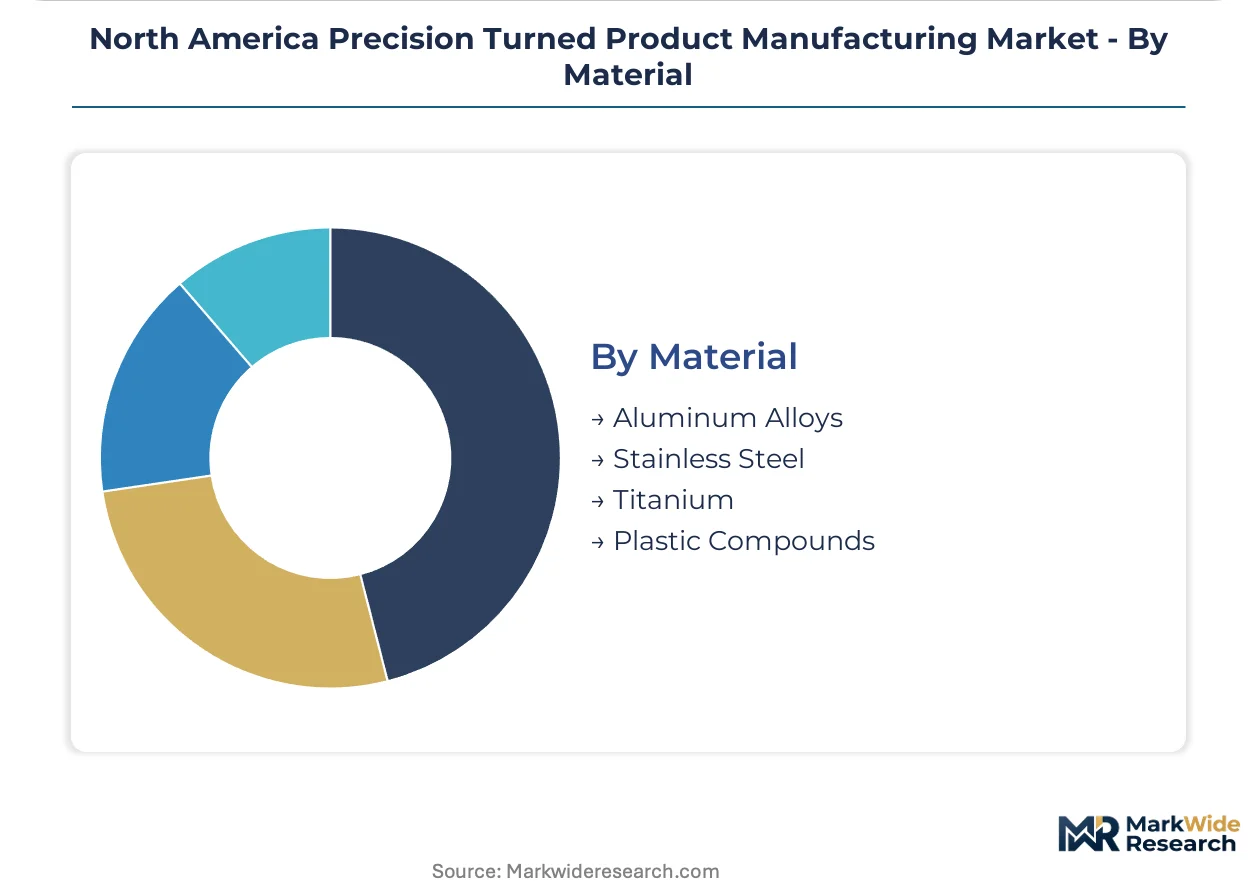
Material:
Material selection reflects end-use performance requirements and supply chain concentration risks.
- Aluminum Alloys:Lightweight housings and thermal management components serve EV and electronics applications. Michigan and California machining clusters process the highest volumes.
- Stainless Steel:Corrosion-resistant fasteners and surgical instruments demand 300-series and 17-4 PH grades. Medical device subcontractors in Warsaw, Indiana maintain dedicated stainless production lines.
- Titanium:Aerospace fasteners and implantable medical components require sponge titanium with full lot traceability. Price volatility with aerospace build rates compresses margins on fixed-price contracts.
- Plastic Compounds:PEEK and other high-performance polymers serve electrical insulation and lightweight structural applications. Electronics industry demand is expanding fastest.
Aluminum Alloys generates the highest throughput; Titanium captures the steepest expansion trajectory on Mexican aerospace scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision turned product manufacturing in North America traces its lineage to Detroit's automotive assembly revolution and Connecticut's aerospace subcontractor networks established during World War II. These historical foundations created specialized labor pools and supplier ecosystems that persist in today's regional concentrations. The analysis examines three national markets where regulatory frameworks and industrial clusters shape competitive positioning.
United States
Michigan's automotive supplier corridor generates high-volume demand for precision shafts and valve train components as EV powertrain redesigns refresh specifications. The EPA's tightened machining coolant discharge rules are compressing margins for small-batch operators while rewarding scaled manufacturers with captive wastewater treatment infrastructure. California's medical device cluster in the San Francisco Bay Area concentrates demand for FDA-validated implantable components with full lot traceability.
Canada
Health Canada's alignment with FDA quality standards enables dual-registered facilities to serve US medical device demand while accessing European markets through MDR equivalence pathways. Environment and Climate Change Canada adds cross-border compliance layers for metalworking fluid discharge that mirror US EPA stringency. Ontario's manufacturing belt around Toronto and Hamilton hosts precision machining subcontractors serving aerospace tier-1s with AS9100 certification.
Mexico
Querétaro and Baja California aerospace assembly plants are scaling titanium fastener orders for narrowbody programs without sufficient local certified supply. SEMARNAT environmental enforcement through pre-approval processes creates barriers for greenfield entrants lacking established compliance relationships. The Bajío Region's industrial parks attract foreign investment seeking proximity to US automotive OEMs with NAFTA-originating content requirements.
North America Precision Turned Product Manufacturing Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive special process capabilities. Tier-1 OEMs in defense and aerospace are consolidating supplier bases from dozens to handfuls, awarding multi-year agreements to facilities with in-house heat treatment, passivation, and NDT. Three archetypes dominate: AS9100-certified aerospace specialists, FDA-validated medical device subcontractors, and high-volume automotive suppliers with PPAP documentation systems. Competitive moves center on M&A absorption of distressed small-batch operators and strategic partnerships for additive-conventional hybrid workflows.
Among US-based fabricators, Sorenson Engineering Inc exemplifies the vertically integrated archetype with capabilities spanning environmental compliance absorption. Camcraft Inc anchors the aerospace specialist tier through tight-tolerance component positioning. Cox Manufacturing Company occupies a position within the quality-system-certified segment serving defense and medical auditors. These three represent how certification depth and captive process control separate sustainable competitors from commoditized pressure.
| Leading Market Players |
|---|
| Sorenson Engineering Inc |
| Nook Industries LLC |
| Premier Farnell Corp |
| Camcraft Inc |
| Creed-Monarch Inc |
| Melling Tool Co |
| Cox Manufacturing Company |
| M & W Industries Inc |
| Kamatics Corporation |
| Others |
Value Network & Pricing Analysis
Sponge titanium price volatility cascades through North American precision turned product manufacturing, compressing margins on fixed-price aerospace contracts while rewarding operators with captive material hedging programs. This input cost instability stratifies pricing power across certification tiers, with AS9100-certified suppliers commanding premium terms that commodity-grade operators cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace specialists from ISO-certified general industrial shops and uncertified commodity producers. Price differentiation hinges on certification grade and volume scale, with medical device lot traceability commanding the steepest premiums. Cost compression in the economy tier is intensifying because small-batch operators lack captive wastewater treatment to absorb EPA compliance costs. Automotive OEMs exhibit the highest price sensitivity, while defense procurement officers prioritize ITAR compliance over unit cost.
Supply Chain Analysis
Freight cost premiums on titanium sponge shipments from Japan and Kazakhstan elevate landed costs for US fastener manufacturers without long-term offtake agreements. Supply concentration centers on the United States, Mexico, and Canada, with raw material flows drawing from sponge producers in Japan, Russia, and China. Single-source vulnerability in Swiss machining equipment creates procurement risk for expanding multi-spindle platforms. Distribution runs through tier-1 OEM approved vendor lists that consolidate annually, favoring vertically integrated partners with in-house heat treatment and NDT capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American precision turned product manufacturing functions as a stable compounder, with reshoring tailwinds in defense procurement providing durable demand visibility across multi-year contract cycles.
For Market Incumbents: Hedge titanium input exposure through long-term sponge offtake agreements with Japanese producers. Acquire distressed small-batch operators in Michigan and Ohio facing EPA compliance cost burdens, consolidating their customer relationships onto your captive wastewater infrastructure. Additive-conventional hybrid workflows represent the priority capability gap to close before defense primes lock in sole-source positions.
For New Entrants and Emerging Players: Launch via greenfield AS9100-certified facilities in Querétaro or Baja California, positioning for Mexican aerospace OEM fastener demand that outpaces local certified supply. Target the orthopedic implant subcontractor tier in Warsaw, Indiana and Memphis, Tennessee, where FDA-validated production line requirements deter general industrial competition. Pursue strategic equipment partnerships with Swiss machine tool distributors to secure programming talent pipelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where environmental compliance costs exceed 8% of revenue for small-batch operators lacking captive treatment infrastructure. The five-to-ten-year viability window favors mid-cap specialists with backward integration into heat treatment and passivation. Target acquisition archetype: AS9100-certified facilities with underutilized capacity and established SEMARNAT relationships in Mexico. Monitor PFAS restriction timelines as the inflection signal for coolant chemistry substitution cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks multi-year aerospace contracts with Boeing and Airbus tier-1 suppliers in Connecticut and Washington state. |
| Captive Heat Treatment Capacity | Enables material pedigree documentation that satisfies defense procurement lot traceability requirements. |
| Additive-Conventional Hybrid Workflow | Reduces titanium waste in aerospace structural brackets, securing sole-source positions with defense primes. |
| SEMARNAT Pre-Approval Greenfield | Accelerates Mexican market entry ahead of competitors navigating environmental compliance timelines. |
| MES-Enabled Lot Traceability | Satisfies FDA Quality System Regulation mandates for implantable medical device components. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with precision machining plant managers, aerospace tier-1 procurement leads, medical device quality directors, and Swiss machine tool distributors with secondary validation. Secondary sources included US EPA enforcement databases, FDA 483 inspection records, SEMARNAT permitting disclosures, and aerospace build rate forecasts from OEM production schedules. Bottom-up facility capacity estimates and top-down end-use demand projections were triangulated to anchor market sizing.
Historical reference periods established baseline capacity utilization and pricing trajectories that inform projections across the analysis window. Segmentation modeling tracked product type, end user industry, technology platform, and material grade dimensions. CAGRs were derived from regression analysis against aerospace build rates, automotive production volumes, and medical device approval pipelines. Forecast inputs included titanium sponge price indices, Swiss machining equipment order backlogs, and EPA regulatory enforcement intensity metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction implementation or aerospace program delays. Stakeholders should weight assumptions against their own operating context, particularly regarding environmental compliance cost absorption and certification timeline contingencies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Industrial Spindles Market