
 Asphalt Market | 2026-2036
Asphalt Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Market Intelligence
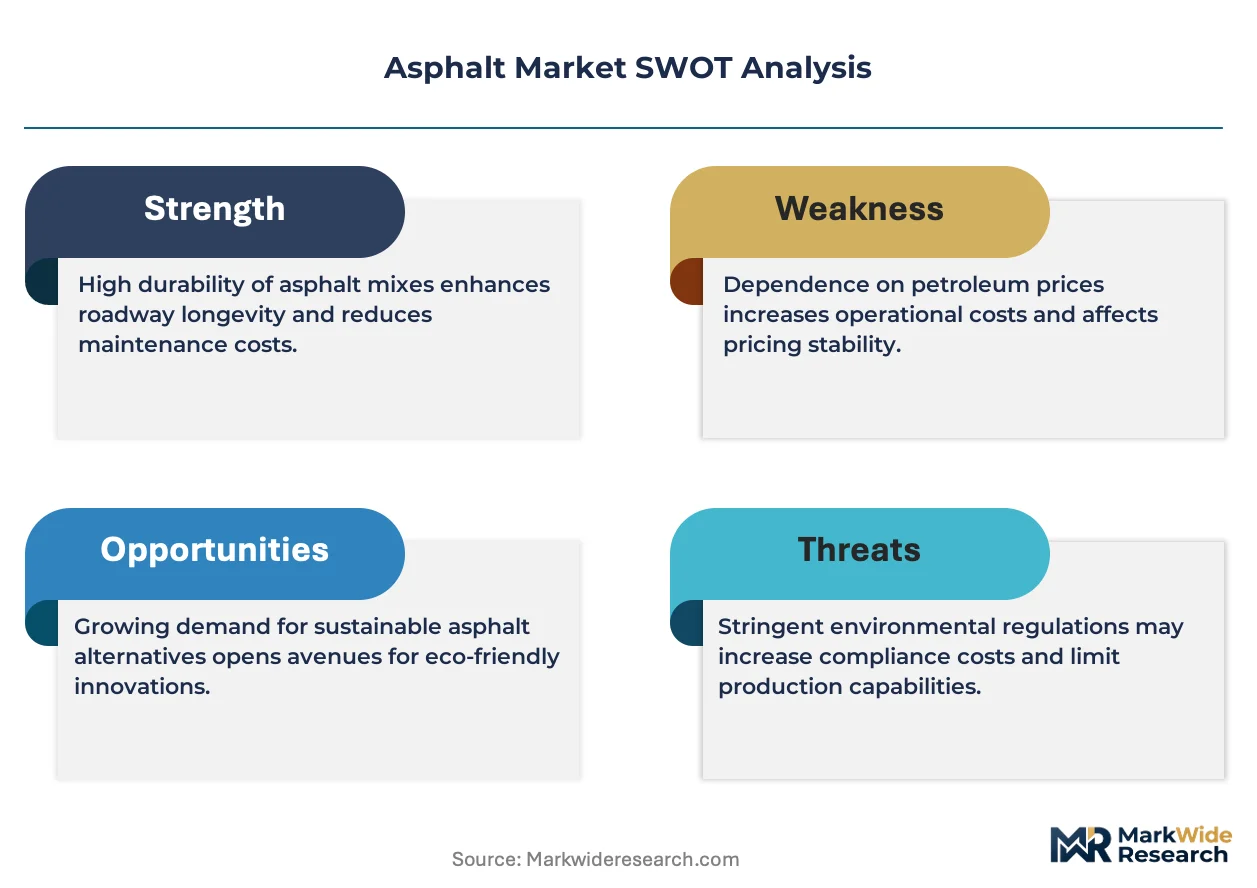
Performance-grade binder specifications is collapsing the gap between commodity asphalt and engineered polymer-modified systems. Hatch Asphalt leverages its vertical integration across refining and terminal operations to secure feedstock consistency. Rose Paving differentiates through specialized airport runway resurfacing contracts that demand Superpave compliance. Alpha Paving Industries dominates municipal maintenance segments with flexible emulsion formulations.
Asphalt comprises bituminous binders derived from petroleum distillation residues, typically graded by penetration value, softening point, and viscosity at 135°C, serving primarily as the waterproofing and load-bearing matrix in paved surfaces and roofing membranes. Polymer Modified and Emulsified types command expanding share as agencies specify rut resistance and cold-mix applicability for sustainable construction cycles. Road Construction anchors volume demand while Waterproofing Membranes generates premium margin pools in commercial building envelopes.
The U.S. Federal Highway Administration enforces Superpave performance grading under AASHTO standards, while the European Committee for Standardization mandates CE-marked bitumen under EN 12591 and EN 14023 for modified grades. China's Ministry of Transport issues JTJ specifications that provincial bidders must satisfy for national trunk highway awards. Stakeholders must monitor how evolving carbon-intensity thresholds for construction materials reshape specification criteria and supplier qualification protocols.
Market Dynamics
Performance-grade binder specifications are collapsing the technical gap between commodity asphalt and engineered polymer-modified systems, forcing contractors to retool specifications and suppliers to recalibrate feedstock sourcing strategies.
Growth Catalysts
- INVEST Act compliance:The U.S. Federal Highway Administration's performance criteria mandate Superpave grading for federal-aid highway projects, accelerating specification upgrades across state DOT portfolios.
- China's expressway expansion:Provincial infrastructure budgets under the Ministry of Transport's JTJ specifications prioritize high-grade paving for national trunk highway networks, concentrating demand for polymer-modified binders.
- CE marking adoption:Europe's EN 14023 standard for modified bitumen grades is tightening performance thresholds, pushing contractors toward certified polymer systems for cross-border infrastructure awards.
Market Restraints
- Crude residue volatility:Vacuum residue feedstock costs track crude differentials unpredictably, compressing blending margins for refiners without captive upstream supply.
- Specialized polymer concentration:SBS and SBR modifier supply clusters in Northeast Asian petrochemical corridors, exposing Western blenders to shipping cost spikes and currency exposure.
- Warm-mix technical ceiling:Foaming and chemical additive approaches to temperature reduction face performance degradation thresholds below 100°C that limit high-stress applications.
Strategic Opportunities
- India's NHAI expansion:The National Highways Authority of India's Bharatmala program under BIS grading protocols creates specification upgrade pathways for polymer-modified penetration grades.
- Rooftop solar integration:Waterproofing membrane specifications for photovoltaic mounting systems are converging with cool-roof reflectivity standards, opening premium formulation segments.
- Recycled asphalt pavement mandates:California's Caltrans and Texas DOT specifications for RAP content percentages are creating demand for rejuvenator additive technologies that restore binder performance.
Industry Challenges
- Superpave technician scarcity:AASHTO-certified binder technicians and mix design engineers command wage premiums that strain regional contractor labor models.
- Terminal storage reconfiguration:Polymer-modified asphalt requires heated storage with agitation systems, forcing capital deployment at distribution terminals historically configured for straight-run binders.
- Multi-jurisdictional certification lag:Contractors bidding across state lines face non-reciprocal approval timelines for proprietary additive packages, compressing project mobilization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Market |
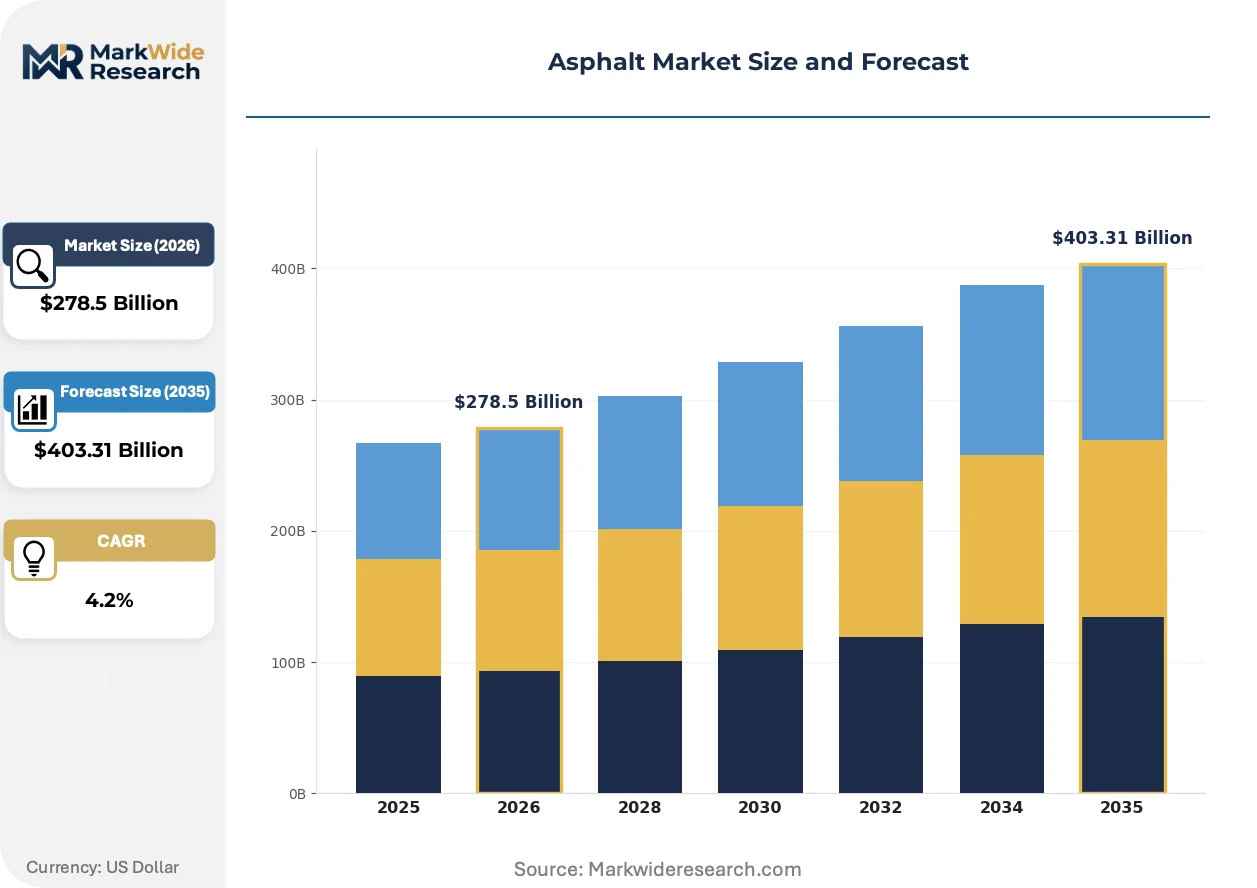
| Market Size in 2026 | $278.5 Billion |
| Market Size in 2035 | $403.31 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cutback, Emulsified, Polymer Modified, Fluxed, Hard Application: Road Construction, Roofing, Hydraulic Engineering, Airport Runways, Waterproofing Membranes End User: Civil Engineering Firms, Construction Contractors, Road Maintenance Companies, Municipal Authorities, Infrastructure Developers Form: Liquid, Solid, Semi-Solid, Granulated, Powdered |
| Companies Covered | Hatch Asphalt, A&A Paving, Rose Paving, Stasi Brothers Asphalt Corp., Ruston Paving Co., Rabine Group, Alpha Paving Industries, M&D Blacktop Co., All County Paving, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Market Strategic Shifts & Innovations
Bio-based binder alternatives, intelligent compaction systems, and circular material flows are reconfiguring how asphalt mixtures are specified, produced, and validated across transportation agencies.
Rejuvenator chemistry is fragmenting the reclaimed asphalt pavement supply chain. Chemical recycling technologies using bio-oils and engineered surfactants restore aged binder rheology to near-virgin performance grades. State DOTs in the U.S. Midwest are piloting 50% RAP content specifications that were technically unfeasible five years ago. This technology is fragmenting the historical virgin-RAP substitution ratio, enabling secondary material streams to compete for premium highway contracts.
REACH authorization procedures for polycyclic aromatic hydrocarbons in paving-grade bitumen are tightening across EU member states. The European Chemicals Agency's sunset date protocols for PAH content above 0.1% are forcing refiners to reconfigure vacuum distillation cut points and hydrotreating severity. Modified binder producers in Germany and the Netherlands are accelerating low-PAH formulation development to secure CE marking continuity for 2026 compliance windows.
Agency procurement for pavement performance is migrating from unit-price contracts to warranty-based agreements with ride-quality retention clauses. State DOTs in Australia and several U.S. jurisdictions now hold contractors liable for International Roughness Index degradation over 5-7 year performance periods. This transfer of lifecycle risk is compressing contractor bidding margins while expanding demand for predictive pavement management systems and long-term binder durability testing protocols.
Asphalt Market Segmentation
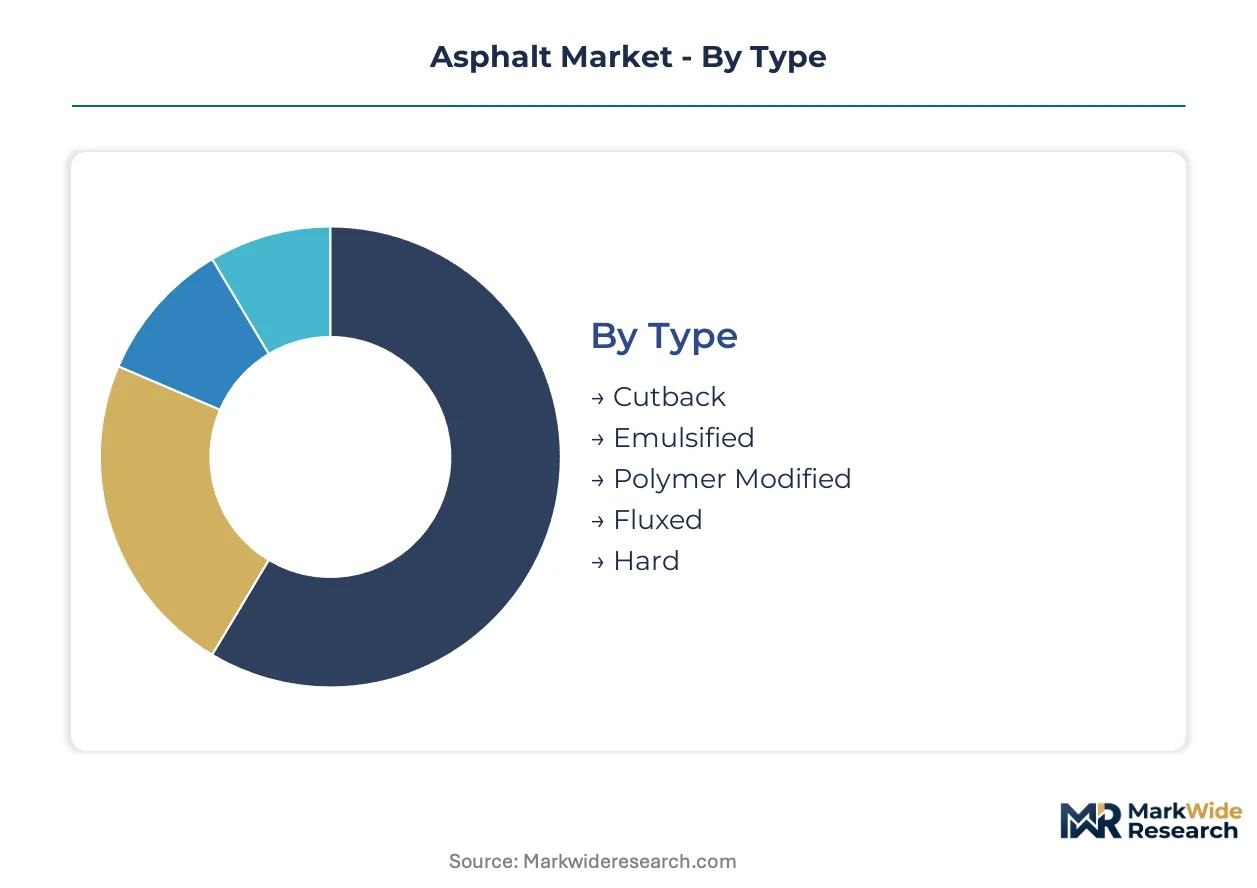
Segmentation in the asphalt market reveals how specification-grade requirements fragment procurement channels. Contractors, refiners, and terminal operators calibrate inventory and blending investments against end-use performance thresholds rather than commodity volume alone.
Type:
Channel mix varies sharply by binder chemistry—polymer-modified grades flow through specialized terminals with heated agitation, while cutback and emulsified types reach job sites via bulk liquid distributors.
- Polymer Modified:SBS and SBR elastomer modification elevates high-temperature rutting resistance and low-temperature thermal cracking performance. China's Ministry of Transport JTJ specifications for national expressway networks concentrate demand for PMB grades in provincial trunk highway awards.
- Emulsified:Water-based dispersion systems enable cold-mix construction without elevated temperatures, supporting sustainable paving cycles and reduced energy consumption. Caltrans and Texas DOT specifications for recycled asphalt pavement content are accelerating emulsion demand for rejuvenator-compatible surface treatments.
- Cutback:Solvent-diluted binders for remote cold-weather applications where heating infrastructure is unavailable.
- Fluxed:Blended with diluent oils to reduce viscosity for specific coating and industrial applications.
- Hard:High-penetration grades for roofing membranes and waterproofing where rigidity and thermal stability dominate.
By volume, emulsified leads in maintenance and rural applications. By growth pace, polymer modified is ahead on specification upgrades.
Application:
Cost tier stratification separates high-volume roadwork from premium-margin waterproofing, with airport runway contracts commanding specialized Superpave compliance premiums.
- Road Construction:Load-bearing pavement matrices for highways, urban corridors, and municipal streets graded by penetration value and viscosity at 135°C. India's NHAI Bharatmala program under BIS protocols is expanding specification-grade penetration for polymer-modified binders.
- Waterproofing Membranes:Bituminous barriers for commercial building envelopes, bridge decks, and below-grade structures requiring thermal stability and elongation resistance. Rooftop solar photovoltaic mounting systems are converging specifications with cool-roof reflectivity standards, opening premium formulation segments.
- Roofing:Shingle saturation and built-up membrane applications with distinct softening point requirements.
- Hydraulic Engineering:Canal linings, dam facings, and marine structures demanding water immersion resistance.
- Airport Runways:Superpave-compliant surfaces with stringent friction and fuel resistance specifications.
Road construction dominates tonnage. Waterproofing membranes claim the steepest expansion trajectory on building envelope performance premiums.
End User:
Customer type determines contract structure—municipal authorities issue unit-price awards while infrastructure developers negotiate warranty-based performance agreements with ride-quality retention clauses.
- Construction Contractors:Private and public works generalists bidding federal-aid highway projects under FHWA INVEST Act criteria. These firms face AASHTO-certified technician scarcity that strains regional labor models and wage structures.
- Municipal Authorities:City and county maintenance departments with cyclical resurfacing budgets and emulsion-based preventive maintenance preferences. California and Texas RAP content mandates are reshaping their procurement toward rejuvenator-compatible formulations.
- Civil Engineering Firms:Design-build and EPC contractors with pavement management system integration capabilities.
- Road Maintenance Companies:Specialized resurfacing and seal-coat operators with seasonal demand patterns.
- Infrastructure Developers:Long-term concession holders and public-private partnership entities with lifecycle cost accountability.
Construction contractors handle the largest project volumes. Infrastructure developers are expanding most quickly on warranty-based risk transfer models.
Form:
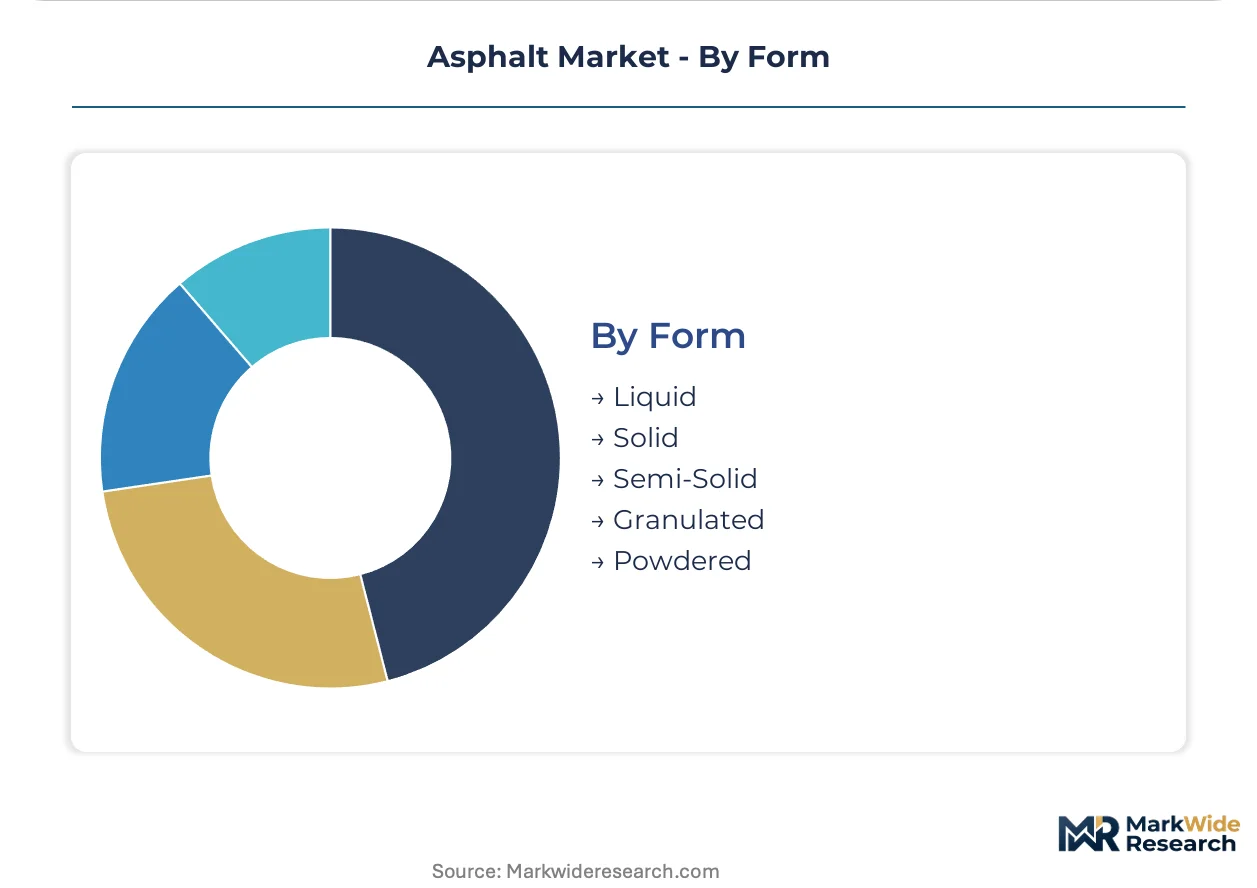
Supply concentration in liquid bulk terminals contrasts with solid and granulated formats that enable extended storage and remote logistics.
- Liquid:Dominant format for hot-mix asphalt plants and terminal distribution, requiring heated storage and transport. Vacuum residue feedstock volatility compresses blending margins for refiners without captive upstream supply.
- Solid:Block and cake forms for industrial roofing and export markets where heated infrastructure is absent.
- Semi-Solid:Mastic and patching compounds with filler reinforcement for maintenance applications.
- Granulated:Free-flowing particles for controlled blending in modified binder production and bagged export.
- Powdered:Micronized bitumen for specialty coatings and polymer compounding with precise dosing requirements.
Liquid form leads by volume through hot-mix infrastructure. Granulated is gaining share fastest on modified binder plant automation and export logistics flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery capacity for vacuum residue feedstock clusters in the United States, China, Germany, India, and Saudi Arabia. These five countries process the majority of bituminous binders for domestic road construction and export markets.
United States
The Federal Highway Administration's INVEST Act criteria mandate Superpave performance grading for federal-aid highway projects. State DOTs in Texas and California are expanding recycled asphalt pavement content specifications. Gulf Coast refineries supply straight-run binders to domestic terminals while Midwest contractors face AASHTO-certified technician shortages.
China
Provincial infrastructure budgets under the Ministry of Transport's JTJ specifications prioritize polymer-modified binders for national expressway networks. Sinopec and PetroChina refineries dominate vacuum residue supply to coastal terminals. The Yangtze River Delta region concentrates demand for high-grade paving materials in Shanghai-Nanjing corridor projects.
Germany
The European Committee for Standardization enforces CE marking under EN 12591 and EN 14023 for modified bitumen grades. REACH authorization procedures for polycyclic aromatic hydrocarbons are forcing refiners to reconfigure vacuum distillation cut points. The Rhine-Ruhr industrial cluster hosts specialized terminals with heated agitation systems for polymer-modified storage.
India
The National Highways Authority of India's Bharatmala program creates specification upgrade pathways for polymer-modified penetration grades. Bureau of Indian Standards protocols govern binder quality for trunk highway awards. Gujarat refineries supply bitumen to western state contractors while Maharashtra's Mumbai-Pune expressway expansion drives premium-grade demand.
Saudi Arabia
Saudi Aramco refineries export vacuum residue to Asian and African markets while domestic demand concentrates on airport runway and highway projects. The Ministry of Transport issues performance specifications for national infrastructure awards. The Eastern Province hosts refining complexes that supply both local construction and Red Sea export terminals.
Asphalt Market Key Industry Players
Concentration sits with vertically integrated refiners and specialized paving contractors rather than diversified construction conglomerates. The market structure splits between captive refinery-to-terminal operators and independent contractors bidding public works. Two strategic archetypes dominate: upstream-integrated suppliers controlling feedstock consistency, and application specialists capturing premium segments through certification compliance. Competitive moves center on terminal storage reconfiguration for polymer-modified grades and cross-state certification reciprocity negotiations.
Among North American contractors, Hatch Asphalt exemplifies upstream-integrated positioning through refining and terminal control, while Rose Paving occupies a position in specialized airport runway resurfacing where Superpave compliance commands premium pricing. Alpha Paving Industries represents the municipal maintenance archetype with flexible emulsion formulations for cyclical resurfacing budgets.
| Leading Market Players |
|---|
| Hatch Asphalt |
| A&A Paving |
| Rose Paving |
| Stasi Brothers Asphalt Corp. |
| Ruston Paving Co. |
| Rabine Group |
| Alpha Paving Industries |
| M&D Blacktop Co. |
| All County Paving |
| Others |
Cost & Logistics Intelligence
Rejuvenator additive substitution for virgin bitumen in high-RAP mixes is redrawing feedstock procurement maps and compressing the premium that polymer-modified grades command over straight-run binders. Contractors blending 50% reclaimed asphalt pavement under Caltrans and Texas DOT specifications now source chemical recycling agents from bio-oil refiners, bypassing traditional vacuum residue markets.
Pricing Analysis
The U.S. Federal Highway Administration's INVEST Act criteria dictate the pricing tier structure across federal-aid highway awards. Three-tier pricing separates Superpave performance-graded polymer systems from standard penetration-grade binders and economy emulsion formulations. Price differentiation rests on AASHTO certification level and volume scale, with certified technicians commanding wage premiums that filter into project bids. Cost compression in standard-grade tiers is intensifying because Gulf Coast refiners face vacuum residue volatility without captive upstream supply. Municipal authorities exhibit highest price sensitivity due to cyclical maintenance budgets, while airport runway contractors absorb premium pricing for Superpave compliance.
Supply Chain Analysis
Northeast Asian petrochemical corridors anchor SBS and SBR modifier supply, exposing Western blenders to shipping cost spikes and currency exposure. Vacuum residue feedstock draws from U.S. Gulf Coast, China, and Saudi Arabian refining complexes, while polymer modifiers hinge on South Korean and Japanese petrochemical output. Single-source vulnerability concentrates in heated terminal storage with agitation systems, where retrofit capital requirements lock out smaller distributors. Distribution runs through liquid bulk terminals to hot-mix plants, with granulated formats gaining share for remote logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of AASHTO-certified binder technicians and mix design engineers constrains contractor expansion and inflates labor costs across regional markets. This capability gap rewards firms that secure certification pipelines or automate specification compliance.
For Market Incumbents: Shield terminal market share by retrofitting heated agitation storage for polymer-modified grades before regional competitors secure JTJ-specification contracts. Backward integration into vacuum residue supply insulates blending margins from crude differential volatility. Cross-state certification reciprocity negotiations compress mobilization windows against emerging bidders. For New Entrants and Emerging Players: Lead with rejuvenator-compatible emulsion formulations targeting California and Texas DOT recycled asphalt pavement mandates. Municipal maintenance departments offer the most penetrable entry point given their cyclical resurfacing budgets and preference for flexible procurement. Technical partnership with bio-oil refiners secures differentiated feedstock access. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap contractors with captive terminal infrastructure and established Superpave certification pipelines. The 5-10 year viability window favors firms positioned for warranty-based performance contracts with ride-quality retention clauses. Monitor state DOT adoption of 50% RAP content specifications as inflection indicator for rejuvenator additive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Storage Reconfiguration | Heated agitation systems for polymer-modified grades unlock JTJ-specification highway awards in China. |
| Backward Integration into Vacuum Residue | Captive refinery supply insulates blending margins from crude differential volatility at Gulf Coast terminals. |
| Rejuvenator Chemistry Partnership | Bio-oil refiner alliances enable 50% RAP content compliance under Caltrans and Texas DOT protocols. |
| Cross-State Certification Reciprocity | Compressed approval timelines for proprietary additive packages accelerate project mobilization across state lines. |
| Warranty-Based Contract Migration | Ride-quality retention clauses transfer lifecycle risk and expand demand for predictive pavement management systems. |
Research Approach
Cross-validation between terminal operator interviews and state DOT specification databases anchors the qualitative findings in this study. Primary fieldwork encompassed discussions with refinery blending managers, AASHTO-certified binder technicians, municipal procurement officers, and polymer modifier distributors. Secondary sources included FHWA INVEST Act guidance documents, EN 12591 and EN 14023 standard texts, JTJ specification manuals, customs trade data on vacuum residue flows, and SEC filings from vertically integrated refiners. Bottom-up project pipeline analysis and top-down refinery capacity assessment triangulate volume estimates.
Sensitivity analysis across crude price scenarios and RAP content mandate timelines shapes the analytical framework. The model segments by binder chemistry type, application tier, end-user contract structure, and regional regulatory cluster. CAGRs derive from weighted average of historical specification upgrade velocity and projected infrastructure budget trajectories. Forecast inputs incorporate Ministry of Transport provincial award schedules and REACH authorization sunset protocols for polycyclic aromatic hydrocarbons.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure budget execution or abrupt regulatory relaxation would require recalibration. Forecasts reflect documented assumptions on technician training pipeline throughput and terminal retrofit capital availability. Practitioners should keep alternative scenarios live as EU PAH compliance deadlines and India's Bharatmala program phasing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market