
 Waterstop Market | 2026-2036
Waterstop Market Size, Share, and Industry Trends Forecast 2026-2036
Waterstop Market Analysis
Asset-light leasing models for specialized waterproofing equipment is reconfiguring competitive entry barriers, enabling regional contractors to bid on complex infrastructure jobs without capital-intensive inventory. Sika AG leverages its global distribution network to sustain specification-grade positioning across European tunnel contracts. Hengshui Jingtong Rubber Co. Ltd anchors its cost structure through captive supply of natural rubber compounds, dominating price-sensitive Asian procurement channels.
Waterstop denotes a hydrophilic or impermeable profile installed across concrete construction joints to prevent water ingress under hydrostatic pressure, typically manufactured from polyvinyl chloride, bentonite clay, or synthetic rubber compounds extruded to ASTM D6499 dimensional tolerances. The product functions as a passive barrier that swells or maintains structural integrity when exposed to moisture, protecting subterranean structures from leakage-induced degradation. Hydrophilic waterstop commands premium positioning in deep foundation and dam applications where sustained hydrostatic loads exceed PVC performance thresholds. Bentonite variants represent the fastest-growing material category, displacing conventional rubber in European infrastructure tenders that prioritize mineral-based sealing chemistry. Contractors and government infrastructure end users concentrate procurement around certified products that satisfy EN 12390 permeability testing, creating margin pools adjacent to raw material commoditization.
ASTM International governs dimensional and performance specifications for North American waterstop deployment, while the EU Construction Products Regulation mandates CE marking and harmonized EN standards for waterproofing systems sold across member states. China's GB standards through SAMR impose additional migration and durability testing that foreign suppliers must navigate for metro and hydropower project eligibility. Stakeholders must monitor evolving national building codes that increasingly specify performance-based rather than prescriptive material requirements, reshaping certification investments and regional manufacturing footprints.
Market Dynamics
Stricter waterproofing mandates under the EU Green Deal and updated F-Gas Regulation are compressing specification timelines for low-permeability synthetic rubber grades across European tunnel contracts, while China's high-speed rail expansion concentrates demand for hydrophilic variants that exceed conventional building standards.
Growth Catalysts
- EU Green Deal waterproofing mandates:The European Commission's climate-neutral building requirements are accelerating specification of mineral-based bentonite waterstop chemistry in public infrastructure tenders.
- China metro tunnel expansion:High-speed rail and underground transit projects in Shanghai, Beijing, and Guangzhou are driving procurement volumes for hydrophilic profiles rated for sustained hydrostatic loads.
- GB standards harmonization:SAMR's updated migration and durability testing protocols are creating eligibility barriers that favor certified domestic suppliers in hydropower and metro applications.
Market Restraints
- Natural rubber price volatility:Fluctuations in Southeast Asian latex supply are compressing margins for manufacturers dependent on captive rubber compound production.
- Supply concentration in East Asia:Bentonite mining and processing capacity clusters in specific Chinese provinces, exposing procurement channels to localized disruption risks.
- Technical performance ceilings:PVC waterstop fails EN 12390 permeability thresholds in deep foundation applications where hydrostatic pressure exceeds material tolerances.
Strategic Opportunities
- Asset-light equipment leasing:Specialized waterproofing machinery rental models are enabling regional contractors to bid on complex tunnel jobs without capital-intensive inventory holdings.
- EU F-Gas Regulation tailwind:Phasedown of fluorinated greenhouse gases is creating specification openings for synthetic rubber alternatives in climate-critical infrastructure.
- Digital specification platforms:Online certification databases are collapsing information asymmetries between certified manufacturers and procurement officers in fragmented Asian markets.
Industry Challenges
- EN 12390 testing bottlenecks:Limited accredited laboratory capacity in Southern Europe is extending certification timelines for bentonite waterstop variants seeking CE marking.
- Skill gaps in hydrophilic installation:Specialized joint-sealing techniques for swelling-profile waterstop require trained crews that remain scarce in emerging African and Latin American markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterstop Market |
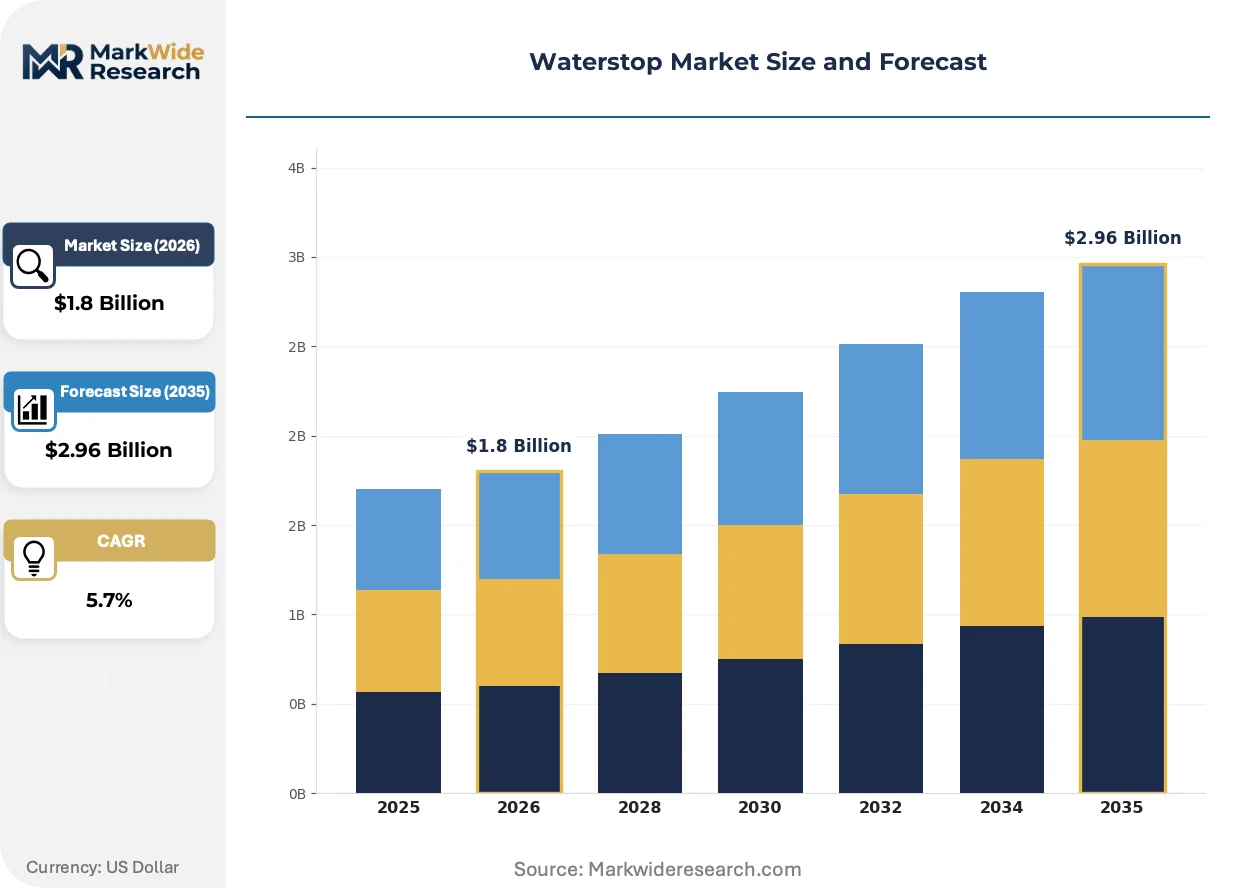
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bentonite Waterstop, PVC Waterstop, Rubber Waterstop, Hydrophilic Waterstop Application: Construction, Tunnels, Foundations, Dams Material: Polyvinyl Chloride, Natural Rubber, Synthetic Rubber, Bentonite End User: Contractors, Engineers, Government, Infrastructure |
| Companies Covered | BoMetals Inc., GCP Applied Technologies Inc., Sika AG, Fosroc Inc, Mapei Corporation, Trelleborg AB, Henry Company, Hengshui Jingtong Rubber Co. Ltd, JP Specialties Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterstop Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are collapsing traditional product hierarchies, while digital procurement tools reconfigure how certified waterstop reaches tunnel and foundation contractors.
Bentonite clay waterstop is collapsing the market position of conventional synthetic rubber in European infrastructure tenders. Hydropower authorities in Norway and dam operators in Switzerland are specifying mineral-based sealing chemistry to satisfy EU Green Deal procurement guidelines. The technology is collapsing premium pricing power for established PVC and rubber compound manufacturers who lack bentonite processing capabilities.
REACH restrictions on persistent organic pollutants are forcing reformulation of plasticizer additives in PVC waterstop compounds. German tunnel contractors now face mandatory substitution assessments for legacy phthalate-based formulations under updated ECHA authorization lists. The regulatory pressure is concentrating specification authority with compounders who have secured SVHC-free additive supply chains.
Leasing models for specialized joint-sealing equipment are fragmenting traditional distributor control over contractor relationships. Regional rental networks in India and Indonesia are displacing inventory-heavy wholesale channels that previously captured margin through equipment bundling. The shift is most visible in price-sensitive Asian markets where contractors prioritize working capital flexibility over long-term equipment ownership.
Waterstop Market Segmentation
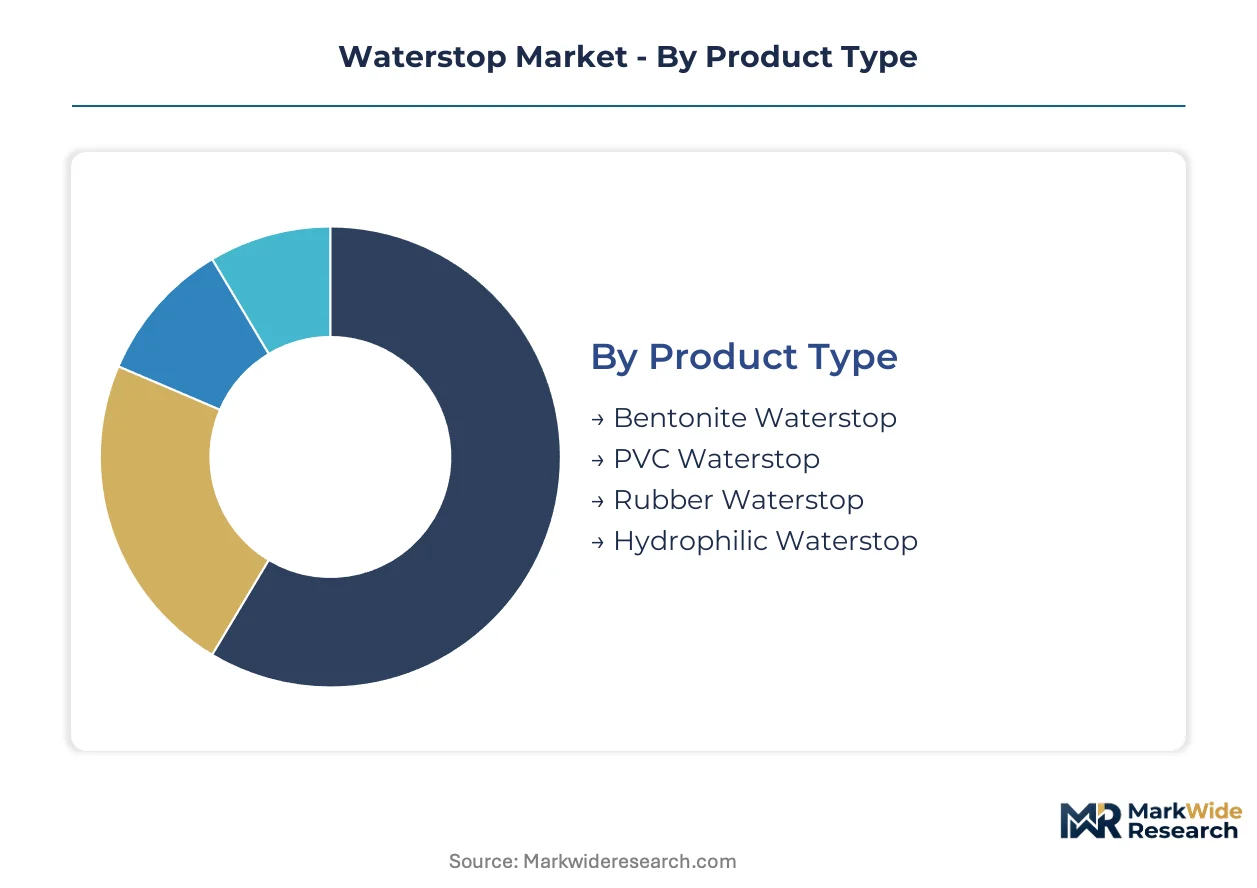
Waterstop specification diverges sharply across hydrostatic load requirements, with material chemistry and installation environment dictating procurement decisions. Contractors segment demand by performance tier rather than price, creating distinct margin pools for certified mineral-based and synthetic compound formulations.
Product Type:
Mature PVC formulations dominate legacy building stock, while emerging bentonite chemistry captures specification authority in climate-mandated infrastructure.
- Bentonite Waterstop:Swelling clay-based profiles expand upon moisture contact to form self-sealing barriers in concrete joints. Norwegian hydropower authorities and Swiss dam operators specify bentonite variants to satisfy EU Green Deal procurement chemistry mandates, displacing conventional rubber in European public tenders.
- Hydrophilic Waterstop:Rubber-polymer compounds engineered for volumetric expansion under sustained hydrostatic pressure serve deep foundation and metro tunnel applications. Shanghai and Beijing metro projects specify hydrophilic profiles rated for hydrostatic loads exceeding PVC tolerances, concentrating procurement volume in China's high-speed rail corridor.
- PVC Waterstop:Extruded polyvinyl chloride profiles remain standard for above-grade construction joints with moderate moisture exposure.
- Rubber Waterstop:Synthetic and natural rubber compounds provide elastic recovery in expansion joints subject to structural movement.
PVC waterstop handles the majority of throughput; bentonite waterstop is expanding most quickly on specification share.
Application:
Cost tier stratification separates capital-intensive tunnel projects from routine building maintenance, with foundation work occupying the middle ground on certification requirements.
- Tunnels:Underground transit and rail corridors demand hydrophilic and bentonite profiles certified to EN 12390 permeability thresholds. Guangzhou metro contractors procure specialized joint-sealing systems that exceed conventional building waterproofing standards, creating premium specification tiers.
- Dams:Hydrostatic load extremes in reservoir and hydropower structures require mineral-based sealing chemistry with documented long-term swelling performance.
- Construction:Commercial and residential building joints specify PVC and standard rubber profiles for above-grade moisture protection.
- Foundations:Deep basement and pile cap applications split procurement between hydrophilic profiles for high water tables and bentonite for contaminated soil conditions.
Tunnel applications concentrate the highest value procurement; dam construction is climbing fastest on specification intensity.
Material:
Supply concentration in East Asian rubber processing and Chinese bentonite mining shapes regional procurement access and price volatility exposure.
- Bentonite:Processed sodium and calcium bentonite clays from specific Chinese provinces supply swelling-profile waterstop manufacturing. Localized mining concentration exposes European and Asian procurement channels to disruption risks, prompting inventory hedging among major contractors.
- Synthetic Rubber:EPDM and neoprene compounds formulated for low permeability capture specification openings under EU F-Gas Regulation phasedown. German tunnel contractors face mandatory substitution assessments for legacy formulations, concentrating authority with compounders holding SVHC-free additive supply chains.
- Natural Rubber:Southeast Asian latex supply fluctuations compress margins for manufacturers dependent on captive compound production.
- Polyvinyl Chloride:REACH restrictions on phthalate plasticizers force reformulation of legacy PVC waterstop compounds across European markets.
Synthetic rubber handles the majority of specification-grade volume; bentonite is gaining share fastest on regulatory tailwinds.
End User:
Customer type determines certification burden and procurement channel, with government infrastructure mandating third-party testing that private contractors often bypass.
- Government:Public infrastructure authorities in Norway, Switzerland, and China's provincial transport bureaus mandate EN 12390 and GB standards compliance with documented chain-of-custody certification. SAMR's updated migration and durability testing protocols create eligibility barriers favoring certified domestic suppliers in Chinese hydropower and metro applications.
- Contractors:Regional construction firms in India and Indonesia leverage asset-light equipment leasing models to bid on complex tunnel jobs without capital-intensive inventory holdings, fragmenting traditional distributor control.
- Infrastructure:State-owned enterprises and utility operators maintain long-term supply agreements with compounders holding multi-standard certification portfolios.
- Engineers:Specification consultants influence material selection through performance-based rather than prescriptive requirements in updated national building codes.
Government procurement handles the majority of certified volume; contractor direct purchasing is expanding fastest on leasing-enabled market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances concentrate waterstop supply in East Asian manufacturing clusters while European infrastructure demand outpaces domestic bentonite processing capacity. China maintains surplus hydrophilic profile production for regional metro tunnel contractors. Germany and Switzerland import swelling-clay formulations to satisfy EU Green Deal chemistry mandates.
China
High-speed rail corridors between Shanghai, Beijing, and Guangzhou generate concentrated procurement of hydrophilic profiles rated for extreme hydrostatic loads. SAMR's updated GB standards on migration and durability testing restrict foreign supplier eligibility in hydropower and metro applications. Sichuan-Chongqing mining clusters supply processed bentonite to domestic waterstop fabricators serving provincial transport bureaus.
Germany
Underground transit expansion in Berlin, Munich, and Hamburg drives specification of low-permeability synthetic rubber grades for tunnel joint-sealing systems. ECHA authorization lists under REACH force mandatory substitution assessments for legacy phthalate-based PVC formulations. Bavarian tunnel contractors source certified bentonite alternatives to meet EU Green Deal procurement chemistry requirements.
United States
Federal infrastructure spending on Northeast Corridor rail tunnels and New York City subway rehabilitation concentrates demand for ASTM D6499 certified profiles. EPA enforcement of stormwater management regulations elevates specification standards for below-grade waterproofing in commercial foundations. Chicago and Los Angeles metro authorities procure hydrophilic variants for deep-bore tunnel sections exceeding conventional PVC tolerances.
Switzerland
Alpine hydropower dam operators specify mineral-based sealing chemistry to satisfy long-term swelling performance requirements under federal procurement guidelines. Swissmedic-aligned cantonal building codes mandate EN 12390 permeability certification for subterranean structures. Geneva and Zurich engineering consultants influence material selection through performance-based specifications in updated national standards.
India
Metro construction in Delhi, Mumbai, and Bangalore creates procurement volume for joint-sealing systems in water-table-intensive foundation conditions. BIS harmonization with international waterproofing standards is elevating certification requirements for imported bentonite and synthetic rubber compounds. Regional contractors in Maharashtra and Karnataka leverage equipment leasing models to bid on complex tunnel contracts without capital-intensive inventory holdings.
Waterstop Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on material chemistry and regional distribution. The vendor base organizes around three archetypes: multinational construction chemical conglomerates with specification-grade certification portfolios, captive rubber compounders dominating price-sensitive Asian procurement channels, and regional fabricators serving localized infrastructure tenders. Consolidation pressure concentrates among European players seeking bentonite processing capabilities, while Asian markets fragment across equipment-leasing-enabled contractor direct purchasing. Dominant competitive moves include backward integration into mineral-based raw material supply and technology licensing for SVHC-free additive formulations.
Among Swiss and German construction chemical conglomerates, Sika AG occupies a position exemplifying specification-grade positioning across European tunnel contracts. Hengshui Jingtong Rubber Co. Ltd anchors the cost-structure tier through captive supply of natural rubber compounds, representing manufacturers dominating price-sensitive Asian procurement channels. Trelleborg AB sits within the synthetic rubber specialization segment, reflecting compounders capturing specification openings under EU F-Gas Regulation phasedown mandates.
| Leading Market Players |
|---|
| BoMetals Inc. |
| GCP Applied Technologies Inc. |
| Sika AG |
| Fosroc Inc |
| Mapei Corporation |
| Trelleborg AB |
| Henry Company |
| Hengshui Jingtong Rubber Co. Ltd |
| JP Specialties Inc. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries processed bentonite clay and synthetic rubber compounds from East Asian manufacturing clusters to European tunnel contractors, with freight cost volatility amplifying price spreads between certified premium grades and standard formulations. This logistics backbone concentrates procurement power among compounders holding captive mineral supply, while downstream price differentiation widens between EN 12390-certified profiles and uncertified alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with government infrastructure authorities paying certification premiums for EN 12390 and GB standards compliance while regional contractors in India and Indonesia prioritize working capital flexibility through equipment-leasing bundles. Price differentiation hinges on hydrostatic load ratings and third-party testing documentation, with hydrophilic profiles commanding substantial premiums over PVC alternatives. Cost compression in standard rubber grades is intensifying because Southeast Asian latex supply fluctuations erode captive compounder margins. Price sensitivity concentrates among regional contractors bidding on price-sensitive Asian procurement channels, while Swiss and Norwegian hydropower authorities exhibit minimal elasticity for mineral-based sealing chemistry.
Supply Chain Analysis
Contract manufacturing concentration sits with Sichuan-Chongqing bentonite processing clusters and Hebei province rubber compounding facilities, with captive supply arrangements dominating domestic Chinese procurement. Raw material sourcing draws from sodium bentonite deposits in Inner Mongolia, natural rubber latex from Thailand and Indonesia, and EPDM polymer feedstock from South Korean petrochemical complexes. Single-source vulnerability runs through concentrated bentonite mining in specific Chinese provinces, exposing European fabricators to localized disruption risks. Distribution runs through specification-grade distributors serving government infrastructure tenders, with equipment-leasing networks fragmenting traditional wholesale channels in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterstop specification increasingly attaches recurring certification maintenance and joint-sealing equipment rental revenue to initial material supply, with digital specification platforms and training service contracts expanding faster than hardware throughput alone.
For Market Incumbents: Pre-empt bentonite chemistry displacement by securing mineral processing capabilities or licensing agreements with Sichuan-Chongqing mining clusters, as EU Green Deal mandates accelerate specification share capture by mineral-based alternatives. Backward integration into SVHC-free additive supply chains defends margin position against REACH reformulation pressures on legacy PVC compounds. Certification investment in multi-standard portfolios—spanning EN 12390, GB standards, and ASTM D6499—creates eligibility barriers for unqualified competitors in government infrastructure tenders. For New Entrants and Emerging Players: African metro construction markets present underpenetrated demand for hydrophilic installation training services and equipment-leasing partnerships, with skill gaps in swelling-profile techniques creating white-space for technical service bundling. Latin American dam operators offer specification openings for bentonite variants as regional procurement gradually harmonizes with EU chemistry mandates. A go-to-market angle anchored in digital certification databases collapses information asymmetries between qualified fabricators and procurement officers in fragmented developing markets. For Investors and Strategic Acquirers: Carve-out targets emerge from construction chemical conglomerates seeking to divest non-core waterproofing divisions lacking bentonite processing capabilities or SVHC-free formulation expertise. Long-term viability favors compounders with demonstrated EN 12390 testing relationships and established SAMR registration pathways for Chinese hydropower eligibility. The signal to monitor is accelerating specification of performance-based rather than prescriptive material requirements in national building code updates, which rewards technical R&D investment over commodity scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Mining | Captive mineral supply secures EU Green Deal specification eligibility against rubber compound displacement. |
| SVHC-Free Additive Reformulation | REACH compliance unlocks German tunnel contractor procurement under updated ECHA authorization lists. |
| Multi-Standard Certification Investment | EN 12390, GB standards, and ASTM D6499 portfolios enable cross-border government infrastructure eligibility. |
| Equipment-Leasing Network Expansion | Asset-light models penetrate price-sensitive Indian and Indonesian contractor channels without inventory risk. |
| Digital Specification Platform Development | Online certification databases collapse information asymmetries in fragmented Asian procurement markets. |
Methodological Framework
A spread of perspectives from tunnel project engineers, waterproofing procurement officers at state-owned enterprises, bentonite mining operations managers, and specialty rubber compound R&D directors converged on the working assumptions underlying demand projections. Primary field engagement combined structured interviews with secondary validation through customs trade data, SAMR GB standards documentation, ECHA REACH authorization updates, and SEC filings from listed construction chemical conglomerates. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts across the analysis window.
Demand-supply balance modeling integrated hydrostatic load requirements by application tier, material chemistry substitution dynamics, and regional regulatory cluster adoption patterns throughout the forecast period. Segmentation dimensions spanned product type, installation environment, end-user procurement authority, and certification grade tier. CAGRs derived from fitted growth curves applied to validated baseline volumes, with industry-specific inputs including high-speed rail construction pipelines and EU F-Gas Regulation implementation timelines.
Practitioners should monitor SAMR standards harmonization progress, EU Green Deal procurement guideline updates, and Southeast Asian rubber supply disruptions for early signals requiring forecast revision. Quarterly review of EN 12390 accredited laboratory capacity expansion and equipment-leasing network penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Artificial Marble Market