
 Middle-East and Africa Industrial Flooring Market | 2026-2036
Middle-East and Africa Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Industrial Flooring Market Foresight
Food processing and pharmaceutical facilities are bifurcating demand away from general manufacturing as the fastest-growing buyer archetype in the Middle-East and Africa industrial flooring space. Flowcrete Group Ltd. leverages its epoxy formulation expertise to anchor projects across Gulf petrochemical complexes. Saudi Industrial Flooring Co. dominates domestic installation capacity through backward integration into substrate preparation services. Cape Industrial Flooring competes on anti-slip system specialization for wet-process environments.
Middle-East and Africa industrial flooring comprises resin-based, cementitious, and polymer-modified surface systems engineered to withstand mechanical abrasion, chemical exposure, and thermal cycling in commercial and industrial settings. Epoxy systems typically achieve compressive strengths exceeding 80 MPa and bond to concrete substrates through amine-cured polymerization, serving primarily to protect structural slabs while enabling hygienic, dust-free operations. Epoxy formulations lead product type demand due to their cost-performance ratio in heavy manufacturing, while polyurethane gains share in food processing where thermal shock resistance matters. Cementitious systems occupy the renovation segment where rapid return-to-service drives specification decisions.
Saudi Arabia's SFDA, South Africa's National Regulator for Compulsory Specifications, and UAE's civil defense authorities enforce divergent fire-safety and hygiene standards that fragment product certification requirements across the region. These regulatory frameworks compel manufacturers to maintain multiple formulation portfolios and testing protocols, raising compliance costs but creating technical barriers that favor established suppliers. Stakeholders must monitor evolving green building codes in Dubai and Riyadh that are beginning to specify low-VOC and recycled-content flooring systems.
Market Dynamics
Saudi Arabia's giga-project construction pipeline is compressing installation timelines for industrial flooring contractors, forcing rapid substrate preparation and resin curing protocols that favor contractors with captive equipment fleets and trained installation crews.
Growth Catalysts
- SFDA hygiene mandates:Saudi Arabia's food and drug regulator is tightening surface certification requirements for food-grade facilities, mandating seamless resin systems that eliminate bacterial harborage points in processing plants.
- Cold-chain infrastructure:GCC warehousing operators are expanding temperature-controlled logistics parks that require specialized polyurethane flooring with thermal shock resistance across freezer-to-ambient transition zones.
- Epoxy formulation advances:Low-VOC amine-cured systems are penetrating pharmaceutical cleanrooms where air quality protocols previously excluded conventional resin applications.
Market Restraints
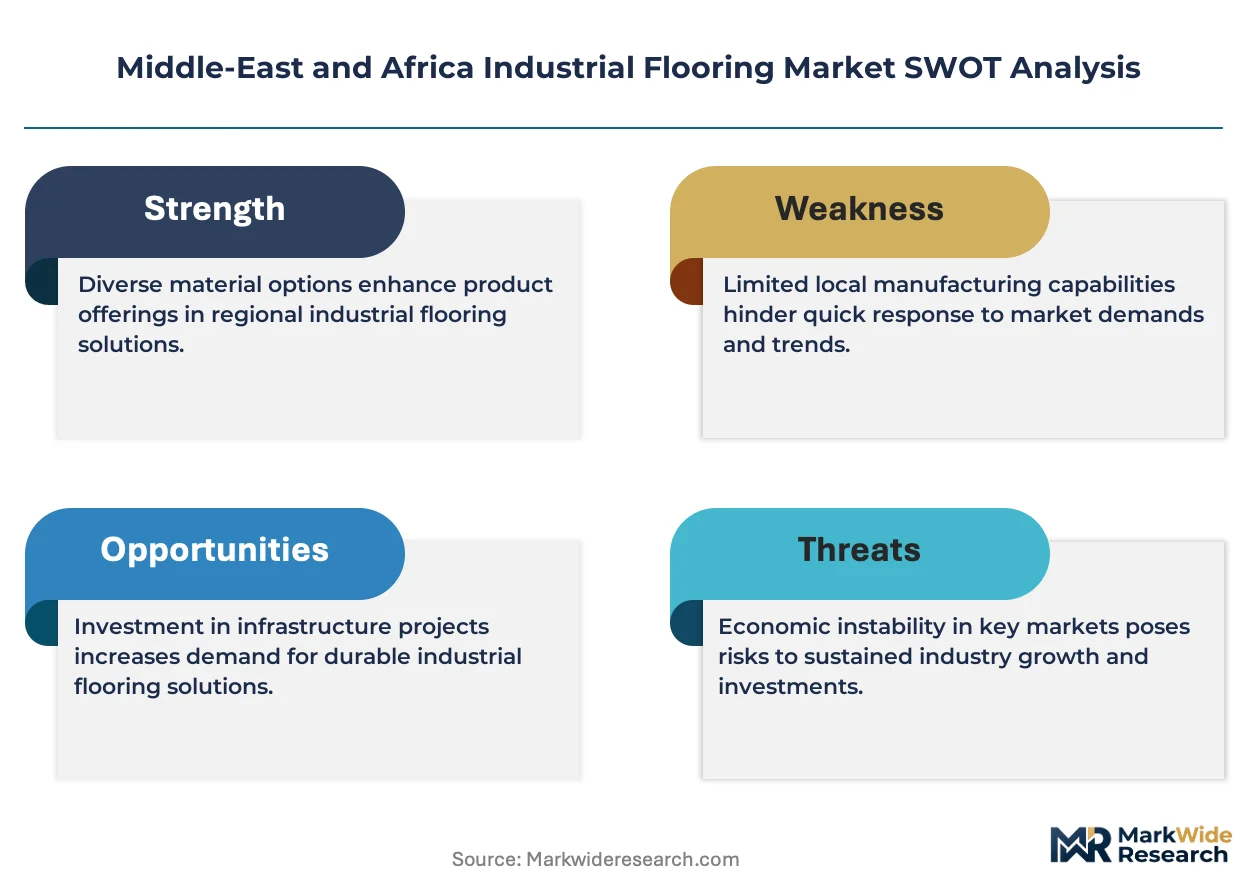
- Petrochemical feedstock volatility:Epoxy resin prices fluctuate with benzene and propylene derivatives from Gulf petrochemical complexes, compressing margins for formulation specialists.
- Specialized contractor scarcity:Substrate preparation and resin application skills concentrate in Saudi Arabia's Eastern Province and UAE's Jebel Ali corridor, creating installation bottlenecks for projects in secondary markets.
- Cementitious competition:Rapid-setting polymer-modified screeds capture renovation segments where facility downtime costs exceed resin system lifecycle advantages.
Strategic Opportunities
- Egyptian industrial zones:Suez Canal Economic Zone manufacturing clusters remain underpenetrated by specialized flooring contractors despite accelerating automotive and textile facility construction.
- Green building codes:Dubai's Al Sa'fat and Riyadh's new sustainable construction standards are beginning to specify recycled-content aggregates and low-emission resin systems, creating certification-premium positioning.
- Anti-slip specialization:Wet-process food and beverage facilities in South Africa's Western Cape are driving demand for textured polyurethane systems that combine chemical resistance with slip-rated surface profiles.
Industry Challenges
- Multi-jurisdiction certification:Contractors must navigate divergent fire-safety testing protocols between UAE civil defense authorities, Saudi SFDA surface standards, and South Africa's National Regulator for Compulsory Specifications, extending project qualification timelines.
- Skilled applicator shortage:Proper epoxy and polyurethane installation requires certified technicians proficient in moisture testing, surface profiling, and pot-life management, with training pipelines failing to match Gulf construction velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Industrial Flooring Market |
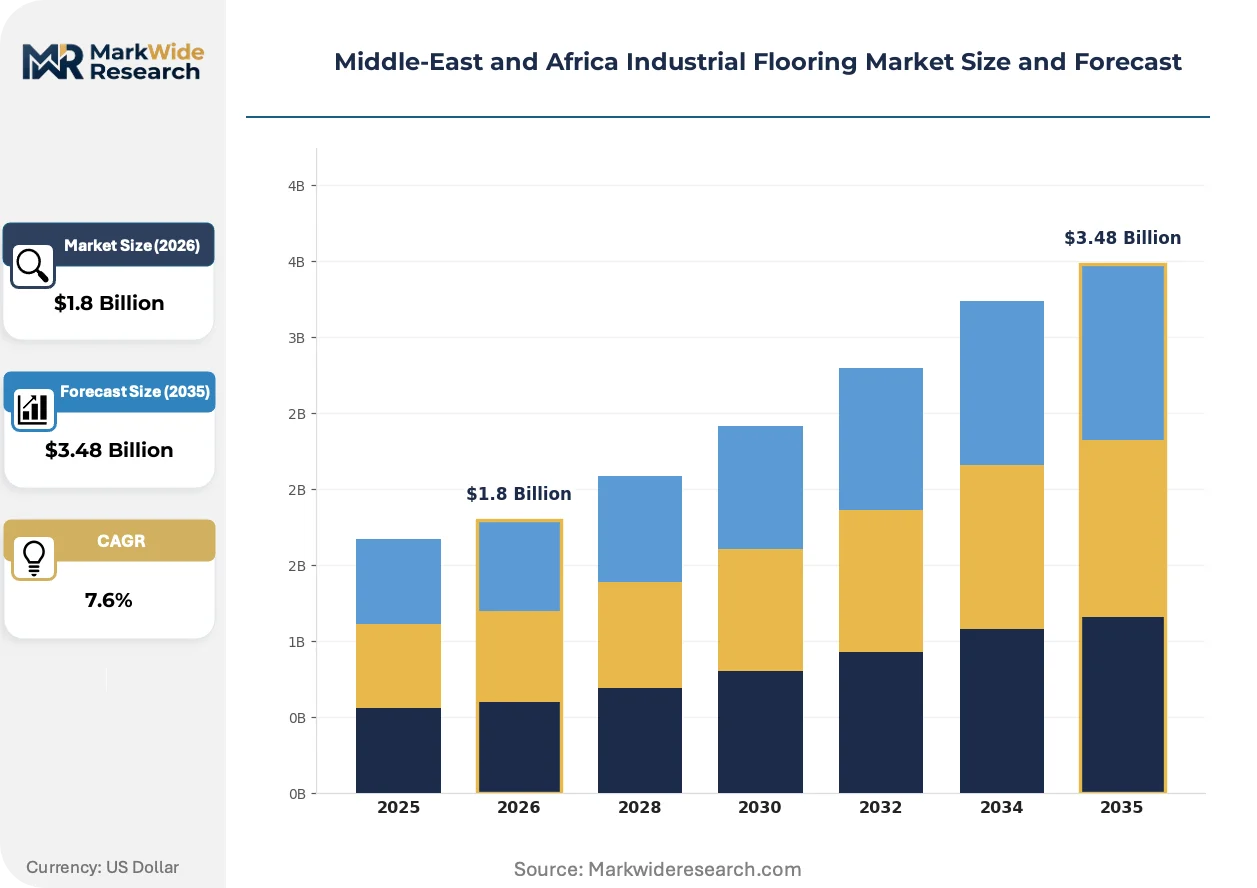
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Cementitious, Vinyl End User: Manufacturing, Warehousing, Food Processing, Pharmaceutical Application: Heavy Duty, Decorative, Anti-slip, Low Maintenance Installation Type: New Construction, Renovation, Repair, Temporary |
| Companies Covered | Cape Industrial Flooring, Floormaster Industrial Flooring Solutions, Flowcrete Group Ltd., Saudi Industrial Flooring Co., Klikflor Pty Ltd, Al Futtaim Group, Interface Middle East, Tarkett, Shaw Industries Group Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Industrial Flooring Market Shifts & Advancements
Resin flooring technology is fragmenting into application-specific formulations as end-users reject generic epoxy systems, while regulatory pressure on VOC emissions and surface hygiene accelerates product substitution cycles across the Middle-East and Africa.
Polyurethane cement hybrid technology is decomposing the traditional separation between heavy manufacturing and food processing flooring specifications. These systems achieve compressive strengths above 70 MPa while tolerating thermal cycling from minus forty to plus one hundred twenty degrees Celsius. South African poultry processing facilities and UAE dairy plants are specifying these hybrids at triple the rate of conventional epoxy, collapsing the historical distinction between chemical-resistant and thermal-shock-resistant categories.
Saudi Arabia's SFDA is extending its Good Manufacturing Practice surface requirements from pharmaceutical facilities into packaged food and beverage plants, mandating documented cleanability and coving at wall-floor junctions. This regulatory expansion is forcing renovation of legacy concrete floors in Riyadh and Jeddah industrial zones. Contractors are responding with rapid-cure methyl methacrylate systems that minimize production downtime during facility upgrades.
Facility engineering teams are consolidating flooring specifications under single-source contractor arrangements that bundle substrate preparation, resin installation, and decade-long performance warranties. This purchasing consolidation is displacing fragmented procurement where civil contractors handled concrete and specialized applicators managed resin finishing. The pattern is most visible in Saudi Arabia's industrial cities, where giga-project developers prefer integrated accountability over segmented contracting risk.
Middle-East and Africa Industrial Flooring Market Segmentation
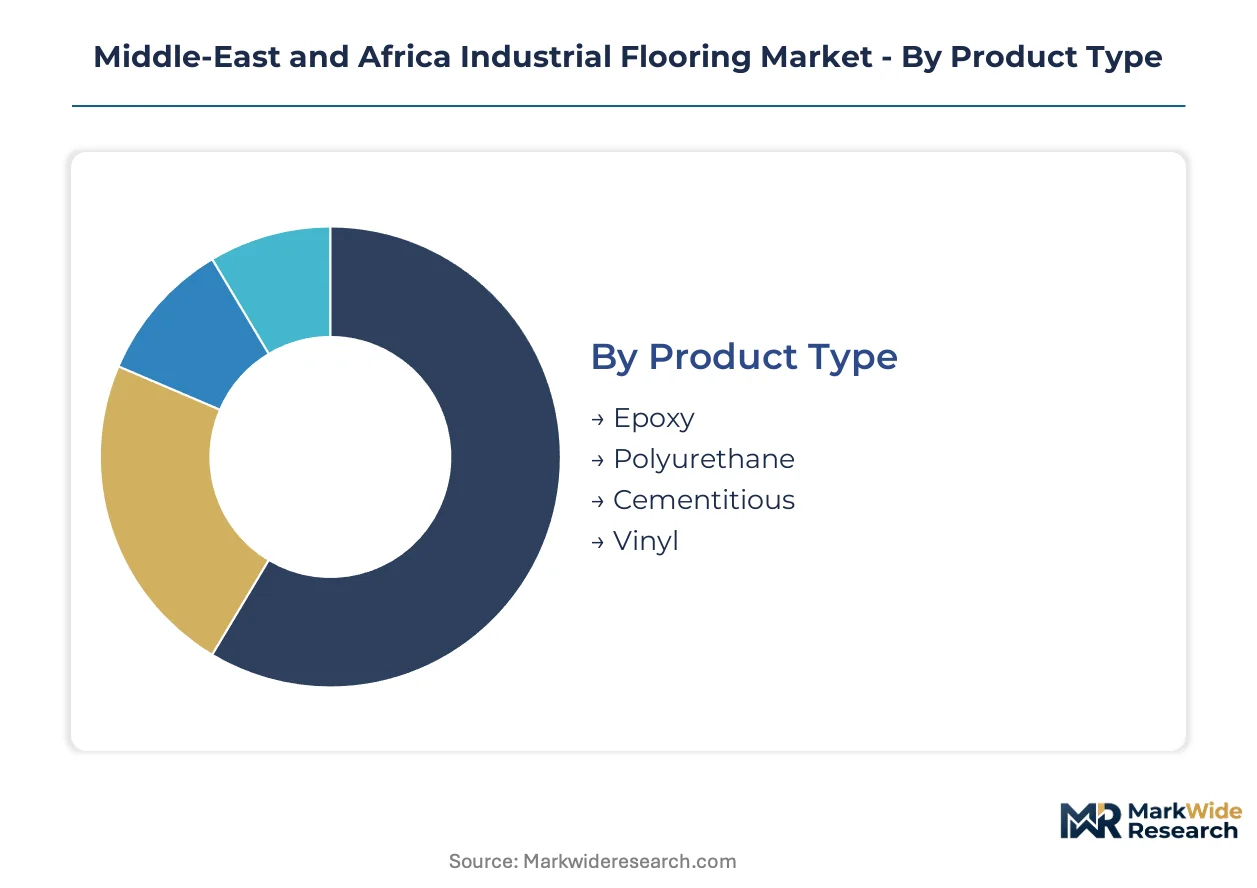
Industrial flooring purchasing in the Middle-East and Africa fragments across resin chemistry, facility type, and installation context. Specification decisions hinge on thermal cycling demands, regulatory hygiene mandates, and construction timeline pressures that vary sharply between Saudi giga-projects and South African renovation cycles.
Product Type:
Epoxy and polyurethane formulations move through specialized applicator networks, while cementitious systems reach facilities via general construction distributors. Channel access shapes specification authority in each segment.
- Epoxy:Amine-cured polymer systems achieve compressive strengths above 80 MPa through cross-linked molecular structures. Demand concentrates in Saudi Arabia's Eastern Province petrochemical complexes, where SFDA hygiene mandates and rapid giga-project timelines favor proven installation protocols.
- Polyurethane:Aliphatic and aromatic formulations deliver thermal shock resistance across minus forty to plus one hundred twenty degree Celsius ranges. Food processing facilities in UAE's Jebel Ali corridor and South Africa's Western Cape specify these systems where freezer-to-ambient transitions dominate operational cycles.
- Cementitious:Polymer-modified screeds serve renovation segments through rapid-setting chemistry that compresses return-to-service windows.
- Vinyl:Sheet and tile systems occupy healthcare and light commercial installations where capital constraints override resin lifecycle economics.
Epoxy dominates installed base across heavy manufacturing corridors. Polyurethane is where expansion concentrates as cold-chain infrastructure multiplies thermal-shock specifications.
End User:
Facility engineering teams in each sector deploy distinct procurement structures—integrated single-source contracting in pharmaceuticals versus fragmented civil-plus-specialist arrangements in general manufacturing.
- Manufacturing:Heavy industrial plants specify resin systems primarily for mechanical abrasion resistance and chemical containment. Automotive and electronics facilities in Egypt's Suez Canal Economic Zone are driving specification volume as manufacturing clusters mature.
- Warehousing:Temperature-controlled logistics parks across the GCC require polyurethane systems with thermal cycling tolerance. E-commerce fulfillment center construction in Dubai South and Riyadh's industrial cities is compressing installation timelines and favoring contractors with captive equipment fleets.
- Food Processing:SFDA surface certification requirements mandate seamless resin systems with documented cleanability and coving at wall-floor junctions.
- Pharmaceutical:Low-VOC epoxy formulations penetrate cleanroom environments where air quality protocols previously excluded conventional resin chemistry.
Manufacturing anchors current specification volume. Food processing is climbing the fastest as regulatory hygiene mandates extend from pharmaceuticals into packaged goods.
Application:
Performance tier determines margin structure—heavy duty and anti-slip commands premium pricing through specialized formulation, while decorative and low-maintenance segments compete on installed cost.
- Heavy Duty:High-build epoxy and polyurethane cement hybrids withstand forklift traffic and chemical spill exposure in continuous operations. Petrochemical facilities in Saudi Arabia's Jubail Industrial City specify these systems where mechanical loading and corrosive exposure coincide.
- Anti-slip:Textured polyurethane profiles combine chemical resistance with slip-rated surface characteristics. Poultry and dairy processing in South Africa's Western Cape drives specification where wet-process environments dominate.
- Decorative:Metallic and quartz-filled epoxy systems serve showroom and reception areas within industrial facilities.
- Low Maintenance:Thin-film sealers and coatings target budget-constrained renovation projects.
Heavy duty commands specification authority in new construction. Anti-slip is gaining share fastest as wet-process food safety regulations tighten.
Installation Type:
Construction phase dictates contractor capability requirements—new construction rewards scale and speed, while renovation demands rapid-cure chemistry and minimal disruption protocols.
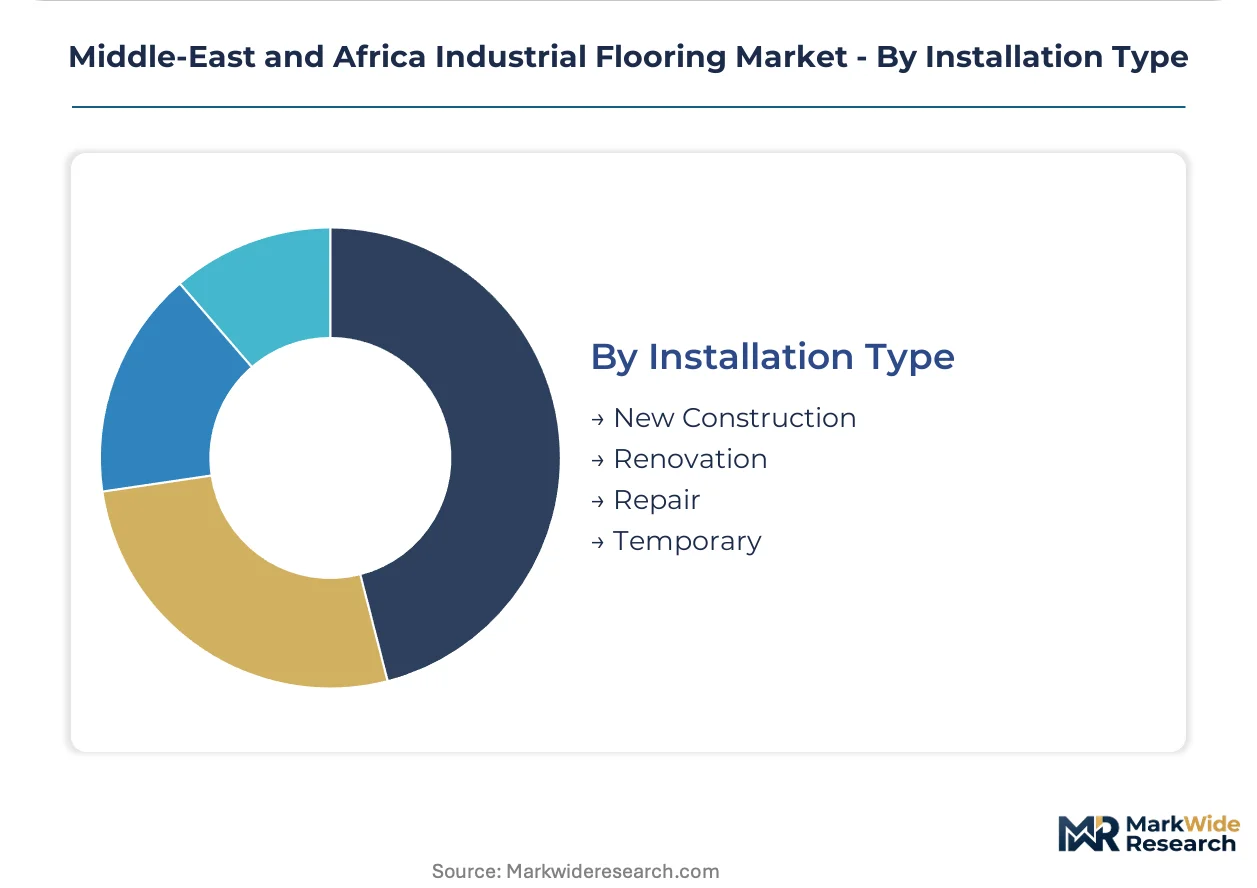
- New Construction:Greenfield industrial facilities in Saudi Arabia's giga-projects specify integrated flooring packages bundled with structural slab work. Single-source accountability is displacing fragmented procurement where civil and resin contractors operated separately.
- Renovation:Methyl methacrylate rapid-cure systems minimize production downtime in operating facilities. Legacy concrete floor upgrades in Riyadh and Jeddah food plants are accelerating as SFDA extends Good Manufacturing Practice surface requirements.
- Repair:Localized patching and recoat services address substrate failure and wear patterns.
- Temporary:Modular flooring systems serve exhibition and event infrastructure with rapid deployment and removal.
New construction absorbs the largest share of specialized contractor capacity. Renovation is expanding most quickly as regulatory compliance deadlines force facility upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal anchors Egypt's industrial flooring specification volume as manufacturing clusters expand along this maritime corridor. Saudi Arabia's Eastern Province petrochemical complexes and UAE's Jebel Ali logistics hub concentrate specialized contractor capacity. South Africa's Western Cape food processing belt drives anti-slip system demand.
Saudi Arabia
Giga-project construction in Riyadh and Jeddah industrial cities accelerates factory and logistics park buildouts requiring rapid-cure resin systems. SFDA hygiene mandates for food-grade surfaces tighten seamless flooring specifications in processing plants. NEOM Northwest development contracts are compressing installation timelines and favoring contractors with captive equipment fleets.
United Arab Emirates
Dubai South e-commerce fulfillment centers and Jebel Ali cold-chain facilities specify polyurethane systems with thermal shock resistance across freezer-to-ambient zones. MOHAP and civil defense authorities enforce fire-safety standards that fragment product certification requirements. Abu Dhabi's industrial zones are consolidating flooring procurement under single-source contractor arrangements with decade-long warranties.
Egypt
Suez Canal Economic Zone manufacturing clusters in automotive and textiles are maturing specification volume for heavy-duty epoxy systems. The country's national building regulator is aligning construction standards with Gulf hygiene protocols. Ain Sokhna port-industrial complexes are attracting specialized flooring contractors previously concentrated in Arabian Peninsula markets.
South Africa
Western Cape poultry and dairy processing facilities specify textured polyurethane profiles combining chemical resistance with slip-rated surface characteristics. The National Regulator for Compulsory Specifications enforces divergent testing protocols that extend project qualification timelines. Gauteng pharmaceutical cleanrooms are adopting low-VOC epoxy formulations previously excluded by air quality protocols.
Middle-East and Africa Industrial Flooring Market Competitive Landscape
Listed leaders compete with private specialists across formulation expertise and installation capacity in a market where technical certification barriers favor established suppliers. The vendor base clusters around three strategic archetypes: multinational resin formulators with Gulf petrochemical complex relationships, domestic contractors with backward integration into substrate preparation services, and regional specialists targeting wet-process anti-slip applications. Dominant competitive moves include captive equipment fleet expansion to compress giga-project timelines and rapid-cure chemistry licensing to capture renovation-driven specification shifts.
Within the formulation specialist tier, Flowcrete Group Ltd. and Cape Industrial Flooring exemplify divergent positioning strategies. Flowcrete anchors multinational reach through epoxy formulation expertise across Gulf petrochemical complexes. Cape Industrial Flooring occupies a position within wet-process specialization, particularly in South Africa's food and beverage segments. Saudi Industrial Flooring Co. represents domestic installation capacity consolidation through in-house substrate preparation services, a structure that aligns with Riyadh's compressed construction timelines.
| Leading Market Players |
|---|
| Cape Industrial Flooring |
| Floormaster Industrial Flooring Solutions |
| Flowcrete Group Ltd. |
| Saudi Industrial Flooring Co. |
| Klikflor Pty Ltd |
| Al Futtaim Group |
| Interface Middle East |
| Tarkett |
| Shaw Industries Group Inc |
| Others |
Supply & Pricing Matrix
Project-based contracting with take-or-pay clauses locks in epoxy resin supply from Gulf petrochemical complexes while anchoring price visibility for Saudi giga-project developers facing compressed installation timelines. This structure transfers feedstock volatility risk to formulation specialists while guaranteeing volume allocation for warehousing and food processing buildouts.
Pricing Analysis
Volume-discount tiering separates SFDA-certified seamless systems from standard epoxy formulations and rapid-cure cementitious alternatives. Certification grade and project scale drive price differentiation, with hygiene-mandated pharmaceutical and food processing floors commanding premiums over general manufacturing specifications. Cost compression in economy-tier cementitious renovation products is intensifying as polymer-modified screed manufacturers compete on return-to-service speed. General manufacturing facilities exhibit highest price sensitivity, while cold-chain logistics operators prioritize thermal-shock performance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for amine hardeners and specialty aggregates not produced in GCC petrochemical corridors. Formulation supply concentrates in Saudi Arabia's Eastern Province, UAE's Jebel Ali chemical hub, and South Africa's KwaZulu-Natal industrial belt. Raw material dependencies include benzene derivatives, propylene feedstocks, and aliphatic isocyanates. Single-source vulnerability runs through Gulf petrochemical complex output for epoxy resin precursors. Distribution runs through specialized applicator networks for resin systems and general construction distributors for cementitious products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where SFDA hygiene mandates and multi-jurisdiction certification requirements create switching costs that cement incumbent positioning.
For Market Incumbents: Shield formulation portfolios through captive substrate preparation capacity in Saudi Arabia's industrial cities, where giga-project velocity rewards contractors with trained installation crews and equipment fleets. Deepen backward integration into surface profiling and moisture testing services to capture renovation cycles as SFDA extends Good Manufacturing Practice requirements. The priority lever sits with rapid-cure methyl methacrylate licensing to compress facility downtime during food plant upgrades. For New Entrants and Emerging Players: SFDA certification fast-tracking offers entry pathway into Riyadh and Jeddah food processing renovation segments where legacy concrete floor upgrades accelerate. Egypt's Suez Canal Economic Zone manufacturing clusters remain most penetrable for heavy-duty epoxy specification, particularly automotive and textile facilities maturing beyond basic civil contractor finishing. Go-to-market angle should anchor on thermal-shock specialization for cold-chain logistics parks multiplying across Dubai South and Riyadh industrial zones. For Investors and Strategic Acquirers: Regional specialists with wet-process anti-slip formulation expertise represent the target acquisition archetype, particularly those anchored in South Africa's Western Cape poultry and dairy processing belt. Long-term viability frames around regulatory hygiene mandate expansion across packaged goods and pharmaceutical cleanroom segments. Signal to watch: Dubai and Riyadh green building code enforcement accelerating low-VOC and recycled-content specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Unlocks food-grade facility specification in Saudi Arabia's expanding processing plant pipeline. |
| Captive Equipment Fleet Expansion | Compresses giga-project installation timelines in NEOM and Riyadh industrial cities. |
| Rapid-Cure Chemistry Licensing | Captures renovation-driven specification as SFDA mandates force legacy floor upgrades. |
| Polyurethane Cement Hybrid Development | Collapses chemical-resistant and thermal-shock-resistant category boundaries for cold-chain operators. |
| Egyptian Contractor Market Entry | Positions for Suez Canal Economic Zone automotive and textile facility maturation. |
Research Methodology
Operator-level perspectives from facility engineering directors, resin formulation technical leads, specialized flooring contractors, and pharmaceutical plant maintenance managers anchored the qualitative base. Primary interview insights triangulated against customs and trade data for epoxy resin imports, Gulf petrochemical complex output disclosures, and Saudi SFDA regulatory filings. Secondary validation drew from construction project databases tracking giga-project flooring packages, national building code updates across Dubai and Riyadh, and cold-chain logistics facility announcements. Bottom-up specification volume estimates reconciled with top-down market sizing across resin chemistry segments.
Sensitivity analysis tested forecast outputs against petrochemical feedstock price volatility scenarios and regulatory enforcement intensity variations across the projection horizon. Segmentation modeling spanned resin chemistry type, facility end-use sector, installation context, and performance tier. CAGRs derived from installation volume trajectories in Saudi giga-projects, GCC cold-chain expansion pipelines, and Egyptian manufacturing cluster maturation. Industry-specific inputs included SFDA hygiene mandate rollout schedules and green building code adoption curves in Dubai and Riyadh.
Underlying assumptions cover sustained Gulf construction velocity, stable multi-jurisdiction certification complexity, and continued petrochemical feedstock availability, with deviation risk concentrated in regulatory enforcement delays or contractor capacity bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
North America Roofing Market