
 Plastic Decking Market | 2026-2036
Plastic Decking Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Decking Market Intelligence
North American capacity expansion is reconfiguring competitive dynamics across the plastic decking supply base. Trex leverages in-house recycled polyethylene sourcing to control raw material costs and stabilize margins. Fiberon anchors its position through dedicated wood-plastic composite extrusion lines optimized for residential scale. MoistureShield differentiates via fully encapsulated board technology that competes directly with traditional hardwood aesthetics.
Plastic decking comprises extruded or molded polymer-based boards engineered for outdoor structural surfacing, typically formulated with PVC, polyethylene, or wood-plastic composite blends containing 40-70% recycled content by weight. The material resists moisture absorption, insect damage, and UV degradation while eliminating the periodic sealing required by natural lumber. Wood Plastic Composite occupies the largest volume share due to its balance of dimensional stability and timber-like appearance, while Recycled Plastics represents the fastest-expanding material category as brands respond to LEED and BREEAM procurement criteria. Solid Decking leads in commercial load-bearing specifications, though Hollow Decking gains traction among cost-sensitive residential developers seeking reduced freight weights.
EPA regulations on chromated copper arsenate lumber treatments and REACH restrictions on heavy metal preservatives in Europe are systematically removing competing materials from specification lists. OSHA workplace exposure standards for sawdust from tropical hardwoods further tilt commercial project bidding toward synthetic alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, as these jurisdictions are preparing end-of-life recovery mandates that will reshape formulation choices and collection infrastructure requirements.
Market Dynamics
Residential construction's pivot toward low-maintenance outdoor living spaces is compressing demand cycles for traditional lumber while expanding specification lists for synthetic alternatives. EPA restrictions on preservative-treated wood are systematically removing incumbent materials from building codes.
Growth Catalysts
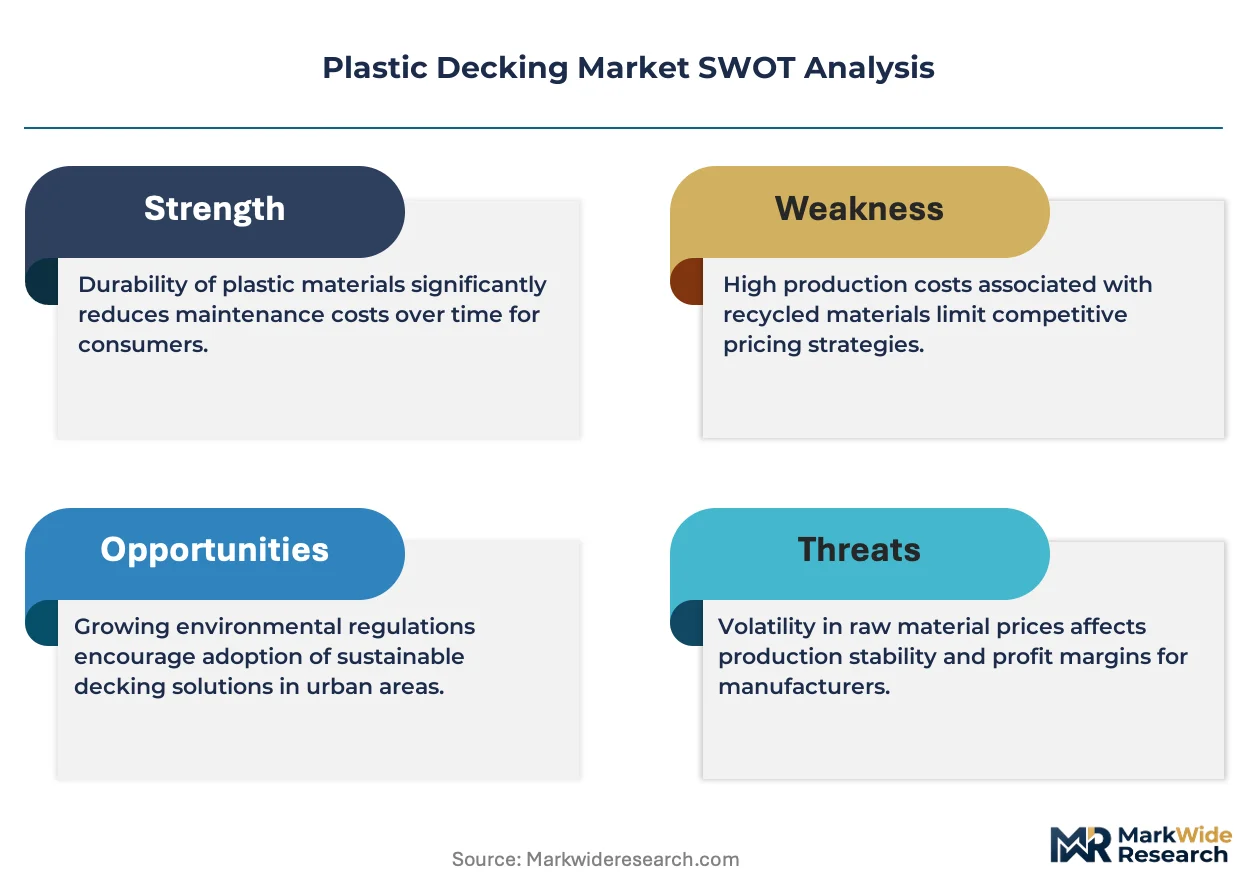
- REACH restrictions on heavy metal preservatives:European regulatory frameworks are eliminating competing tropical hardwood treatments from commercial specification lists, redirecting project bids toward composite alternatives.
- LEED and BREEAM procurement criteria:Green building certification systems are embedding recycled content thresholds that favor wood-plastic composite formulations in institutional construction.
- OSHA workplace exposure standards:Sawdust mitigation requirements for tropical hardwood cutting are tilting commercial decking contracts toward synthetic materials that generate cleaner fabrication environments.
Market Restraints
- Recycled polyethylene supply concentration:Post-consumer plastic feedstock availability clusters around municipal recycling infrastructure in the United States, creating geographic supply asymmetries.
- Thermal expansion differential:Composite boards exhibit greater dimensional movement across temperature cycles than natural lumber, complicating installation tolerances in extreme climate zones.
- Upfront cost premium:First-cost differentials against pressure-treated pine persist as a specification barrier in price-sensitive residential new construction segments.
Strategic Opportunities
- Extended producer responsibility mandates:California's pending end-of-life recovery frameworks will create first-mover advantages for brands with established take-back infrastructure.
- Marine and waterfront applications:Saltwater-immersion specifications represent an underpenetrated vertical where fully encapsulated board technology commands performance premiums.
- Direct-to-contractor digital platforms:Bypassing traditional lumberyard distribution is compressing lead times for renovation contractors in metropolitan renovation corridors.
Industry Challenges
- Extrusion technician scarcity:Wood-plastic composite manufacturing requires specialized process engineering expertise that outpaces vocational training program output.
- Color batch consistency:Pigment dispersion across recycled feedstock variability demands real-time quality systems that strain mid-scale production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Decking Market |
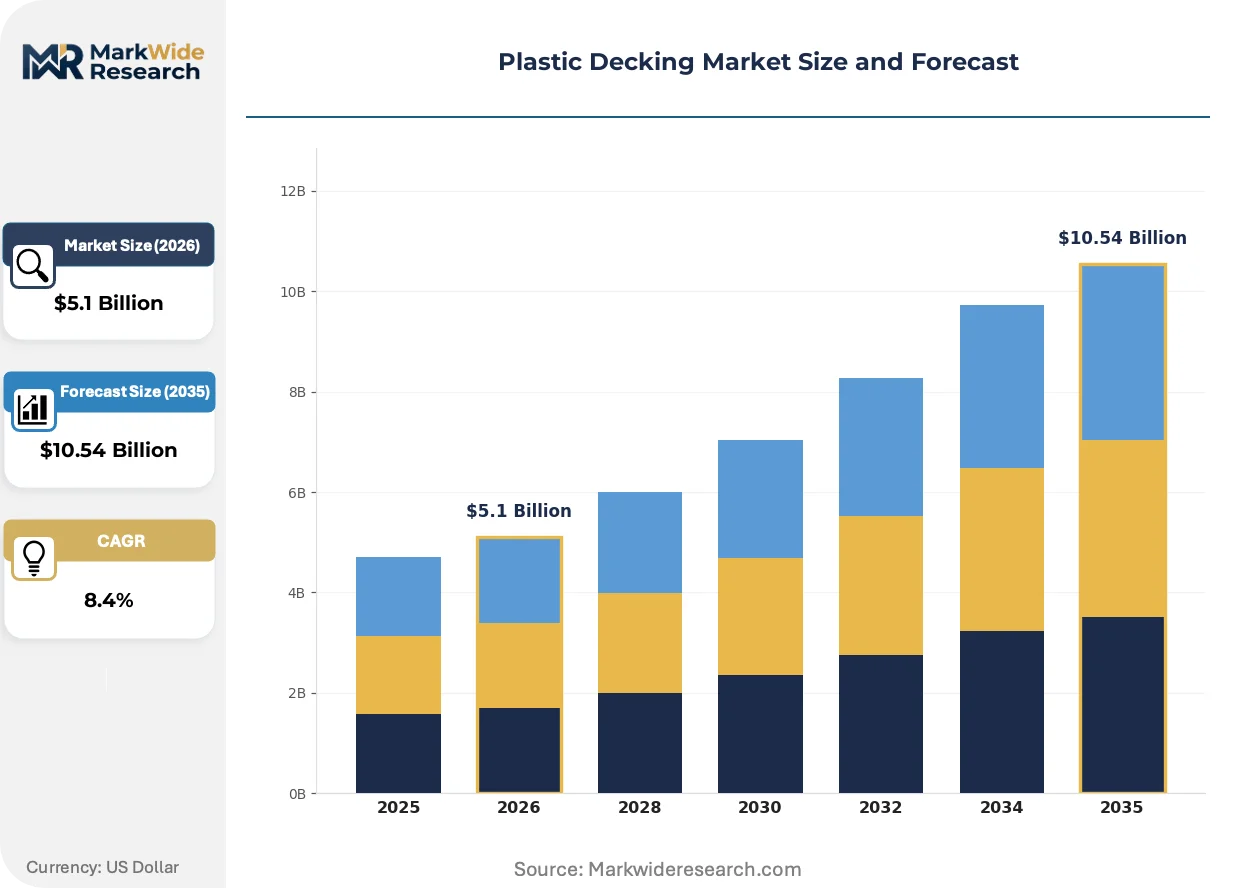
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyvinyl Chloride, Wood Plastic Composite, Polyethylene, Recycled Plastics, Thermoplastic Olefin Product Form: Solid Decking, Hollow Decking, Grooved Boards, Ribbed Boards, Perforated Decking Application: Residential Patios, Commercial Outdoor Spaces, Recreational Parks, Garden Pathways, Rooftop Decks End User: Homeowners, Commercial Property Developers, Landscaping Companies, Resort Operators, Facility Managers |
| Companies Covered | Zuri, Deckorators, Trex, MoistureShield, NewTechWood, TimberTech, Wolf, WearDeck, Fiberon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Decking Market Strategic Shifts & Innovations
Formulation science and regulatory compliance are converging to redefine performance benchmarks across outdoor surfacing categories. Material suppliers are racing to capture specification share as building codes harden against legacy preservatives.
Fully encapsulated board technology is collapsing the performance gap between synthetic decking and tropical hardwood aesthetics. High-end residential architects are specifying these products for waterfront properties where moisture resistance determines material selection. The technology is collapsing traditional tier boundaries between premium composite and exotic lumber categories.
EPA regulations on chromated copper arsenate treatments are systematically removing incumbent materials from specification lists. Lumberyards are destocking treated pine inventories as building codes adopt stricter preservative standards. Commercial project bidding in the United States is responding fastest, with synthetic alternatives capturing marina and boardwalk contracts.
Homeowner renovation cycles are compressing as digital design tools accelerate project visualization and material selection. Contractors are bypassing traditional lumberyard showrooms for manufacturer-direct sampling programs. This pattern concentrates in Sun Belt metropolitan areas where outdoor living renovation spending remains elevated year-round.
Plastic Decking Market Segmentation
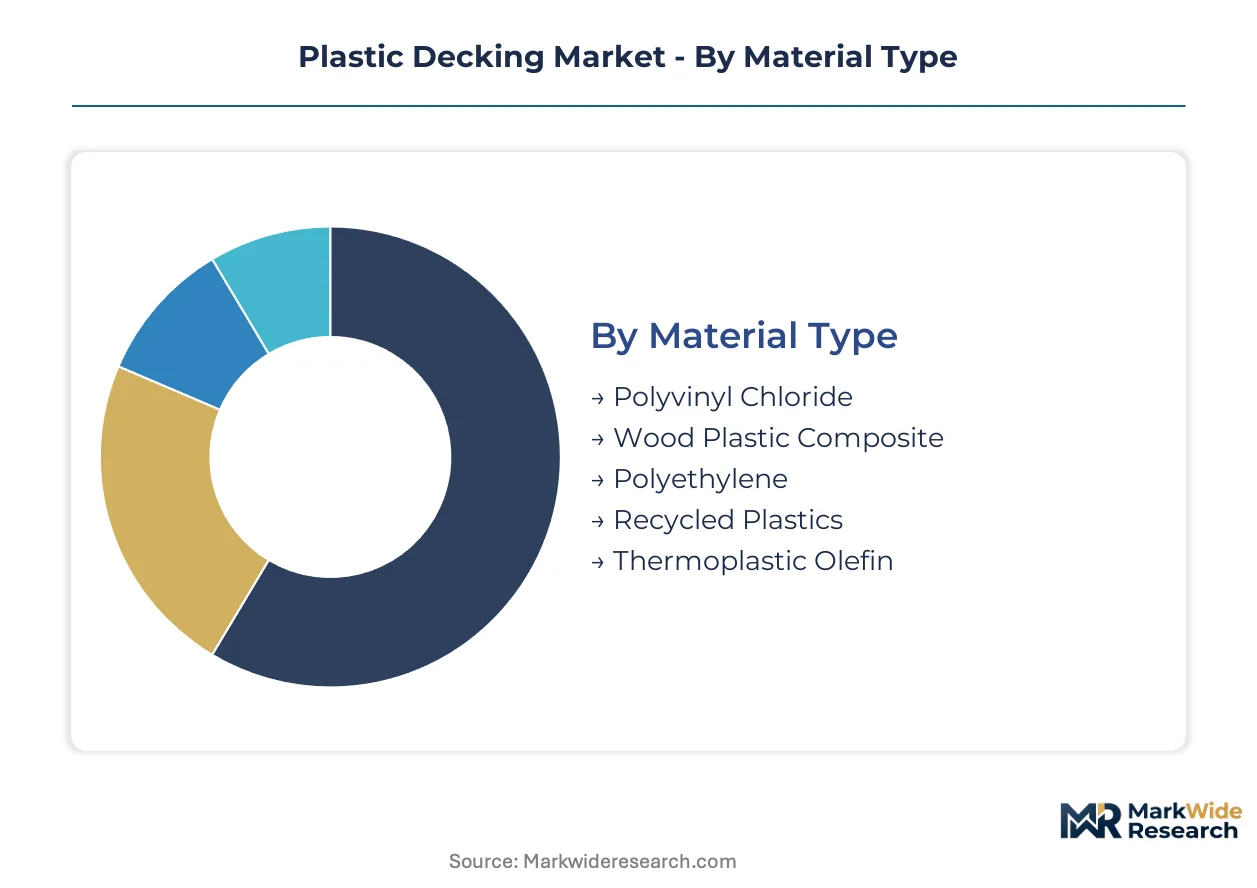
Material formulation and board architecture determine performance thresholds across climate zones and load requirements. Customer procurement patterns diverge sharply between renovation-driven homeowners and specification-driven commercial developers, creating distinct margin structures within each segment cluster.
Material Type:
Cost tier differentiation separates commodity feedstocks from engineered composite formulations with recycled content premiums.
- Wood Plastic Composite:Blends thermoplastic resins with wood flour at 40-70% recycled content ratios, delivering dimensional stability with timber aesthetics. Demand concentrates in United States residential patio renovations where homeowners prioritize low-maintenance durability over first-cost savings.
- Recycled Plastics:Formulated from post-consumer polyethylene and polypropylene streams, these boards carry LEED procurement advantages. Expansion accelerates fastest in California and EU markets where extended producer responsibility mandates reshape specification criteria.
- Polyvinyl Chloride:Virgin polymer formulations offer superior moisture resistance for waterfront applications.
- Polyethylene:High-density grades dominate hollow decking extrusion for weight-sensitive projects.
- Thermoplastic Olefin:Engineered for extreme UV exposure in Sun Belt metropolitan corridors.
Wood Plastic Composite commands the established base. The steepest expansion runs through Recycled Plastics.
Product Form:
Volume and freight economics drive specification trade-offs between structural mass and installation efficiency.
- Solid Decking:Full-profile extrusions deliver maximum load-bearing capacity for commercial boardwalks and marina installations. Demand clusters in United States waterfront developments where building engineers specify deflection resistance under concentrated live loads.
- Hollow Decking:Chambered internal structures reduce material weight by 30-40%, cutting freight costs for multi-story rooftop projects. Cost-sensitive residential developers in Texas and Florida metropolitan areas specify these for high-rise balcony installations.
- Grooved Boards:Edge profiles accommodate hidden fastening systems for premium residential finishes.
- Ribbed Boards:Surface textures enhance slip resistance for pool surround applications.
- Perforated Decking:Open-grid designs enable drainage in recreational park boardwalks.
Solid Decking anchors commercial specification. Hollow Decking is gaining share fastest among metropolitan residential developers.
Application:
Customer type and project scale segment performance requirements across structural and aesthetic dimensions.
- Residential Patios:Single-family renovation projects prioritize color consistency and hidden fastening compatibility. United States Sun Belt homeowners drive volume, with Phoenix and Atlanta metropolitan areas showing concentrated spending on outdoor living upgrades.
- Commercial Outdoor Spaces:Multi-tenant properties demand fire-rated assemblies and warranty-backed performance. Facility managers in California specify these for corporate campus installations where OSHA workplace exposure standards eliminate tropical hardwood alternatives.
- Recreational Parks:Municipal procurement emphasizes ADA-compliant surface traction and vandal resistance.
- Garden Pathways:Lightweight hollow boards suit residential landscaping with minimal structural requirements.
- Rooftop Decks:Dead-load restrictions favor thermoplastic formulations over traditional lumber.
Residential Patios holds the volume base. Commercial Outdoor Spaces is climbing the fastest as regulatory pressure accelerates synthetic substitution.
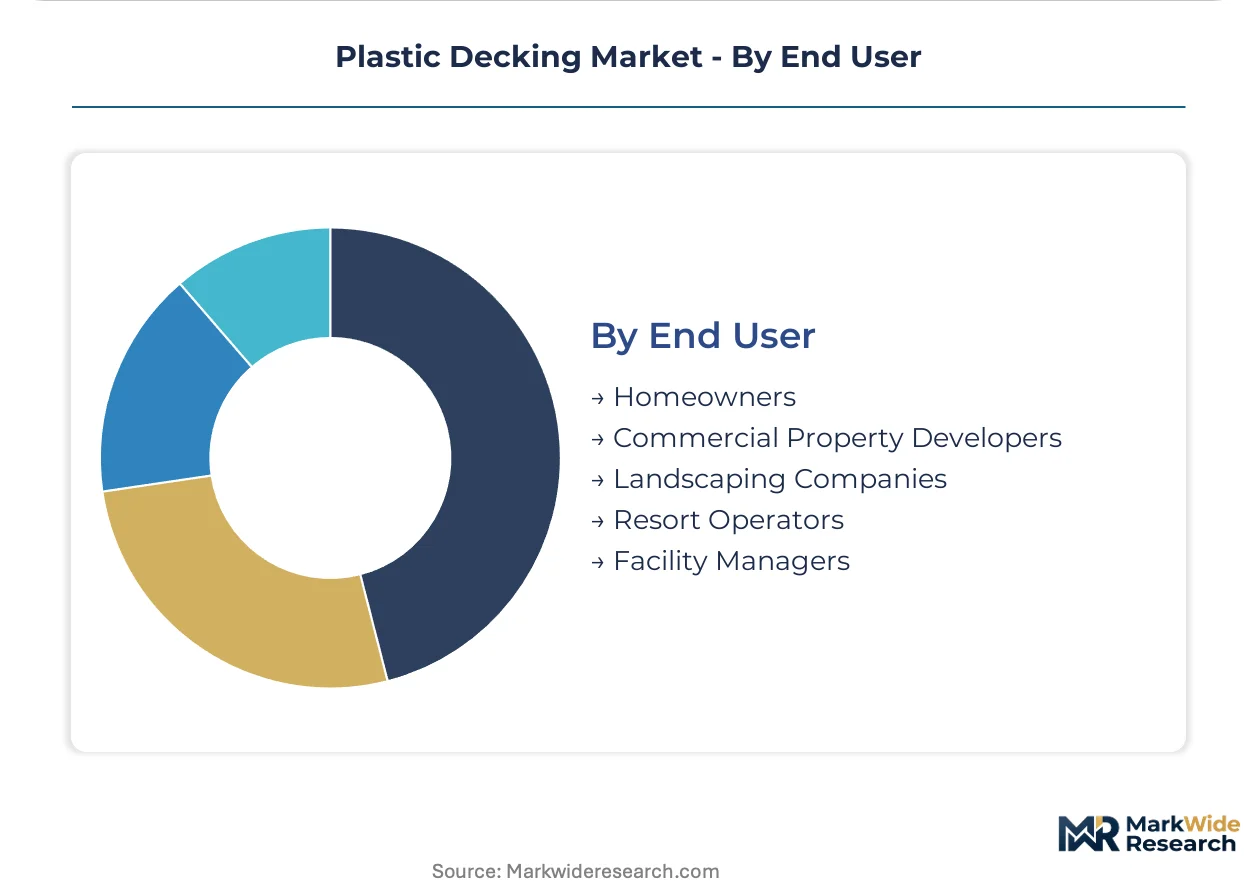
End User:
Procurement authority and project timeline urgency create divergent buying behaviors across customer categories.
- Homeowners:Direct purchasers research digital visualization tools before sampling, compressing decision cycles. Demand concentrates in United States renovation corridors where manufacturer-direct platforms bypass traditional lumberyard distribution.
- Commercial Property Developers:Institutional buyers embed recycled content thresholds into RFP specifications. LEED compliance requirements in California and New York tilt bidding toward wood-plastic composite suppliers with verified supply chain documentation.
- Landscaping Companies:Installation contractors prioritize board consistency and fastening system compatibility.
- Resort Operators:Waterfront properties specify fully encapsulated boards for salt-immersion durability.
- Facility Managers:Maintenance cost reduction drives synthetic replacement of aging tropical hardwood installations.
Homeowners represent the established demand base. Commercial Property Developers show the steepest expansion trajectory as green building certification systems harden procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA restrictions on chromated copper arsenate treatments are redirecting United States specification patterns toward synthetic alternatives. Outdoor living renovation spending concentrates in Sun Belt metropolitan corridors. Building codes across multiple jurisdictions are hardening against legacy wood preservatives.
United States
Residential patio construction drives volume in Phoenix and Atlanta metropolitan areas where homeowners prioritize low-maintenance durability. OSHA workplace exposure standards for tropical hardwood sawdust tilt commercial bidding toward composite materials. California's pending extended producer responsibility frameworks are reshaping formulation choices for brands serving the West Coast.
Canada
Waterfront property development in British Columbia and Ontario generates demand for moisture-resistant board technologies. Health Canada's PMRA maintains stringent preservative standards that limit pressure-treated lumber specifications. Vancouver and Toronto metropolitan clusters show concentrated adoption of recycled-content decking for green building compliance.
Germany
REACH restrictions on heavy metal preservatives eliminate competing tropical hardwood treatments from commercial specification lists. Municipal procurement in Bavaria and North Rhine-Westphalia embeds recycled content thresholds favoring wood-plastic composites. The country's national building energy codes are tightening material performance requirements for outdoor structural applications.
United Kingdom
LEED-equivalent BREEAM procurement criteria favor wood-plastic composite formulations in institutional construction projects. Greater London and Southeast England renovation corridors show accelerated homeowner adoption of digital design tools for material selection. The country's building regulations are systematically removing chromated copper arsenate lumber from approved material schedules.
Australia
Waterfront marina and boardwalk specifications in New South Wales and Queensland command performance premiums for fully encapsulated board technologies. The country's national construction code is adopting stricter durability standards for coastal structural applications. Sydney and Melbourne metropolitan areas concentrate renovation spending on outdoor living upgrades.
Plastic Decking Market Key Industry Players
Vertically integrated recyclers and specialized extrusion houses split the market into distinct capability tiers. The vendor base clusters around three strategic archetypes: in-house feedstock controllers optimizing raw material costs, dedicated composite specialists scaling residential production lines, and technology licensors differentiating through encapsulated board patents. Capacity expansion and direct-to-contractor digital platform development represent the dominant competitive moves reshaping distribution economics.
Among United States-based manufacturers, Trex and Fiberon exemplify the feedstock-control archetype through captive recycled polyethylene sourcing, while MoistureShield occupies a position within the technology-differentiation tier emphasizing moisture-barrier engineering. These three entities anchor the competitive structure visible in the North American supply base.
| Leading Market Players |
|---|
| Zuri |
| Deckorators |
| Trex |
| MoistureShield |
| NewTechWood |
| TimberTech |
| Wolf |
| WearDeck |
| Fiberon |
| Others |
Cost & Logistics Intelligence
Post-consumer polyethylene feedstock availability clusters around United States municipal recycling infrastructure, concentrating margin capture among manufacturers with captive sourcing arrangements in the Southeast and Midwest. This geographic asymmetry in recycled resin supply directly shapes where pricing power accrues downstream.
Pricing Analysis
United States Gulf Coast pricing for recycled polyethylene runs 15-20 percent below Pacific Coast delivered costs, compressing margins for West Coast extruders without rail-sourced feedstock contracts. Three-tier pricing structure across premium encapsulated, standard composite, and economy hollow board tiers separates MoistureShield's fully sealed products from Fiberon's residential lines from import PVC alternatives. Pricing pressure stems from freight cost inflation on hollow decking shipments to multi-story rooftop projects. Price-sensitive residential developers in Texas and Florida metropolitan areas drive volume at the economy tier, while resort operators on waterfront properties show minimal sensitivity to premium positioning.
Supply Chain Analysis
Contract manufacturing for wood-plastic composite extrusion concentrates with specialized compounding houses in Ohio, Pennsylvania, and Ontario that operate dedicated WPC production lines. Geographic supply concentration centers on the United States Great Lakes region, Southern Ontario, and select Bavarian industrial clusters in Germany. Raw material dependencies include post-consumer HDPE milk jug streams, wood flour from furniture manufacturing residue, and virgin PVC resin from petrochemical complexes. Single-source vulnerability runs through municipal recycling contract renewals that gate recycled polyethylene availability. Distribution runs through lumberyard networks in renovation corridors, with direct-to-contractor platforms gaining share in Sun Belt metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic decking sits in early-cycle expansion as EPA restrictions on preservative-treated lumber systematically remove incumbent materials from building codes across multiple United States jurisdictions. This regulatory tailwind accelerates specification substitution faster than penetration saturation.
For Market Incumbents: Harden feedstock security through long-term municipal recycling contracts or backward integration into post-consumer plastic collection infrastructure. Trex's captive polyethylene sourcing model demonstrates how upstream control defends margin position against resin price volatility. Capacity additions in Southeast United States recycling corridors would preempt emerging entrant access to lowest-cost feedstock basins. For New Entrants and Emerging Players: Build out marine and waterfront application expertise where fully encapsulated board technology commands performance premiums and incumbent penetration remains shallow. Saltwater-immersion specifications for marina and boardwalk projects represent the most penetrable vertical. A go-to-market angle anchored in coastal contractor direct sampling programs bypasses established lumberyard gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed extrusion specialists in the United States Midwest that consolidated during the previous decade but lack brand recognition in coastal specification markets. Long-term viability across a 5-10 year window hinges on positioning for California extended producer responsibility mandates. The signal to watch is municipal procurement RFP language embedding recycled content thresholds and take-back infrastructure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycled Feedstock Integration | Trex's in-house polyethylene sourcing stabilizes margin volatility against municipal contract renewal cycles. |
| Direct-to-Contractor Digital Platform | Manufacturer-direct sampling compresses lead times for Phoenix and Atlanta renovation contractors. |
| Fully Encapsulated Board Patent Licensing | MoistureShield's moisture-barrier technology collapses performance gaps with tropical hardwood aesthetics. |
| Extended Producer Responsibility Infrastructure | California's pending take-back mandates will reshape formulation choices and collection network requirements. |
| Marine Specification Certification Investment | Saltwater-immersion testing protocols unlock marina and boardwalk contracts with performance premiums. |
Research Approach
A spread of perspectives from composite extrusion plant managers, lumberyard procurement directors, residential renovation contractors, and municipal recycling program administrators converged on the working assumptions. Primary fieldwork combined structured interviews with downstream specification influencers and upstream feedstock suppliers. Secondary validation drew from EPA regulatory filings, OSHA workplace exposure standards documentation, LEED and BREEAM certification databases, and building code adoption records across United States jurisdictions. Bottom-up volume estimates from extrusion line capacity and top-down demand triangulation from construction spending data were reconciled.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material formulation tier, board architecture type, application vertical, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted substitution curves against pressure-treated lumber and tropical hardwood baselines. Industry-specific forecast inputs incorporated EPA enforcement timelines for chromated copper arsenate restrictions and California extended producer responsibility implementation trajectories.
Stress conditions across recycled polyethylene feedstock availability, freight cost inflation, and regulatory enforcement pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticity and specification inertia in commercial construction. Quarterly review of municipal recycling contract awards and building code amendment dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Europe Faucet Market