
 Industrial Concrete Flooring Market | 2026-2036
Industrial Concrete Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Concrete Flooring Market Analysis
Modular specification bundles combining epoxy coatings with diamond-polished substrates is hardening as the default procurement format for warehouse and distribution center operators. Sika AG leverages its integrated adhesives and coatings portfolio to anchor large-scale logistics projects across Europe. MBCC Group differentiates through specialized self-leveling compounds and trowel-applied systems for heavy manufacturing environments. RPM International Inc. competes via broad brand architecture spanning industrial maintenance coatings and concrete repair solutions.
Industrial concrete flooring comprises cementitious slab systems treated with mechanical or chemical processes to achieve specified surface hardness, flatness tolerances, and chemical resistance for commercial and industrial facilities. Polished concrete surfaces achieve Mohs hardness ratings of 7-8 through progressive diamond-grit refinement, delivering dust-free environments critical for pharmaceutical and food-processing plants. Epoxy coatings command premium positioning in manufacturing plants due to superior resistance to acids, solvents, and thermal shock from process equipment. Overlay systems represent the fastest-growing installation category as facility managers prioritize rapid turnaround over full slab replacement.
The US EPA regulates VOC content in concrete coatings through national architectural and industrial maintenance standards, while the EU REACH framework restricts hazardous substances in hardeners and solvents used in epoxy formulations. OSHA slip-resistance requirements and FDA food-contact surface standards further shape product development priorities for US-facing suppliers. Stakeholders must monitor evolving low-carbon cement specifications and embodied carbon disclosure mandates that will soon filter into industrial construction procurement criteria.
Market Dynamics
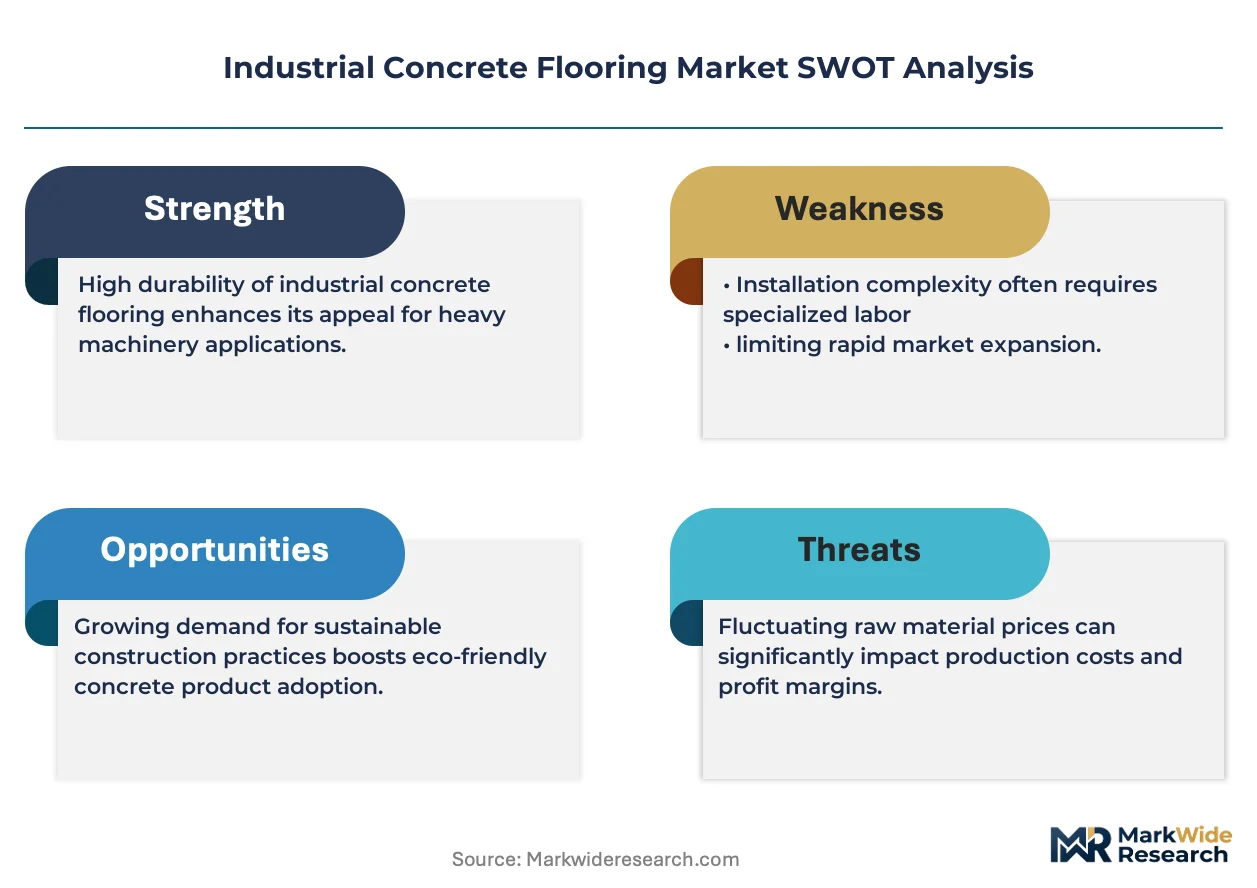
Regulatory tightening around VOC emissions is compressing formulation choices while accelerating specification of water-based epoxy systems and mechanically polished substrates across warehouse and distribution center construction.
Growth Catalysts
- EU REACH restrictions on hazardous hardeners:Procurement teams in Germany and the Netherlands are redirecting volume toward low-emission coating systems. This regulatory pressure is expanding the addressable market for water-based epoxy formulations.
- Warehouses and distribution centers:E-commerce fulfillment networks in China and India are specifying diamond-polished concrete with integrated joint fillers to achieve 24-hour operational readiness. Surface flatness tolerances of FF50+ are becoming standard procurement criteria.
- Overlay installation systems:Rapid-cure cementitious toppings are displacing full slab replacement in manufacturing plant retrofits. Facility managers prioritize 72-hour turnaround windows over extended downtime.
Market Restraints
- Petrochemical input volatility:Epoxy resin prices fluctuate with benzene and propylene feedstock markets. Formulators lack pricing power to pass through sustained cost spikes to locked construction contracts.
- Specialized applicator concentration:Certified diamond-polishing contractors cluster in Germany, the United States, and Japan. Project timelines in emerging markets stretch due to equipment and technician scarcity.
- Polyurethane coating substitution:Hybrid polyurethane systems capture specification share in light industrial settings where chemical resistance requirements are moderate. Epoxy coatings face displacement in non-heavy manufacturing segments.
Strategic Opportunities
- India manufacturing corridor buildouts:The Delhi-Mumbai Industrial Corridor and Tamil Nadu electronics parks are greenfield sites specifying polished concrete with conductive static-dissipative coatings. First-mover applicators are securing multi-year maintenance contracts.
- US Inflation Reduction Act clean energy incentives:Battery gigafactory construction in Nevada, Georgia, and Michigan is specifying acid-resistant epoxy systems for electrolyte handling zones. Chemical resistance testing to ASTM C267 is becoming a bid requirement.
- IoT-enabled floor condition monitoring:Embedded moisture sensors and wear-depth detectors are converging with maintenance management software. Predictive resurfacing schedules are replacing fixed-interval maintenance in pharmaceutical and food-processing plants.
Industry Challenges
- Diamond-grit technician certification:CPC- and F-Number-qualified flatness specialists command wage premiums exceeding 40% above standard concrete finishers. Training pipeline capacity limits project scaling.
- Slab moisture vapor emission testing:ASTM F1869 calcium chloride and ASTM F2170 in-situ RH testing add 7-14 days to project schedules. Coating failures from untested slabs drive warranty disputes and rework costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Concrete Flooring Market |
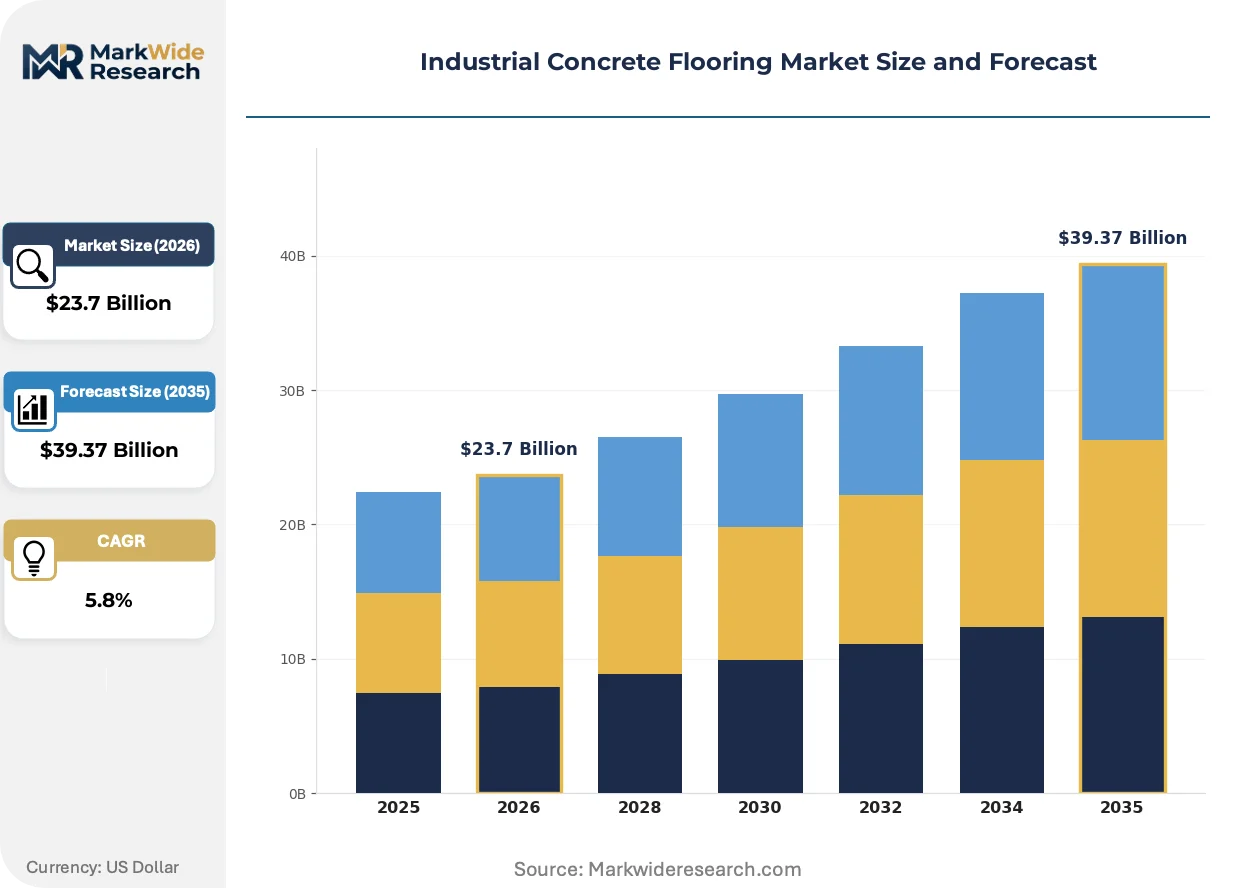
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polished Concrete, Stained Concrete, Epoxy Coatings, Overlay Systems Application: Warehouses, Manufacturing Plants, Retail Spaces, Distribution Centers Installation Method: Diamond Polishing, Self-Leveling, Trowel Applied, Stamped End User: Construction Companies, Property Developers, Industrial Facilities, Commercial Spaces |
| Companies Covered | The Sherwin-Williams Company, PPG Industries Inc., Sika AG, Henkel Corporation, Nippon Paint Holdings Co. Ltd, MBCC Group, Akzo Nobel N.V., JOTUN, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Concrete Flooring Market Emerging Trajectories
Surface preparation and coating application technologies are converging with digital specification tools and embedded sensor systems, compressing project timelines while extending performance warranties.
Laser-guided screeding and ride-on power trowels equipped with GPS flatness mapping are decentralizing quality control from manual string-line verification to real-time automated adjustment. Warehouse developers in Germany and the United States are adopting these systems to guarantee FF60+ floor flatness specifications on 100,000-square-meter slabs. The technology is decentralizing subcontractor risk allocation by embedding performance verification into equipment operation rather than post-pour inspection.
The US EPA's architectural and industrial maintenance coating VOC limits are tightening permissible solvent content in epoxy formulations. Manufacturers are responding with waterborne and high-solids systems that trade extended cure times for regulatory compliance. Food-processing and pharmaceutical facilities in California and the Northeast are absorbing premium pricing to meet both EPA standards and FDA food-contact surface requirements.
Facility managers are unbundling installation and maintenance contracts, separating initial surface preparation from multi-year performance warranties. Third-party certification bodies such as ISO and independent flooring consultants are inserting themselves between owners and applicators to arbitrate warranty claims. This pattern is most pronounced in the United States and United Kingdom, where private equity-owned logistics real estate platforms prioritize operational expenditure predictability over lowest-first-cost procurement.
Industrial Concrete Flooring Market Segmentation
Industrial concrete flooring procurement varies sharply by operational intensity, chemical exposure risk, and speed-to-occupancy requirements. Specification bundles differ fundamentally between high-turnover logistics facilities and heavy manufacturing environments with process equipment thermal shock exposure.
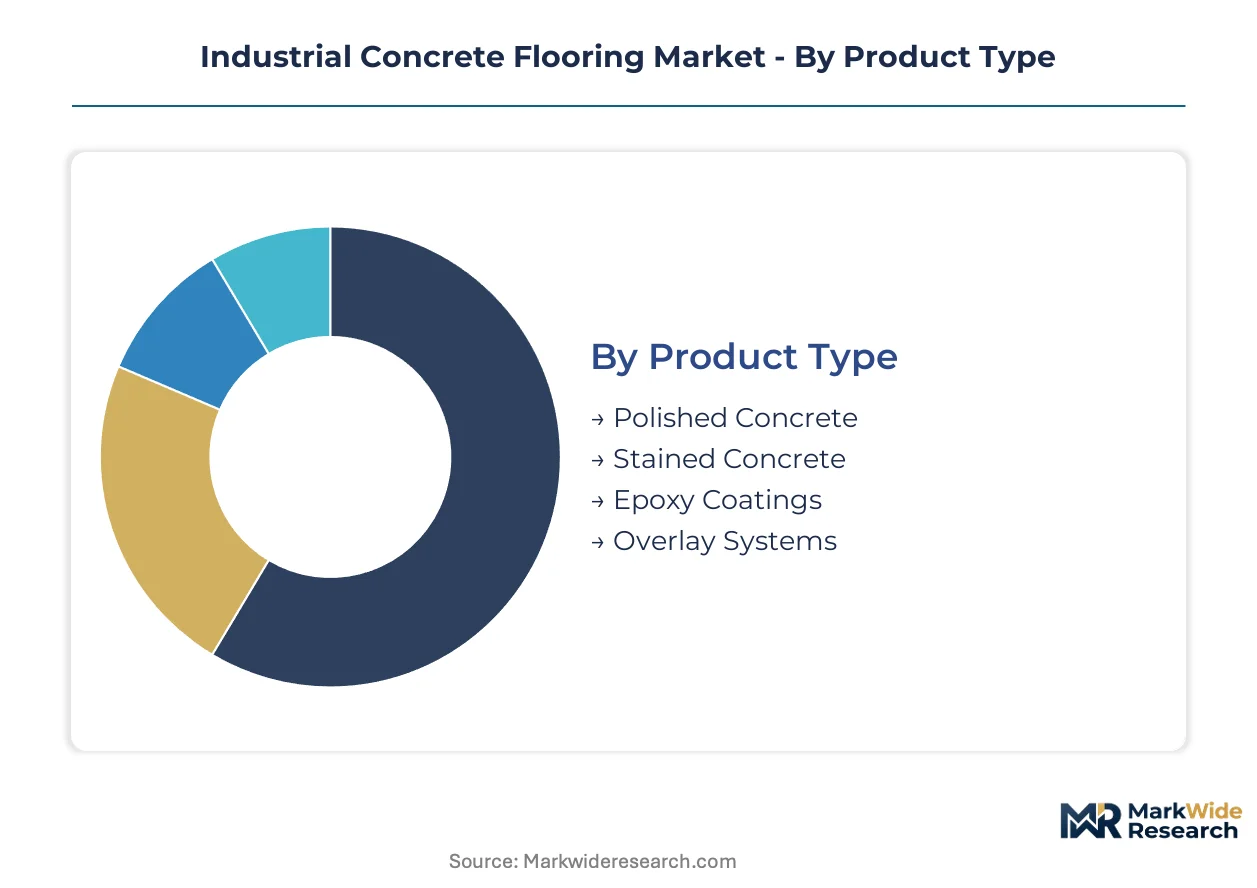
Product Type:
Volume concentrates in mechanically refined substrates, while premium capture belongs to chemically resistant coating systems with extended performance warranties.
- Polished Concrete:Progressive diamond-grit refinement achieves Mohs hardness ratings of 7-8 and dust-free surfaces without topical coatings. E-commerce fulfillment networks in China and India specify FF50+ flatness tolerances with integrated joint fillers for 24-hour operational readiness.
- Epoxy Coatings:Two-component thermosetting systems deliver superior resistance to acids, solvents, and thermal shock from process equipment. Battery gigafactory construction in Nevada, Georgia, and Michigan specifies acid-resistant formulations for electrolyte handling zones with ASTM C267 chemical resistance testing as a bid requirement.
- Stained Concrete:Reactive metallic salts penetrate cementitious substrates to produce decorative color variation without film-forming layers. Retail environments and commercial showrooms absorb premium pricing for aesthetic differentiation.
- Overlay Systems:Rapid-cure cementitious toppings displace full slab replacement in manufacturing retrofits. Facility managers prioritize 72-hour turnaround windows over extended downtime.
Mature deployment sits with polished concrete in warehouse and distribution center specifications. Newer deployment is concentrated in epoxy coating systems for battery manufacturing and pharmaceutical cleanroom environments.
Application:
Procurement scale tracks logistics infrastructure buildout velocity, with manufacturing specifications commanding premium coating complexity.
- Warehouses:Diamond-polished concrete with conductive static-dissipative coatings dominates specifications for the Delhi-Mumbai Industrial Corridor and Tamil Nadu electronics parks. First-mover applicators secure multi-year maintenance contracts.
- Manufacturing Plants:Heavy equipment load-bearing requirements and chemical exposure drive specification of trowel-applied epoxy systems with self-leveling underlayments. EU REACH restrictions on hazardous hardeners redirect procurement toward low-emission formulations in Germany and the Netherlands.
- Distribution Centers:Laser-guided screeding and GPS flatness mapping guarantee FF60+ specifications on 100,000-square-meter slabs. Automated quality control embeds performance verification into equipment operation.
- Retail Spaces:Aesthetic priorities favor stained concrete and polished substrates with decorative aggregate exposure. Foot traffic intensity determines sealer specification grade.
Established specification patterns dominate warehouse and distribution center construction. Steepest expansion trajectory belongs to manufacturing plant retrofits with overlay systems replacing full slab replacement.
Installation Method:
Equipment intensity separates high-precision mechanical refinement from labor-intensive hand-applied systems.
- Diamond Polishing:Multi-stage grit progression from 30-metal to 3000-resin achieves specified gloss and hardness metrics. Certified CPC- and F-Number-qualified flatness specialists command wage premiums exceeding 40% above standard concrete finishers.
- Self-Leveling:Cementitious or epoxy-based pump-applied compounds achieve 3mm tolerance over 2 meters. MBCC Group differentiates through specialized formulations for heavy manufacturing environments.
- Trowel Applied:Hand-finishing or power-trowel placement of epoxy mortars and resurfacers accommodates irregular substrates. Applicator skill concentration limits project scaling in emerging markets.
- Stamped:Patterned mat impression into plastic concrete creates textured surfaces for aesthetic or slip-resistance requirements. Commercial plaza and hospitality applications absorb higher maintenance cycles.
Equipment-dependent methods dominate new construction specifications. Labor-intensive techniques persist in retrofit and decorative applications.
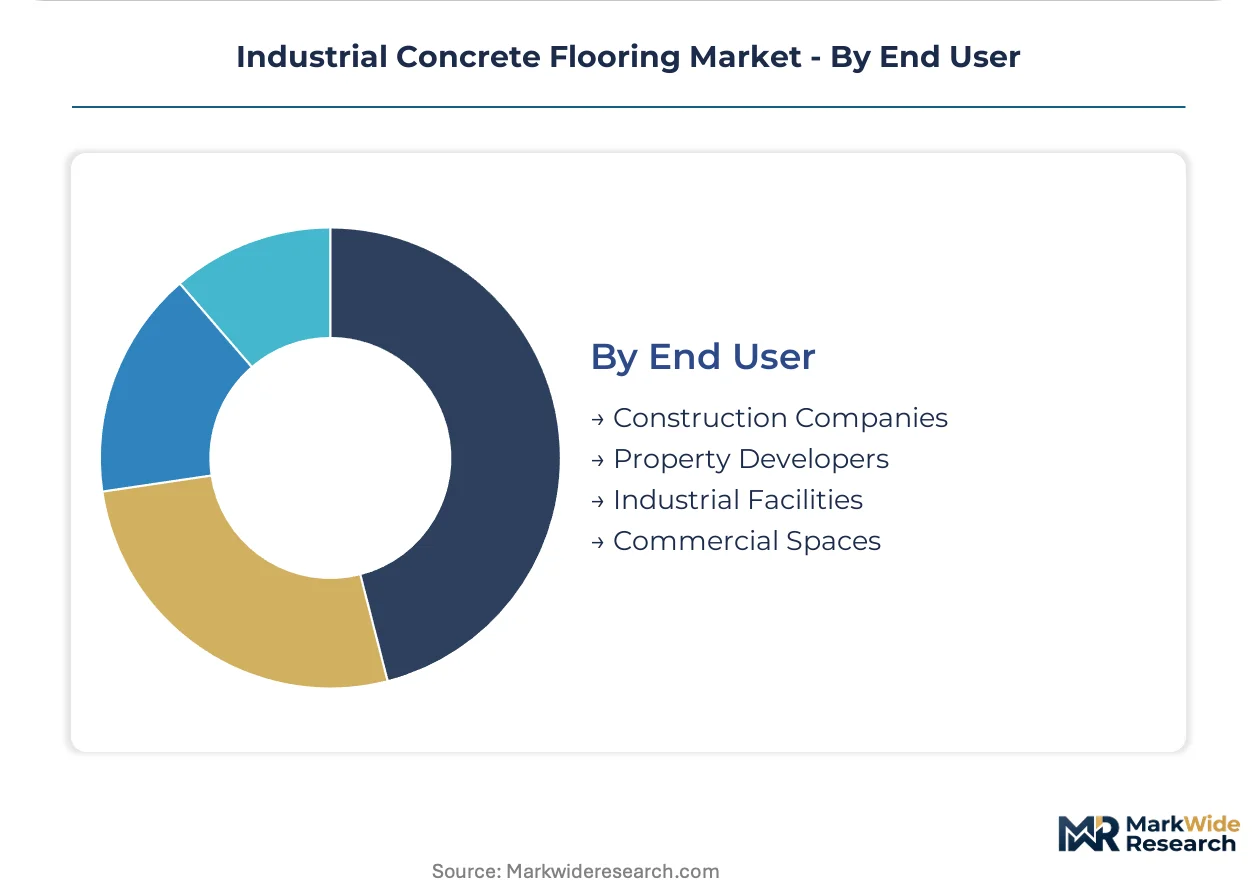
End User:
Contractor procurement behavior differs from owner-direct specification on risk allocation and warranty structure.
- Construction Companies:Bid-driven procurement prioritizes first-cost minimization with standard performance specifications. Locked construction contracts limit formulator pricing power during petrochemical input volatility.
- Industrial Facilities:Owner-operators unbundle installation and maintenance contracts, separating initial surface preparation from multi-year performance warranties. Third-party certification bodies arbitrate warranty claims.
- Property Developers:Private equity-owned logistics real estate platforms prioritize operational expenditure predictability over lowest-first-cost procurement. Predictive resurfacing schedules replace fixed-interval maintenance.
- Commercial Spaces:Tenant improvement specifications balance aesthetic impact with durability requirements. Turnkey contractor relationships dominate procurement channels.
Institutional knowledge concentrates with industrial facility operators. Specification innovation emerges from developer platforms with portfolio-scale maintenance data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and industrial corridor programs are concentrating demand across manufacturing belts, with tax incentives redirecting warehouse and logistics construction toward designated development nodes.
United States
Battery gigafactory construction in Nevada, Georgia, and Michigan drives specification of acid-resistant epoxy systems for electrolyte handling zones. The US EPA's architectural and industrial maintenance coating VOC limits tighten permissible solvent content in formulations. Dallas-Fort Worth and Chicago logistics hubs adopt laser-guided screeding with GPS flatness mapping to guarantee FF60+ specifications on mega-distribution slabs.
China
E-commerce fulfillment networks in the Yangtze River Delta and Pearl River Delta specify diamond-polished concrete with integrated joint fillers for 24-hour operational readiness. The country's national environmental regulator enforces dual carbon goals that filter into low-emission construction procurement criteria. Shenzhen and Shanghai electronics parks anchor demand for conductive static-dissipative coatings in semiconductor fabrication facilities.
Germany
EU REACH restrictions on hazardous hardeners in epoxy formulations redirect procurement toward water-based systems in automotive manufacturing plants. The country's federal environmental agency enforces stringent VOC thresholds that exceed baseline EU requirements. Bavaria and Baden-Württemberg industrial zones concentrate certified diamond-polishing contractors with CPC- and F-Number-qualified flatness specialists.
India
The Delhi-Mumbai Industrial Corridor and Tamil Nadu electronics parks specify polished concrete with conductive coatings for greenfield manufacturing sites. The country's national standards body issues construction material specifications that accelerate adoption of industrial-grade flooring systems. First-mover applicators in Gujarat and Karnataka secure multi-year maintenance contracts with automotive and electronics manufacturers.
Industrial Concrete Flooring Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, installation equipment, and applicator certification tiers. Market structure fragments across adhesive manufacturers pivoting into coatings, construction chemical specialists, and industrial maintenance service platforms. Three archetypes dominate: integrated construction chemical suppliers, coating-focused multinationals with broad brand architectures, and regional applicator networks with captive equipment fleets. Consolidation pressures intensify through backward integration into resin production and forward integration into certified installation services.
Within the integrated supplier tier, Sika AG anchors European logistics projects through combined adhesives and coatings portfolios. MBCC Group exemplifies specialized compound manufacturers with self-leveling and trowel-applied system expertise. RPM International Inc. occupies a position spanning industrial maintenance coatings and concrete repair solutions across North American distribution networks. These three entities represent distinct strategic postures: geographic anchoring, technical specialization, and portfolio breadth.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| Sika AG |
| Henkel Corporation |
| Nippon Paint Holdings Co. Ltd |
| MBCC Group |
| Akzo Nobel N.V. |
| JOTUN |
| RPM International Inc. |
| Others |
Supply Flow & Price Mechanics
Captive integration into resin production anchors pricing power for epoxy formulators serving battery gigafactory and pharmaceutical cleanroom contracts. Construction chemical suppliers with in-house benzene derivative capacity insulate margin structures from petrochemical feedstock volatility that compresses spot-market competitors.
Pricing Analysis
Short-lead-time premiums dominate project-based contracting as facility managers prioritize 72-hour overlay turnaround over standard 14-day cure schedules. Three-tier pricing structure across premium, standard, and economy levels separates diamond-polished FF60+ specifications from basic trowel-applied systems. Cost compression in water-based epoxy formulations is intensifying because REACH-compliant hardeners carry raw material premiums. General construction contractors exhibit highest price sensitivity while private equity-owned logistics platforms absorb premium pricing for multi-year performance warranties.
Supply Chain Analysis
Refurbishment flows from failed coating installations in US distribution centers create secondary demand for diamond-grit reprocessing services. Manufacturing concentration centers on Germany, China, and the United States for precision polishing equipment and epoxy resin production. Raw material sourcing draws from benzene and propylene feedstock markets in the US Gulf Coast and Middle East. Single-source vulnerability sits with certified CPC- and F-Number-qualified flatness specialists clustering in Bavaria and Baden-Württemberg. Distribution runs through applicator networks with captive equipment fleets rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified diamond-polishing technician scarcity props pricing for FF50+ flatness specifications as training pipeline capacity constrains project scaling across emerging markets.
For Market Incumbents: Hedge against polyurethane coating substitution in light industrial segments by accelerating water-based epoxy R&D to capture EU REACH-mandated procurement shifts. Backward integration into low-emission hardener production defends margin position against petrochemical input volatility. Channel control through captive applicator certification programs limits technician wage premium leakage to independent contractors. For New Entrants and Emerging Players: The price-point gap between premium diamond-polished systems and economy-grade stained concrete creates white-space capture opportunity in India manufacturing corridor buildouts. Target Gujarat and Karnataka automotive electronics parks with conductive static-dissipative coating bundles. Go-to-market angle centers on multi-year maintenance contract anchoring against first-cost-focused construction bidders. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified construction chemical conglomerates seeking regional applicator network scale. Long-term viability frames around portfolio-scale maintenance data platforms replacing fixed-interval resurfacing schedules. Acquisition target archetype: regional diamond-polishing contractors with CPC certification density. Signal to watch: EPA VOC threshold tightening accelerating water-based formulation adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Applicator Network Expansion | CPC-qualified technician pipelines in India and Germany lock in multi-year logistics contracts. |
| Water-Based Epoxy R&D Scale-Up | REACH-compliant formulations capture redirected procurement from German automotive plants. |
| Embedded Sensor Integration | IoT-enabled wear-depth detectors extend maintenance contract renewal rates in pharmaceutical facilities. |
| Regional Resin Production Footprint | Captive benzene derivative capacity insulates margin structures from Gulf Coast feedstock volatility. |
| Overlay System Rapid-Cure Formulation | 72-hour turnaround specifications displace full slab replacement in US manufacturing retrofits. |
Methodological Framework
Document review covered customs and trade data, EPA VOC compliance filings, and EU REACH substance restriction updates, complemented by interviews with plant engineers at battery gigafactories, procurement leads at logistics real estate platforms, diamond-polishing contractors with CPC certification, and technical R&D directors at construction chemical suppliers. Secondary validation drew from SEC 10-K disclosures, national standards body specifications, and industrial flooring warranty claim databases. Bottom-up project pipeline tracking triangulated against top-down construction spending forecasts.
Cross-reference between historical installation volume patterns and expert panel input on specification shift timing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include surface treatment type, installation method equipment intensity, end-use operational environment, and regional regulatory stringency tier. CAGRs derived from slope consensus across triangulated demand drivers. Industry-specific forecast inputs incorporated ASTM F1869 moisture testing adoption curves and laser-guided screeding equipment deployment rates.
Inputs from certified applicator trade associations and coating manufacturer technical service departments were available through the study window; gaps in real-time project cancellation data introduce uncertainty bands around near-term overlay system demand. Forecasts reflect assumptions on EPA VOC threshold evolution and EU REACH substance list expansion. Practitioners should monitor technician certification pipeline capacity and battery gigafactory construction permit approvals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Light Gauge Steel Framing Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Shotcrete Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Sprayed Concrete Market
Building Materials
Composite Decking and Railing Market
Building Materials
Roof Cover Boards Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Iron and Steel Slag Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Steel Sleepers Market
Building Materials
Africa Green Cement Market
Building Materials
Glass Facade Market
Building Materials
Cribbing Blocks Market