
 Blind Bolts Market | 2026-2036
Blind Bolts Market Size, Share, and Industry Trends Forecast 2026-2036
Blind Bolts Market Intelligence
The capability gap between vertically integrated fastener specialists and component assemblers is collapsing as tier-one suppliers internalize precision forging and heat-treatment operations. Hilti Group leverages its captive metallurgy labs to control titanium-grade consistency from billet to finished fastener. Bollhoff Group anchors its position through dedicated aerospace accreditation sites in Germany and North America. SFS Group AG differentiates via automated cold-forming cells that compress lot-to-lot variation below aviation tolerance thresholds.
Blind bolts are one-sided installation fasteners engineered with a collapsible sleeve or expanding body that forms a blind-side bulb when torque is applied, typically achieving shear strengths from 95 ksi to 160 ksi depending on alloy grade. They secure structural joints where rear access is impossible, such as wing box assemblies, ship hull compartments, and steel framing nodes. Heavy-duty blind bolts dominate commercial aerospace bill-of-materials due to fatigue-rated performance under cyclic loading, while titanium blind bolts represent the fastest-expanding material class as OEMs pursue airframe weight reduction targets. Mechanical installation methods retain the largest installed base, though hydraulic systems gain share in high-volume automotive chassis applications.
FAA airworthiness standards and EASA Part 21 production organization approvals mandate lot traceability and mechanical testing documentation for every aerospace fastener batch. REACH restrictions on hexavalent chromium coatings push European suppliers toward zinc-nickel and ceramic conversion alternatives. Stakeholders must monitor evolving OEM qualification timelines and dual-source requirements as supply chain resilience clauses harden across Boeing, Airbus, and tier-one contracts.
Market Dynamics
OEM fastener qualification timelines are compressing as Boeing and Airbus dual-source requirements harden, forcing tier-one suppliers to internalize heat-treatment and precision forging capabilities previously outsourced to specialty metallurgy houses.
Growth Catalysts
- REACH hexavalent chromium restrictions:European coating bans accelerate zinc-nickel and ceramic conversion adoption, creating upgrade cycles across installed aerospace fastener bases.
- Single-aisle production ramp:Airbus A320 family and Boeing 737 MAX assembly lines in Toulouse, Hamburg, and Renton consume fatigue-rated heavy-duty blind bolts at elevated volumes.
- Titanium alloy substitution:95 ksi to 160 ksi shear-strength titanium grades displace steel variants in wing box assemblies where rear access is structurally impossible.
Market Restraints
- Titanium sponge volatility:Russian and Ukrainian feedstock disruptions concentrate supply risk with three non-Chinese sponge producers.
- FAA/EASA lot traceability mandates:Mechanical testing documentation requirements extend batch release cycles by 15-20% for non-vertically integrated suppliers.
- Lockbolt mechanical interference:Two-sided installation alternatives retain cost advantages in ship hull and steel framing applications with rear access.
Strategic Opportunities
- Indian defense aerospace:Hindustan Aeronautics Limited indigenization mandates open qualification pathways for foreign fastener specialists with BIS certification.
- Hydraulic installation systems:Automated torque-and-tension equipment converges with automotive chassis high-volume assembly lines in Stuttgart and Wolfsburg.
- EU Green Deal circularity requirements:Remanufacturing clauses in aerospace procurement contracts favor fastener designs with reusable sleeve architectures.
Industry Challenges
- Heat-treatment technician scarcity:Vacuum furnace operation and metallurgical process control expertise concentrates with retiring aerospace workforce cohorts.
- OEM qualification timeline compression:Boeing and Airbus dual-source mandates require parallel PPAP submissions that strain engineering validation bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blind Bolts Market |
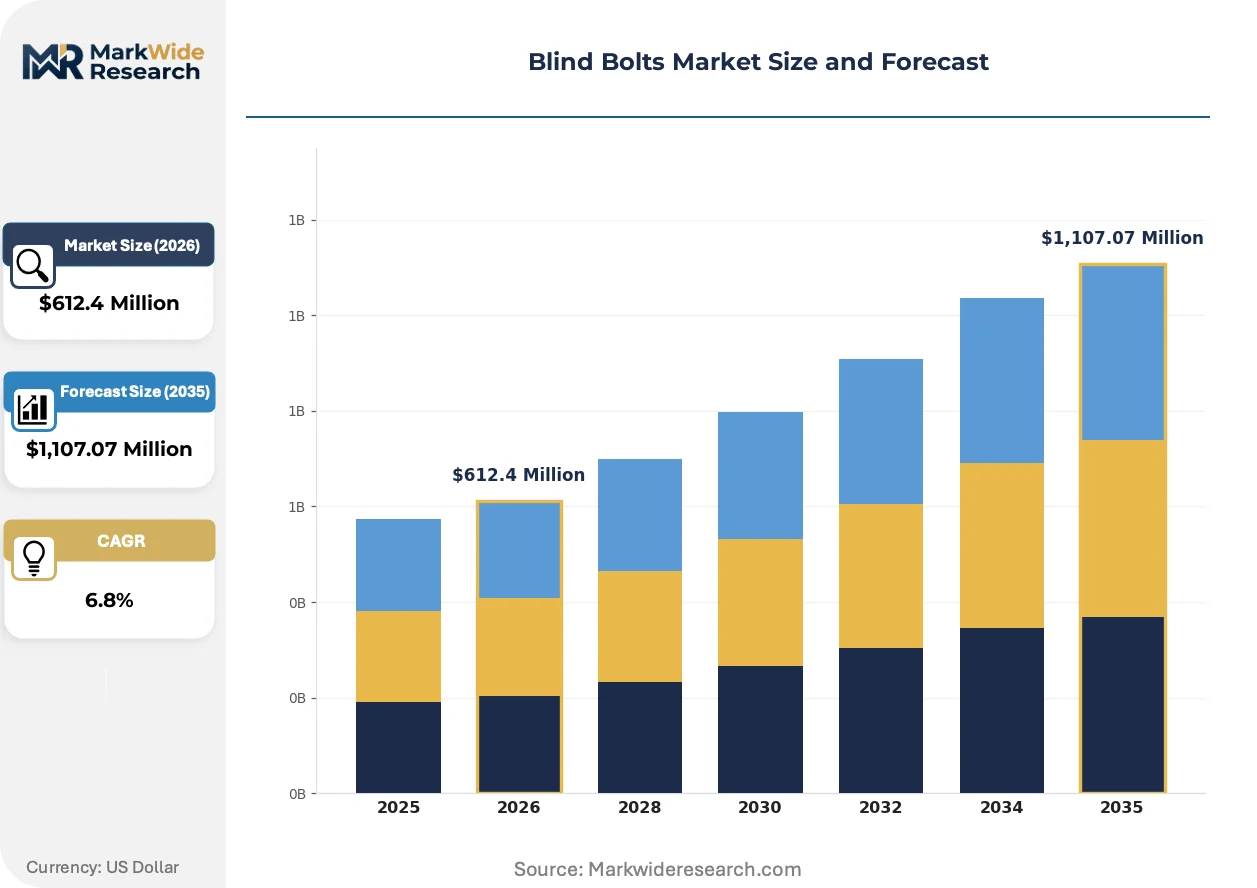
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blind Bolts, Heavy-Duty Blind Bolts, High-Strength Blind Bolts, Specialty Blind Bolts Industry Vertical: Aerospace, Automotive, Construction, Marine Material: Steel, Aluminum, Stainless Steel, Titanium Installation Method: Rivet Installation, Mechanical Installation, Hydraulic Installation, Pneumatic Installation |
| Companies Covered | Hilti Group, Parker Hannifin Corporation, Fastenal Company, Bollhoff Group, SFS Group AG, Wurth Group, Stanley Black & Decker, LISI Group, TriMas Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blind Bolts Market Strategic Shifts & Innovations
Fastener installation methodologies are bifurcating as aerospace retains mechanical torque systems while automotive chassis assembly adopts hydraulic automation for throughput gains.
Cold-formed titanium blind bolts with integrated break-stem designs are supplanting traditional multi-piece sleeve assemblies in wing-to-fuselage joints. Spirit AeroSystems and GKN Aerospace procurement specifications now prioritize these consolidated architectures for lot-to-lot consistency below 0.001 inch tolerance variation. The shift is compressing supplier qualification timelines by eliminating secondary machining operations.
EASA Part 21 production organization approvals now mandate digital thread documentation from billet source to installed fastener, extending traceability requirements beyond FAA airworthiness standards. European tier-one suppliers in Germany and France are retrofitting ERP systems to capture real-time metallurgical test data. The regulatory divergence is fragmenting batch release protocols between continental production sites.
Airframe OEMs now unbundle after-market fastener inventory from original equipment contracts, forcing suppliers to maintain consignment stock at final assembly line locations. Boeing's Everett and Charleston facilities operate vendor-managed inventory programs that transfer working capital burden upstream. The model is most advanced in United States commercial aerospace, with European OEMs piloting similar arrangements at Hamburg Finkenwerder.
Blind Bolts Market Segmentation
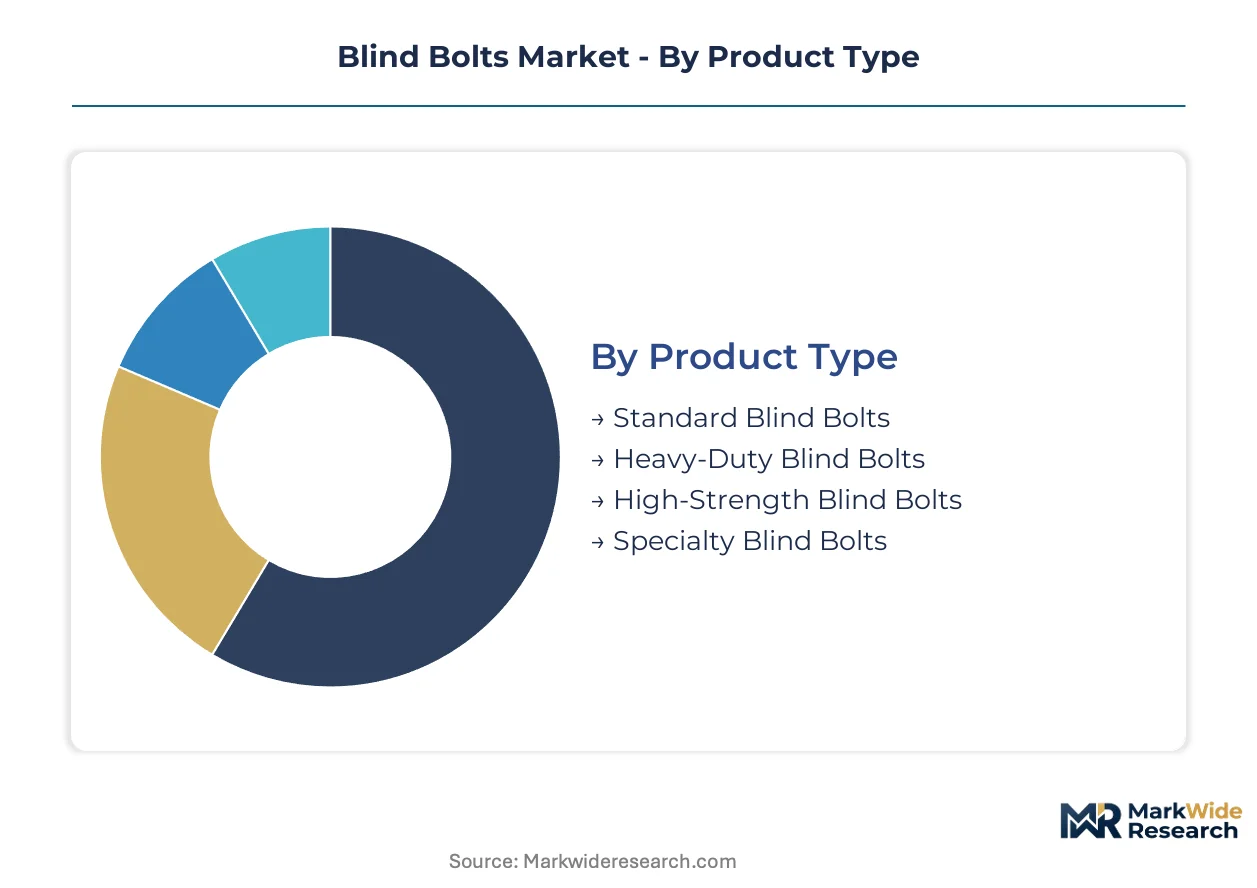
Blind bolt procurement patterns diverge sharply across aerospace fatigue-rated specifications, automotive high-volume chassis requirements, and marine corrosion-resistant standards. OEM qualification protocols and installation automation levels fragment supplier strategies across each segment boundary.
Product Type:
Margin pools concentrate in heavy-duty and high-strength variants where aerospace certification barriers protect pricing power.
- Standard Blind Bolts:General-purpose fasteners with shear strengths below 95 ksi serve construction steel framing and non-structural marine applications. Demand clusters in Germany's commercial building sector where DIN standards govern specification.
- Heavy-Duty Blind Bolts:Fatigue-rated designs achieving 95-160 ksi shear strength dominate commercial aerospace bill-of-materials for wing box and fuselage joints. Airbus A320 and Boeing 737 MAX assembly lines in Toulouse and Renton consume elevated volumes under dual-source procurement mandates.
- High-Strength Blind Bolts:Precision-forged titanium and alloy steel variants meet EASA Part 21 traceability requirements for primary structural joints. Heat-treatment documentation extends batch release cycles.
- Specialty Blind Bolts:Custom geometries for confined-space ship hull compartments and automated automotive chassis fixtures. BIS certification pathways open Indian defense aerospace procurement.
Heavy-duty blind bolts hold installed capacity. High-strength blind bolts are rotating up the share rankings.
Industry Vertical:
Volume concentration follows airframe OEM production ramps and automotive platform renewal cycles.
- Aerospace:Single-aisle and wide-body assembly lines drive specification of titanium-grade blind bolts with integrated break-stem designs. Spirit AeroSystems and GKN Aerospace procurement prioritizes lot-to-lot consistency below 0.001 inch tolerance variation.
- Automotive:Chassis assembly lines in Stuttgart and Wolfsburg adopt hydraulic installation systems for throughput gains. Steel variants retain cost advantages in rear-accessible joints.
- Construction:Steel framing nodes with rear access constraints specify mechanical installation methods. REACH hexavalent chromium restrictions accelerate zinc-nickel coating adoption.
- Marine:Ship hull compartments with sealed compartments require corrosion-resistant stainless steel and specialty geometries. Lockbolt alternatives compete where two-sided installation remains feasible.
Aerospace commands specification authority. Automotive is climbing the fastest on installation automation investment.
Material:
Cost tier stratification separates commodity steel from aerospace-grade titanium with tenfold price multiples.
- Steel:Carbon and alloy grades serve construction and automotive applications where weight penalties are acceptable. DIN and JIS standards govern European and Japanese procurement specifications.
- Aluminum:Lightweight variants address marine superstructure and secondary aerospace joints. Corrosion performance limits primary structural adoption.
- Stainless Steel:300-series and precipitation-hardened grades withstand salt spray environments in ship hull compartments. Premium grades achieve aerospace corrosion resistance without titanium cost.
- Titanium:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr alloys deliver 95-160 ksi shear strength at 40% weight reduction versus steel. Russian and Ukrainian sponge supply disruptions concentrate risk with three non-Chinese producers.
Steel holds installed capacity. Titanium is gaining share fastest on airframe weight reduction mandates.
Installation Method:
Customer type bifurcation separates aerospace mechanical retention from automotive hydraulic automation.
- Rivet Installation:Legacy mechanical methods retain aerospace installed base for field maintenance and repair operations. FAA airworthiness directives govern technician certification.
- Mechanical Installation:Torque-controlled systems dominate commercial aerospace final assembly where precision trumps speed. Boeing Everett and Charleston vendor-managed inventory programs optimize line-side availability.
- Hydraulic Installation:Automated torque-and-tension equipment converges with automotive chassis high-volume requirements. Equipment capital intensity barriers limit supplier entry.
- Pneumatic Installation:Compressed-air systems serve construction and marine applications with portable deployment requirements. Lower precision tolerance suits non-structural joints.
Mechanical installation holds installed capacity. Hydraulic systems are rotating up the share rankings on automotive automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes aerospace-grade titanium blind bolts for commercial airframe assembly, while Germany concentrates on automotive chassis automation and China scales domestic production for defense aerospace indigenization.
United States
Boeing's 737 MAX and 787 assembly lines in Renton and Charleston drive specification of fatigue-rated heavy-duty blind bolts with integrated break-stem designs. FAA airworthiness directives mandate lot traceability from billet source to installed fastener, extending batch documentation requirements. Vendor-managed inventory programs at Everett and Charleston transfer working capital burden upstream to tier-one suppliers.
Germany
Airbus A320 family production in Hamburg and automotive chassis assembly in Stuttgart and Wolfsburg split demand between aerospace fatigue-rated specifications and hydraulic installation automation. EASA Part 21 production organization approvals require digital thread documentation beyond FAA standards. REACH hexavalent chromium restrictions accelerate zinc-nickel coating adoption across installed fastener bases.
China
Commercial Aircraft Corporation of China's C919 program and defense aerospace indigenization mandates expand domestic blind bolt procurement. GB standards and MIIT regulations govern specification for indigenous airframe programs. Shanghai and Xi'an production clusters concentrate titanium sponge processing and precision forging capacity for military aviation applications.
India
Hindustan Aeronautics Limited indigenization mandates open qualification pathways for foreign fastener specialists with BIS certification. Defense procurement policies prioritize domestic manufacturing under the PLI scheme for aerospace components. Bengaluru and Hyderabad defense aerospace clusters absorb elevated volumes of specialty blind bolts for combat aircraft programs.
Japan
Mitsubishi Heavy Industries and Subaru Corporation airframe programs specify JIS-standard blind bolts for regional jet and defense applications. METI industrial policy supports titanium alloy substitution in weight-critical structural joints. Nagoya and Komaki aerospace manufacturing districts concentrate precision forging and heat-treatment expertise for domestic OEM supply chains.
Blind Bolts Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the blind bolts market. Vertically integrated fastener specialists control captive metallurgy labs and heat-treatment operations, while component assemblers face margin compression as tier-one suppliers internalize precision forging capabilities. Three archetypes dominate: metallurgy-integrated manufacturers with billet-to-fastener control, accreditation-heavy specialists with dedicated aerospace sites, and automation-focused suppliers with cold-forming cell investments. Competitive moves concentrate on backward integration into titanium sponge sourcing and parallel PPAP submissions for Boeing and Airbus dual-source mandates.
Among European-anchored fabricators, Hilti Group and Bollhoff Group occupy positions in the integrated metallurgy tier, with SFS Group AG representing the automation-focused archetype through Swiss-based precision manufacturing. Hilti Group exemplifies captive supply chain control from raw material to finished fastener. Bollhoff Group anchors accreditation-heavy positioning through dedicated aerospace certification sites. SFS Group AG sits within the high-automation specialist segment, compressing lot-to-lot variation through process control investments.
| Leading Market Players |
|---|
| Hilti Group |
| Parker Hannifin Corporation |
| Fastenal Company |
| Bollhoff Group |
| SFS Group AG |
| Wurth Group |
| Stanley Black & Decker |
| LISI Group |
| TriMas Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Boeing, Airbus, and tier-one fastener suppliers lock in titanium-grade access while anchoring price visibility across multi-year production cycles, insulating aerospace procurement from spot-market volatility in raw material inputs.
Pricing Analysis
Contract-based long-term offtake structures dominate aerospace procurement, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. FAA and EASA qualification status commands substantial premiums over commercial-grade alternatives. Cost compression in standard-grade steel variants is intensifying because automotive chassis buyers prioritize throughput over performance specifications. Construction and marine segments exhibit highest price sensitivity, while aerospace OEMs demonstrate lowest sensitivity due to airworthiness liability exposure.
Supply Chain Analysis
Vendor-managed inventory programs at Boeing Everett and Charleston reflect just-in-time preferences, while titanium sponge sourcing demands strategic stockpiling given Russian and Ukrainian feedstock disruptions. Supply concentrates in the United States, Germany, and China, with precision forging and heat-treatment capacity tethered to aerospace manufacturing clusters. The supply chain draws from titanium sponge, alloy steel billets, and zinc-nickel coating chemistries as critical inputs. Single-source vulnerability in non-Chinese titanium sponge producers constitutes primary structural risk. Distribution runs through tier-one supplier consignment stock at final assembly line locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium alloy substitution mandates and EASA digital thread documentation requirements are reshaping competitive positioning, creating high-growth disruption as qualification barriers rise and supplier consolidation accelerates.
For Market Incumbents: Consolidate backward integration into titanium sponge sourcing to mitigate Russian supply concentration risk, and expand captive heat-treatment capacity to compress batch release cycles under FAA lot traceability mandates. Lockbolt mechanical interference in marine and construction applications threatens margin pools in non-aerospace segments. Certification investment in EASA Part 21 production organization approvals secures pricing power in European aerospace procurement. For New Entrants and Emerging Players: Differentiate on hydraulic installation system integration for automotive chassis automation, targeting Stuttgart and Wolfsburg assembly lines where throughput requirements outpace incumbent mechanical system capabilities. Indian defense aerospace represents the most penetrable geography under HAL indigenization mandates with BIS certification pathways. Specialty geometries for confined-space ship hull compartments offer alternative white-space entry. Partner with established tier-one suppliers for parallel PPAP submission support to accelerate Boeing and Airbus qualification timelines. For Investors and Strategic Acquirers: Metallurgy-integrated manufacturers with billet-to-fastener control represent the priority acquisition archetype, capturing margin pools protected by aerospace certification barriers and OEM dual-source requirements. Long-term viability hinges on titanium-grade substitution momentum and regulatory tightening on traceability standards across the analysis window. Watch for EASA-FAA regulatory divergence on digital thread documentation as inflection indicator for European supplier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captures supply security as Russian feedstock disruptions concentrate risk with three non-Chinese producers. |
| EASA Part 21 Production Organization Approval | Unlocks European aerospace procurement as digital thread documentation mandates fragment batch release protocols. |
| Hydraulic Installation System Development | Converges with Stuttgart and Wolfsburg automotive chassis automation for throughput gains. |
| Vendor-Managed Inventory Expansion | Transfers working capital burden upstream while securing line-side availability at Boeing Charleston and Everett. |
| Indian BIS Certification Pathway | Opens HAL defense procurement under indigenization mandates in Bengaluru and Hyderabad clusters. |
Research Approach
Cross-validation between primary interviews with aerospace procurement directors, fastener manufacturing engineers, and metallurgical process specialists and secondary validation through FAA airworthiness directive filings, EASA certification databases, and customs trade data anchors the qualitative findings. Bottom-up triangulation against tier-one supplier capacity disclosures and top-down reconciliation with OEM bill-of-materials data ensures methodological rigor.
Sensitivity analysis across titanium sponge price volatility scenarios, OEM production rate assumptions, and regulatory timeline compressions informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, industry vertical, material grade, and installation method, with regional production cluster dynamics as an aerospace-specific dimension. CAGRs derive from compound growth trajectory analysis against baseline aerospace assembly line throughput and automotive platform renewal cycles, incorporating REACH coating transition timelines and dual-source procurement mandate diffusion.
Forecasts assume regulatory continuity in FAA airworthiness standards and EASA Part 21 frameworks; material policy shifts would require re-modeling. Specific risk factors include titanium sponge supply disruption, heat-treatment technician scarcity, and OEM qualification timeline compression beyond historical bandwidth. Revision becomes warranted when titanium alloy substitution rates or regulatory documentation requirements cross thresholds that alter supplier cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cladding Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Geocells Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
United States Architectural Coatings Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Long Steel Market
Building Materials
Europe Fiber Cement Market
Building Materials
Natural Stone Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Global Pozzolan Market
Building Materials
GCC Concealed Cistern Market