
 Finland Transportation Infrastructure Construction Market | 2026-2036
Finland Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Transportation Infrastructure Construction Market Foresight
The EU Green Deal is expanding the cost-of-entry calculus for contractors bidding on Finnish transportation infrastructure. YIT leverages its integrated project delivery model to capture complex rail and tunnel contracts across the Nordic region. Destia anchors its position through deep specialization in road maintenance and winter-resilient asphalt technologies. Skanska AB competes by extending its digital construction platforms into Finnish municipal planning processes.
Finland transportation infrastructure construction encompasses the engineering, materials procurement, and physical assembly of roads, bridges, railways, and tunnels designed to withstand subarctic thermal cycling and permafrost heave. Structural concrete for Finnish bridge decks typically incorporates air-entrainment of four to seven percent by volume to resist freeze-thaw degradation across design lives exceeding 100 years. Roads and railways together command the dominant share of project value, with railways capturing the fastest expansion as the Finnish Transport Infrastructure Agency prioritizes electrified corridors linking Vaasa, Tampere, and Kouvola to Baltic Sea ports. Concrete and asphalt remain the volume leaders in materials, though steel reinforcement grades are climbing as composite bridge designs gain regulatory approval for longer spans with reduced maintenance intervals.
The Finnish Transport Infrastructure Agency, the Finnish Transport and Communications Agency Traficom, and the Ministry of the Environment collectively shape demand through procurement rules that embed lifecycle carbon accounting and nature-compensation requirements into contract awards. BIS-aligned material certification and EU taxonomy compliance for sustainable finance now function as de facto gatekeepers for market access on publicly funded projects. Stakeholders must monitor how the EU AI Act and forthcoming construction-technology standards will reshape bidding criteria for automated earthworks and predictive maintenance systems.
Market Dynamics
EU Green Deal carbon-accounting mandates are restructuring Finnish procurement protocols. The Finnish Transport Infrastructure Agency now embeds lifecycle emissions thresholds into contract awards, forcing contractors to reconfigure material sourcing and construction methodologies to qualify for publicly funded rail and road projects.
Growth Catalysts
- Railway Electrification Mandates:The EU Green Deal requires carbon-neutral freight corridors by 2050. Finnish authorities prioritize electrified rail links connecting Vaasa, Tampere, and Kouvola to Baltic Sea ports.
- Subarctic Material Innovation:Air-entrained concrete formulations with four to seven percent volume tolerance resist freeze-thaw degradation. Bridge deck specifications now exceed 100-year design lives.
- Greater Helsinki Concentration:Urban rail extensions and port connectivity upgrades absorb disproportionate capital allocation. Municipal budgets channel resources into dense metropolitan infrastructure networks.
Market Restraints
- Steel Grade Cost Escalation:Composite bridge designs require higher-grade reinforcement. Material certification under BIS-aligned standards adds procurement friction and extends lead times.
- Nature-Compensation Burden:The Ministry of the Environment mandates habitat offset calculations for every linear kilometer of new track. Project feasibility studies now consume 18-24 additional months.
- Specialized Contractor Scarcity:Tunnel boring and permafrost engineering expertise concentrates among Nordic consortia. Limited bidding pools inflate risk premiums on complex underground segments.
Strategic Opportunities
- Automated Earthworks Integration:The EU AI Act will soon classify construction autonomy systems. Finnish contractors positioning predictive maintenance algorithms gain first-mover advantage in bidding criteria.
- Tampere-Oulu Corridor Gap:Northern Finland rail density lags southern networks. Electrification of the Tampere-Oulu axis remains uncontracted despite freight volume projections.
- Digital Twin Convergence:Municipal planning processes in Helsinki, Espoo, and Vantaa increasingly require Building Information Modeling interoperability. Contractors offering integrated digital construction platforms capture planning-phase influence.
Industry Challenges
- Permafrost Engineering Talent Scarcity:Geotechnical specialists capable of modeling thermal heave in discontinuous permafrost zones command premium compensation. Finnish universities graduate fewer than fifteen qualified engineers annually.
- EU Taxonomy Compliance Timeline:Sustainable finance verification for construction bonds requires third-party validation of Scope 3 emissions. Documentation burdens delay project financial close by six to nine months.
- Legacy Rail Signaling Integration:New electrified corridors must interface with Soviet-era signaling infrastructure near Russian border zones. Protocol mismatches create commissioning delays and safety certification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Transportation Infrastructure Construction Market |
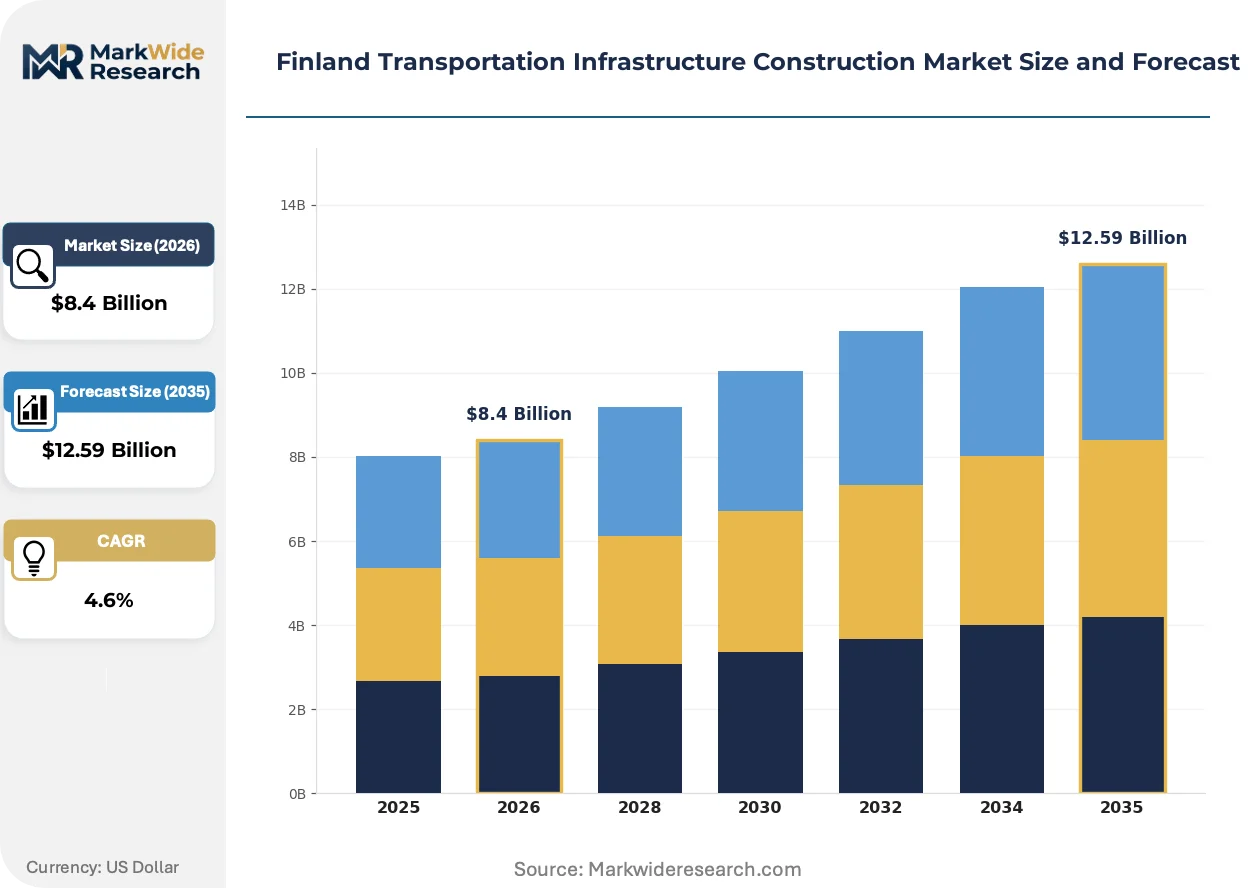
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Tunnels Material Type: Steel, Concrete, Asphalt, Composites End User: Government, Private Sector, Municipalities, Contractors Construction Phase: Planning, Design, Execution, Maintenance |
| Companies Covered | A-insinoorit Oy (AINS Group), Skanska AB, Destia, YIT, Strabag SE, Colas, Vinci SA, AFRY, SRV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Transportation Infrastructure Construction Market Shifts & Advancements
Digital construction platforms and predictive maintenance systems are reconfiguring how Finnish infrastructure gets financed, built, and operated. Regulatory technology mandates and buyer procurement evolution are compressing traditional project delivery timelines.
Building Information Modeling is integrating federated data environments across design, procurement, and asset management phases. The Finnish Transport Infrastructure Agency mandates BIM Level 2 compliance on all contracts exceeding €5 million. Contractors deploying cloud-based collaboration platforms compress design-review cycles and reduce change-order frequency during construction execution.
EU taxonomy disclosure requirements are forcing carbon-accounting transparency into subcontractor selection. The Finnish Ministry of the Environment requires embodied emissions declarations for cement, steel, and asphalt batches. Project developers sourcing low-carbon concrete mixes from domestic suppliers secure preferential scoring in competitive tenders.
Municipal buyers are consolidating maintenance contracts into decade-long performance agreements. Helsinki, Espoo, and Vantaa now bundle road surface renewal with winter resilience guarantees. Contractors absorbing lifecycle risk in exchange for extended revenue visibility are displacing traditional unit-price bidders in metropolitan procurement.
Finland Transportation Infrastructure Construction Market Segmentation
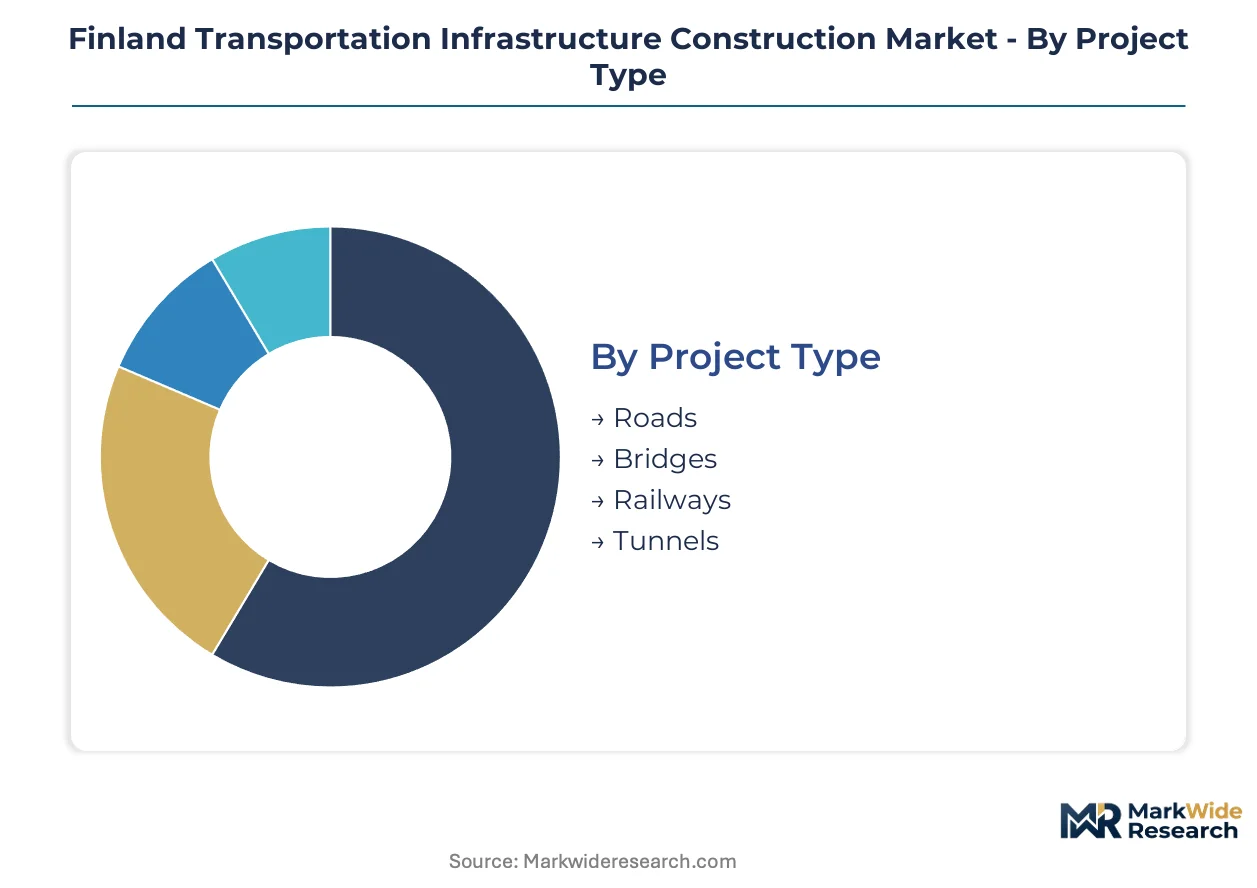
Finnish infrastructure procurement embeds lifecycle carbon accounting and thermal resilience requirements into every contract tier. Segment boundaries blur as integrated project delivery consolidates design-build-maintain obligations. Understanding where capital concentrates across project types, materials, and construction phases reveals how contractors must reconfigure capabilities to qualify for publicly funded awards.
Project Type:
Railways and roads function as standalone capital programs with dedicated funding streams, while bridges and tunnels typically embed within larger corridor projects requiring specialized subcontracting pools.
- Roads:Winter-resilient asphalt specifications dominate procurement in southern Finland. The Finnish Transport Infrastructure Agency channels maintenance budgets into decade-long performance contracts around Helsinki, Espoo, and Tampere, bundling surface renewal with snow-load guarantees.
- Railways:Electrified freight corridors absorb disproportionate capital allocation under EU Green Deal mandates. The Vaasa-Tampere-Kouvola port linkage commands priority status, with thermal expansion joints and subarctic signaling integration driving specialized engineering requirements.
- Bridges:Air-entrained concrete decks with 100-year design lives embed within road and rail networks. BIS-aligned certification for freeze-thaw resistant formulations extends lead times for prestressed elements.
- Tunnels:Permafrost heave modeling and groundwater intrusion systems concentrate expertise among Nordic consortia. Limited bidding pools inflate risk premiums on underground segments near discontinuous permafrost zones.
Roads lead volumes today; railways are gaining share fastest.
Material Type:
Cost tiers separate commodity bulk materials from engineered formulations carrying certification premiums and extended warranty obligations.
- Concrete:Air-entrainment of four to seven percent by volume resists freeze-thaw degradation across bridge decks and tunnel linings. Domestic suppliers with EU taxonomy-compliant embodied emissions declarations secure preferential scoring in competitive tenders.
- Asphalt:Polymer-modified binders and winter-grade formulations command price premiums over standard mixes. Municipal buyers in Greater Helsinki specify performance warranties spanning 15-20 years for arterial road surfaces.
- Steel:Higher-grade reinforcement bars serve composite bridge designs with reduced maintenance intervals. BIS-aligned material certification adds procurement friction and extends delivery schedules for structural sections.
- Composites:Fiber-reinforced polymers gain regulatory approval for corrosive environments and lightweight superstructures. Limited domestic production capacity forces reliance on imported prefabricated elements.
Concrete leads volumes today; composites are climbing the fastest.
End User:
Customer type determines contract structure, with government and municipal buyers consolidating multi-phase obligations while private sector procurement favors discrete, transfer-risk arrangements.
- Government:The Finnish Transport Infrastructure Agency embeds lifecycle carbon thresholds and nature-compensation requirements into rail and road awards. Procurement rules now function as de facto gatekeepers for market access on federally funded corridors.
- Municipalities:Helsinki, Espoo, and Vantaa bundle road maintenance with winter resilience guarantees under decade-long performance agreements. Contractors absorbing lifecycle risk displace traditional unit-price bidders in metropolitan procurement.
- Private Sector:Industrial port operators and mining companies fund dedicated freight spurs and access roads. These projects face fewer environmental offset requirements but demand faster execution timelines.
- Contractors:Large Nordic consortia self-perform specialized segments, sourcing materials through captive supply arrangements. Vertical integration into asphalt production and concrete batching defends margin position against commodity price volatility.
Government leads volumes today; municipalities are expanding most quickly.
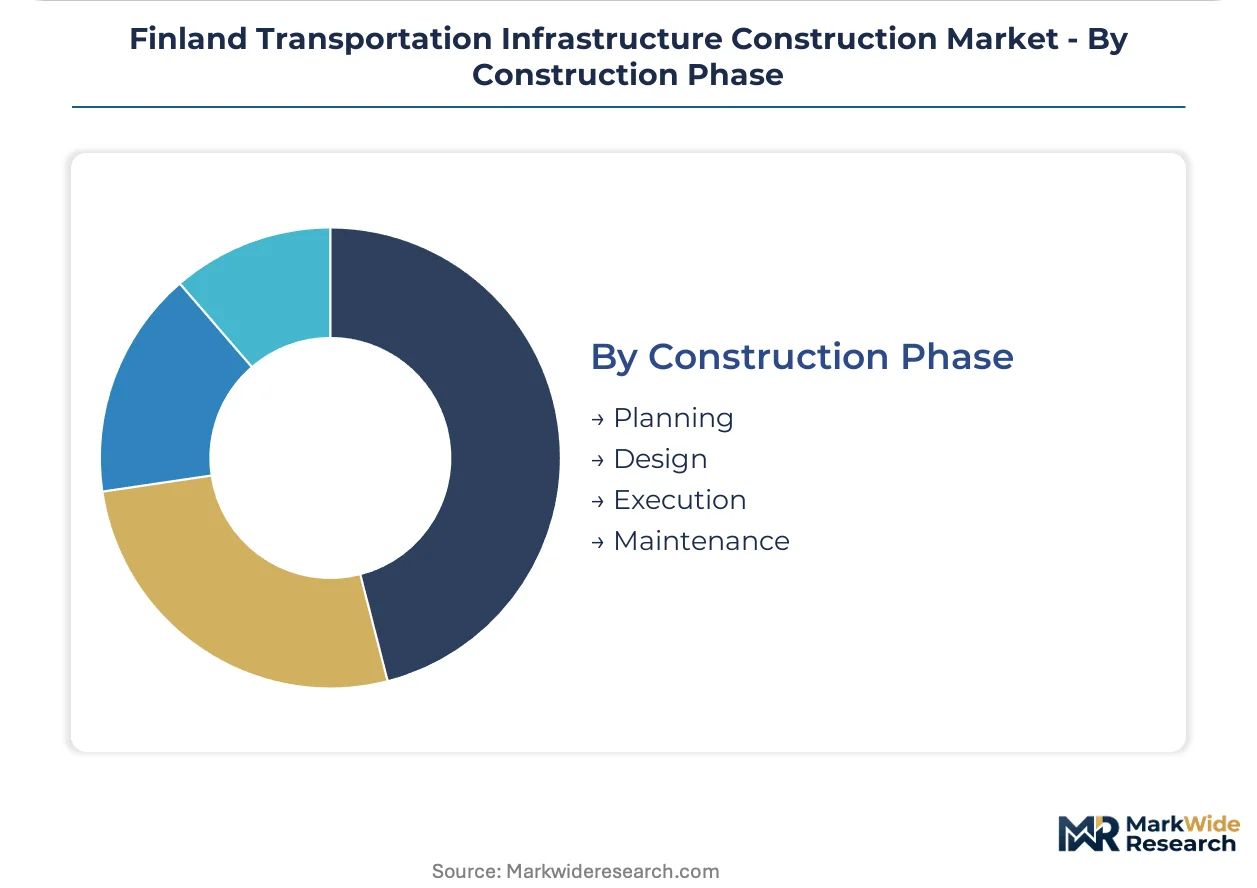
Construction Phase:
Maturity gradients separate established planning and execution capabilities from emerging digital integration across design and maintenance functions.
- Execution:Physical assembly of earthworks, structures, and track systems concentrates labor and equipment deployment. Automated earthworks systems face pending classification under the EU AI Act, reshaping bidding criteria for contractors positioning predictive algorithms.
- Maintenance:Performance-based contracts now span 10-15 year horizons, transferring operational risk from public agencies to private operators. Digital twin integration enables predictive intervention before thermal cycling degrades bridge decks.
- Planning:BIM Level 2 compliance is mandatory on all contracts exceeding €5 million. Cloud-based collaboration platforms compress design-review cycles and reduce change-order frequency during subsequent construction phases.
- Design:Federated data environments integrate structural, geotechnical, and environmental modeling. Permafrost engineering talent scarcity limits specialist availability for northern corridor feasibility studies.
Execution leads volumes today; maintenance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland's transportation infrastructure construction sector traces its modern lineage to post-war state-led industrialization, when the Finnish Transport Infrastructure Agency's predecessor organizations standardized bridge and road specifications for subarctic conditions. This institutional foundation established procurement protocols that now govern EU Green Deal compliance across the Nordic region.
Greater Helsinki
The metropolitan core absorbs disproportionate capital allocation through urban rail extensions and port connectivity upgrades. Helsinki, Espoo, and Vantaa bundle road maintenance into decade-long performance contracts with winter resilience guarantees. Municipal procurement here channels resources into dense infrastructure networks serving the country's primary economic cluster.
Pirkanmaa and Tampere Region
Electrified freight corridor development concentrates in this central logistics hub connecting western ports to eastern rail networks. The Finnish Transport Infrastructure Agency prioritizes the Vaasa-Tampere-Kouvola axis under EU Green Deal carbon-neutral mandates. Tampere's growing metropolitan population drives concurrent demand for urban transit expansion and intermodal freight terminals.
Western Finland and Vaasa
Port connectivity upgrades dominate procurement as Baltic Sea freight volumes expand. The region's energy-intensive industrial base requires dedicated rail spurs linking production facilities to electrified corridors. Coastal bridge replacements incorporate air-entrained concrete formulations specified for 100-year design lives against freeze-thaw degradation.
Northern Ostrobothnia and Oulu
Rail density lags southern networks despite freight volume projections for Arctic corridor development. Permafrost heave modeling and discontinuous permafrost engineering requirements limit specialist contractor availability. The Tampere-Oulu electrification gap represents the largest uncontracted rail opportunity in the national portfolio.
Southwest Finland and Turku
Archipelago bridge maintenance and port modernization absorb specialized engineering capacity. The Finnish Ministry of the Environment mandates habitat offset calculations for linear infrastructure crossing coastal wetland zones. Turku's historic urban core requires tunnel boring expertise for underground transit alternatives.
Finland Transportation Infrastructure Construction Market Competitive Landscape
The competitive structure tilts toward integrated Nordic consortia capable of delivering design-build-maintain obligations under lifecycle carbon accounting rules. Player concentration reflects specialized expertise in subarctic engineering rather than scale-driven commoditization. Two strategic archetypes dominate: vertically integrated domestic specialists controlling captive material supply, and multinational platform operators extending digital construction capabilities. Consolidation pressure intensifies through municipal procurement bundling and EU taxonomy compliance barriers that favor established players with validated emission disclosure systems.
Among Nordic-based integrated contractors, YIT, Destia, and Skanska AB occupy distinct positioning vectors. YIT exemplifies the project delivery archetype capturing complex rail and tunnel contracts through federated execution models. Destia anchors the maintenance-specialist tier with deep capabilities in road preservation and winter-resilient surface technologies. Skanska AB represents the multinational platform approach, extending digital construction interoperability into municipal planning processes across the region. Each occupies a defensible position against procurement criteria that now embed BIM Level 2 compliance and predictive maintenance algorithm readiness as scoring differentiators.
| Leading Market Players |
|---|
| A-insinoorit Oy (AINS Group) |
| Skanska AB |
| Destia |
| YIT |
| Strabag SE |
| Colas |
| Vinci SA |
| AFRY |
| SRV |
| Others |
Supply & Pricing Matrix
Air-entrained concrete formulations with four to seven percent volume tolerance flow from domestic batching plants through BIS-aligned certification gates into premium-priced bridge deck contracts, while standard road asphalt moves through municipal procurement at compressed margins.
Pricing Analysis
Performance-based contracting with decade-long maintenance obligations anchors the dominant pricing structure across Finnish transportation infrastructure. Price differentiation separates EU taxonomy-compliant material batches with embodied emissions declarations from uncertified commodity supplies. Pricing pressure stems from nature-compensation requirements extending project feasibility timelines by 18-24 months. Municipal buyers in Greater Helsinki exhibit highest price sensitivity due to bundled road maintenance budgets, while private port operators absorb premium pricing for accelerated execution timelines.
Supply Chain Analysis
Geotechnical specialists capable of modeling permafrost heave in discontinuous zones command premium compensation, with Finnish universities graduating fewer than fifteen qualified engineers annually. Cement and steel reinforcement draw from domestic suppliers and Nordic consortia, while fiber-reinforced polymer composites feed from limited import channels. Single-source vulnerability concentrates in tunnel boring equipment and automated earthworks systems facing pending EU AI Act classification. Distribution runs through the Finnish Transport Infrastructure Agency's centralized procurement portal for federally funded corridors, with municipal buyers operating parallel tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finland's transportation infrastructure construction sector functions as a Nordic capability arbitrage play, where subarctic engineering expertise unavailable in Southern European markets commands substantial contract premiums under EU Green Deal procurement rules.
For Market Incumbents: Anchor defensible positioning through captive supply arrangements in concrete batching and asphalt production, insulating margin structures against commodity volatility. Deepen BIM Level 2 compliance capabilities and predictive maintenance algorithm development to meet evolving scoring criteria. The EU AI Act's pending classification of construction autonomy systems threatens first-mover advantage for unprepared contractors. For New Entrants and Emerging Players: Digital construction platforms offering federated data environments across design and asset management phases provide the most penetrable entry vector. Target the Tampere-Oulu electrification gap, where rail density lags and specialist contractor scarcity limits incumbent bidding pools. Position cloud-based collaboration tools that compress design-review cycles for municipal contracts exceeding €5 million thresholds. For Investors and Strategic Acquirers: Consolidation pressure builds where EU taxonomy compliance barriers and validated emission disclosure systems favor established players with institutional procurement relationships. Long-term viability centers on contractors absorbing lifecycle risk through integrated design-build-maintain obligations. Monitor the Finnish Transport Infrastructure Agency's procurement rule evolution for automated earthworks and predictive maintenance scoring weight adjustments as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Design-Build-Maintain Capability Development | Captures decade-long performance contracts with lifecycle risk transfer from Finnish Transport Infrastructure Agency. |
| EU Taxonomy-Compliant Material Sourcing | Secures preferential tender scoring through domestic supplier partnerships with validated embodied emissions declarations. |
| Digital Twin and BIM Level 2 Platform Investment | Compresses design-review cycles and reduces change-order frequency in municipal planning processes across Helsinki, Espoo, and Vantaa. |
| Permafrost Engineering Talent Acquisition | Addresses specialist scarcity limiting bidding pool depth for northern corridor projects near discontinuous permafrost zones. |
| Predictive Maintenance Algorithm Development | Positions first-mover advantage as EU AI Act classification reshapes bidding criteria for automated earthworks systems. |
Research Methodology
Bottom-up project-type and material-category modeling reconciled against top-down procurement tracking and contractor capacity assessment forms the analytical core of this study. Primary interviews with project directors at the Finnish Transport Infrastructure Agency, municipal procurement officers in Greater Helsinki, geotechnical engineering leads, and construction consortium executives combined with secondary validation from EU Green Deal implementation documents, Finnish Ministry of the Environment regulatory filings, and customs data on construction material imports.
Input-output matrices mapping capital allocation across railways, roads, bridges, and tunnels through execution, maintenance, planning, and design phases generated volume and value estimates across the projection horizon. Segmentation dimensions encompassed project type, material category, end-user archetype, and construction phase. CAGRs derived from historical procurement patterns and announced pipeline visibility adjusted for nature-compensation timeline extensions and EU taxonomy compliance documentation burdens.
The model assumes a particular technology adoption path for automated earthworks and predictive maintenance systems; alternative pathways for AI Act classification timelines or BIM interoperability standards would alter the outlook. Forecasts reflect assumptions on electrified freight corridor prioritization and permafrost engineering graduate pipeline expansion. Practitioners should monitor EU AI Act implementation schedules and Finnish Transport Infrastructure Agency scoring weight adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market