
 Polymer-Modified Cementitious Mortar Market | 2026-2036
Polymer-Modified Cementitious Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer-Modified Cementitious Mortar Market Intelligence
European specialty chemical producers is consolidating regional supply chains for polymer-modified cementitious mortar feedstocks. BASF SE leverages its dispersion technology portfolio to anchor premium-grade output for industrial flooring systems. Sika AG competes through vertically controlled distribution networks spanning Western European renovation channels. Mapei S.p.A. differentiates via formulation depth across repair mortar categories for commercial contractors.
Polymer-modified cementitious mortar comprises Portland cement blended with acrylic, SBR, or EVA polymer dispersions, achieving flexural strength exceeding 8 MPa and enhanced adhesion to diverse substrates for structural repair and finish applications. Pre-mixed mortars dominate volume flows through construction company procurement channels, while self-leveling mortars capture expanding share in industrial flooring specifications demanding rapid installation cycles. Polymer dispersion technology leads installed base, though hybrid systems integrating microfiber reinforcement are gaining specification traction for high-traffic commercial substrates.
REACH compliance governs polymer constituent registration across European value chains, while India's BIS standards enforce minimum performance thresholds for cementitious repair products in public infrastructure. China's GB standards and dual carbon goals are reshaping formulation requirements toward lower-emission polymer systems. Stakeholders must monitor regulatory divergence between emission-focused European frameworks and performance-centric Asian standards when allocating R&D and manufacturing footprints.
Market Dynamics
Polymer dispersion chemistry is compressing installation cycles and displacing conventional cementitious repair systems across commercial flooring and infrastructure rehabilitation. REACH registration requirements for acrylic and SBR additives are forcing reformulation investments among European compounders, while India's BIS certification mandates tighten performance thresholds for public works procurement.
Growth Catalysts
- Dual carbon goals in China:Lower-emission polymer systems are gaining specification traction as MEE enforcement tightens emission disclosure requirements for construction material suppliers.
- Industrial flooring retrofit:Self-leveling mortars with rapid cure profiles are capturing specification share from epoxy systems in warehouse and logistics facility upgrades.
- Microfiber hybrid systems:Polymer-cement matrices reinforced with synthetic microfibers are penetrating high-traffic commercial substrates demanding flexural strength above 8 MPa.
Market Restraints
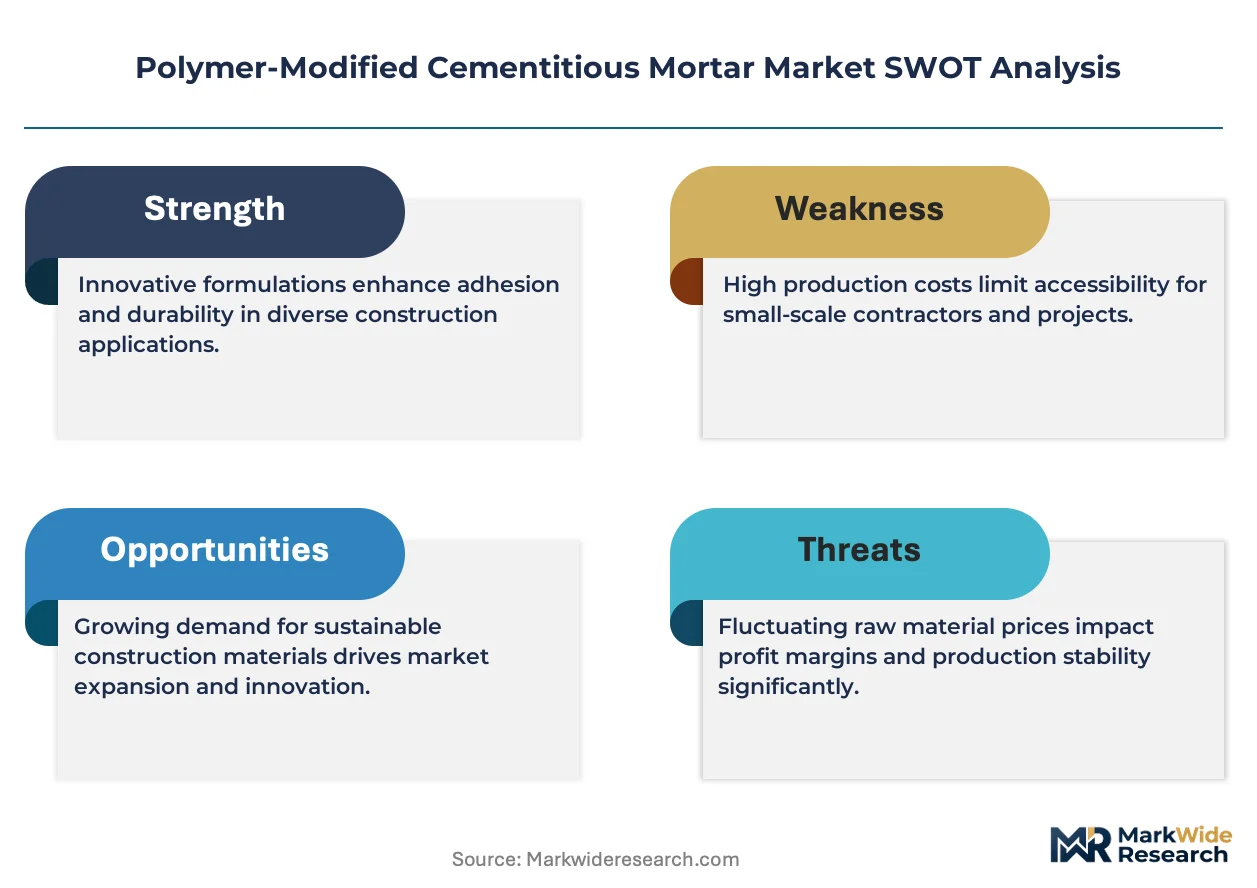
- Acrylic monomer cost volatility:Feedstock price swings for specialty polymer dispersions compress margin stability for mid-tier mortar compounders.
- European supply concentration:Dispersion technology leadership clusters among German and Swiss specialty chemical producers, creating procurement bottlenecks for Asian blenders.
- Epoxy substitution in premium flooring:Solvent-free epoxy systems retain specification dominance in pharmaceutical and electronics cleanroom environments.
Strategic Opportunities
- India's infrastructure corridors:BIS-certified repair mortars face supply gaps in state highway and railway rehabilitation programs.
- CE marking acceleration:The EU Green Deal's embodied carbon reporting requirements favor pre-mixed mortars with verified Environmental Product Declarations.
- Digital specification platforms:Construction procurement software is disintermediating traditional distributor relationships for commercial contractor purchasing.
Industry Challenges
- Polymer-cement compatibility testing:Extended laboratory validation cycles delay product launches as substrate diversity expands.
- Certified applicator scarcity:Specification-grade mortar installation demands trained contractor networks that remain underdeveloped outside tier-one Chinese and Indian cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer-Modified Cementitious Mortar Market |
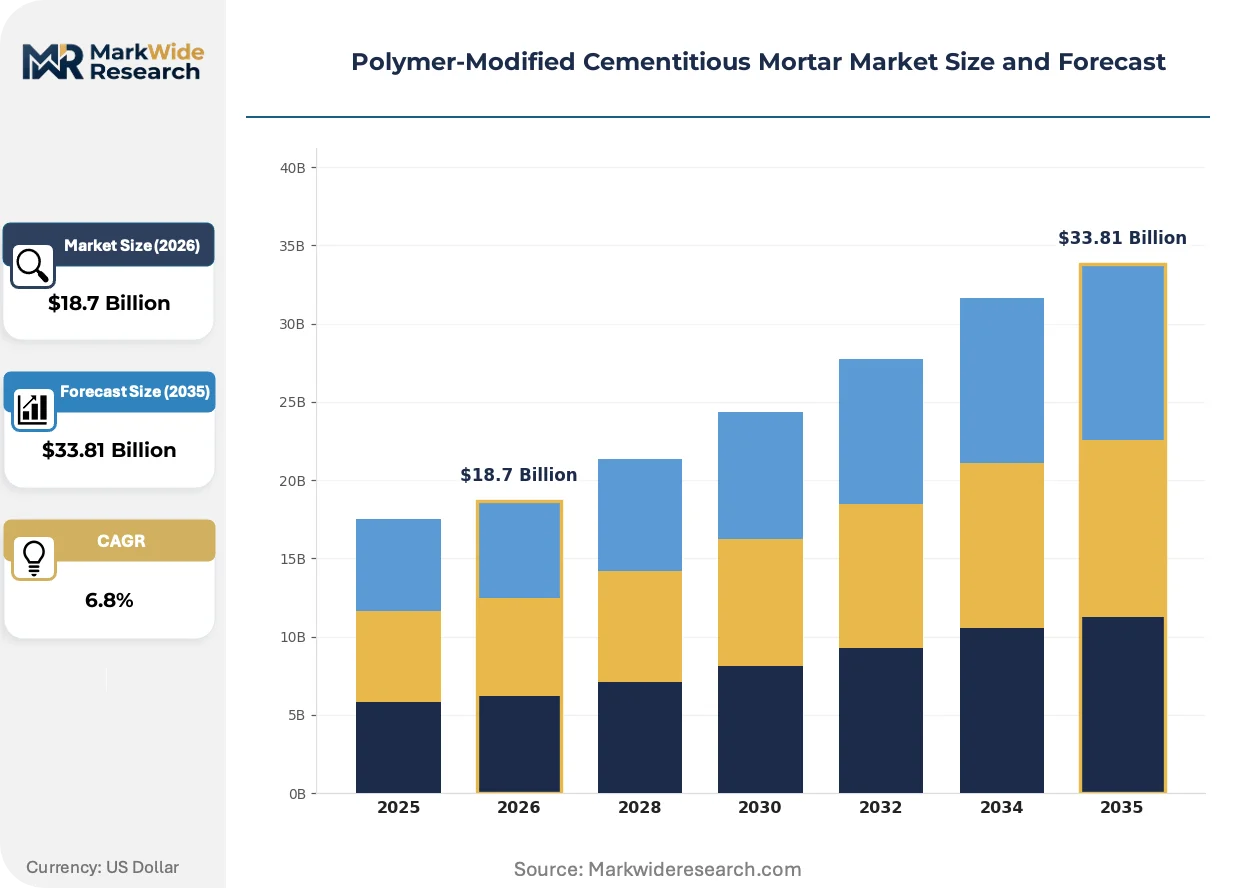
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-mixed Mortars, Polymer-Modified Thin Set, Repair Mortars, Self-Leveling Mortars Application: Flooring, Wall Covering, Tile Installation, Industrial Flooring End User: Construction Companies, DIY Enthusiasts, Commercial Contractors, Industrial Professionals Technology: Polymer Dispersion, Emulsion Technology, Microfiber Reinforcement, Hybrid Systems |
| Companies Covered | Saint-Gobain, H.B. Fuller Construction Products, BASF SE, Henkel AG & Co. KGaA, Pidilite Industries Limited, Sika AG, Fosroc International Limited, Laticrete International, LLC, Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer-Modified Cementitious Mortar Market Strategic Shifts & Innovations
Formulation science is converging with digital construction workflows and circular material mandates to redefine competitive advantage in polymer-modified cementitious systems. Three developments are compressing traditional product lifecycles and reshaping procurement criteria.
Hybrid polymer-microfiber systems are expanding into structural repair applications previously reserved for shotcrete or epoxy injection. German infrastructure contractors are specifying these blends for bridge deck rehabilitation requiring rapid traffic reopening. The technology is expanding into coastal megacity construction belts where salt-induced deterioration demands enhanced substrate adhesion.
REACH's 2023 polymer constituent registration deadlines forced European compounders to consolidate dispersion supply chains and eliminate unregistered additives. Industrial flooring specifications now demand full SVHC disclosure, compressing formulation flexibility. Asian exporters to Europe are establishing captive REACH compliance offices in Rotterdam and Hamburg.
Performance-based contractor purchasing is displacing brand-loyal specification patterns among commercial flooring installers. Tier-one Chinese construction groups now mandate third-party flexural strength certification prior to bulk procurement. This behavioral shift concentrates volume among testing-capable compounders in Jiangsu and Guangdong provinces.
Polymer-Modified Cementitious Mortar Market Segmentation
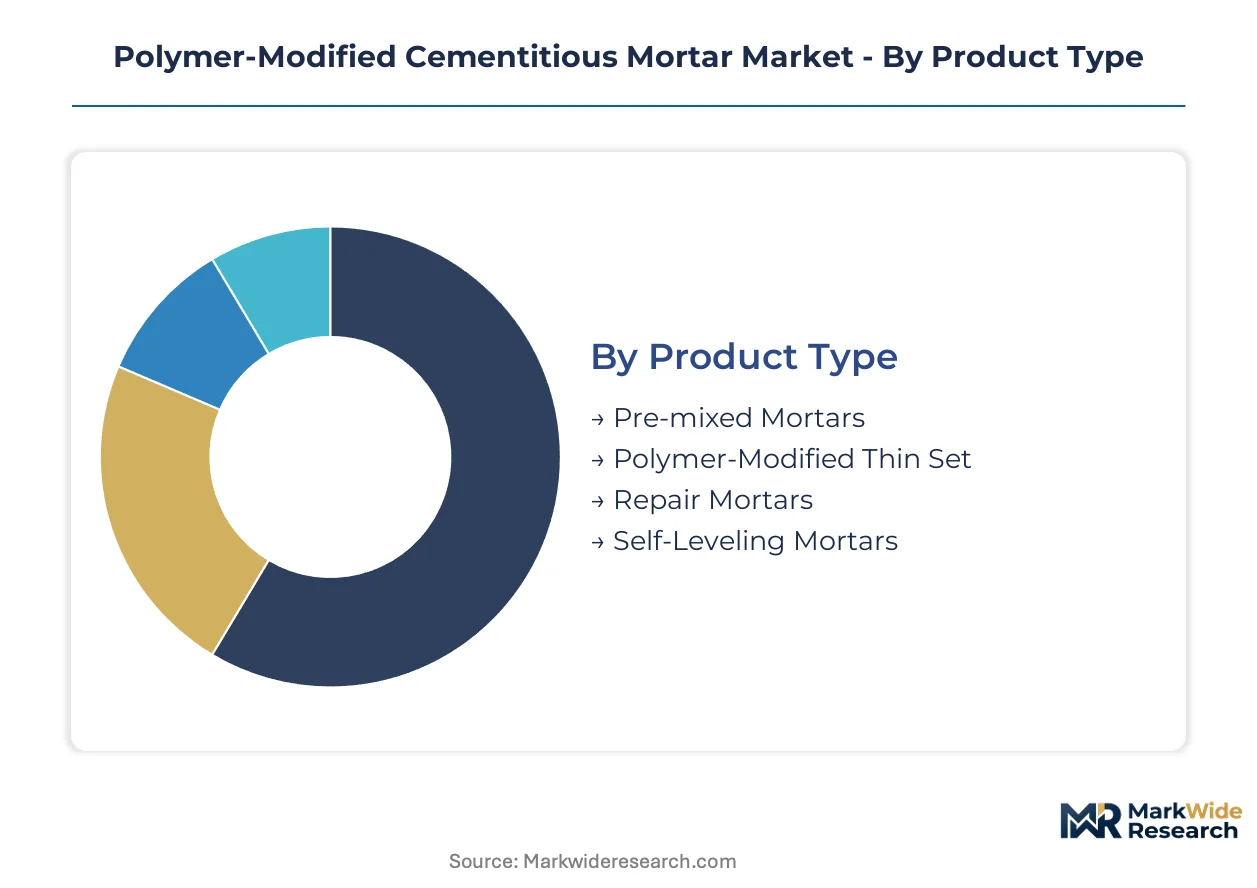
Product differentiation in polymer-modified cementitious mortar hinges on installation speed, substrate compatibility, and specification grade. Construction procurement teams segment purchases by performance tier rather than commodity chemistry, creating distinct volume flows across pre-mixed and field-blended categories.
Product Type:
Standalone pre-mixed systems dominate specification-grade procurement, while field-modified blends retain share in cost-sensitive renovation channels.
- Pre-mixed Mortars:Factory-blended Portland cement with acrylic or SBR dispersions at controlled water ratios, ensuring consistent flexural performance above 8 MPa. Demand concentrates in China's coastal megacity construction belts where commercial contractors face compressed installation schedules and mandatory third-party certification.
- Repair Mortars:High-adhesion formulations engineered for structural rehabilitation of deteriorated concrete substrates, often incorporating corrosion inhibitors. India's state highway and railway rehabilitation programs are driving specification volume as BIS certification mandates tighten compliance thresholds for public infrastructure tenders.
- Polymer-Modified Thin Set:Specialized bedding compounds for ceramic and natural stone tile installation with enhanced bond strength.
- Self-Leveling Mortars:Flowable systems designed for rapid-cure industrial flooring applications demanding flatness tolerances.
Volume placements concentrate in Pre-mixed Mortars; the faster expansion belongs to Self-Leveling Mortars.
Application:
End-use segmentation reflects diverging performance requirements between aesthetic finish systems and load-bearing industrial specifications.
- Industrial Flooring:Heavy-duty polymer-cement screeds and toppings engineered for forklift traffic, chemical resistance, and rapid return-to-service. Warehouse and logistics facility upgrades across Germany's Rhine-Ruhr industrial corridor are displacing epoxy systems with lower-VOC cementitious alternatives that satisfy REACH SVHC disclosure requirements.
- Flooring:General-purpose polymer-modified screeds and toppings for commercial and residential substrates. China's tier-one construction groups in Jiangsu and Guangdong provinces are mandating third-party flexural strength certification prior to bulk procurement, concentrating volume among testing-capable compounders.
- Wall Covering:Skim coats and base coats for interior and exterior plaster systems requiring enhanced adhesion.
- Tile Installation:Polymer-modified adhesives and grouts for ceramic, porcelain, and natural stone applications.
Industrial Flooring commands premium pricing; Flooring delivers the steepest volume expansion as residential retrofit accelerates.
End User:
Procurement authority separates specification-grade mortar flows from retail-oriented bagged product channels.
- Commercial Contractors:Mid-to-large construction firms executing commercial flooring, infrastructure repair, and renovation projects with engineered specification requirements. Asia-Pacific infrastructure corridors are scaling specification-grade purchases as digital procurement platforms disintermediate traditional distributor relationships.
- Construction Companies:General builders and specialty trade contractors purchasing through construction company procurement channels. Pre-mixed mortars dominate these volume flows where batch consistency and installation speed determine project economics.
- Industrial Professionals:Facility maintenance teams and specialized flooring contractors serving manufacturing and logistics operations.
- DIY Enthusiasts:Residential consumers purchasing bagged or small-container products through retail hardware channels.
Commercial Contractors drive margin capture; Construction Companies anchor volume throughput.
Technology:
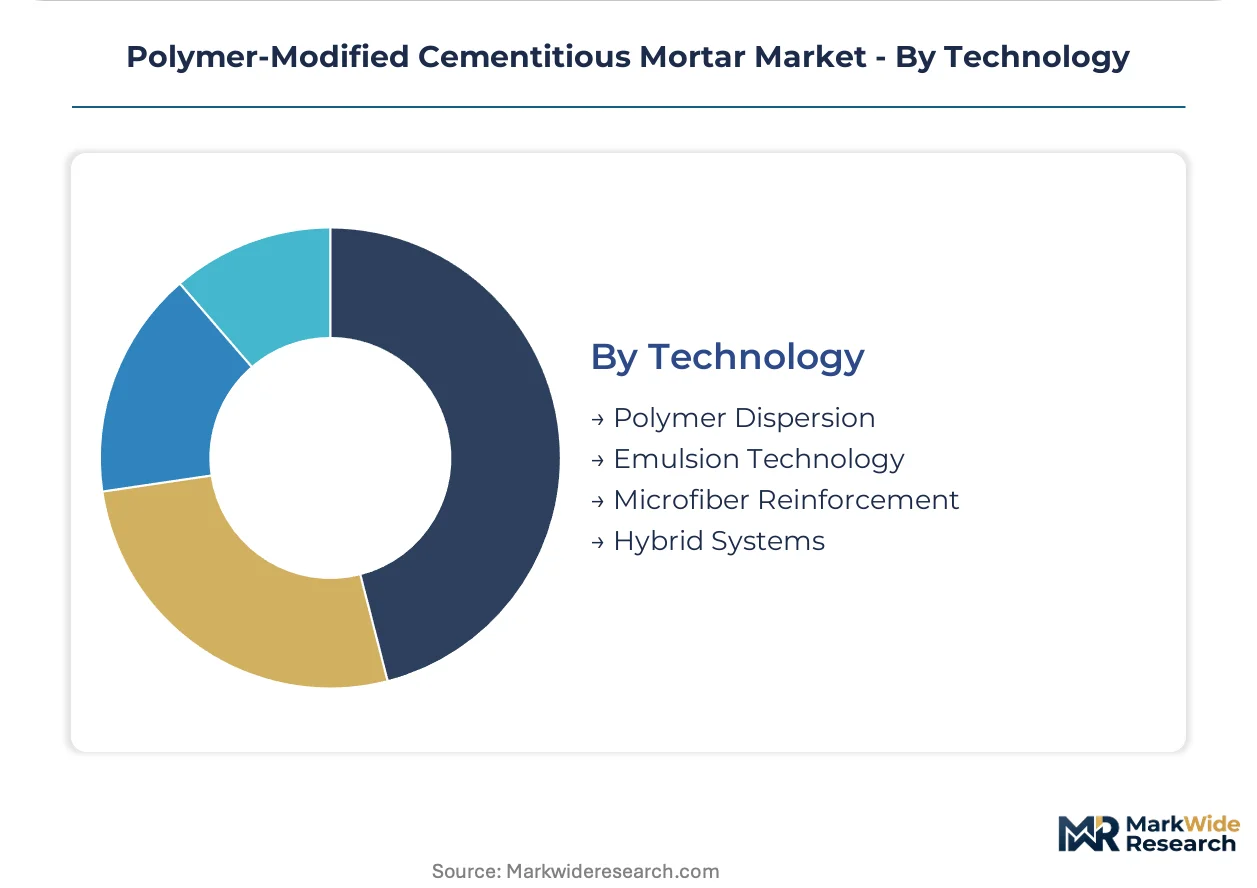
Polymer integration methods determine performance ceilings, cure profiles, and regulatory compliance pathways across formulation portfolios.
- Polymer Dispersion:Liquid acrylic, SBR, or EVA emulsions blended with Portland cement to enhance adhesion, flexibility, and water resistance. REACH registration requirements for acrylic and SBR additives are forcing reformulation investments among European compounders while maintaining the dominant installed base.
- Hybrid Systems:Polymer-cement matrices incorporating synthetic microfibers for structural repair applications demanding flexural strength above 8 MPa and rapid traffic reopening. German infrastructure contractors are specifying these blends for bridge deck rehabilitation.
- Emulsion Technology:Water-based polymer delivery systems optimized for specific substrate compatibility and environmental conditions.
- Microfiber Reinforcement:Discrete synthetic fiber additions to polymer-modified matrices for crack control and impact resistance.
Polymer Dispersion retains volume leadership; Hybrid Systems are climbing the fastest as structural repair specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland cement feedstock availability and polymer dispersion manufacturing clusters anchor regional supply configurations across construction corridors. Specification-grade mortar demand concentrates where infrastructure rehabilitation programs intersect with tightening certification mandates.
China
Coastal megacity construction belts in Jiangsu and Guangdong provinces drive specification-grade volume as tier-one construction groups mandate third-party flexural strength certification. The Ministry of Ecology and Environment enforces dual carbon goals that reshape formulation requirements toward lower-emission polymer systems. Shanghai and Shenzhen industrial zones concentrate dispersion technology manufacturing for domestic and export supply.
Germany
Rhine-Ruhr industrial corridor warehouse and logistics facility upgrades displace epoxy systems with lower-VOC cementitious alternatives. REACH registration requirements for acrylic and SBR additives force reformulation investments among specialty compounders. BASF SE anchors premium-grade output from Ludwigshafen dispersion technology facilities serving Western European renovation channels.
India
State highway and railway rehabilitation programs generate specification volume as BIS certification mandates tighten compliance thresholds for public infrastructure tenders. The Bureau of Indian Standards enforces minimum performance thresholds for cementitious repair products in government procurement. Mumbai and Delhi-NCR construction corridors scale specification-grade purchases through emerging digital procurement platforms.
United States
Industrial flooring retrofit activity in warehouse and distribution center construction drives rapid-cure mortar specifications. EPA VOC emission standards influence polymer system selection for commercial and industrial applications. Texas and California construction markets concentrate demand for pre-mixed systems with verified performance documentation.
United Arab Emirates
Mega-project construction in Dubai and Abu Dhabi generates demand for high-performance repair mortars in aggressive coastal environments. MOHAP and local building codes enforce substrate adhesion and durability standards for structural rehabilitation. Dubai Industrial City clusters manufacturing and distribution infrastructure serving Gulf Cooperation Council export markets.
Polymer-Modified Cementitious Mortar Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue hybrid microfiber and rapid-cure formulation spaces. Specialty chemical conglomerates with captive dispersion technology anchor premium positioning, while regional blenders compete on certification agility and local distribution density. Two strategic archetypes dominate: vertically integrated dispersion manufacturers and specification-focused formulation specialists. Competitive intensity concentrates around REACH compliance investments and BIS certification acquisition in priority markets.
Among European-based specialty chemical producers, BASF SE and Sika AG exemplify dispersion technology leadership and vertically controlled distribution approaches respectively. Pidilite Industries Limited represents the regional specialist archetype, occupying a position anchored in South Asian construction chemical markets. These three entities illustrate the competitive spectrum from global conglomerate to emerging market-focused formulation depth.
| Leading Market Players |
|---|
| Saint-Gobain |
| H.B. Fuller Construction Products |
| BASF SE |
| Henkel AG & Co. KGaA |
| Pidilite Industries Limited |
| Sika AG |
| Fosroc International Limited |
| Laticrete International, LLC |
| Mapei S.p.A. |
| Others |
Cost & Logistics Intelligence
Acrylic monomer spot indices cascade through polymer-modified cementitious mortar value chains, compressing margin stability for mid-tier compounders while anchoring premium pricing power among dispersion technology leaders with captive feedstock positions. REACH registration costs and BIS certification investments stratify pricing tiers across European and Asian procurement channels.
Pricing Analysis
Third-party flexural strength certification bundles separate premium-grade pre-mixed mortars from unbundled field-blended alternatives across commercial contractor procurement. Three-tier pricing structure across premium, standard, and economy levels reflects dispersion technology ownership, REACH compliance depth, and installation warranty coverage. Cost compression in mid-tier segments intensifies because acrylic monomer volatility transfers directly into compounder margins. Small-scale renovation contractors exhibit highest price sensitivity; industrial flooring specifiers prioritize performance documentation over unit cost.
Supply Chain Analysis
Container freight rate fluctuations from Rotterdam and Hamburg to Mumbai and Shanghai directly impact landed costs for dispersion-dependent blenders without captive manufacturing. Feedstock supply concentrates in Germany, Switzerland, and China; acrylic and SBR emulsion production draws from petrochemical complexes in Ludwigshafen, Basel, and Nanjing. Single-source vulnerability persists for European compounders reliant on Asian monomer shipments. Distribution runs through vertically controlled networks for premium grades and construction company procurement channels for volume pre-mixed flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer-modified cementitious mortar competitive dynamics favor consolidation plays as REACH registration deadlines and BIS certification mandates force sub-scale compounders toward exit or acquisition.
For Market Incumbents: Extend dispersion technology leadership through backward integration into acrylic monomer supply and captive REACH compliance offices in Rotterdam serving Asian export channels. BASF SE and Sika AG archetypes should consolidate regional blender networks in India's state highway corridors before BIS thresholds tighten further. Certification agility represents the critical defensive lever against emerging hybrid-microfiber specialists. For New Entrants and Emerging Players: Digital procurement platform partnerships offer the fastest route around entrenched distributor relationships in China's Jiangsu and Guangdong construction belts. White-space targets concentrate in BIS-certified repair mortar supply gaps across Indian railway rehabilitation programs and rapid-cure self-leveling specifications for German logistics facility retrofits. Specification-grade contractor training programs anchor sustainable go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap compounders with BIS certification pipelines in Maharashtra and Karnataka as infrastructure tender volumes accelerate. Five-to-ten-year viability hinges on dual carbon goal alignment for China exposure and REACH-registered formulation portfolios for European access. Monitor MEE enforcement intensity as the inflection signal for lower-emission polymer system specification share.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock secures margin stability against spot price volatility in European value chains. |
| REACH Compliance Office Establishment | Rotterdam-based registration capabilities unlock premium-grade European industrial flooring specifications. |
| BIS Certification Acquisition | Compliance depth captures Indian state highway and railway rehabilitation tender volumes. |
| Hybrid Microfiber R&D Investment | Bridge deck and high-traffic commercial substrates demand flexural performance above 8 MPa. |
| Digital Procurement Platform Partnership | Construction software disintermediation redirects commercial contractor purchasing toward direct manufacturer relationships. |
Research Approach
Trade customs databases, specialty chemical association publications, and construction procurement platform disclosures formed the secondary backbone for volume and value estimation. Primary interviews with plant managers at dispersion manufacturing facilities, procurement leads at tier-one Chinese construction groups, technical R&D directors at European compounders, and commercial contractors across Asia-Pacific infrastructure corridors validated demand assumptions. Bottom-up and top-down triangulation reconciled segment-level placements with aggregate market sizing.
Bottom-up modeling anchored projections across the analysis window, with top-down macroeconomic cross-checks for construction spending and infrastructure investment intensity. Segmentation dimensions included product type tier, application performance requirements, end-user procurement authority, and polymer integration technology. CAGRs derived from regression analysis against historical volume trajectories, with formulation cost curves and regulatory compliance timelines as industry-specific inputs.
Caveats apply where MEE enforcement intensity, acrylic monomer price spikes, or BIS certification timeline delays could materially shift the outlook. Forecasts embed assumptions around dual carbon goal implementation pace and REACH registration completion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Glass Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
East Africa Cement Market
Building Materials
United States Architectural Coatings Market
Building Materials
Composite Rebar Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Roofing and Insulation Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Building Asphalt Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Pozzolana Cement Market
Building Materials
Europe Aluminum Door and Window Market