
 EMEA Prestressed Concrete (PC) Wire and Strand Market | 2026-2036
EMEA Prestressed Concrete (PC) Wire and Strand Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Prestressed Concrete (PC) Wire and Strand Market Foresight
Aftermarket inspection and recertification services for existing prestressed structures is fragmenting as asset owners extend bridge lifespans across Europe and the Middle East. ArcelorMittal S.A. leverages its integrated steelmaking capacity to control wire rod supply from European mills through downstream drawing operations. N.V. Bekaert S.A. anchors its position through specialized surface treatment technologies that enhance bond performance in aggressive environments. DWK Drahtwerk Köln GmbH competes on precision cold drawing capabilities serving German transportation authorities with tight tolerance specifications.
Prestressed Concrete (PC) Wire and Strand comprises high-carbon steel wires and multi-wire strands tensioned to impart compressive stress in concrete elements, typically manufactured through cold drawing to tensile strengths exceeding 1,860 MPa followed by stress relieving to stabilize mechanical properties. Its primary purpose is to enable longer structural spans and thinner concrete sections in infrastructure and buildings. PC Strand commands the dominant value share as bridge decks and post-tensioned slabs require seven-wire configurations with superior load distribution. Surface Treatment technology is gaining share as epoxy-coated and galvanized variants address durability mandates in coastal Middle Eastern markets and de-icing salt exposure across Nordic countries.
CE marking under the EU Construction Products Regulation governs mechanical performance declarations for PC wire and strand sold across European member states, while ECHA's REACH framework restricts hazardous substances in metallic coatings and lubricants used during drawing. Saudi Arabia's SASO standards and South Africa's SABS certification create parallel compliance pathways for suppliers targeting public infrastructure tenders in those markets. Stakeholders must monitor evolving national carbon accounting rules that increasingly embed embodied emissions into procurement scoring for concrete superstructure projects.
Market Dynamics
The EU Green Deal's embodied carbon mandates are compressing procurement timelines for prestressed concrete suppliers as transportation authorities embed carbon accounting into tender scoring. This regulatory pressure is reshaping competitive positioning across European and Middle Eastern markets.
Growth Catalysts
- EU Green Deal carbon thresholds:Transportation authorities in Germany and France now require Environmental Product Declarations for bridge superstructure materials, accelerating specification of low-carbon PC strand variants.
- Saudi Vision 2030 infrastructure pipeline:The kingdom's giga-project portfolio is generating concentrated demand for corrosion-resistant surface-treated strand in coastal megadevelopments.
- Post-tensioning automation:Robotic tensioning systems are reducing installation labor hours by half on large-span bridge decks, expanding addressable project scale for contractors.
Market Restraints
- Scrap steel price volatility:Wire rod feedstock costs fluctuate with Turkish and Egyptian scrap import arbitrage, compressing margin visibility for independent European wire drawers.
- Belgian-Luxembourg supply concentration:Three integrated steelmakers control over sixty percent of EMEA wire rod capacity, creating bottleneck risk during mill maintenance cycles.
- Fiber-reinforced polymer substitution:CFRP tendons are displacing steel strand in select cable-stayed footbridges where electromagnetic neutrality matters.
Strategic Opportunities
- South African rail modernization:Transnet's freight corridor expansion represents underpenetrated demand for heavy-haul bridge PC wire as procurement reopens after logistics restructuring.
- Epoxy-powder hybrid coatings:Convergence of fusion-bonded epoxy with zinc-aluminum metallization is opening specification in Arabian Gulf salt-fog exposure zones previously served by stainless alternatives.
- Digital twin integration:Sensor-embedded smart strand is creating aftermarket revenue streams through structural health monitoring subscriptions on aging European viaducts.
Industry Challenges
- Stress-relief furnace operator scarcity:Specialized heat-treatment technicians with continuous-line experience are retiring faster than vocational programs replenish talent pools in Germany and Poland.
- SASO-SABS dual certification timelines:Saudi and South African type-approval processes run eighteen months in parallel, delaying market entry for mid-cap European suppliers without local testing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Prestressed Concrete (PC) Wire and Strand Market |
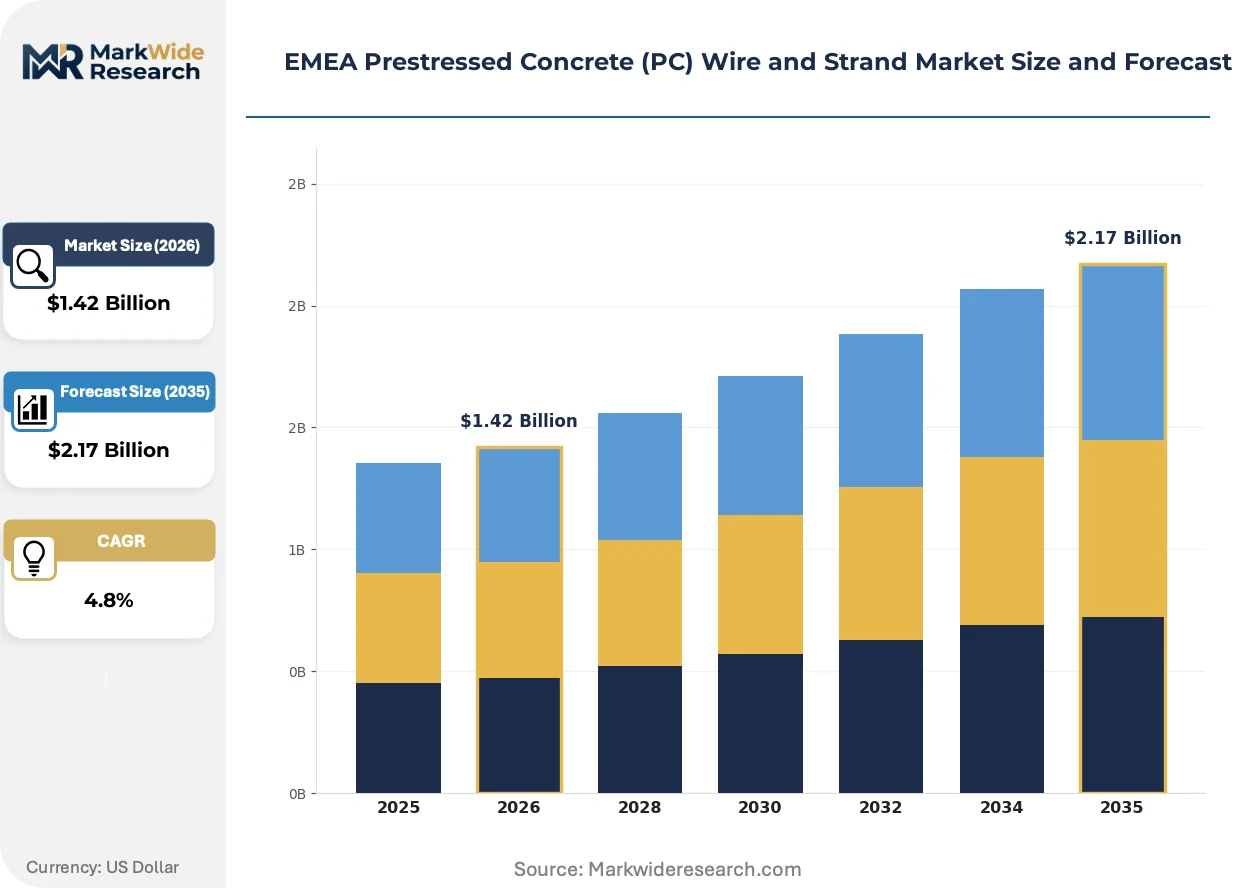
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PC Wire, PC Strand, PC Bar, PC Cable Application: Bridges, Buildings, Parking Structures, Water Tanks End User: Construction Companies, Civil Engineers, Transportation Authorities, Contractors Technology: Stress Relieving, Cold Drawing, Hot Rolling, Surface Treatment |
| Companies Covered | ArcelorMittal S.A., N.V. Bekaert S.A., DWK Drahtwerk Köln GmbH, FAPRICELA, Tensar International Limited, SABIC, TATA Steel Limited, Kiswire LTD., TMG Global Pte Ltd., Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Prestressed Concrete (PC) Wire and Strand Market Shifts & Advancements
Surface engineering and digital integration are displacing commodity-grade supply as infrastructure owners prioritize whole-life cost over initial material outlay. These shifts favor suppliers with in-house metallurgical R&D and field-service capabilities.
Hybrid corrosion-protection systems combining hot-dip galvanizing with organic topcoats are hybridizing the durability-performance tradeoff for Middle Eastern coastal infrastructure. Saudi Aramco and UAE transportation authorities specify these variants on twenty-five-year design-life marine structures. The technology is hybridizing procurement criteria away from pure alloy upgrades toward engineered coating architectures.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents is forcing reformulation of void-forming ducts used in bonded post-tensioning systems. Manufacturers are shifting to CO2-based physical foaming for duct cores to maintain CE marking compliance. German and Austrian bridge engineers are specifying these compliant ducts on federal highway tenders ahead of 2027 enforcement deadlines.
Asset owners are unbundling inspection and recertification from original supply contracts, creating standalone service revenue pools. European rail infrastructure managers now procure structural health assessments separately from material supply, fragmenting the traditional single-source model. This disintermediation is most pronounced in France and the United Kingdom where Network Rail and SNCF Réseau operate centralized bridge asset registries.
EMEA Prestressed Concrete (PC) Wire and Strand Market Segmentation
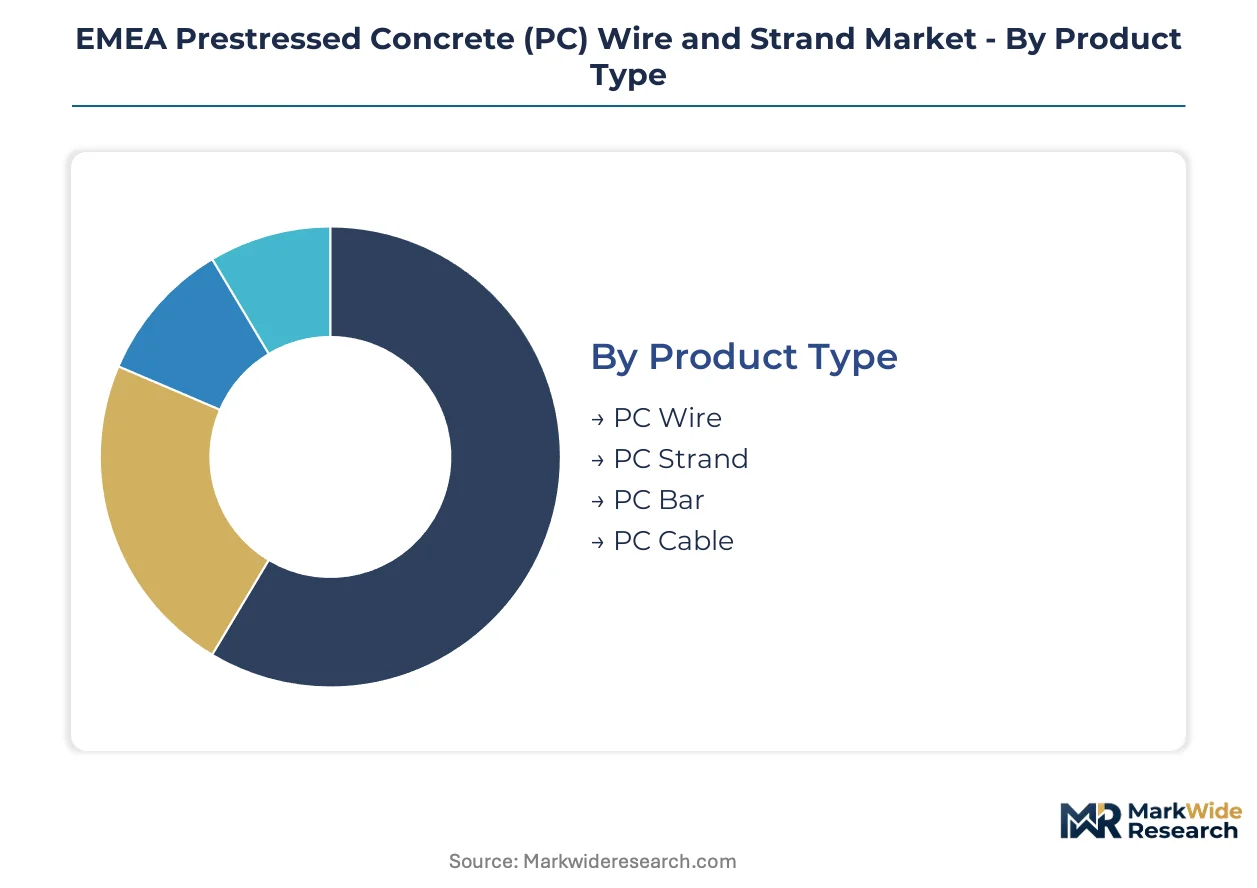
Segmentation in the EMEA Prestressed Concrete Wire and Strand Market reveals how specification requirements diverge across infrastructure types and procurement channels. Bridge engineers prioritize seven-wire strand configurations with superior fatigue resistance, while building contractors balance span capability against installation labor costs.
Product Type:
Product selection tracks directly to load-bearing requirements and tensioning methodology across EMEA infrastructure projects.
- PC Strand:Seven-wire helical configurations dominate bridge deck and post-tensioned slab applications across German Autobahn expansions and Saudi giga-projects. German transportation authorities specify this variant for its load distribution characteristics in continuous spans exceeding 40 meters.
- PC Wire:Single-wire products serve precast hollow-core flooring and railway sleeper manufacturing where automated tensioning lines favor simpler feedstock. French precasters favor drawn wire for standardized building components with repetitive section geometry.
- PC Bar:Threaded bars enable bonded post-tensioning in nuclear containment and liquid storage structures requiring re-tensioning capability. South African water authorities specify bar systems for reservoir domes in seismic zones.
- PC Cable:Multi-strand bundled cables address stay-cable and external tendon applications in cable-stayed bridges across the UAE and Qatar. Corrosion protection engineering drives specification more than material cost in these marine exposure environments.
Established volume favors PC Strand; emerging adoption favors PC Cable in Middle Eastern megaproject portfolios.
Application:
Application mix reflects EMEA public infrastructure spending patterns and urban density gradients.
- Bridges:Road and rail crossings concentrate demand in Germany, France, and Saudi Arabia where federal procurement pipelines favor long-span designs. Post-tensioned concrete box girders require seven-wire strand with strict relaxation specifications under EU Green Deal carbon accounting protocols.
- Buildings:Commercial and residential high-rises in Dubai and Riyadh drive flat-slab post-tensioning demand. Unbonded systems with greased-sheathing dominate here for speed of installation in tower construction cycles.
- Parking Structures:Multi-level car parks across UK urban centers specify corrosion-protected strand for durability in chloride-rich environments. Carbonation-induced corrosion governs design-life calculations more than structural load.
- Water Tanks:Circular prestressed concrete reservoirs in South Africa and Saudi Arabia employ circumferential wire winding or vertical bar tensioning. Leak-tightness requirements exceed structural efficiency as the primary design driver.
Bridge construction commands the dominant specification authority; building applications expand most quickly in Gulf Cooperation Council markets.
End User:
Procurement authority distribution shapes contract structures and supplier relationship intensity across the value chain.
- Transportation Authorities:German BAST, French SNCF Réseau, and Saudi Ministry of Transport embed whole-life cost models into tender evaluation. These entities specify performance-grade strand with mandatory Environmental Product Declarations under tightening carbon thresholds.
- Construction Companies:Tier-one contractors in UAE and Qatar bundle material supply with design-build contracts, favoring suppliers with integrated engineering support. Procurement teams prioritize installation productivity over unit material cost in labor-constrained markets.
- Civil Engineers:Consulting firms in France and the Netherlands specify strand characteristics in performance-based technical prescriptions. Design liability concentration drives conservative safety factor selection and premium-grade material preference.
- Contractors:Subcontracted post-tensioning specialists across Poland and Romania compete on installation speed and equipment utilization. These operators source commodity-grade strand through distributors with limited technical engagement.
Transportation Authorities anchor premium-grade demand; Contractors represent the steepest expansion trajectory as installation specialization fragments.
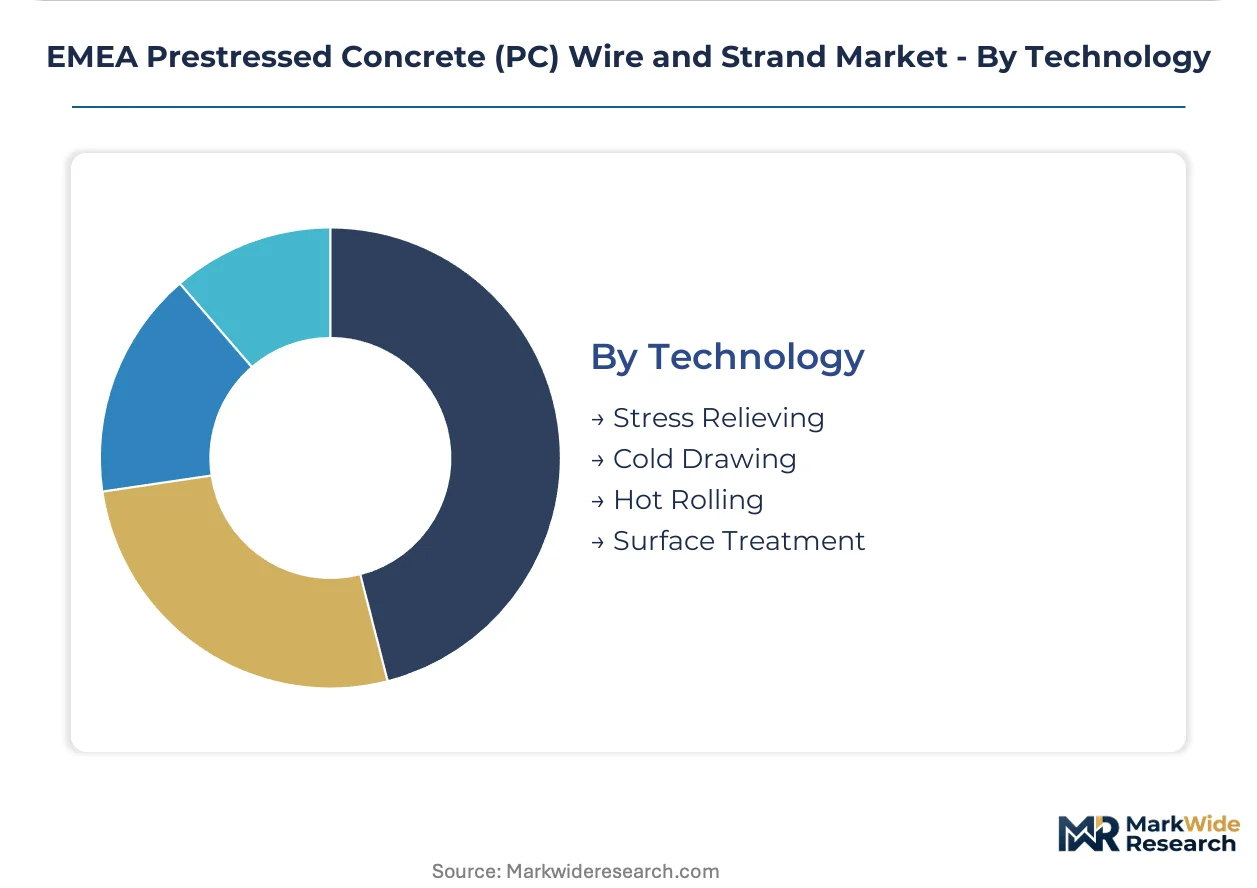
Technology:
Process technology selection determines mechanical property achievement and corrosion resistance capability.
- Surface Treatment:Epoxy coating and hot-dip galvanizing address durability mandates in Saudi coastal developments and Nordic de-icing salt exposure. Fusion-bonded epoxy variants command specification premiums in marine environments where design life exceeds 50 years.
- Stress Relieving:Continuous furnace heat treatment stabilizes microstructure for low-relaxation performance required in bridge stay-cables and bonded post-tensioning. German and Austrian mills lead process control precision for this specification tier.
- Cold Drawing:Multi-pass reduction from wire rod to final diameter achieves tensile strengths exceeding 1,860 MPa through work hardening. DWK Drahtwerk Köln and Belgian integrated producers control precision tolerance capability for German rail authority contracts.
- Hot Rolling:Bar and coarse wire production for threaded bar systems employs controlled rolling to achieve mechanical properties without subsequent drawing. Energy intensity and scale economics favor integrated steelmakers with captive rod supply.
Surface Treatment gains specification share fastest; Stress Relieving remains the volume foundation for structural-grade supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across EMEA: European transportation authorities prioritize low-carbon PC strand for bridge rehabilitation, while Middle Eastern developers specify corrosion-resistant variants for coastal megaprojects. African procurement concentrates on cost-optimized wire for rail sleeper replacement programs.
Germany
Federal Autobahn expansions and rail bridge renewals drive specification of seven-wire low-relaxation strand. BAST mandates Environmental Product Declarations under EU Green Deal carbon thresholds for all superstructure materials. The Rhine-Ruhr industrial corridor hosts integrated steelmaking and precision drawing operations serving domestic transportation authorities.
Saudi Arabia
NEOM and Red Sea Project developments generate concentrated demand for epoxy-coated and galvanized strand in marine exposure zones. SASO certification requirements govern public infrastructure procurement timelines and technical compliance. Eastern Province industrial cities host downstream wire processing facilities supplying giga-project construction sites.
France
SNCF Réseau's bridge asset registry drives aftermarket inspection services and replacement strand procurement for aging viaducts. CE marking under the EU Construction Products Regulation governs mechanical performance declarations for all structural applications. The Grand Est region concentrates post-tensioning contractors serving cross-border rail corridors.
South Africa
Transnet freight corridor expansions and water reservoir construction sustain demand for PC wire and bar systems. SABS certification creates parallel compliance pathways for suppliers targeting public infrastructure tenders. Gauteng province hosts precast concrete manufacturing clusters supplying regional infrastructure projects.
United Arab Emirates
Dubai and Abu Dhabi transportation authorities specify fusion-bonded epoxy strand for coastal bridge structures exceeding fifty-year design life. MOHAP-adjacent technical regulations influence construction material standards in parallel with SASO alignment. Jebel Ali industrial zone concentrates steel processing and surface treatment capabilities for regional re-export.
EMEA Prestressed Concrete (PC) Wire and Strand Market Competitive Landscape
Capability concentration sits with integrated steelmakers controlling wire rod supply; scale advantage sits with specialized wire drawers serving premium specification tiers. The market structures around three archetypes: integrated metallurgical producers with captive feedstock, precision cold-draw specialists with transportation authority relationships, and surface treatment innovators addressing coastal durability mandates. Dominant competitive moves include backward integration into wire rod production and geographic expansion through dual-certification partnerships in Saudi Arabia and South Africa.
Among European integrated producers, ArcelorMittal S.A. and N.V. Bekaert S.A. occupy positions representing scale metallurgy and specialized surface engineering respectively. DWK Drahtwerk Köln GmbH exemplifies the precision-draw specialist archetype with German transportation authority relationships. These three entities anchor the competitive structure through differentiated control points: captive steelmaking, coating technology, and tolerance precision.
| Leading Market Players |
|---|
| ArcelorMittal S.A. |
| N.V. Bekaert S.A. |
| DWK Drahtwerk Köln GmbH |
| FAPRICELA |
| Tensar International Limited |
| SABIC |
| TATA Steel Limited |
| Kiswire LTD. |
| TMG Global Pte Ltd. |
| Others |
Supply & Pricing Matrix
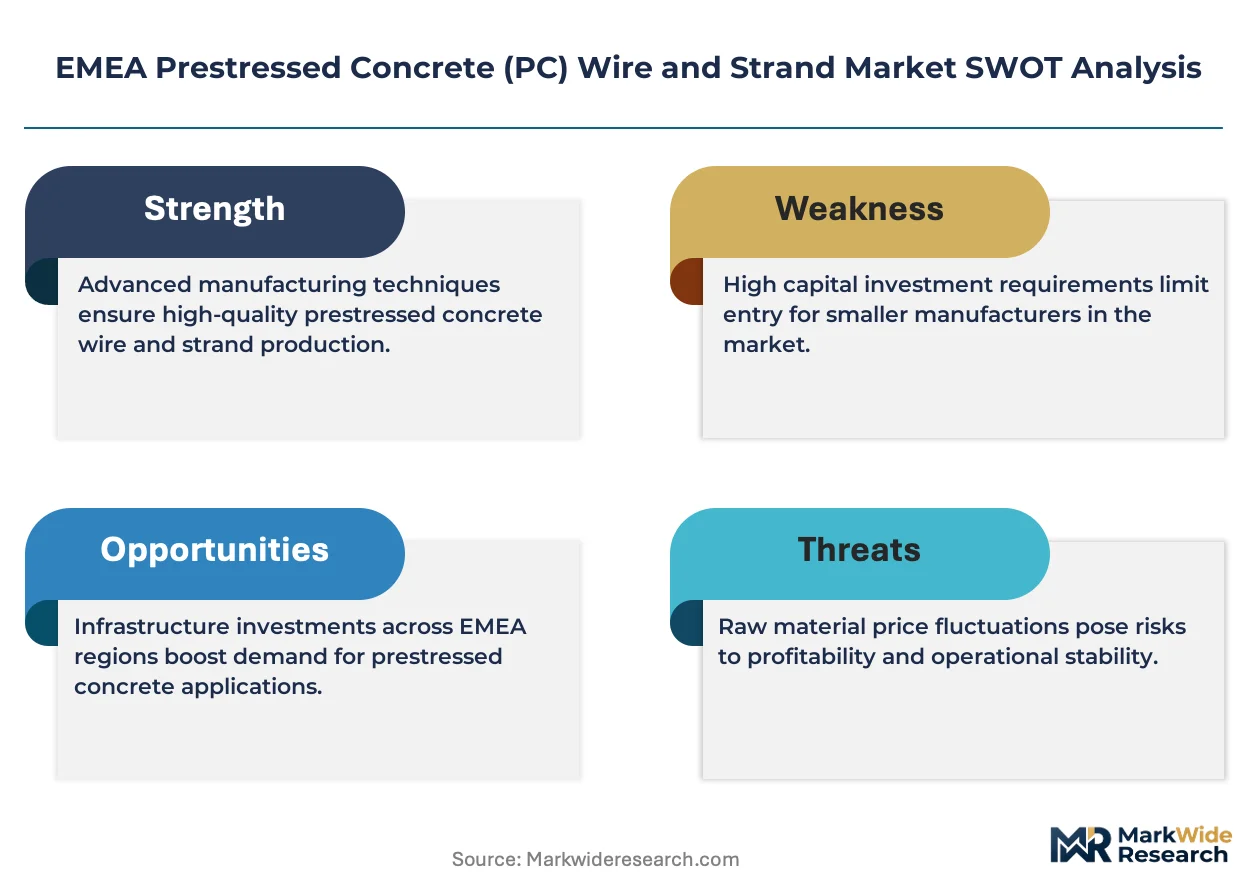
Overcapacity in Turkish wire rod mills is compressing feedstock premiums across Southern European drawing operations, forcing independent processors to absorb margin erosion or surrender market share to integrated producers with captive steelmaking. This utilization imbalance simultaneously empowers Belgian-Luxembourg integrated mills to enforce long-term offtake terms on German transportation authority contracts while squeezing mid-tier competitors into spot-market vulnerability.
Pricing Analysis
Long-term offtake agreements anchor pricing stability for German and French transportation authority contracts, while spot-market exposure dominates procurement for Gulf Cooperation Council project contractors facing compressed construction timelines. Price differentiation rests on CE marking tier and Environmental Product Declaration depth, with premium-grade low-relaxation strand commanding substantial spreads over commodity wire for precast applications. Cost compression in standard-grade supply is intensifying because Turkish scrap arbitrage volatility transmits directly into wire rod quotations. Contractors represent the most price-sensitive segment, prioritizing installation productivity over unit material cost in labor-constrained Middle Eastern markets.
Supply Chain Analysis
Belgian, Luxembourg, and German integrated steelmakers hold dominant wire rod capacity serving downstream drawing operations across the EMEA region. Raw material flows draw from Turkish scrap import markets, Egyptian billet arbitrage, and domestic European steel recycling streams. Single-source vulnerability concentrates in the Rhine-Ruhr industrial corridor where three producers control critical feedstock supply. Distribution runs through direct mill relationships for large transportation authority contracts and specialized distributors serving fragmented post-tensioning contractors in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prestressed concrete wire and strand sits in early-cycle expansion as Saudi Vision 2030 giga-projects accelerate specification of corrosion-resistant surface-treated variants for coastal megadevelopments. Infrastructure carbon accounting across European transportation authorities is embedding Environmental Product Declarations into tender scoring, creating premium-tier demand expansion.
For Market Incumbents: Harden supply security through backward integration into wire rod production or exclusive offtake partnerships with Belgian-Luxembourg mills, insulating against Turkish scrap volatility that threatens margin stability. Deepen certification investments for dual SASO-SABS pathways to capture South African rail modernization and Saudi coastal infrastructure procurement before mid-cap competitors establish local testing partnerships. Fiber-reinforced polymer substitution in select cable-stayed applications demands accelerated R&D in sensor-embedded smart strand to create defensible aftermarket revenue streams. For New Entrants and Emerging Players: South African water reservoir construction and Transnet freight corridor bridge replacement represent the most penetrable entry points, with SABS certification requirements creating temporary shelter from established European suppliers lacking local testing infrastructure. Epoxy-powder hybrid coating specialization for Arabian Gulf salt-fog exposure zones offers specification differentiation without requiring integrated steelmaking scale. A go-to-market angle anchored through South African engineering partnerships can bypass the eighteen-month dual-certification timelines that delay European mid-cap market entry. For Investors and Strategic Acquirers: Capital is best deployed toward precision cold-draw specialists with established transportation authority relationships and in-house stress-relief furnace capabilities, as specialized heat-treatment technician scarcity creates durable competitive moats. Surface treatment innovators with fusion-bonded epoxy metallization expertise command premium positioning in Middle Eastern marine exposure specifications. The signal to watch is Saudi Aramco and UAE transportation authority procurement pattern shifts toward twenty-five-year design-life coating architectures, indicating acceleration in premium-tier demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod Production | Captive supply from Belgian-Luxembourg mills secures margin visibility against Turkish scrap arbitrage volatility. |
| Dual Certification Partnership | SASO-SABS parallel pathways accelerate Saudi and South African public infrastructure tender participation timelines. |
| Hybrid Coating Technology Development | Fusion-bonded epoxy with zinc-aluminum metallization opens specification in Arabian Gulf salt-fog exposure zones. |
| Sensor-Embedded Smart Strand Launch | Digital twin integration creates aftermarket structural health monitoring subscriptions on aging European viaducts. |
| Stress-Relief Furnace Capacity Expansion | Continuous-line heat treatment precision addresses retiring technician scarcity in Germany and Poland. |
Research Methodology
The analysis maps prestressed concrete wire, strand, bar, and cable sub-sectors, each validated through primary interviews with bridge engineers, post-tensioning contractors, transportation authority procurement officers, and steel mill technical directors. Secondary validation draws from EU Construction Products Regulation filings, SASO and SABS certification registries, customs wire rod trade data, and Environmental Product Declaration databases. Bottom-up project pipeline assessment across German Autobahn expansions, Saudi giga-projects, and South African Transnet corridors triangulates against top-down steel consumption modeling.
Assumptions held fixed include EU Green Deal carbon threshold enforcement timelines and Saudi Vision 2030 infrastructure commitment continuity, while scrap steel price volatility and fiber-reinforced polymer substitution rates were varied across sensitivity scenarios. Segmentation dimensions encompass product type, application, end-user procurement authority, and surface treatment technology tier. CAGRs were derived from elasticity-adjusted demand projections incorporating infrastructure spending correlation analysis and prestressed concrete intensity per bridge deck square meter.
Stress conditions across Turkish scrap import arbitrage, Belgian-Luxembourg mill maintenance cycles, and dual-certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of transportation authority tender scoring methodology shifts and Saudi giga-project construction pace indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Fiberglass Doors Market