
 Europe Exterior Sheathing Market | 2026-2036
Europe Exterior Sheathing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Exterior Sheathing Market Intelligence
Green project finance and sustainability-linked leasing is rewriting capital access for exterior sheathing procurement across European construction value chains. Knauf Insulation leverages its mineral wool integration to anchor specification in energy-efficiency retrofit programs. Kingspan Group plc competes through controlled distribution of insulated panel systems into commercial envelope projects. James Hardie Industries plc differentiates via fiber-cement technology leadership in moisture-resistant residential applications.
Europe exterior sheathing comprises structural and non-structural panels applied to building frames to brace walls, manage moisture, and provide substrate for cladding systems, typically manufactured from wood-based composites, cementitious matrices, or thermoplastic resins in thicknesses ranging from 12 mm to 25 mm. OSB dominates volume in residential framing across Northern Europe due to engineered consistency and competitive fiber economics. Fiber cement occupies premium positioning in commercial and multi-family segments where fire resistance ratings and facade integration command margin pools. Vinyl sheathing sustains growth in agricultural and light industrial outbuildings through low installed cost and minimal maintenance requirements.
CE marking under the EU Construction Products Regulation mandates declared performance for mechanical resistance and reaction-to-fire characteristics, while REACH restricts formaldehyde emissions from resin-bonded wood panels. France's RE2020 environmental regulation and Germany's EnEV thermal standards collectively shape product formulation priorities and market access conditions. Stakeholders must monitor evolving embodied carbon accounting rules under the EU Green Deal that will recertify acceptable material hierarchies before the next building code revision cycle.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing material hierarchies across specification chains, forcing substitution toward lower-carbon substrates before the next building code revision cycle completes.
Growth Catalysts
- France's RE2020 environmental regulation:Mandates lifecycle carbon accounting for new construction, accelerating engineered panel adoption in dense urban corridors.
- Residential retrofit programs:Germany's building stock renovation targets are pulling specification upgrades across mineral wool-integrated systems.
- Moisture-resistant fiber-cement technology:Multi-family developers in Belgium and the Netherlands specify these panels for facade integration with fire resistance ratings.
Market Restraints
- Resin input cost volatility:Formaldehyde-based binders in OSB production face price swings tied to petrochemical feedstock markets.
- Baltic supply concentration:Softwood fiber for engineered panels clusters in Scandinavian and Baltic state sawmill networks, creating geographic vulnerability.
- REACH emission restrictions:Tightening formaldehyde limits from resin-bonded wood panels add compliance friction for mid-tier manufacturers.
Strategic Opportunities
- Poland's underpenetrated commercial envelope segment:Logistics and light industrial construction growth outpaces specification of insulated panel systems.
- EU CSRD disclosure mandates:Large contractors face supply chain emissions reporting requirements, favoring suppliers with verified EPDs.
- Digital specification platforms:BIM-integrated product libraries are compressing architect-to-manufacturer direct channels in France and Germany.
Industry Challenges
- Fire testing certification timelines:CE marking under CPR for reaction-to-fire characteristics requires extended laboratory validation cycles.
- Cross-border logistics reconfiguration:Post-Brexit customs friction disrupts just-in-time panel delivery to UK construction sites from continental mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Exterior Sheathing Market |
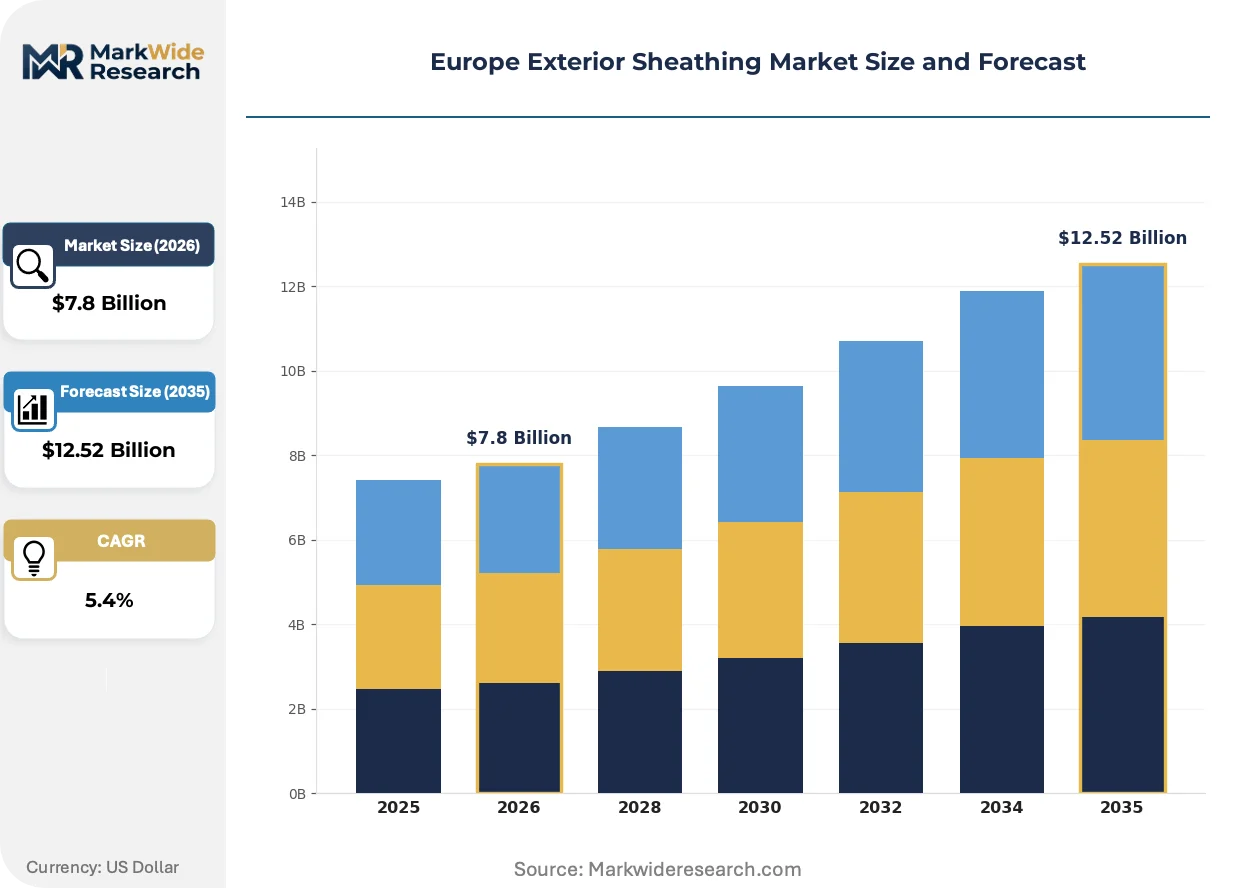
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, OSB, Fiber Cement, Vinyl Application: Residential, Commercial, Agricultural, Industrial Thickness: 1/2 inch, 5/8 inch, 3/4 inch, 1 inch Installation Method: Nail, Screw, Adhesive, Clip |
| Companies Covered | Weyerhaeuser Company, Knauf Insulation, Georgia-Pacific LLC, Fermacell GmbH, CertainTeed Corporation, Huber Engineered Woods LLC, James Hardie Industries plc, Kingspan Group plc, Louisiana-Pacific Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Exterior Sheathing Market Strategic Shifts & Innovations
Material science convergence and digital specification tools are compressing traditional product hierarchies while regulatory disclosure mandates reshape procurement qualification criteria across European construction value chains.
Cross-laminated timber sheathing is hybridizing structural and insulation functions in single-layer wall assemblies. Scandinavian multi-family developers specify these panels to reduce envelope complexity and accelerate close-in schedules. The technology is compressing demand for separate OSB and mineral wool layering in mid-rise residential projects.
REACH formaldehyde emission restrictions are tightening resin chemistry requirements for wood-based panels. Manufacturers reformulate binders toward phenol-resorcinol or bio-based alternatives to maintain market access. French and German specification offices now prioritize EPD-verified low-emission products in public procurement frameworks.
Architects and contractors are consolidating specification decisions around embodied carbon databases. Digital platforms like One Click LCA and EC3 displace traditional manufacturer catalog relationships. This behavioral shift concentrates most visibly in Netherlands and Denmark where municipal clients mandate whole-building LCA submissions.
Europe Exterior Sheathing Market Segmentation
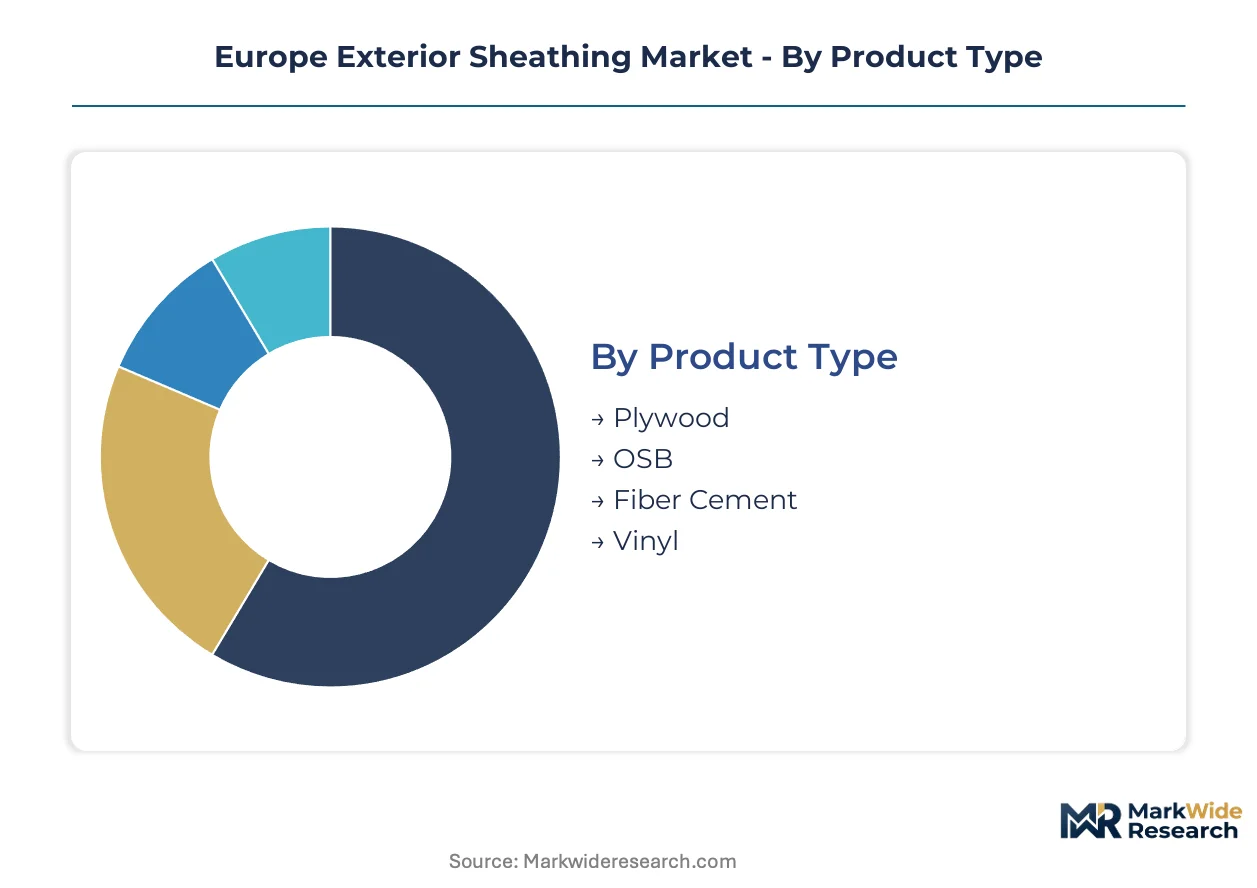
Specification cycles for exterior sheathing vary dramatically across product categories and end-use applications. Procurement patterns in residential retrofit programs compress decision timelines for standard panel formats. Complex commercial envelope projects extend specification cycles as fire certification and embodied carbon accounting add validation layers.
Product Type:
Replacement cycles differentiate these segments sharply, with agricultural and light industrial outbuildings demanding refresh every 12-15 years while commercial facades extend to 25-30 year service intervals.
- OSB:Engineered wood panels bonded with phenolic or isocyanate resins deliver dimensional stability across variable moisture conditions. German and Scandinavian residential developers specify OSB for its fiber economics and CE-marked structural consistency under the Construction Products Regulation. REACH formaldehyde emission restrictions are forcing binder reformulation toward bio-based alternatives.
- Fiber Cement:Calcium silicate matrices reinforced with cellulose fibers provide fire resistance ratings and moisture immunity for multi-family facades. Belgium and Netherlands developers specify these panels where RE2020 lifecycle carbon thresholds and facade integration requirements command premium positioning. Extended laboratory validation for reaction-to-fire certification compresses manufacturer margins.
- Plywood:Cross-laminated veneer construction delivers structural shear capacity for traditional timber framing applications. Baltic softwood fiber concentration creates geographic supply vulnerability.
- Vinyl:PVC resin extrusions with integrated drainage planes serve agricultural outbuildings and light industrial structures. Low installed cost and minimal maintenance sustain specification in price-sensitive segments.
OSB anchors the volume base while fiber cement gains share at the steepest rate.
Application:
End-use concentration shapes margin structures, with commercial envelope projects supporting three-tier pricing across premium, standard, and economy certification grades while agricultural applications compete on raw material efficiency.
- Residential:Single-family and multi-family construction drives specification of moisture-managed panel systems integrated with mineral wool insulation. France's Ile-de-France corridor concentrates demand for engineered panel assemblies meeting RE2020 thermal performance mandates. German EnEV standards accelerate retrofit specification upgrades.
- Commercial:Office, retail, and institutional envelopes specify fire-rated panel systems with verified EPDs for EU CSRD supply chain disclosure compliance. Netherlands and Denmark municipal procurement frameworks mandate whole-building LCA submissions.
- Agricultural:Barns, storage facilities, and livestock structures prioritize low capital outlay and chemical resistance. Vinyl and OSB dominate specification.
- Industrial:Logistics centers and manufacturing facilities demand rapid envelope close-in with minimal labor input. Insulated panel systems concentrate specification in Poland's expanding warehouse construction segment.
Residential applications command the revenue base while commercial projects exhibit the steepest specification upgrade trajectory.
Thickness:
Panel thickness correlates directly with structural load-bearing requirements and thermal bridging performance, creating distinct specification tiers across climate zones and building heights.
- 5/8 inch:The dominant specification for residential wall bracing and commercial curtainwall substrate across Northern Europe. This thickness balances shear capacity with fastener holding power for nail and screw installation methods. German timber-frame construction codes reference this dimension as standard.
- 1/2 inch:Light-duty applications in agricultural outbuildings and interior shear walls where structural demand is minimal. Cost-sensitive specification dominates.
- 3/4 inch:Heavy commercial and industrial applications requiring enhanced racking resistance. Multi-story timber construction in Scandinavian markets specifies this thickness.
- 1 inch:Structural insulated panels and high-performance envelopes combining sheathing with integrated insulation. Premium positioning limits volume.
5/8 inch panels anchor specification volume while 1 inch assemblies expand most quickly in mid-rise timber construction.
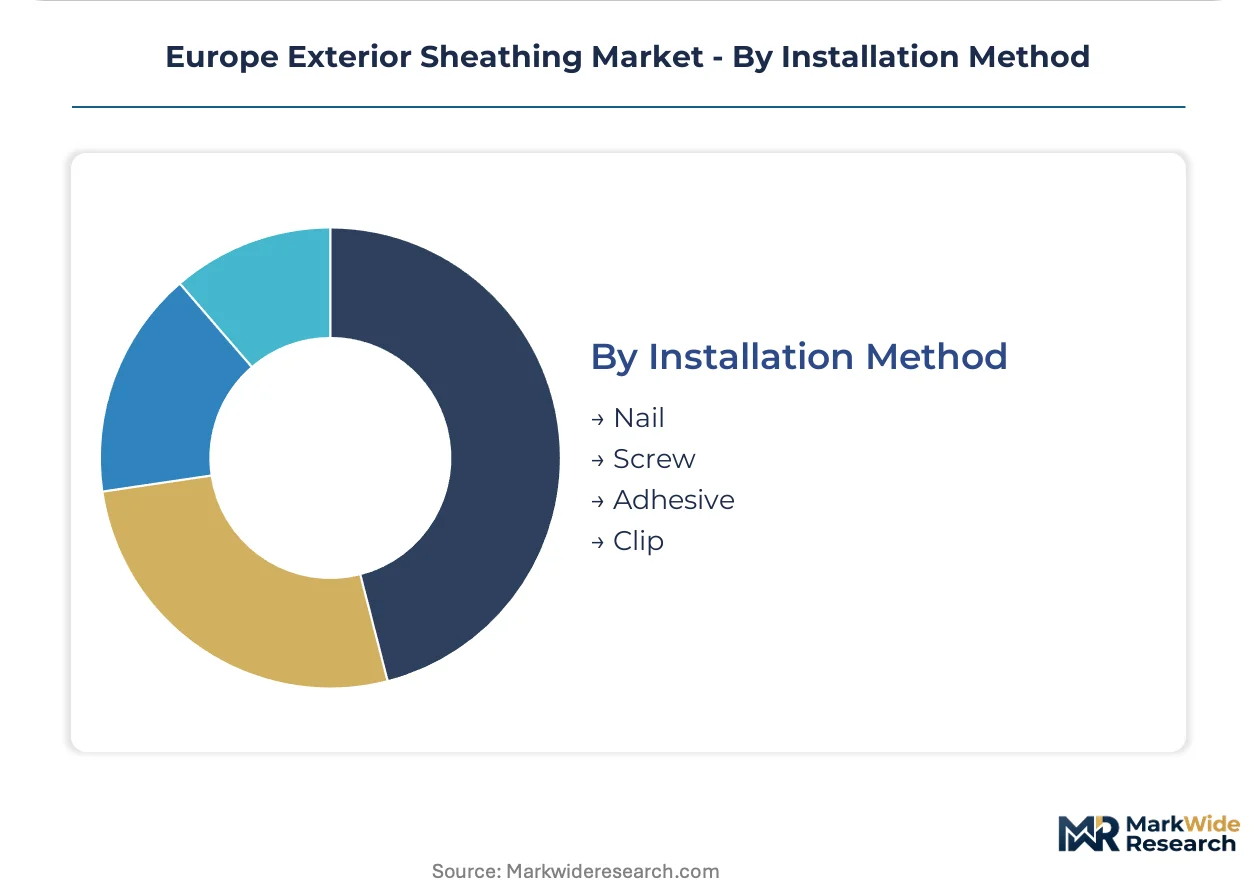
Installation Method:
Labor cost differentials and weather-tightness requirements separate these attachment approaches, with mechanical fastening dominating Northern European markets and adhesive systems penetrating Mediterranean climates.
- Nail:Pneumatic fastening dominates residential framing across Germany, Poland, and the Baltic states. Speed of installation and familiarity with timber-frame construction sustain specification. CE marking requirements for nail withdrawal resistance shape panel surface preparation.
- Screw:Enhanced pull-out capacity suits commercial applications and high-wind zones. Belgium and Netherlands specification offices favor screw attachment for facade integration reliability.
- Adhesive:Structural adhesives penetrate Mediterranean markets where masonry substrate conversion and moisture management drive specification. Extended cure times limit cold-weather application.
- Clip:Concealed fastening systems serve premium facade applications where aesthetic continuity matters. Rainscreen assemblies in French commercial projects specify clip attachment.
Nail installation anchors the volume base while clip systems gain specification share in architect-driven commercial facades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's embodied carbon thresholds and national retrofit mandates are redistributing specification intensity across European construction corridors. France's RE2020 and Germany's EnEV standards anchor regulatory divergence that shapes material substitution patterns.
Germany
Residential retrofit programs targeting building stock renovation pull specification upgrades toward mineral wool-integrated panel systems. EnEV thermal standards mandate performance thresholds that compress decision timelines for engineered products. The Rhine-Ruhr metropolitan corridor concentrates demand for OSB and fiber-cement assemblies in multi-family energy-efficiency projects.
France
RE2020 lifecycle carbon accounting mandates accelerate engineered panel adoption in dense urban construction zones. Public procurement frameworks now prioritize EPD-verified low-emission products for municipal building envelopes. The Ile-de-France corridor anchors specification concentration where facade-integrated panel systems command premium positioning.
Netherlands
Municipal clients mandate whole-building LCA submissions that compress architect specification behavior around embodied carbon databases. Digital platforms displace traditional manufacturer catalog relationships in commercial envelope procurement. The Randstad urban agglomeration drives demand for fire-rated panel systems with verified supply chain disclosures.
Poland
Logistics and light industrial construction growth outpaces specification of insulated panel systems in the commercial envelope segment. Warehouse construction expansion in the Warsaw and Krakow metropolitan areas creates specification gaps for rapid envelope close-in solutions. Baltic softwood fiber networks supply engineered panel mills with geographic concentration risk.
Belgium
Multi-family developers specify moisture-resistant fiber-cement panels where facade integration and fire resistance ratings command margin pools. Extended laboratory validation for CE marking reaction-to-fire certification compresses manufacturer margins. The Brussels-Antwerp-Ghent corridor concentrates commercial envelope projects requiring screw-attachment reliability.
Europe Exterior Sheathing Market Key Industry Players
Channel-controlling players compete with product-specialist players across specification tiers defined by certification grade and thermal performance. The vendor base clusters around three strategic archetypes: integrated building materials conglomerates, engineered wood specialists, and facade-system pure-plays. Consolidation pressure concentrates among mid-tier resin-bonded panel manufacturers facing REACH compliance friction. Dominant competitive moves include backward integration into captive fiber supply and strategic partnerships with digital specification platforms.
Among Germany-based building materials specialists, Knauf Insulation and Fermacell GmbH exemplify the integrated-systems archetype that anchors specification in energy-efficiency retrofit programs. Kingspan Group plc occupies a position within the insulated panel specialist tier competing through controlled distribution into commercial envelope projects. James Hardie Industries plc represents the fiber-cement technology leadership position in moisture-resistant residential applications. Weyerhaeuser Company and Louisiana-Pacific Corporation sit within the North American-engineered wood specialist group supplying Northern European markets through Baltic fiber networks.
| Leading Market Players |
|---|
| Weyerhaeuser Company |
| Knauf Insulation |
| Georgia-Pacific LLC |
| Fermacell GmbH |
| CertainTeed Corporation |
| Huber Engineered Woods LLC |
| James Hardie Industries plc |
| Kingspan Group plc |
| Louisiana-Pacific Corporation |
| Others |
Cost & Logistics Intelligence
Baltic sawmill clusters in Latvia and Estonia anchor fiber supply for engineered panel production, with capacity utilization swings directly transmitting to OSB pricing power across Northern European construction markets. German and Polish distributors absorb these fluctuations through long-term offtake contracts that buffer spot market volatility.
Pricing Analysis
Certification level creates the primary spread across exterior sheathing tiers, with CE-marked reaction-to-fire ratings commanding substantial premiums over standard structural grades. Three-tier pricing structure across premium, standard, and economy levels separates fiber-cement facade systems from commodity OSB and agricultural vinyl panels. Cost compression in mid-tier resin-bonded products is intensifying because REACH formaldehyde restrictions force binder reformulation. Agricultural end-users exhibit highest price sensitivity, while commercial envelope developers prioritize fire-rated certification over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now dominate supplier-financing arrangements as mills compete for specification loyalty among major distributors. Raw material flows draw from Scandinavian softwood forests, German petrochemical complexes for phenolic resins, and Belgian calcium silicate deposits for fiber-cement matrices. Single-source vulnerability concentrates in Baltic fiber networks where sawmill consolidation has reduced qualified supplier pools. Distribution runs through national building materials merchants with direct-to-contractor platforms gaining share in France and Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
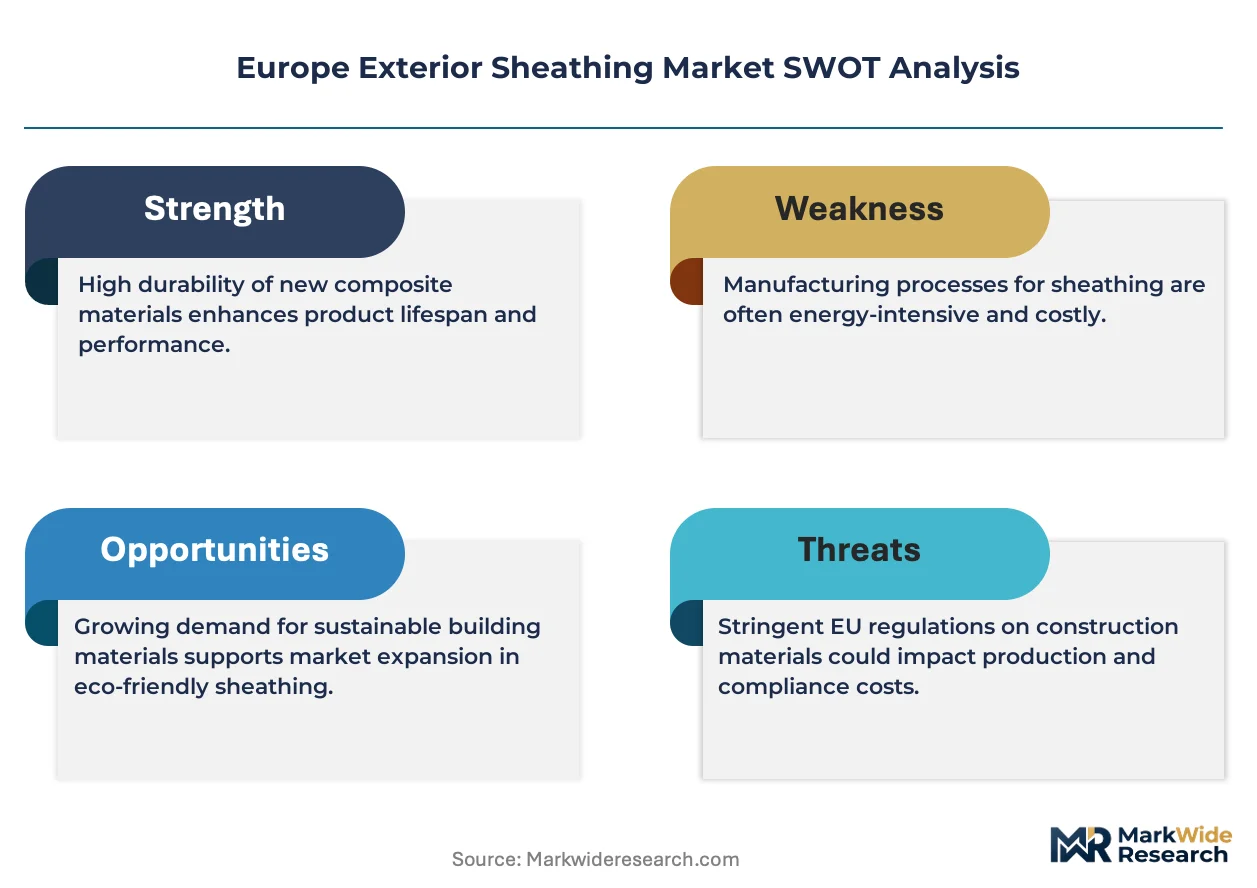
This market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH compliance and CE marking timelines create structural barriers that protect incumbents from rapid competitive displacement.
For Market Incumbents: Pre-empt specification lock-in by embedding EPD-verified products into France's RE2020-mandated public procurement frameworks before the next building code revision cycle completes. Deepen captive fiber supply through Baltic sawmill partnerships to defend against resin input cost volatility. Prioritize certification investment in reaction-to-fire ratings to maintain premium positioning against emerging cross-laminated timber substitutes.
For New Entrants and Emerging Players: Pursue Poland's underpenetrated commercial envelope segment where logistics construction growth outpaces insulated panel system specification. Target digital specification platform partnerships as the primary go-to-market angle, compressing architect-to-manufacturer channels in Netherlands and Denmark municipal procurement. White-space opportunity concentrates in rapid-installation clip-system products for French rainscreen facades.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among facade-system pure-plays with specification-anchored maintenance contracts. Long-term viability favors acquisition targets with verified EPD libraries and EU CSRD disclosure-ready supply chain data. Watch for inflection signals in embodied carbon accounting rule finalization under the EU Green Deal, which will recertify acceptable material hierarchies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Baltic Fiber Supply | Captive softwood sourcing mitigates geographic concentration risk from Scandinavian sawmill networks. |
| EPD Verification Investment | Environmental Product Declaration certification unlocks France RE2020 and Netherlands municipal procurement eligibility. |
| Digital Specification Platform Partnership | BIM-integrated product libraries compress architect decision cycles in Germany and France commercial projects. |
| Bio-Based Binder Reformulation | Phenol-resorcinol alternatives maintain REACH compliance as formaldehyde emission restrictions tighten. |
| Insulated Panel System Capacity Addition | Poland logistics construction growth creates demand for rapid envelope close-in solutions. |
Research Approach
A spread of perspectives from plant managers at engineered panel mills, procurement leads at German and French distributors, technical R&D directors at resin suppliers, and specification architects in Belgium and Netherlands converged on the working assumptions. Secondary validation drew from EU Construction Products Regulation filings, ECHA REACH substance dossiers, national building stock renovation databases, and customs trade data for softwood fiber flows. Bottom-up segment sizing triangulated against top-down construction spend allocation across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across product type, application, thickness tier, and installation method. CAGRs derived from regression analysis of historical specification intensity against regulatory mandate implementation timelines. Industry-specific forecast inputs included EnEV thermal standard compliance deadlines and EU Green Deal embodied carbon threshold evolution.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates, energy input costs, or Baltic fiber export tariffs would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pacing and substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United States Architectural Coatings Market
Building Materials
Block Paving Market
Building Materials
Roof Cover Boards Market
Building Materials
Ductile Iron Pipe Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Cribbing Blocks Market
Building Materials
East Africa Cement Market
Building Materials
Low-E Construction Glass Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Mass Timber Construction Market
Building Materials
Roofing and Insulation Market
Building Materials
Building and Construction Plastics Market