
 Global Steel Service Centers Market | 2026-2036
Global Steel Service Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steel Service Centers Market Foresight
Digital coil tracking and automated inventory orchestration is rewriting how steel service centers synchronize mill schedules with just-in-time fabrication demand. Reliance Steel & Aluminum Co. leverages its decentralized branch network to sustain same-day fulfillment across North American manufacturing clusters. Kloeckner Metals Corporation anchors its competitive stance through a cloud-connected platform that links customers to real-time stock levels across 40-plus locations. Tata Steel Limited differentiates via integrated ownership of upstream melt capacity and downstream precision slitting operations.
Steel service centers function as intermediate processors that transform mill-produced hot-rolled and cold-rolled coils into dimensionally precise blanks, slit strips, and leveled sheets meeting ASTM or EN thickness tolerances. Their primary commercial purpose is to absorb batch-scale mill economics while delivering small-lot, specification-matched feedstock to fabricators and OEM assembly lines. Cut-to-length and slitting services command the largest share of value flow given their ubiquity across construction and heavy machinery supply chains, while laser cutting and robotic handling represent the fastest-expanding technology tier as automotive and renewable energy customers specify tighter edge quality and repeatability. Blanking and edge conditioning capture concentrated margin pools where aerospace and tier-1 supplier certifications create qualification barriers.
The US EPA enforces emissions reporting under the Greenhouse Gas Reporting Program that extends to steel processing facilities above threshold thermal inputs, while REACH and the EU Carbon Border Adjustment Mechanism shape material sourcing standards for European-bound exports. Japan's METI administers energy-efficiency benchmarks under the Top Runner program that influence equipment upgrade cycles at domestic processing centers. Stakeholders must monitor how divergent carbon-accounting rules across Washington, Brussels, and Tokyo fragment compliance architectures and reshape supplier qualification criteria.
Market Dynamics
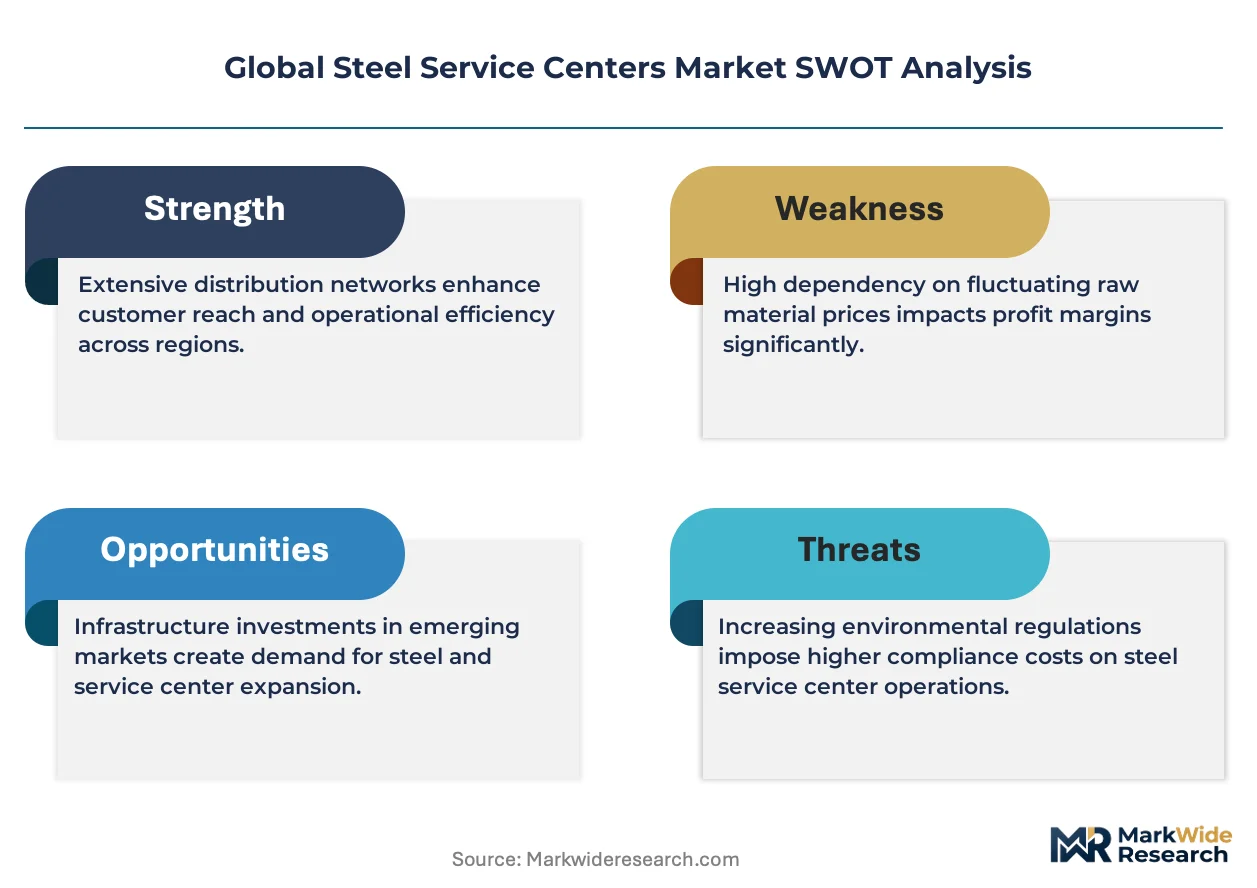
The EU Carbon Border Adjustment Mechanism is forcing steel service centers to reconstruct supply chain documentation from ore source to finished coil, compressing margins for processors lacking embedded emissions tracking infrastructure.
Growth Catalysts
- EV Platform Architecture:Automotive OEMs specify tailored high-strength steel blanks for battery enclosure structures and lightweight chassis components. Demand concentrates in India's western industrial corridor stretching from Mumbai to Pune.
- Digital Coil Tracking:Automated inventory orchestration synchronizes mill schedules with just-in-time fabrication demand. Cloud-connected platforms link customers to real-time stock levels across distributed branch networks.
- REACH Compliance:European material sourcing standards reshape supplier qualification criteria for export-bound processors. Documentation of chemical substance thresholds creates competitive moats for certified service centers.
Market Restraints
- Scrap Price Volatility:Ferrous scrap inputs swing with Turkish export demand and container shipping rates. Margin compression hits processors without long-term mill supply agreements.
- Upstream Concentration:Integrated steel mills in China and India control two-thirds of global hot-rolled coil capacity. Independent service centers face allocation rationing during supply tightness.
- Substitution by Aluminum:Battery electric vehicle manufacturers specify aluminum extrusions for closure panels and structural nodes. High-strength steel loses share in body-in-white applications above 150 kg per vehicle.
Strategic Opportunities
- Renewable Energy Fabrication:Wind tower manufacturers require thick-gauge plate with through-thickness toughness certification. Service centers with in-house thermal cutting and ultrasonic testing capture specification-driven premiums.
- US IRA Manufacturing Credits:Domestic content bonuses for clean energy infrastructure stimulate greenfield processing capacity. Co-location with solar tracker and inverter assembly plants reduces logistics costs.
- Laser-Blanking Convergence:Fiber laser cutting married to automated material handling collapses setup times for small-lot aerospace orders. Edge quality repeatability satisfies AMS specifications without secondary conditioning.
Industry Challenges
- Millwright Skill Scarcity:Precision slitting line maintenance requires expertise in hydraulic tension control and edge trim optimization. Retirement waves deplete the technician pipeline faster than vocational programs replenish it.
- AS9100 Certification Timelines:Aerospace customer qualification spans 18-24 months for first article approval. Working capital ties up in inventory segregation and audit documentation before revenue recognition.
- Legacy ERP Integration:Coil tracking systems must interface with 1990s-era mill scheduling software. Data format incompatibilities delay real-time visibility deployments by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steel Service Centers Market |
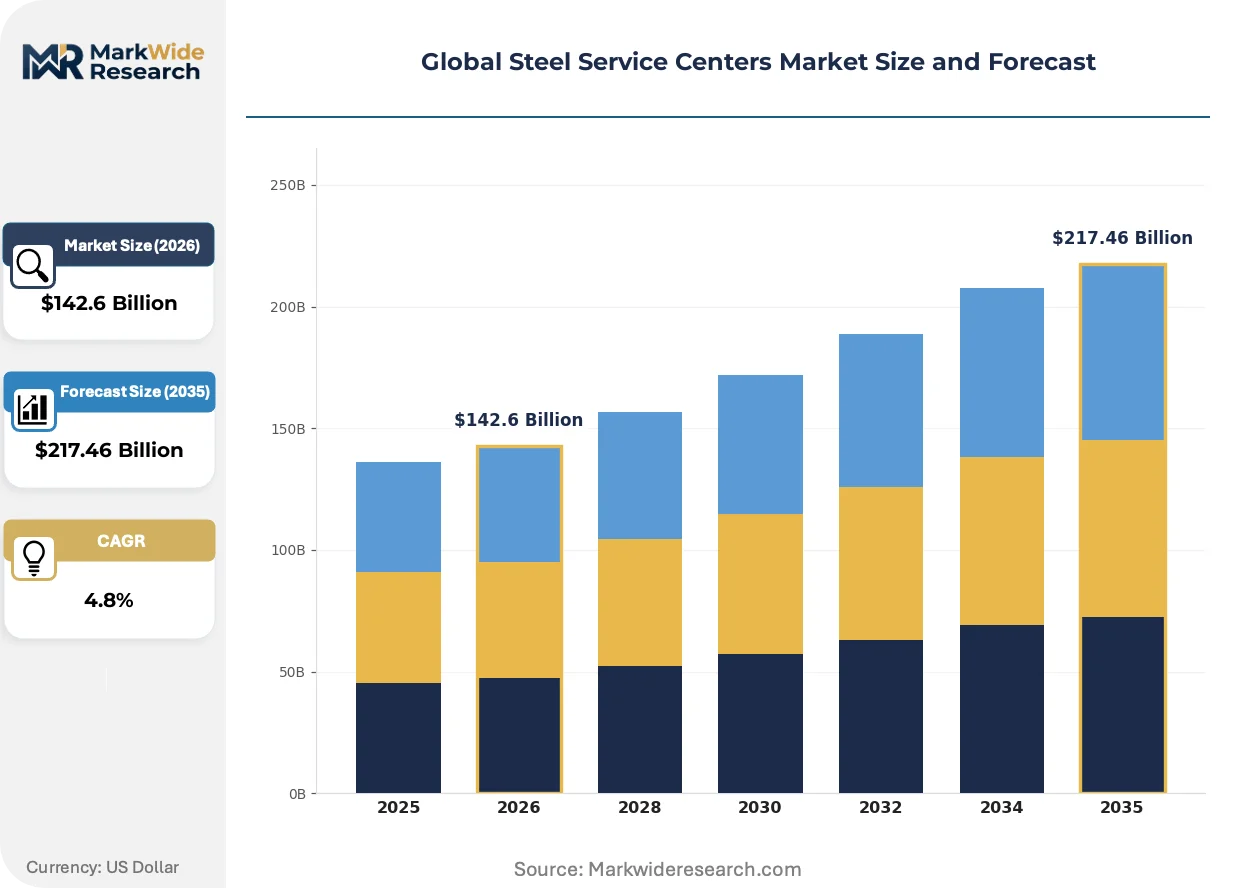
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $217.46 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cut-to-Length, Slitting, Blanking, Shearing, Leveling, Edge Conditioning Application: Construction, Shipbuilding, Heavy Machinery, Electrical Appliances, Renewable Energy, Transportation Equipment Technology: Automatic Coil Processing, Thermal Cutting, Laser Cutting, Plasma Cutting, Robotic Handling, Hydraulic Pressing End User: Fabricators, Metal Distributors, Tier-1 Suppliers, OEMs, Aftermarket Providers, Industrial Workshops |
| Companies Covered | Nippon Steel Corporation, Ryerson Holding Corporation, Reliance Steel & Aluminum Co., Samuel, Son & Co., Limited, Kloeckner Metals Corporation, ArcelorMittal S.A., Tata Steel Limited, Steel Dynamics, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steel Service Centers Market Shifts & Advancements
Automation is collapsing traditional batch-processing economics while regulatory carbon-accounting mandates reconfigure supplier qualification protocols across three continents.
Laser blanking systems equipped with real-time edge quality monitoring are collapsing the distinction between service center processing and OEM-ready blank delivery. Wind tower and agricultural equipment manufacturers now specify laser-cut plate directly from processors, bypassing in-house burning operations. This compression eliminates one handling step and 48-72 hours from typical mill-to-fabrication lead times.
The EU Carbon Border Adjustment Mechanism extends emissions documentation requirements to imported steel processed through third-country service centers. European-bound exports now require verified embedded carbon certificates from ore extraction through hot rolling. German automotive tier-1 suppliers have begun disqualifying processors unable to provide ISO 14064-compliant greenhouse gas inventories.
Automotive OEMs now mandate vendor-managed inventory programs with consumption-based billing rather than traditional purchase-order cycles. Tier-1 stamping plants receive daily milk-run deliveries of pre-blanked coils sequenced to press-line schedules. This shift is most visible in the US Southeast, where Hyundai, BMW, and Mercedes-Benz assembly plants anchor regional service center investment clusters.
Global Steel Service Centers Market Segmentation
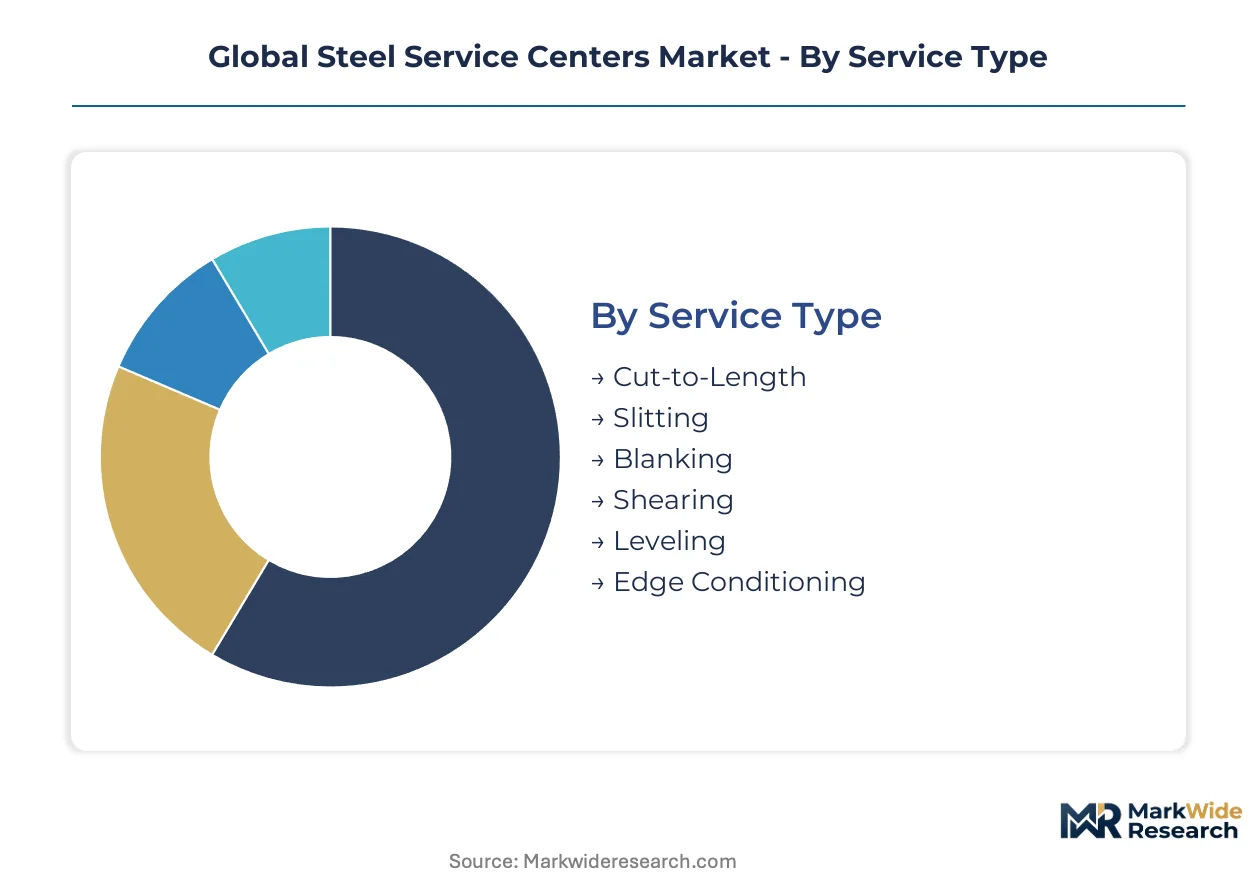
Steel service centers segment their operations across processing capabilities, end-use applications, and customer tiers. Each dimension carries distinct margin profiles, capital intensity requirements, and qualification barriers that reshape competitive positioning.
Service Type:
After-sales service intensity varies sharply across processing lines, with precision blanking and edge conditioning demanding ongoing calibration support while cut-to-length runs on minimal touch maintenance.
- Cut-to-Length:Transforms master coils into flat sheets meeting exact length specifications with tight thickness tolerances. Construction fabricators in India's western industrial corridor from Mumbai to Pune absorb the bulk of volume as infrastructure buildouts accelerate.
- Slitting:Longitudinal cutting of wide coils into multiple narrow strips with controlled edge quality and crown profiles. Heavy machinery OEMs and tier-1 automotive suppliers specify slit coils for precision stamping operations where burr height directly impacts die life.
- Blanking:Produces dimensionally precise flat blanks ready for direct press feeding. Aerospace and tier-1 supplier certifications create steep qualification barriers.
- Shearing:Straight-line cutting of sheet and plate stock with guillotine or rotary mechanisms. Metal distributors rely on shearing for quick-turn custom sizes.
- Leveling:Removes coil set and crossbow through roller leveling to achieve flatness specifications. Electrical appliance manufacturers demand leveled blanks for automated assembly lines.
- Edge Conditioning:Rounds or bevels edges to eliminate shear burrs and stress risers. Wind tower fabricators specify conditioned plate for welded seam integrity.
Cut-to-Length holds the largest share; momentum sits with Blanking as automotive OEM procurement shifts to pre-processed coil-ready formats.
Application:
Cost tier segmentation separates commodity construction plate from specification-critical renewable energy and transportation grades where testing documentation commands premium pricing.
- Construction:Structural steel framing, roofing, and cladding applications with standard ASTM tolerances. US Southeast manufacturing clusters near Hyundai and BMW assembly plants drive regional service center density.
- Shipbuilding:Thick-gauge plate with through-thickness toughness and ABS certification requirements. Korean and Japanese yards source through specialized processors with in-house ultrasonic testing.
- Heavy Machinery:Wear-resistant plate for mining equipment and agricultural implements. India's western industrial corridor concentrates demand for high-strength grades.
- Electrical Appliances:Cold-rolled and coated steels for motors, transformers, and white goods. Japanese METI energy-efficiency benchmarks shape material specifications.
- Renewable Energy:Wind tower sections and solar tracker structures requiring thick plate with Charpy impact certification. US IRA manufacturing credits stimulate domestic processing capacity.
- Transportation Equipment:High-strength and advanced high-strength steels for chassis, battery enclosures, and structural nodes. EV platform architectures specify tailored blanks with tailored mechanical properties.
Construction commands the greatest volume; Renewable Energy climbs the fastest as offshore wind tower specifications tighten.
Technology:
Customer type segmentation distinguishes high-volume automotive programs requiring automated coil-to-blank integration from job-shop fabricators accepting manual handling and longer lead times.
- Automatic Coil Processing:Integrated decoil, level, and cut lines with programmable length and stacker systems. Tier-1 stamping plants with vendor-managed inventory programs specify automatic lines for sequenced milk-run deliveries.
- Laser Cutting:Fiber laser systems with real-time edge quality monitoring and automated nesting software. Aerospace AMS specifications now accept laser-cut edges without secondary conditioning.
- Thermal Cutting:Oxy-fuel and plasma arc systems for thick plate division. Shipyards and heavy fabricators specify thermal-cut plate above 25mm thickness.
- Plasma Cutting:High-definition plasma with water injection for reduced heat-affected zones. Agricultural equipment manufacturers balance cut quality against cost.
- Robotic Handling:Automated coil loading, stacking, and packaging systems. Labor scarcity in North American manufacturing clusters accelerates deployment.
- Hydraulic Pressing:Precision blanking and forming operations with tonnage control. Tier-1 suppliers integrate hydraulic pressing with progressive die operations.
Automatic Coil Processing dominates installed base; Laser Cutting gains share fastest as edge quality specifications tighten across automotive and aerospace.
End User:
Supply concentration shapes this dimension, with OEMs and tier-1 suppliers consolidating procurement through qualified processor networks while fabricators and workshops fragment across regional service centers.
- Fabricators:Job shops and contract manufacturers converting processed steel into welded assemblies and finished components. India's Pune-Mumbai corridor hosts dense fabricator clusters serving automotive and machinery OEMs.
- Metal Distributors:Secondary wholesalers stocking standard sizes for quick-turn construction and maintenance demand. Inventory velocity determines margin sustainability.
- Tier-1 Suppliers:Stamping and sub-assembly houses with direct OEM contracts and stringent quality systems. AS9100 and IATF 16949 certifications create entry barriers.
- OEMs:Original equipment manufacturers with vendor-managed inventory and consumption-based billing. US Southeast automotive plants anchor regional processing investment.
- Aftermarket Providers:Replacement part fabricators and service centers with sporadic, specification-matched orders. Long tail demand with higher per-pound margins.
- Industrial Workshops:Maintenance and repair operations with unpredictable, small-lot requirements. Digital coil tracking platforms reduce search costs for odd sizes.
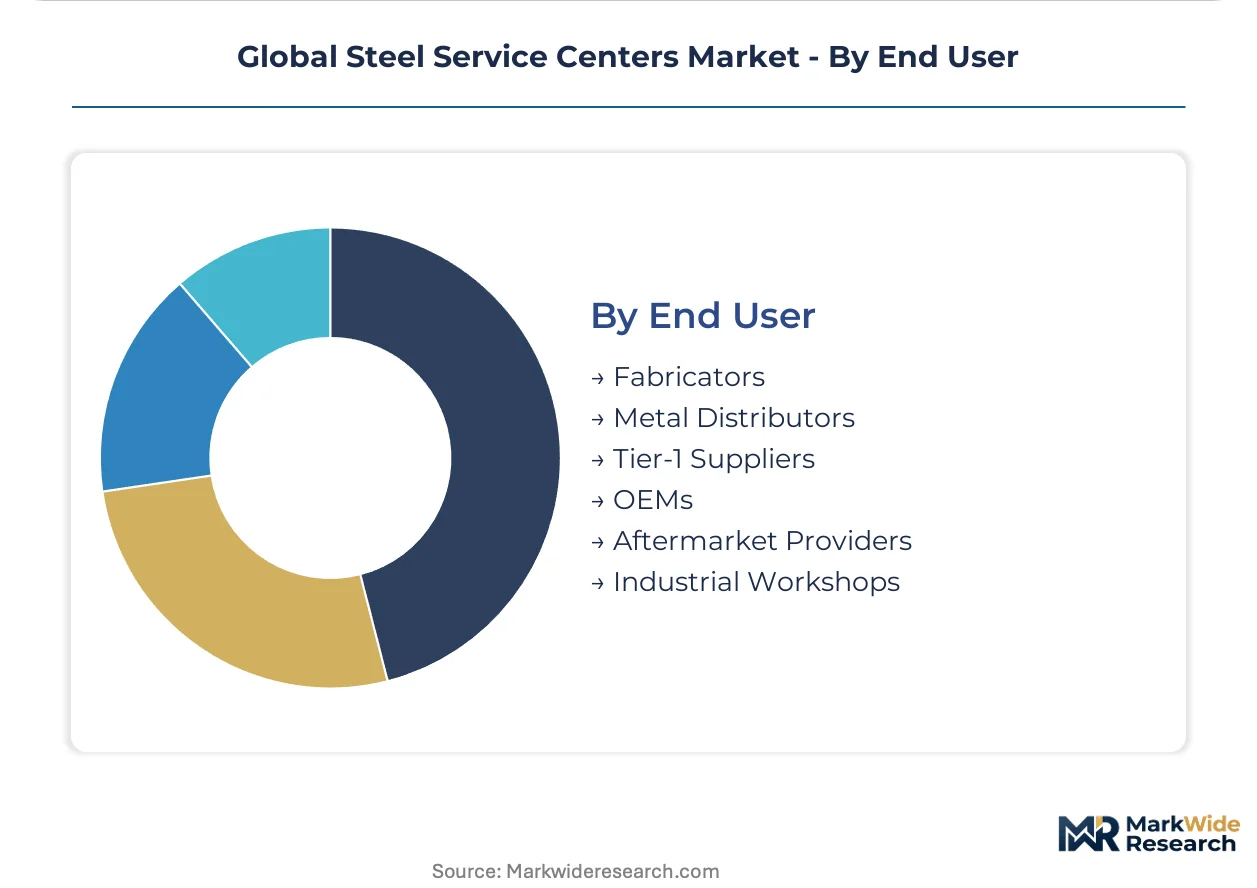
Fabricators represent the broadest end-user base; Tier-1 Suppliers and OEMs concentrate procurement fastest through qualified processor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian service centers supply precision-slit coils to German automotive tier-1 suppliers facing EU Carbon Border Adjustment Mechanism documentation requirements. This trade corridor illustrates how carbon-accounting mandates reshape procurement geography.
United States
Domestic content bonuses under the Inflation Reduction Act stimulate greenfield processing capacity near solar tracker assembly plants. The EPA enforces emissions reporting under the Greenhouse Gas Reporting Program for facilities above thermal input thresholds. Regional investment clusters concentrate in the Southeast near Hyundai, BMW, and Mercedes-Benz assembly operations.
Germany
Automotive tier-1 suppliers demand ISO 14064-compliant greenhouse gas inventories from imported steel processors. The EU Carbon Border Adjustment Mechanism extends emissions documentation to third-country service centers supplying European-bound exports. Industrial demand concentrates in the Ruhr industrial corridor and Baden-Württemberg precision manufacturing zones.
India
Infrastructure buildouts accelerate consumption of cut-to-length flat sheets across construction fabricators. The Bureau of Indian Standards shapes material certification protocols for structural steel applications. The western industrial corridor stretching from Mumbai to Pune hosts dense automotive and machinery OEM supplier networks.
Japan
Electrical appliance manufacturers specify leveled blanks for automated assembly lines with stringent flatness tolerances. METI administers energy-efficiency benchmarks under the Top Runner program that influence domestic processing center equipment upgrade cycles. Demand concentrates in the Chubu region around Nagoya manufacturing clusters.
China
Integrated steel mills control two-thirds of global hot-rolled coil capacity, creating allocation leverage over independent service centers. The Ministry of Ecology and Environment implements dual carbon goals that pressure mills and processors to document emissions. Yangtze River Delta fabricators supply precision components to renewable energy equipment manufacturers.
Global Steel Service Centers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidation pressure intensifies as carbon-accounting compliance costs favor scaled operators with embedded emissions tracking infrastructure. Three archetypes dominate: integrated mill-processor hybrids with captive upstream supply, decentralized branch-network distributors with same-day fulfillment capabilities, and precision-processing specialists with aerospace and automotive certifications. M&A activity targets regional processors with established OEM qualification relationships, while technology licensing agreements accelerate laser-blanking and automated coil-handling deployment.
Within the integrated hybrid archetype, Tata Steel Limited and ArcelorMittal S.A. exemplify upstream-downstream coordination through captive melt capacity and precision slitting operations. Reliance Steel & Aluminum Co. occupies a position among North American branch-network distributors with decentralized fulfillment capabilities. Kloeckner Metals Corporation represents the cloud-connected platform tier linking distributed inventory to real-time customer visibility. Nippon Steel Corporation anchors the Asia-Pacific precision-processing segment with established automotive and electrical steel certifications.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Ryerson Holding Corporation |
| Reliance Steel & Aluminum Co. |
| Samuel, Son & Co., Limited |
| Kloeckner Metals Corporation |
| ArcelorMittal S.A. |
| Tata Steel Limited |
| Steel Dynamics |
| Thyssenkrupp AG |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam container freight corridor transmits Turkish scrap export volatility directly into European service center coil premiums, amplifying price spreads between integrated mill-processor hybrids and independent distributors lacking long-term offtake anchors.
Pricing Analysis
Cost-plus contracts indexed to Platts hot-rolled coil assessments dominate procurement between mills and service centers, with quarterly adjustments passing through ferrous scrap and natural gas input swings. Pricing stratifies across premium, standard, and economy tiers based on ASTM thickness tolerance bands and IATF 16949 certification status. Cost compression in commodity cut-to-length runs through aggressive Turkish scrap competition, while margins hold firmer in aerospace-qualified blanking where AS9100 documentation creates supply scarcity. Tier-1 automotive stampers exhibit lowest price sensitivity given vendor-managed inventory sequencing requirements; metal distributors and job-shop fabricators in India's western corridor negotiate hardest on per-pound differentials.
Supply Chain Analysis
Upstream hot-rolled coil supply concentrates in China, India, and Japan, where integrated mills control two-thirds of global capacity and ration allocations to independent processors during tightness. Service center operations rest on ferrous scrap, natural gas for annealing, and alloy additives for high-strength grades. Single-source vulnerability runs through Yangtze River Delta mill clusters exposed to MEE emissions enforcement and power rationing. Distribution runs through decentralized branch networks with same-day fulfillment to automotive clusters, co-located processing near renewable energy fabrication sites, and regional stocking points for construction fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Steel Service Centers Market sits in early-cycle recovery as EV platform tooling investments and US IRA manufacturing credits restock fabrication demand after destocking headwinds.
For Market Incumbents: Pre-empt aluminum substitution in battery enclosure applications by deepening high-strength steel blanking capabilities and securing automotive OEM qualification for next-generation chassis architectures. Defend margin position through backward integration into precision slitting equipment and embedded emissions tracking infrastructure that satisfies EU Carbon Border Adjustment Mechanism documentation requirements for European-bound exports.
For New Entrants and Emerging Players: Build out laser-blanking capacity in the US Southeast near Hyundai and BMW assembly plants, where vendor-managed inventory programs concentrate procurement through qualified processor networks with IATF 16949 certification. Target renewable energy fabrication white space in offshore wind tower plate with through-thickness toughness certification, leveraging US IRA domestic content bonuses to offset greenfield capital requirements against established construction-grade competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-processing specialists with aerospace and automotive certifications over commodity distributors exposed to scrap price volatility. The five-to-ten-year viability window rewards processors with cloud-connected inventory platforms and embedded carbon-accounting infrastructure. Watch Turkish scrap export demand and container shipping rates as lead indicators of margin compression cycles that trigger consolidation opportunities among undercapitalized regional operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Slitting | Captures margin pools from automotive OEM procurement of tailored high-strength steel blanks. |
| Embedded Emissions Tracking Deployment | Creates competitive moats against EU Carbon Border Adjustment Mechanism disqualification risks. |
| Laser-Blanking Capacity Expansion | Collapses setup times for small-lot aerospace orders meeting AMS edge quality specifications. |
| Co-location with Renewable Energy Assembly | Reduces logistics costs for solar tracker and wind tower manufacturers under US IRA credits. |
| Cloud-Connected Inventory Platform | Links customers to real-time stock levels across distributed branch networks for same-day fulfillment. |
Research Methodology
A spread of perspectives from service center operations managers, automotive tier-1 procurement directors, mill scheduling coordinators, and renewable energy fabrication engineers converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, SEC 10-K filings, and steel industry association production statistics. Bottom-up coil processing capacity estimates and top-down end-use consumption models were triangulated against Platts price assessments and EPA Greenhouse Gas Reporting Program facility disclosures.
Demand-supply balance modeling across the projection horizon incorporated segmentation dimensions spanning service type, end-use application, processing technology, and customer tier. CAGRs were derived from rolling average growth rates applied to base-year market sizing, with cross-checks against automotive production forecasts, wind tower installation pipelines, and construction steel consumption indices. Industry-specific forecast inputs included EV platform architecture shifts, EU Carbon Border Adjustment Mechanism implementation timelines, and METI Top Runner equipment upgrade cycles.
Stress conditions across Turkish scrap export demand, container shipping rate spikes, and integrated mill allocation rationing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and technology adoption curves. Cross-checking against IHS Markit steel consumption data and automotive registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
North America Gutter Guards Market