
 Turkey Ceramic Tiles Market | 2026-2036
Turkey Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Ceramic Tiles Market Analytics
Aftermarket specification consulting is tilting margin pools away from pure manufacturing volume toward technical advisory services. Kaleseramik leverages captive quarrying operations to control raw material costs across its Anatolian production base. VitrA sustains design-led positioning through its Istanbul-based R&D campus, which competes with Italian studios for hospitality-sector contracts. Graniser Seramik anchors export competitiveness via Izmir port logistics, giving it freight advantages into North African markets.
Ceramic tiles are thin, flat slabs formed from clay, silica, and fluxing agents, then fired at temperatures between 1,000°C and 1,400°C to achieve varying densities and water absorption rates; their primary purpose is to provide durable, hygienic, and aesthetically finished surfaces for floors and walls in built environments. Porcelain, fired at the highest temperatures with minimal water absorption, commands the strongest margin profile among material categories due to its suitability for high-traffic commercial installations. Floor tiles dominate volume throughput in the residential end user segment, while glazed tiles capture premium positioning through digital inkjet decoration that replicates natural stone and wood grain textures.
Turkiye's Ministry of Trade enforces origin certification requirements that shape export eligibility for ceramic tile shipments into EU customs territory, while BIS-equivalent Turkish Standards Institution (TSE) markings govern domestic product compliance for abrasion resistance and slip coefficients. The country's national environmental regulator mandates wastewater treatment and dust recovery systems at production facilities, raising capital barriers for smaller kilns. Stakeholders must monitor how Turkiye's EU candidacy alignment process affects harmonized technical standards for ceramic products destined for European markets.
Market Dynamics
Seismic building codes enforced by Turkiye's Ministry of Environment, Urbanization and Climate Change are compressing demand toward lighter porcelain cladding systems, while Marmara region logistics infrastructure concentrates supply-side power among producers with captive port access.
Growth Catalysts
- Istanbul-Ankara residential construction:Large-format porcelain absorption in high-rise developments is pulling volume through specialized distribution networks serving contractor-specifier relationships.
- EU candidacy alignment:Harmonized technical standards under Turkiye's EU accession process are unlocking customs territory eligibility for certified producers.
- Digital inkjet decoration:Advanced glazing technologies enabling natural stone replication are capturing premium positioning in hospitality-sector specifications.
Market Restraints
- Natural gas price volatility:Kiln firing energy costs constitute a structural input burden that smaller producers cannot hedge through long-term supply contracts.
- Quarrying concentration in Anatolia:Captive raw material control by integrated manufacturers creates supply-side asymmetry for non-vertically positioned competitors.
- Water absorption technical ceiling:Porcelain's density requirements limit application flexibility in certain retrofit scenarios where substrate load capacity is constrained.
Strategic Opportunities
- North African export corridors:Izmir port freight advantages position Turkish producers to serve Moroccan and Algerian construction growth with competitive landed costs.
- Technical advisory services:Aftermarket specification consulting represents margin pool expansion beyond pure manufacturing volume for design-capable firms.
- EU Green Deal alignment:Carbon border adjustment mechanism preparation creates first-mover advantage for producers investing in dust recovery and wastewater treatment systems.
Industry Challenges
- Seismic code compliance timeline:TSE certification processes for slip coefficients and abrasion resistance create product launch delays for reformulation cycles.
- Kiln capex intensity:Continuous roller kiln technology upgrades require capital deployment that fragments competitive position between modernized and legacy facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Ceramic Tiles Market |
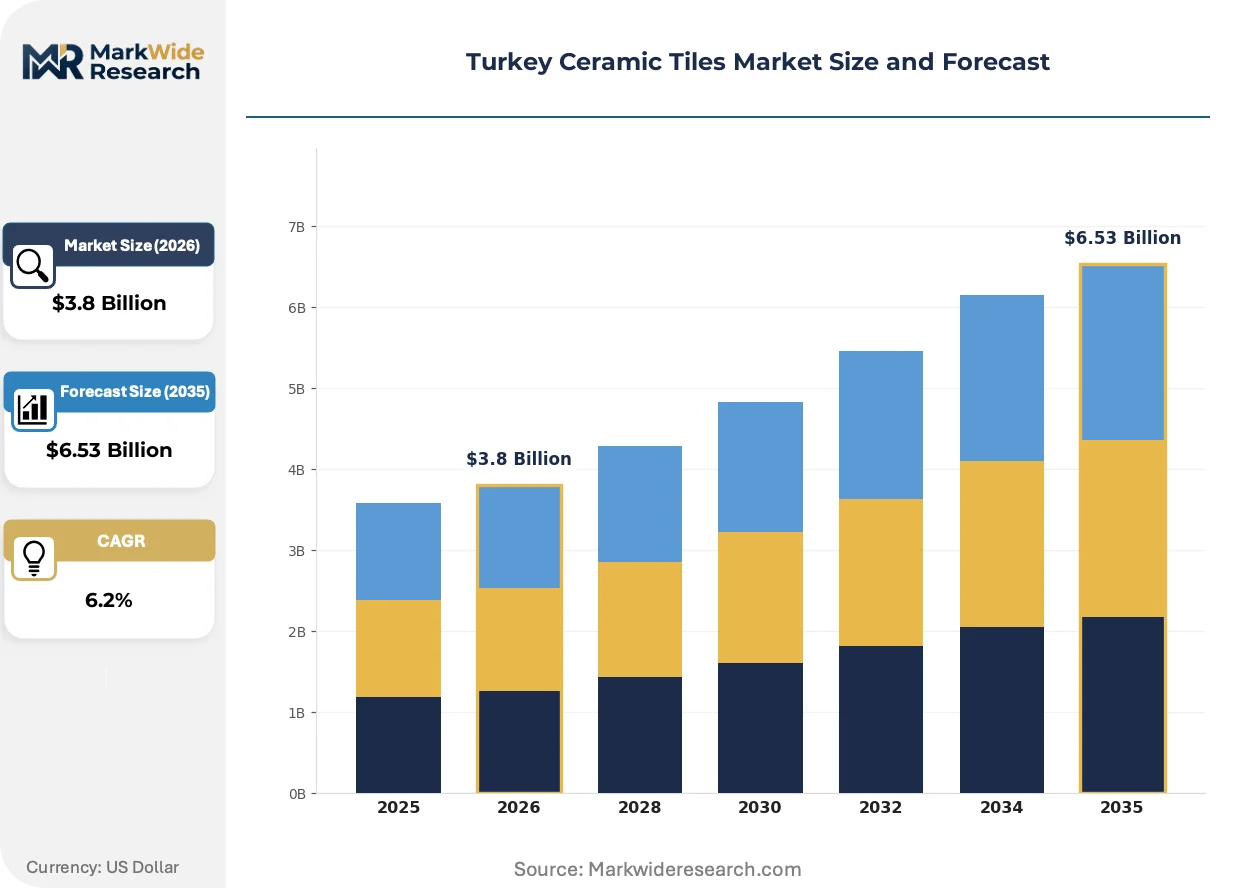
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Tiles, Wall Tiles, Outdoor Tiles, Glazed Tiles Material: Ceramic, Porcelain, Stoneware, Terracotta End User: Residential, Commercial, Industrial, Institutional Design: Sleek, Rustic, Textured, Patterned |
| Companies Covered | Seramiksan, Yurtbay Seramik, Kaleseramik, Graniser Seramik, Turkish Ceramics, VitrA, Ege Seramik, Akgun Seramik, NG Kutahya Seramik, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Ceramic Tiles Market Evolving Landscape
Digital specification workflows and advanced surface engineering are compressing traditional design-to-installation cycles while elevating technical performance requirements across Turkish ceramic tile production.
Large-format thin porcelain slabs are virtualizing traditional thick-body tile specifications by delivering equivalent structural performance at reduced weight. Hospitality developers in Istanbul are specifying these systems for high-rise facade applications. The technology is virtualizing established supply relationships between quarried stone suppliers and project specifiers.
Turkiye's Ministry of Trade origin certification requirements are reshaping export eligibility protocols for EU-bound shipments. Industrial consequence includes documentation burden concentration among smaller exporters lacking dedicated compliance functions. Certified producers are responding by embedding customs specialists within sales organizations serving European markets.
Architects and interior designers are consolidating specification authority through direct manufacturer relationships that displace traditional distributor intermediaries. Contractor purchasing departments are accepting this channel shift where technical support and sample logistics are integrated. The pattern is most visible in Ankara's commercial development sector where design-build contracts predominate.
Turkey Ceramic Tiles Market Segmentation
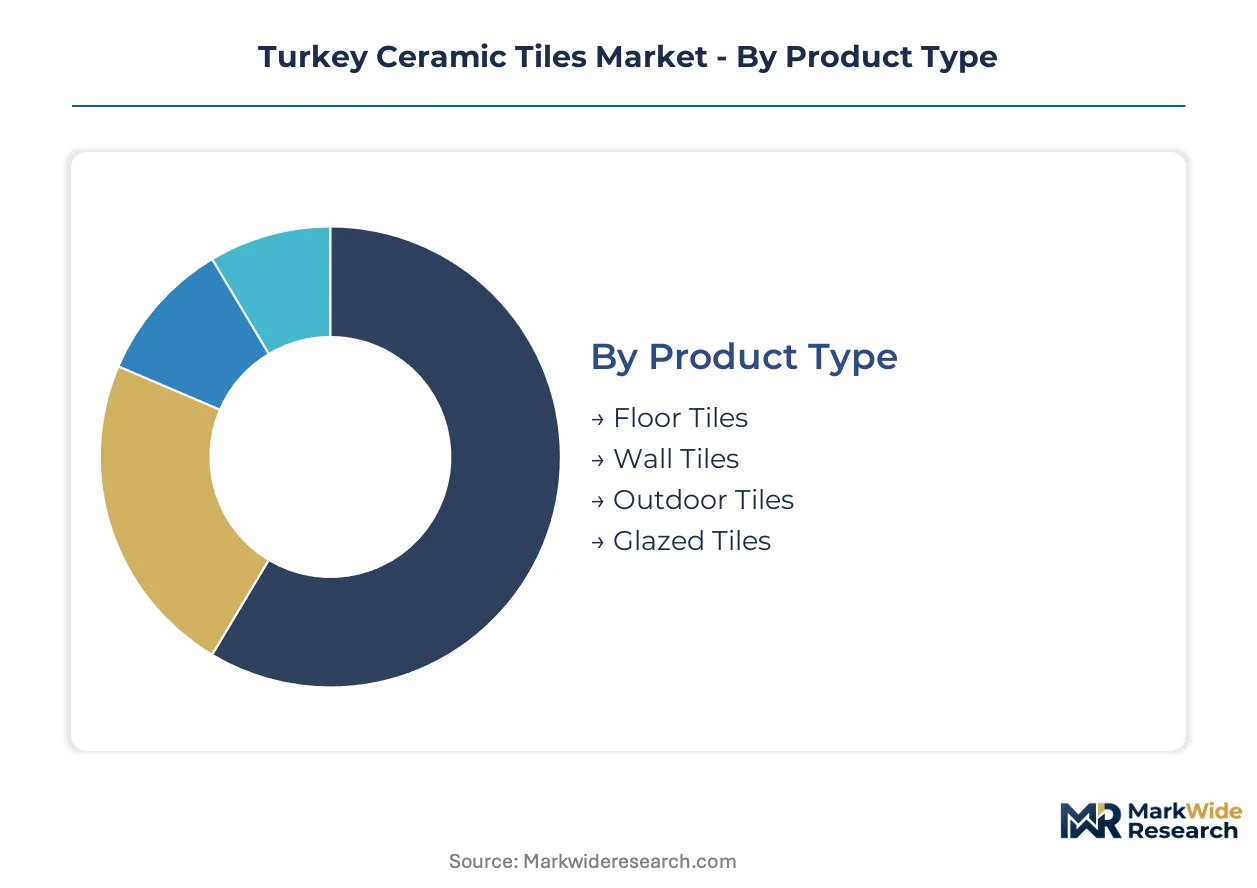
Segmentation in the Turkish ceramic tiles market reveals how seismic codes, export logistics, and specification authority are concentrating demand across distinct technical and aesthetic categories. Each dimension carries different margin profiles and capital requirements.
Product Type:
Mature formats dominate volume throughput while emerging specifications capture specification authority in high-rise developments.
- Floor Tiles:Thick-body formats fired at 1,000-1,200°C absorb mechanical load in residential high-rises across Istanbul's Esenyurt and Beylikdüzü districts. Large-format porcelain variants are displacing traditional 30x30cm specifications in contractor-direct procurement channels.
- Wall Tiles:Lower-density ceramic bodies with higher water absorption rates serve vertical cladding applications where substrate weight constraints apply. Glazed surface treatments with digital inkjet decoration command premium positioning in Ankara hospitality specifications.
- Outdoor Tiles:Frost-resistant porcelain pavers with textured slip-resistant surfaces serve terrace and plaza applications in Marmara region commercial developments.
- Glazed Tiles:Vitrified surface layers enable aesthetic replication of marble and wood grain through advanced printing technologies.
Floor tiles handle the majority of throughput; glazed tiles are expanding most quickly on share through hospitality-sector premium capture.
Material:
Cost tier stratification separates commodity ceramics from specification-grade porcelain with distinct kiln intensity and margin profiles.
- Porcelain:Fired above 1,200°C with water absorption below 0.5%, delivering structural density for high-traffic commercial installations. Turkiye's Ministry of Environment seismic codes favor its lighter cladding variants for high-rise facades in Istanbul.
- Ceramic:Standard earthenware bodies with 3-10% water absorption serve cost-sensitive residential flooring across Anatolian inland markets.
- Stoneware:Intermediate density fired at 1,150-1,250°C balances durability with moderate weight for institutional retrofit applications.
- Terracotta:Low-fired porous clay with distinctive reddish iron oxide coloring serves heritage restoration and rustic aesthetic specifications.
Porcelain commands the highest margin tier; ceramic maintains volume dominance in mass residential.
End User:
Customer type segmentation tracks how specification authority consolidates differently across project scale and procurement sophistication.
- Residential:Single-family and multi-unit housing developments in Istanbul and Ankara absorb standardized formats through distributor networks serving contractor relationships.
- Commercial:Office, retail, and hospitality developers in Istanbul's Levent and Maslak districts specify large-format thin porcelain through direct manufacturer relationships.
- Industrial:Manufacturing facilities and warehouses require abrasion-resistant heavy-duty tiles with chemical resistance certifications.
- Institutional:Schools, hospitals, and government buildings in Ankara prioritize slip coefficient compliance under TSE standards for public safety liability.
Residential channels move the highest unit volumes; commercial specifications are climbing the fastest as design-build contracts consolidate authority.
Design:
Aesthetic segmentation maps to specification channel sophistication and digital production capability requirements.
- Sleek:Minimalist large-format surfaces with rectified edges and polished finishes serve contemporary hospitality and corporate interiors in Istanbul.
- Rustic:Textured surfaces with deliberate irregularity replicate aged stone and terracotta for boutique hotel and restaurant specifications.
- Textured:Three-dimensional relief patterns and tactile surfaces enable slip resistance without compromising visual continuity.
- Patterned:Digital inkjet reproductions of geometric and floral motifs serve traditional aesthetic preferences in Middle East export markets.
Sleek designs anchor premium positioning; textured formats are gaining share fastest through seismic code alignment with lighter cladding systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Turkish sub-markets. Mass residential buyers in Anatolian inland provinces prioritize cost-per-square-meter metrics. Specifiers in Istanbul's high-rise commercial towers absorb premium porcelain pricing for seismic compliance and facade performance.
Marmara Region
Istanbul and Bursa absorb the highest porcelain volumes for high-rise residential cladding. Turkiye's Ministry of Environment enforces seismic codes that favor lighter porcelain systems over traditional thick-body ceramics. The Gebze-Dilovasi industrial corridor hosts integrated kilns serving both domestic projects and Izmir port export logistics.
Aegean Region
Izmir anchors export competitiveness through captive port access to North African markets. The Turkish Standards Institution certifies abrasion resistance and slip coefficients for shipments into EU customs territory. Menemen and Torbali production zones concentrate dust recovery and wastewater treatment investments ahead of EU Green Deal alignment.
Central Anatolia
Ankara's government and institutional construction drives demand for TSE-certified slip-resistant tiles in schools and hospitals. The capital's procurement departments prioritize public safety liability compliance over aesthetic premium capture. Konya's inland logistics raise landed costs for export-oriented producers versus coastal competitors.
Mediterranean Region
Antalya's hospitality development pipeline specifies large-format thin porcelain for resort and hotel interiors. Digital inkjet decoration capabilities enable natural stone replication for international tourism-sector contracts. Alanya and Mersin sub-markets balance seasonal construction cycles with year-round ceramic distribution throughput.
Black Sea Region
Trabzon and Samsun serve smaller-scale residential renovation demand with cost-sensitive ceramic formats. Humidity exposure in coastal climates limits porcelain absorption rates versus inland specifications. Regional distributors maintain inventory positions for quick-turn contractor relationships without direct manufacturer integration.
Turkey Ceramic Tiles Market Competitive Landscape
Capability concentration sits with design-led specialists; scale advantage sits with quarry-integrated producers. The vendor base splits between vertically positioned manufacturers controlling Anatolian raw material access and design-capable firms competing for hospitality-sector specifications. Three archetypes dominate: quarry-captive cost leaders, R&D-intensive design houses, and export-logistics specialists. Competitive moves center on kiln technology upgrades and specification consulting service expansion.
Among quarry-integrated producers, Kaleseramik exemplifies backward integration into captive raw material control. VitrA occupies a position within the design-led tier, competing through Istanbul-based aesthetic development for hospitality contracts. Graniser Seramik anchors the export-logistics archetype through Izmir port freight advantages into North African markets.
| Leading Market Players |
|---|
| Seramiksan |
| Yurtbay Seramik |
| Kaleseramik |
| Graniser Seramik |
| Turkish Ceramics |
| VitrA |
| Ege Seramik |
| Akgun Seramik |
| NG Kutahya Seramik |
| Others |
Value Network & Pricing Analysis
Natural gas price volatility in kiln firing operations determines both the spread between premium porcelain and commodity ceramic tiers and the geographic shape of production concentration around coastal logistics corridors. Buyers absorbing energy cost pass-throughs cluster in Istanbul's high-rise commercial segment, while Anatolian inland residential markets enforce rigid cost-per-square-meter ceilings that compress margins for non-integrated producers.
Pricing Analysis
Aftermarket specification consulting and technical advisory services drive lifetime value capture beyond unit transaction margins. Three-tier pricing structure across premium large-format porcelain, standard glazed ceramic, and economy thick-body floor tiles separates seismic-compliant cladding from basic residential coverage. Cost compression in the economy tier intensifies as captive quarrying operations at Kaleseramik and similar integrated players offset energy volatility through upstream material control. Mass residential buyers in Central Anatolia exhibit highest price sensitivity, while Istanbul hospitality specifiers absorb premium positioning for design-led digital inkjet finishes.
Supply Chain Analysis
Anatolian clay deposits and silica quarries feed production networks concentrated in Turkiye's Marmara and Aegean coastal zones. Raw material inputs draw from captive mining operations, imported fluxing agents, and natural gas supply contracts tied to volatile spot markets. Single-source vulnerability in energy procurement fragments competitive position between producers with long-term supply hedges and exposed smaller kilns. Distribution runs through specialized contractor-direct channels in Istanbul and Ankara, with Izmir port logistics anchoring North African export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of seismic engineering expertise combined with EU Green Deal compliance capability is concentrating margin capture among producers with integrated technical advisory functions. Firms lacking both captive raw material access and specification consulting infrastructure face structural displacement.
For Market Incumbents: Entrench position by deepening captive quarrying control across Anatolian clay deposits and embedding customs specialists within European-facing sales organizations to navigate TSE certification timelines. Kiln technology upgrades to continuous roller systems represent the critical capacity lever against legacy facility fragmentation. Threat of margin compression from natural gas volatility demands energy contract restructuring before pricing power erodes further. For New Entrants and Emerging Players: Mid-market institutional retrofit applications in Ankara's hospital and school construction pipeline represent the most penetrable entry point, as TSE slip coefficient compliance requirements create specification barriers that favor technical capability over scale. North African export markets via Izmir freight advantages offer secondary white-space with lower capital intensity than domestic premium positioning. Go-to-market execution should anchor on specification consulting partnerships with design-build contractors rather than distributor channel displacement. For Investors and Strategic Acquirers: Turkiye's EU candidacy alignment process and impending carbon border adjustment mechanism implementation reshape the acquisition landscape toward producers with dust recovery and wastewater treatment infrastructure already deployed. Long-term viability over the next decade hinges on regulatory compliance capability rather than pure manufacturing scale. Acquisition target archetype: design-capable mid-tier firms with Izmir port access and incomplete vertical integration. Signal to watch: TSE certification backlog delays as indicator of compliance infrastructure scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Roller Kiln Upgrade | Energy efficiency gains at Marmara production facilities compress firing cost differentials against legacy competitors. |
| Captive Quarrying Expansion | Backward integration into Anatolian clay deposits insulates margin profiles from raw material spot volatility. |
| EU Green Deal Alignment Investment | Dust recovery and wastewater treatment systems position certified producers for carbon border adjustment mechanism eligibility. |
| Specification Consulting Service Launch | Technical advisory functions capture margin pools shifting from pure manufacturing volume toward design-build contractor relationships. |
| Izmir Port Logistics Optimization | Freight cost advantages into Algerian and Moroccan construction markets sustain export competitiveness against Italian and Spanish rivals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across plant managers at integrated kilns, procurement leads at Istanbul-based hospitality developers, distribution channel partners serving Ankara contractor networks, and technical R&D directors overseeing digital inkjet decoration lines. Secondary validation drew from Turkish Standards Institution certification records, Turkiye Ministry of Trade export documentation, customs and trade data through the Aegean Exporters Association, and SEC filings of publicly listed building materials conglomerates with ceramic tile operations. Bottom-up volume modeling across product type and material segments was triangulated against top-down macro construction spending data.
Calibration against historical CAGRs from adjacent building materials categories anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, material density tier, end user procurement sophistication, and regional logistics access. Growth rates derived from construction permit issuance trends in Istanbul and Ankara, EU customs territory eligibility progression under harmonized technical standards, and kiln capacity utilization rates reported through industry associations.
Stress conditions across natural gas price bands, seismic code enforcement timelines, and EU accession process velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding construction permit continuity and export corridor stability that regulatory or macroeconomic shocks could revise. Cross-checking against Turkish Statistical Institute building completion data and Eurostat construction production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Acoustic Doors Market