
 Global Iron and Steel Casting Market | 2026-2036
Global Iron and Steel Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Iron and Steel Casting Market Foresight
Modular component bundling is repositioning procurement patterns for heavy engineering buyers who now specify pre-machined casting kits rather than raw pourings. ArcelorMittal leverages its integrated melt-to-finish footprint to supply these configured assemblies across European automotive and energy accounts. POSCO anchors its competitive stance through captive raw material access at its Pohang complex. Precision Castparts Corp. specializes in aerospace-grade superalloy castings that command premium positioning in turbine engine supply chains.
Iron and steel casting encompasses the pouring of molten ferrous alloys into moulds to produce components typically weighing from grams to over 200 tonnes, with carbon content ranging from 2% in gray iron to below 0.5% in wrought-grade steel castings, serving as the structural backbone for machinery that cannot be formed by forging or fabrication. Ductile iron castings now lead product type volumes due to their superior tensile strength and elongation properties replacing traditional gray iron in critical stress applications. Sand casting dominates method selection for heavy sections above 50 kilograms where tooling economy outweighs surface finish requirements, while investment casting captures margin pools in precision components below 5 kilograms for aerospace and medical tool manufacturing end user industries.
EPA emissions standards for metal casting facilities in the United States mandate maximum achievable control technology for hazardous air pollutants from melt operations, while REACH compliance in Europe restricts certain alloy additives in cast products destined for consumer appliance applications. China's MEE enforces dual carbon goals through provincial energy intensity caps that directly limit foundry operating hours during peak demand periods. Stakeholders must monitor how these diverging regulatory trajectories reshape locational competitiveness for new capacity investments and alloy formulation choices.
Market Dynamics
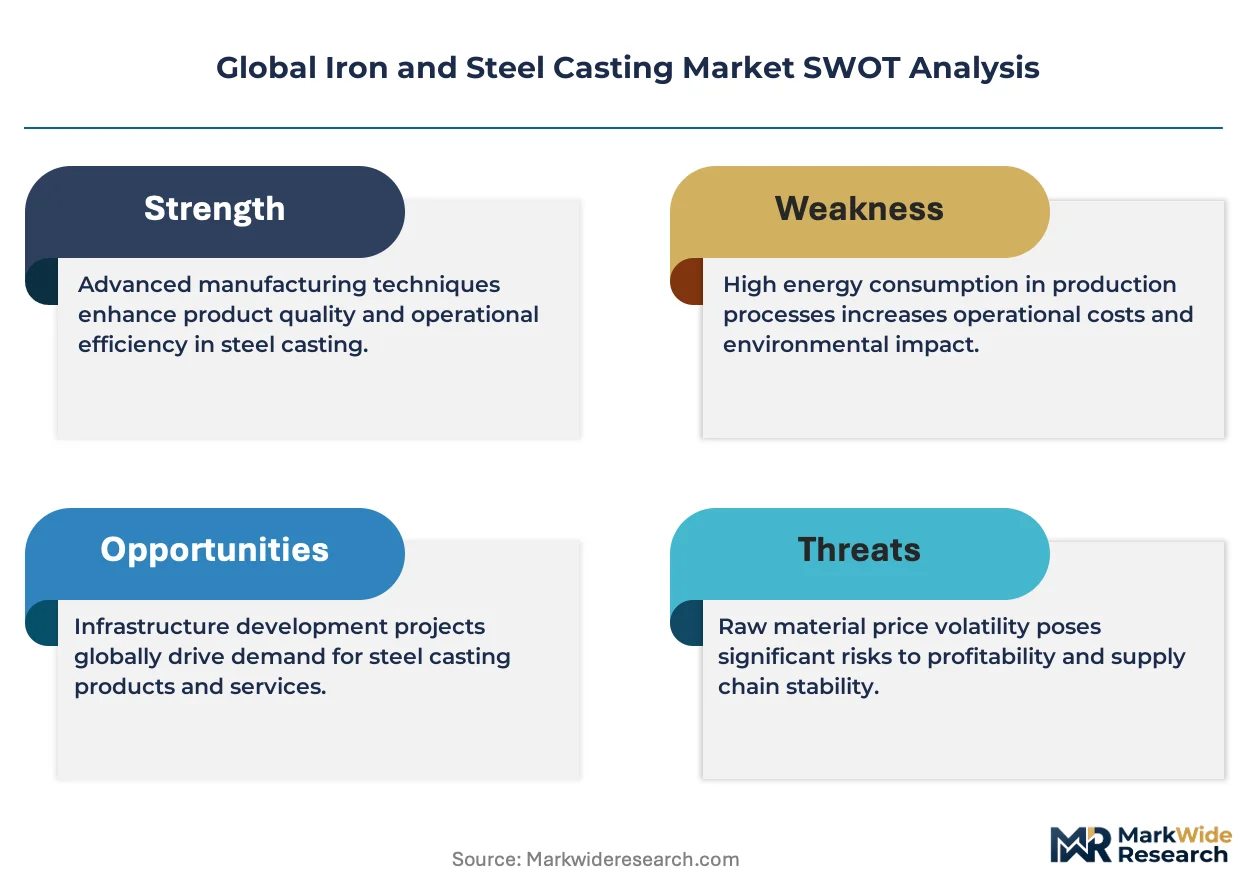
Foundry operators face mounting pressure from China's GB emissions standards, which are compressing operating windows for carbon-intensive melt shops while simultaneously creating competitive advantage for facilities with electric arc furnace flexibility and integrated pollution control systems.
Growth Catalysts
- Power generation expansion:Utilities in India and Southeast Asia are commissioning new baseload capacity requiring turbine housings, driving foundry orders for heavy-section castings above 50 tonnes.
- REACH compliance differentiation:European casters with certified low-lead alloy formulations capture appliance manufacturing contracts as REACH restricts certain additives in consumer-facing products.
- Ductile iron substitution:Automotive chassis manufacturers specify nodular iron grades replacing gray iron in stress-critical suspension components due to superior elongation properties.
Market Restraints
- Scrap price volatility:Ferrous scrap constitutes 60-80% of melt shop input costs, with Turkish and Vietnamese export demand creating price spikes that compress foundry margins unpredictably.
- MEE operating hour caps:China's Ministry of Ecology and Environment enforces provincial energy intensity limits that restrict foundry runtime during peak grid demand periods.
- Investment casting cost floor:Ceramic shell materials and precision wax pattern tooling create minimum economic order quantities that exclude small-batch medical device producers.
Strategic Opportunities
- Western India industrial corridor:Demand concentrates from Pune to Ahmedabad for machined casting kits serving agricultural machinery and construction equipment OEMs.
- IRA domestic content credits:US wind turbine manufacturers qualify for Inflation Reduction Act incentives by sourcing nacelle housings from domestic foundries with verified melt-to-finish traceability.
- Digital twin convergence:Foundries integrating computational fluid dynamics with thermal stress simulation reduce prototype iterations and accelerate customer qualification timelines.
Industry Challenges
- Patternmaking skill erosion:North American and European foundries report acute shortages of journeyman patternmakers capable of hand-sculpting complex core boxes for prototype development.
- Multi-standard certification burden:Suppliers to aerospace and medical verticals must simultaneously maintain NADCAP, ISO 9001, and customer-specific process approvals with diverging audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Iron and Steel Casting Market |
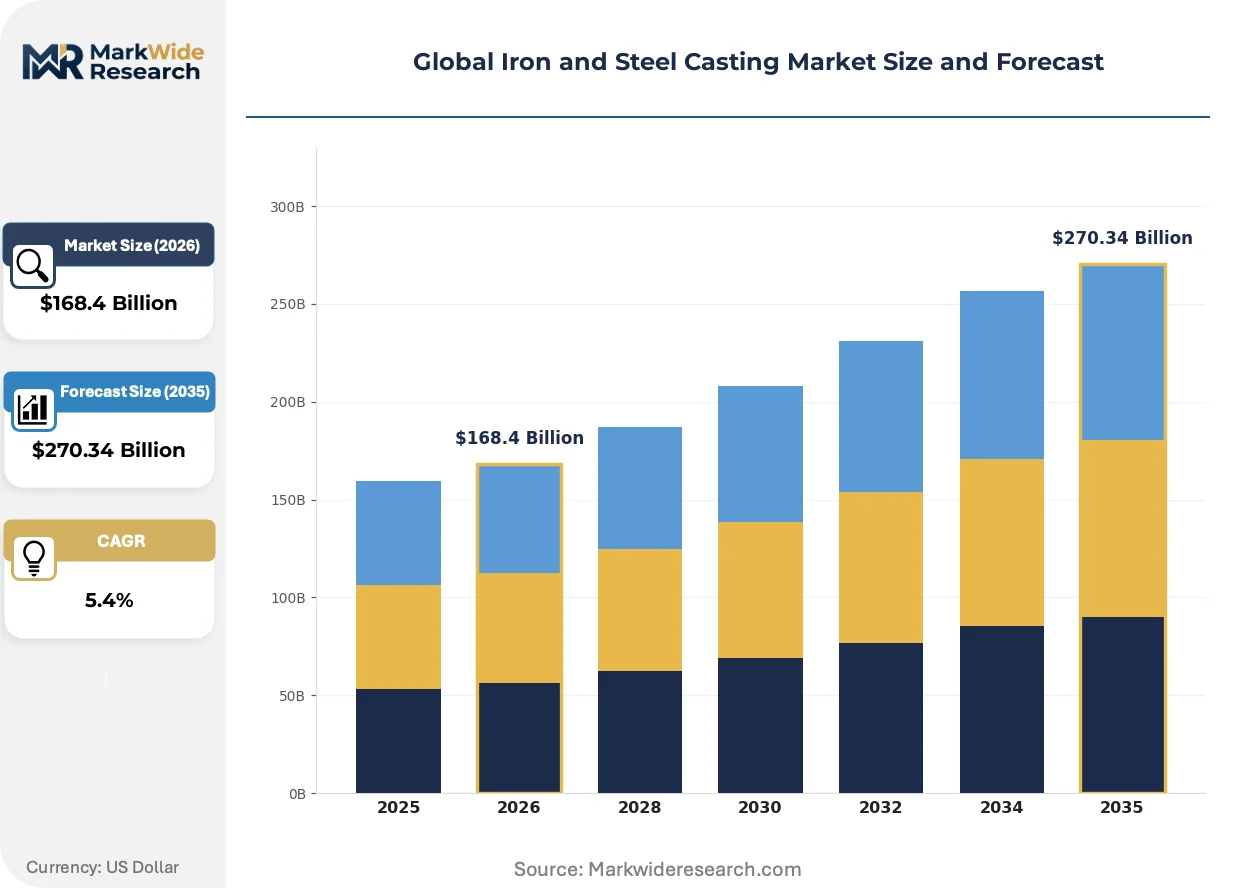
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $270.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gray Iron, Ductile Iron, Carbon Steel, Alloy Steel, Stainless Steel, Malleable Iron Casting Method: Sand Casting, Shell Moulding, Investment Casting, Centrifugal Casting, Die Casting, Lost Foam Application: Machinery Components, Power Generation, Construction Equipment, Mining Equipment, Maritime Equipments, Agricultural Implements End User Industry: Heavy Engineering, Consumer Appliances, Transportation Equipment, Oilfield Equipment, Tool Manufacturing, Material Handling |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, POSCO, Nucor Corporation, Thyssenkrupp AG, Doosan Corporation, Precision Castparts Corp., Georg Fischer Ltd, Kobe Steel, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Iron and Steel Casting Market Shifts & Advancements
Additive manufacturing is penetrating sand casting workflows, with printed mold cores eliminating hard tooling for prototypes and low-volume production runs. This convergence of digital fabrication with traditional pour technology is compressing lead times and reshaping competitive economics across multiple end-use verticals.
3D-printed sand cores and molds are modularizing pattern shop operations by enabling geometric complexity impossible with conventional core assembly. Aerospace turbine blade casters at Precision Castparts and medical implant foundries adopt printed refractory molds for cooling channel integration. The technology is modularizing the traditional separation between design engineering and manufacturing engineering, allowing iteration cycles measured in days rather than weeks.
EPA maximum achievable control technology mandates for hazardous air pollutants from iron and steel melting operations are forcing capital deployment toward baghouse upgrades and secondary emissions capture. US foundries in Indiana and Ohio report seven-figure compliance investments with payback periods extending beyond typical equipment financing terms. Gray iron engine block producers serving automotive accounts face the steepest cost absorption pressure as OEMs resist price pass-through for environmental compliance.
Heavy engineering buyers now specify pre-machined casting kits rather than raw pourings, transferring dimensional risk and finish machining investment upstream to foundries. European energy sector procurement teams at Siemens Energy and GE Vernova require delivered-to-line configured assemblies with documented CMM inspection data. This specification shift is most visible in German and Austrian power generation supply chains, where integrated melt-to-finish suppliers capture multi-year frame contracts unavailable to raw casting merchants.
Global Iron and Steel Casting Market Segmentation
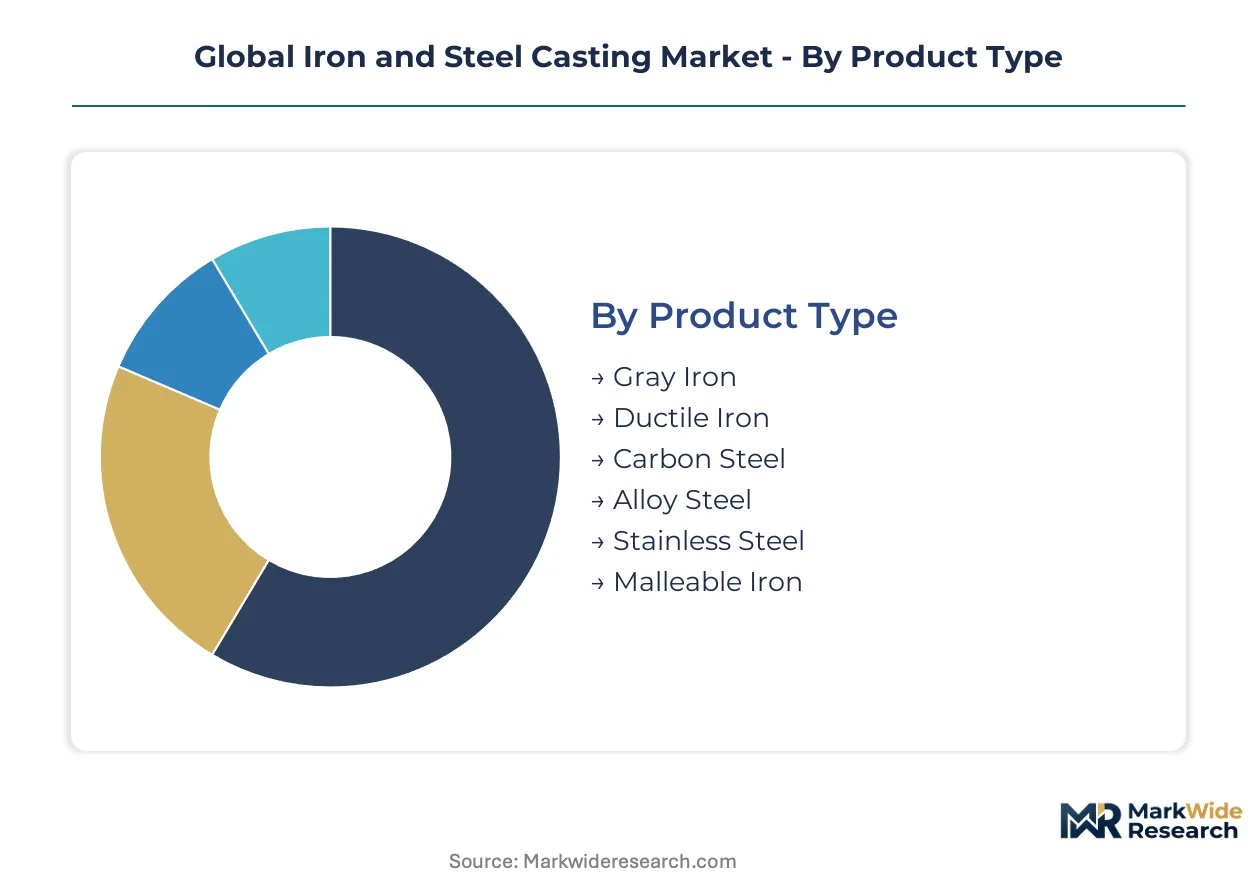
Segmentation in iron and steel casting reveals how material specifications, forming technologies, and end-use demands create distinct competitive arenas. Foundries specialize along these axes, with capability portfolios determining which customer verticals they can serve profitably.
Product Type:
Material chemistry and microstructure define performance ceilings for stress-bearing applications across industrial machinery and infrastructure equipment.
- Ductile Iron:Nodular graphite morphology delivers tensile strength above 400 MPa with 18% elongation, enabling substitution for forged steel in automotive suspension arms. Demand concentrates in India's western industrial corridor for tractor transmission housings as agricultural OEMs source locally machined kits.
- Gray Iron:Flake graphite structure provides excellent vibration damping and machinability at lower material cost, though with brittle fracture characteristics limiting dynamic load applications. German and Austrian power generation supply chains specify this grade for stationary turbine housings where thermal cycling resistance matters more than impact toughness.
- Carbon Steel:Weldable grades with carbon content below 0.3% serve structural castings for mining equipment frames requiring field repairability.
- Alloy Steel:Chromium-molybdenum formulations withstand abrasion in cement plant kiln tyres and ball mill liners.
- Stainless Steel:Corrosion-resistant grades meet FDA and EFSA requirements for food processing machinery exposed to caustic washdown cycles.
- Malleable Iron:Heat-treated white iron microstructures offer ductility in thin-section pipe fittings where gray iron would fracture.
Mature deployment sits with Gray Iron in established automotive engine blocks. Newer deployment is concentrated in Ductile Iron replacing forged components.
Casting Method:
Process selection trades tooling investment against surface finish precision and geometric complexity, with volume economics determining viable order quantities.
- Sand Casting:Clay-bonded silica molds accommodate single-piece castings exceeding 200 tonnes, making this the default for hydroelectric turbine runners and cement kiln support rollers. China's MEE operating hour caps disproportionately pressure sand foundries due to their energy-intensive mold drying and shakeout operations.
- Investment Casting:Ceramic shell molds built around wax patterns achieve surface finishes below 125 microns Ra and dimensional tolerances of ±0.5%, capturing aerospace turbine blade and medical implant applications where NADCAP certification gates supplier qualification. REACH compliance on alloy additives restricts certain nickel superalloy formulations for European medical device accounts.
- Shell Moulding:Phenolic resin-coated sand enables medium-volume production of gear housings with better surface quality than green sand.
- Centrifugal Casting:Rotational force distributes metal against mold walls for axisymmetric components like pipe and cylinder liners.
- Die Casting:Hardened steel tooling permits high-pressure injection for thin-walled automotive brackets in zinc and aluminum alloys.
- Lost Foam:Vaporized polystyrene patterns eliminate parting lines and core assembly for complex engine block geometries.
Volume concentration favors Sand Casting for heavy industrial castings. Margin capture is climbing fastest in Investment Casting for aerospace and medical verticals.
Application:
End-use specifications cascade through material grade, inspection protocol, and delivery format requirements, fragmenting foundry addressable markets.
- Power Generation:Steam and gas turbine housings above 50 tonnes require ultrasonic testing to ASTM A609 standards, with Siemens Energy and GE Vernova procurement teams mandating delivered-to-line machined kits with CMM inspection data. IRA domestic content credits are reshaping US sourcing patterns for wind turbine nacelle housings.
- Machinery Components:Pump bodies, valve housings, and compressor frames constitute the volume base for general-purpose foundries serving job-shop customers.
- Construction Equipment:Excavator track frames and crane counterweights demand impact-resistant grades for quarry and demolition environments.
- Mining Equipment:Abrasion-resistant alloy steel castings for mill liners and crusher mantles face extreme wear conditions.
- Maritime Equipments:Classification society rules from Lloyd's Register and DNV govern steel grades for propellers and rudder stocks.
- Agricultural Implements:India's western corridor from Pune to Ahmedabad concentrates demand for tractor transmission housings and combine harvester components.
Specification intensity peaks in Power Generation with multi-standard certification burdens. Procurement flexibility is greatest in Machinery Components.
End User Industry:
Customer verticals impose distinct quality systems, volume profiles, and geographic sourcing mandates that structure foundry competitive positioning.
- Heavy Engineering:Custom specifications for single-source critical components support long-term frame contracts with integrated melt-to-finish suppliers. ArcelorMittal leverages captive raw material access to supply configured assemblies across European energy accounts.
- Transportation Equipment:Automotive OEMs specify nodular iron grades for chassis components, with Tier 1 suppliers maintaining IATF 16949 certification.
- Consumer Appliances:REACH restrictions on lead and cadmium additives in cast products destined for European markets create compliance differentiation for certified low-lead alloy formulators.
- Oilfield Equipment:Sour service requirements per NACE MR0175 govern alloy selection for wellhead components.
- Tool Manufacturing:Investment castings for cutting tool holders and die components require precise heat treatment response.
- Material Handling:Forklift mast channels and crane wheels balance wear resistance against weldability for field repair.
Contract duration extends longest in Heavy Engineering with multi-year frame agreements. Order fragmentation is most pronounced in Consumer Appliances with seasonal demand spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across Gujarat, Maharashtra, and Tamil Nadu drive foundry concentration through tax holidays and duty exemptions on imported melting equipment. India's western industrial corridor anchors agricultural machinery casting demand. Chinese coastal provinces face MEE operating hour caps that compress carbon-intensive melt shop runtime.
China
GB emissions standards tighten compliance requirements for sand foundries in Jiangsu and Shandong provinces. MEE provincial energy intensity caps restrict operating hours during peak grid demand periods. The Yangtze River Delta concentrates investment casting capacity serving medical device exporters facing REACH alloy restrictions.
India
Western industrial corridor demand from Pune to Ahmedabad concentrates procurement for machined casting kits serving tractor OEMs. PLI scheme incentives for agricultural machinery production amplify foundry orders for transmission housings. Coimbatore and Rajkot cluster job-shop capacity for pump and valve castings.
Germany
Siemens Energy and GE Vernova procurement teams mandate delivered-to-line machined turbine housings with CMM inspection data. REACH compliance on lead additives creates differentiation for certified low-lead alloy formulators serving appliance manufacturers. Bavarian foundries anchor European power generation supply chains.
United States
IRA domestic content credits reshape sourcing for wind turbine nacelle housings requiring melt-to-finish traceability. EPA maximum achievable control technology mandates force capital deployment toward baghouse upgrades in Indiana and Ohio. Gray iron engine block producers face cost absorption pressure as automotive OEMs resist environmental compliance pass-through.
Japan
Automotive chassis manufacturers specify nodular iron grades replacing gray iron in suspension components. METI industrial decarbonization roadmaps pressure foundries toward electric arc furnace conversion. Nagoya and Osaka industrial zones concentrate precision casting for machine tool and construction equipment OEMs.
Global Iron and Steel Casting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The market structures around three archetypes: integrated steelmakers with captive foundry operations, independent job-shop foundries serving multiple verticals, and precision investment casters targeting aerospace and medical certification requirements. Consolidation pressure intensifies as heavy engineering buyers consolidate supplier panels around pre-machined kit capabilities. Geographic expansion and technology licensing dominate competitive moves as players seek MEE-compliant capacity and digital twin integration.
Among integrated steelmakers, ArcelorMittal exemplifies the diversified conglomerate archetype through European energy sector supply relationships. POSCO occupies a position reflecting captive raw material access at coastal industrial complexes. Precision Castparts Corp. anchors the precision investment casting tier serving turbine engine supply chains with superalloy capabilities. These three represent divergent strategic postures: backward integration into mining, coastal logistics optimization, and aerospace-grade metallurgical specialization.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| Nucor Corporation |
| Thyssenkrupp AG |
| Doosan Corporation |
| Precision Castparts Corp. |
| Georg Fischer Ltd |
| Kobe Steel, Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between NADCAP-qualified aerospace casters and commodity sand foundries manifests in both pricing premiums and supply chain tiering. Premium investment casters command three-to-five-fold price multiples over gray iron job shops while operating through direct OEM relationships, whereas commodity producers compete via distributor networks with thin margins and volatile scrap-cost pass-through.
Pricing Analysis
Lead-time compression drives pricing stratification across the analysis window. Investment casting houses serving Precision Castparts and medical implant OEMs capture premiums for sub-two-week prototype delivery, while sand foundries with excess green-sand capacity discount spot orders to cover fixed melt-shop overhead. Price differentiation hinges on NADCAP certification tier and melt-to-finish traceability documentation. Pricing pressure stems from automotive OEMs resisting environmental compliance cost pass-through for gray iron engine blocks. Tier 1 suppliers with IATF 16949 certification exhibit lowest price sensitivity; job-shop machinery component buyers demonstrate highest sensitivity to ferrous scrap index movements.
Supply Chain Analysis
Reverse-logistics flows for remelt scrap and core sand reclamation anchor circularity economics in heavy-section foundries. Geographic supply concentration centers on China, India, and Germany, with Jiangsu and Shandong provinces hosting carbon-intensive sand capacity subject to MEE operating hour caps. Raw material dependencies draw from Turkish and Vietnamese ferrous scrap export markets, Chinese graphite electrode supply, and Australian iron ore fines. Single-source vulnerability sits with ceramic shell material suppliers for investment casting. Distribution runs through direct mill-to-line delivery for power generation turbine housings and distributor-stocked inventory for agricultural machinery replacement castings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics dominate this market as MEE operating hour caps and patternmaking skill erosion prop pricing for qualified capacity. Foundries with integrated pollution control and digital twin capabilities capture structural premiums unavailable to carbon-intensive competitors.
For Market Incumbents: Deploy captive raw material access as a defensive moat against scrap price volatility. ArcelorMittal and POSCO exemplify backward integration into mining and coastal logistics that insulates margin structures. Incumbents should accelerate electric arc furnace conversion to preempt GB emissions standard tightening in China. Certification investment in NADCAP and ISO 9001 maintenance gates aerospace and medical vertical entry against emerging Asian competitors. For New Entrants and Emerging Players: Begin with additive manufacturing-enabled sand core printing to bypass patternmaking skill scarcity constraining North American and European incumbents. Western India's industrial corridor from Pune to Ahmedabad offers the most penetrable geography, with PLI scheme incentives amplifying agricultural machinery casting demand. A go-to-market angle targeting machined casting kit delivery—transferring dimensional risk upstream—aligns with Siemens Energy and GE Vernova procurement specifications. For Investors and Strategic Acquirers: Re-rating potential sits with precision investment casters given IRA domestic content credit catalysts reshaping US wind turbine nacelle sourcing. Long-term viability over a five-to-ten year horizon favors facilities with verified melt-to-finish traceability and electric arc furnace flexibility. Acquisition targets should display integrated pollution control systems and digital twin simulation capabilities. Monitor MEE provincial energy intensity enforcement patterns as the critical inflection signal for Chinese capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Arc Furnace Conversion | MEE operating hour caps in Jiangsu and Shandong favor EAF flexibility over carbon-intensive cupola melting. |
| Additive Manufacturing Integration | 3D-printed sand cores eliminate hard tooling for prototypes, compressing lead times for Siemens Energy qualification cycles. |
| Backward Integration into Scrap Processing | Captive ferrous scrap sorting reduces exposure to Turkish and Vietnamese export demand price spikes. |
| NADCAP Certification Investment | Gates supplier qualification for Precision Castparts aerospace turbine blade contracts with superalloy casting requirements. |
| Machined Casting Kit Capability | Delivers pre-configured assemblies with CMM inspection data, meeting GE Vernova delivered-to-line specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with foundry operations directors, heavy engineering procurement managers at Siemens Energy and GE Vernova, automotive Tier 1 supplier quality engineers, and patternmaking trade association representatives combined with bottom-up capacity surveys and top-down trade flow validation. Secondary sources included EPA emissions compliance databases, China's MEE provincial energy intensity disclosures, REACH substance restriction updates from ECHA, and ferrous scrap export statistics from customs authorities. Triangulation across these streams ensured cross-validation of melt-shop capacity estimates and pricing tier boundaries.
Data-stream reconciliation employed a segmented analytical framework across product type, casting method, application, and end user industry dimensions over the projection horizon. Volume outputs modeled sand casting tonnage for heavy industrial components separately from investment casting value capture in aerospace and medical verticals. CAGRs derived from regression analysis against power generation capital expenditure cycles, agricultural machinery production indices, and automotive platform casting content trends. Industry-specific forecast inputs incorporated MEE operating hour cap enforcement scenarios and IRA domestic content credit qualification thresholds.
Underlying measurement precision varies by segment; investment casting with NADCAP certification carries tighter precision than commodity gray iron job-shop capacity. Forecasts reflect assumptions regarding regulatory enforcement continuity, scrap price mean reversion, and patternmaking workforce availability that could shift materially. Practitioners should monitor MEE provincial energy intensity cap announcements, Turkish ferrous scrap export tariff movements, and automotive OEM environmental compliance cost pass-through negotiations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Quarry Tiles Market