
 Prefabricated Building System Market | 2026-2036
Prefabricated Building System Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Building System Market Outlook
Project finance tied to green bonds and sustainability-linked loans is reshaping competitive entry in prefabricated construction. Kirby Building Systems leverages its steel fabrication scale to anchor large commercial contracts across the Middle East and Southeast Asia. Skyline Champion Corporation sustains manufacturing density through factory-direct channels in North American residential markets. Sekisui House differentiates through precision-engineered modular housing systems that dominate Japan's urban infill segment.
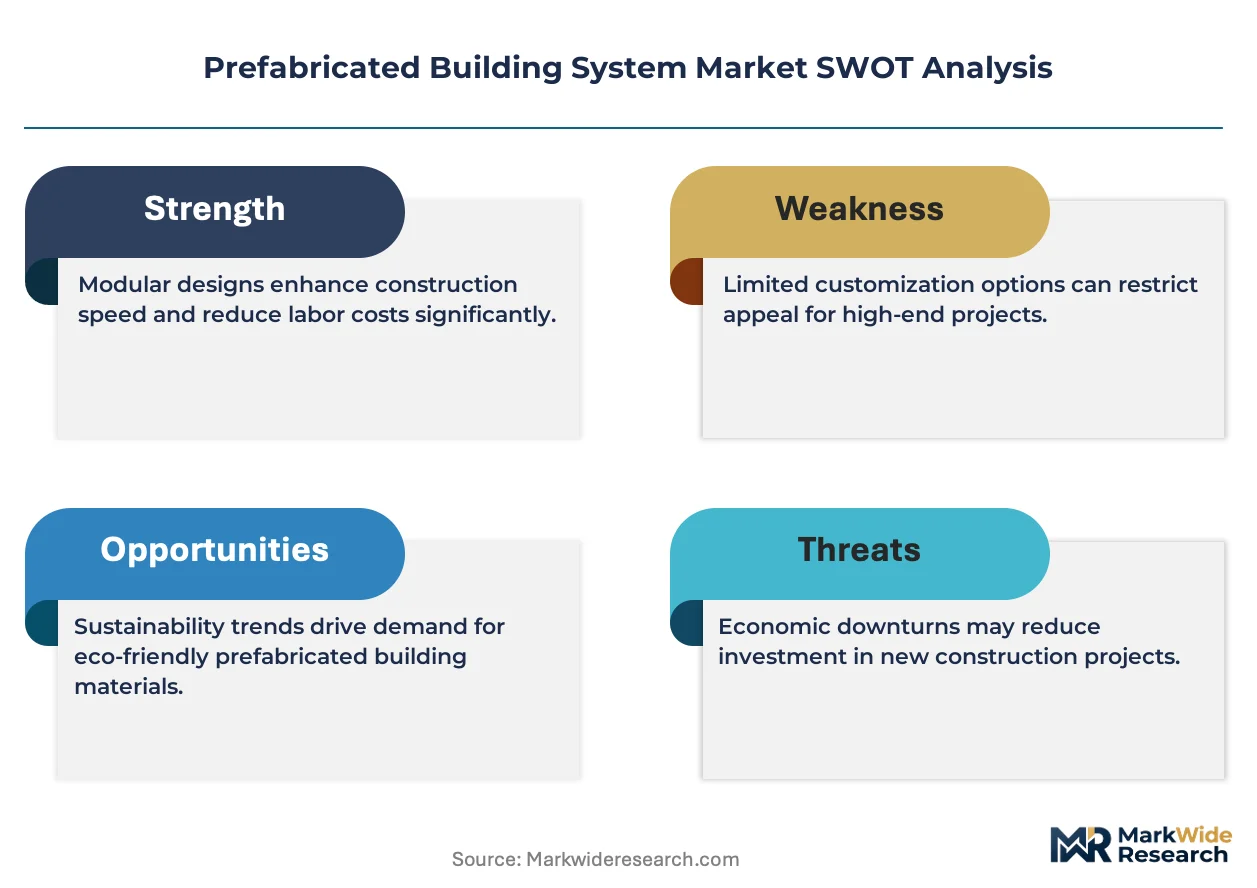
Prefabricated building systems encompass factory-manufactured structural assemblies—typically steel frames, concrete panels, or volumetric modular units—engineered for transport and rapid on-site integration, with dimensional tolerances often held within 2 millimeters to ensure weather-tight sealing and load-path continuity. These systems serve primarily to compress construction schedules, reduce site labor dependency, and standardize quality in housing projects, office buildings, and hospitality developments. Steel frames and modular units currently occupy the largest share of product-type value, while hybrid systems are gaining traction where developers seek to optimize across material cost, thermal performance, and seismic resilience. Among applications, housing projects lead in volume terms, though hospitality and office buildings represent higher-margin segments due to finish complexity and shorter payback requirements.
The EU Green Deal and F-Gas Regulation are tightening embodied-carbon thresholds for imported building materials, pushing European manufacturers toward low-carbon steel and cross-laminated timber hybrids. In the United States, OSHA and ICC code cycles are elevating factory certification requirements for structural components, raising compliance costs for smaller fabricators while favoring scaled producers. China's GB standards and dual carbon goals are accelerating domestic substitution of high-emission concrete processes with prefabricated alternatives. Stakeholders must monitor how diverging national carbon-accounting rules for construction alter cost competitiveness across supply bases and project locations.
Market Dynamics
Carbon-accounting mandates embedded in the EU Green Deal and F-Gas Regulation are forcing a material-specification pivot across prefabricated construction, compressing embodied-carbon thresholds and reconfiguring supplier qualification criteria.
Growth Catalysts
- EU F-Gas Regulation:Tightened embodied-carbon standards for imported insulation and refrigerant-bearing components accelerate substitution toward low-carbon steel and cross-laminated timber hybrids in German factory-fabricated housing clusters.
- Urban infill density:Japanese metropolitan authorities prioritize precision-engineered modular systems for constrained sites, compressing approval timelines for volumetric units versus conventional stick-built alternatives.
- OSHA factory certification:Elevated structural-component standards in the United States favor scaled producers with captive testing infrastructure, consolidating contract awards toward multi-facility fabricators.
Market Restraints
- Low-carbon steel premium:Electrified arc-furnace output carries input-cost volatility tied to scrap availability and electricity tariffs, compressing margins on green-certified projects.
- Supply concentration:Cross-laminated timber panel production clusters in Austria and Germany create geographic chokepoints for European modular builders seeking mass-timber structural cores.
- Seismic code fragmentation:Divergent lateral-load requirements across Japanese prefectures and California jurisdictions force redundant engineering cycles, inflating customization costs for standardized volumetric units.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea Development Authority procurement frameworks specify off-site fabrication for hospitality and residential volumes, opening contract entry for steel-frame specialists with Middle East logistics experience.
- GB standards acceleration:China's dual carbon goals mandate prefabricated substitution for high-emission cast-in-place concrete in provincial infrastructure, creating domestic demand for precast panel systems.
- Digital-twin integration:Convergence of BIM workflows with factory automation software enables real-time dimensional tolerance tracking, reducing on-site rework for hospitality developers with compressed payback requirements.
Industry Challenges
- Welding certification scarcity:Factory fabrication of steel moment frames demands AWS D1.8 seismic-qualified welders, with talent pipelines constricted across Midwestern US manufacturing zones.
- Transport modulus constraints:Volumetric unit highway-width limits in Germany and Japan force dimensional compromises that increase on-site connection complexity and weather-tight sealing risk.
- Carbon-accounting audit timelines:Third-party verification of embodied-carbon claims under EU Green Deal protocols extends project financing close cycles by 60-90 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Building System Market |
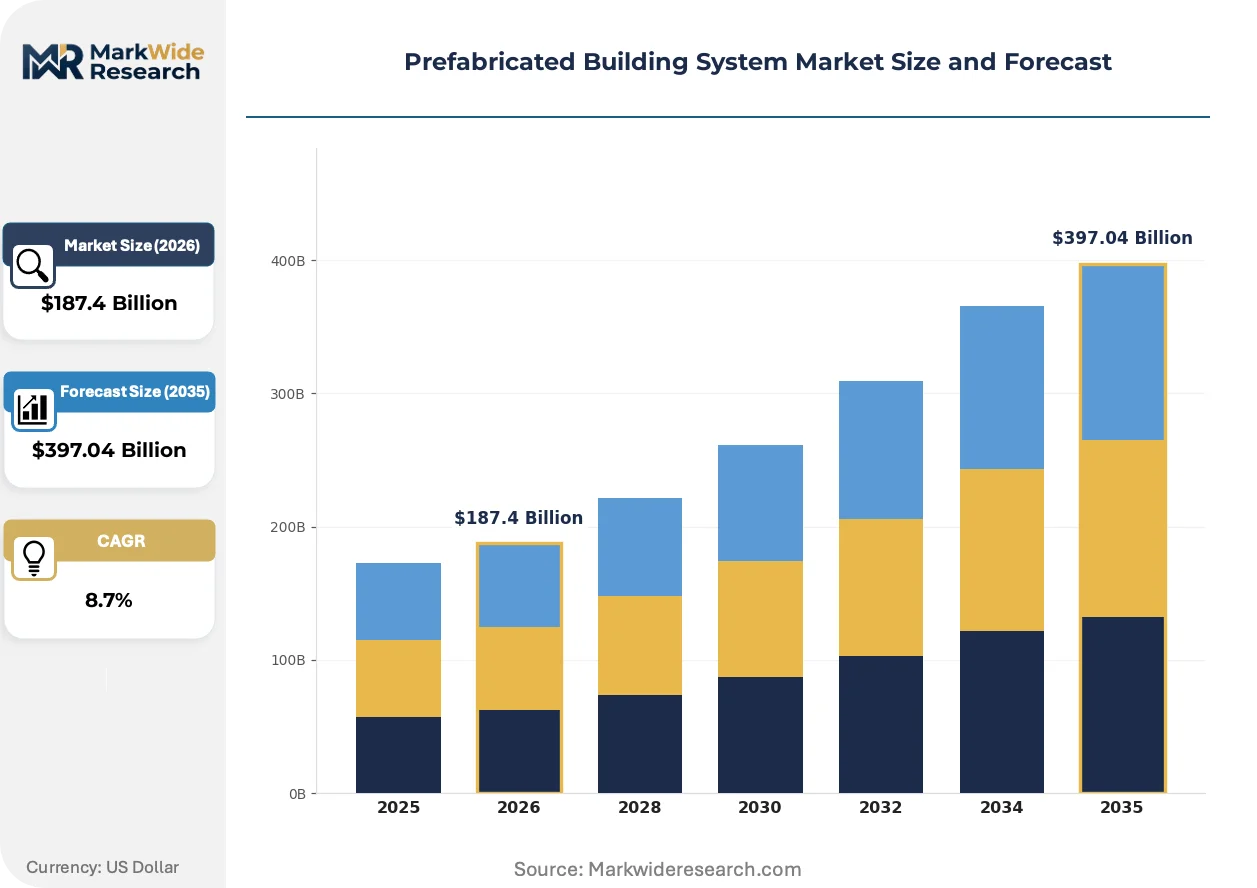
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Panels, Steel Frames, Modular Units, Hybrid Systems End User: Residential Developers, Commercial Builders, Government Projects, Educational Institutions Installation Method: On-site Assembly, Factory Fabrication, Off-site Installation, Quick Assembly Application: Housing Projects, Office Buildings, Retail Spaces, Hospitality |
| Companies Covered | Algeco Scotsman, Skyline Champion Corporation, Kirby Building Systems, Astron Buildings, Lindal Cedar Homes, ATCO, CIMC Modular Building, Laing O'Rourke, Sekisui House, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Building System Market Strategic Shifts
Material science advances and digital fabrication protocols are compressing the traditional trade-off between customization speed and structural performance in factory-built assemblies.
Cross-laminated timber is migrating from boutique residential applications to mid-rise commercial and hospitality structural cores. Developers in Bavaria and British Columbia specify mass-timber hybrid frames for five-to-twelve-story projects, drawn by biogenic carbon sequestration credentials. The technology is migrating from aesthetic differentiator to baseline structural option, compressing steel-frame dominance in segments where fire-rating and span requirements permit.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents for insulation materials forces reformulation of structural insulated panels. European manufacturers accelerate pentane and water-blown alternatives, with thermal performance penalties driving thicker wall assemblies. German and Austrian fabricators face the steepest compliance curves, retrofitting production lines ahead of 2027 threshold dates.
Design-build procurement is consolidating authority over specification decisions into single-source contractors with captive fabrication capacity. General contractors in the US Southeast and Australian eastern seaboard integrate modular delivery into lump-sum proposals, displacing traditional design-bid-award sequences. This concentration is most visible in healthcare and student housing verticals, where schedule certainty commands premium pricing.
Prefabricated Building System Market Segmentation
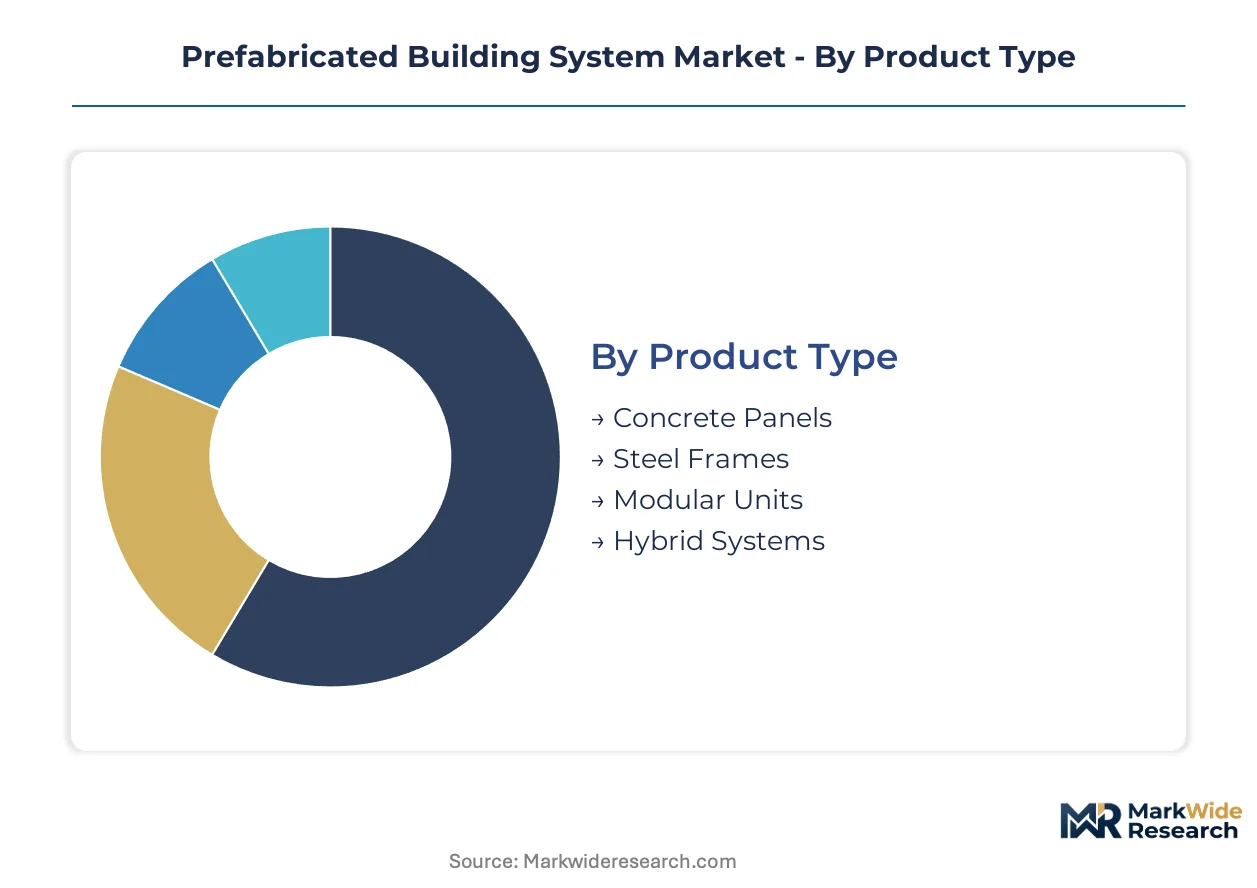
Material specification and procurement channel choices in prefabricated construction create divergent margin profiles and compliance burdens across product categories. Segmentation reveals where factory automation investments concentrate versus where site labor dependency persists.
Product Type:
Mature categories dominate current contract value, while emerging hybrid formats capture sustainability-driven specification shifts.
- Steel Frames:Structural steel moment frames and braced systems fabricated through CNC cutting and robotic welding deliver dimensional tolerances within 2 millimeters. Demand clusters in German commercial developments and Saudi giga-projects where seismic qualification and span requirements exceed timber capabilities.
- Modular Units:Volumetric factory-built rooms complete with MEP rough-ins and interior finishes enable 30-50% schedule compression versus stick-built alternatives. Japanese metropolitan authorities prioritize these systems for urban infill where site access constraints prevent conventional construction staging.
- Concrete Panels:Precast wall and floor assemblies substitute for cast-in-place concrete in China's provincial infrastructure builds under GB standards acceleration.
- Hybrid Systems:Mass-timber and steel composite frames balance biogenic carbon sequestration with structural span performance in Bavarian mid-rise commercial cores.
Steel frames retain volume leadership; hybrid systems hold the steepest expansion curve.
End User:
Cost tier stratification separates specification authority between price-sensitive volume builders and premium-schedule developers.
- Government Projects:Public procurement frameworks across EU member states and Saudi Arabia mandate embodied-carbon disclosure and factory certification, consolidating awards toward scaled fabricators with captive testing infrastructure. EU Green Deal compliance timelines extend bid-to-award cycles by 60-90 days.
- Commercial Builders:Design-build contractors in the US Southeast and Australian eastern seaboard integrate modular delivery into lump-sum proposals for healthcare and student housing verticals where schedule certainty commands premium pricing.
- Residential Developers:Factory-direct channels in North American markets sustain manufacturing density through repetitive single-family and multifamily typologies.
- Educational Institutions:Campus expansion projects in Japan and Germany specify precision-engineered modular classrooms to minimize operational disruption during academic terms.
Government projects anchor premium-tier contract values; commercial builders drive volume throughput in private markets.
Installation Method:
Geography determines logistics feasibility, with highway-width limits in Germany and Japan forcing dimensional compromises on volumetric units.
- Factory Fabrication:Structural components produced in climate-controlled facilities eliminate weather delays and standardize weld quality through automated processes. OSHA and ICC code cycles in the United States elevate certification requirements, raising compliance costs for smaller fabricators.
- Off-site Installation:Complete volumetric modules transported to prepared foundations reduce on-site labor dependency and connection complexity in constrained Japanese urban sites.
- On-site Assembly:Panelized systems delivered flat-packed minimize transport modulus constraints but increase weather-tight sealing risk during field integration.
- Quick Assembly:Standardized connection details and pre-installed MEP rough-ins compress final commissioning timelines for hospitality developers with compressed payback requirements.
Factory fabrication commands specification authority in regulated markets; quick assembly methods gain traction in schedule-sensitive hospitality segments.
Application:
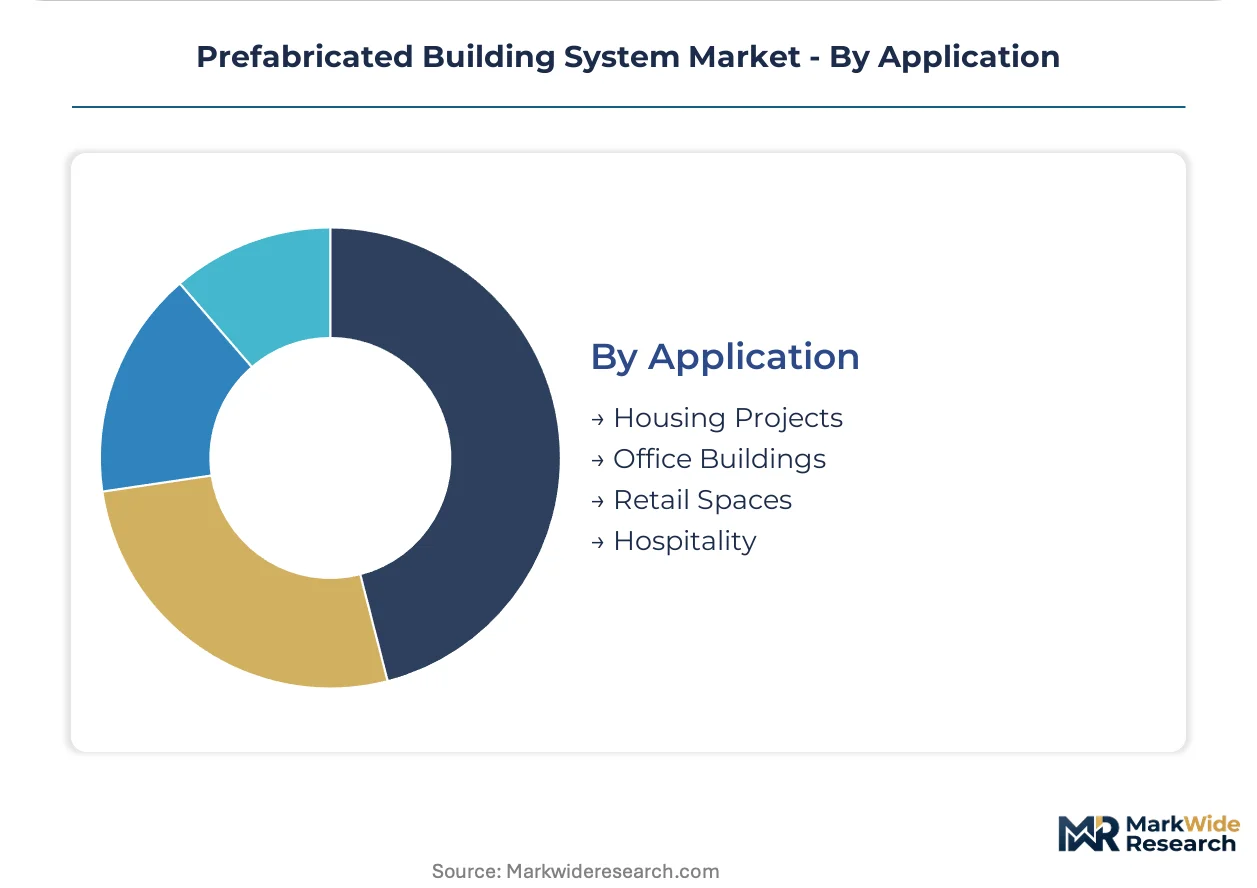
Margin structure inverts between high-volume housing and finish-complex hospitality developments.
- Hospitality:Hotel and resort projects specify high-finish volumetric units with integrated FF&E packages, commanding 40-60% premium over base structural costs. NEOM and Red Sea Development Authority procurement frameworks in Saudi Arabia specify off-site fabrication for residential and hospitality volumes.
- Office Buildings:Commercial cores in German and British Columbia markets migrate toward mass-timber hybrid frames for five-to-twelve-story projects where biogenic carbon credentials support green bond financing.
- Housing Projects:Single-family and multifamily residential applications lead absolute volume terms through repetitive typologies and factory-direct distribution channels.
- Retail Spaces:Big-box and strip mall developments utilize precast concrete panels and steel frames for rapid enclosure and tenant fit-out flexibility.
Housing projects retain volume leadership; hospitality holds the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-accounting mandates and Saudi giga-project procurement frameworks are reconfiguring where prefabricated capacity concentrates, with factory-fabricated housing clusters expanding fastest in jurisdictions that embed off-site construction into public infrastructure planning.
Germany
Bavarian and Baden-Württemberg housing clusters are scaling precision-engineered modular output for mid-rise commercial cores. The EU F-Gas Regulation's 2027 threshold dates force rapid reformulation of structural insulated panels, with German fabricators retrofitting production lines for pentane-blown alternatives. Factory-fabricated housing in southern Germany now serves as the reference standard for EU Green Deal compliance benchmarking.
Japan
Metropolitan authorities in Tokyo and Osaka prioritize volumetric modular systems for constrained urban infill sites. METI streamlines approval timelines for factory-certified volumetric units versus conventional stick-built alternatives. Sekisui House anchors precision-engineered modular production in the Kanto region, supplying urban infill developments with dimensional tolerances held within 2 millimeters.
China
Provincial infrastructure builds under GB standards acceleration substitute precast concrete panels for high-emission cast-in-place processes. The country's dual carbon goals mandate prefabricated construction in state-funded residential and transportation projects. Yangtze River Delta fabricators are expanding precast panel capacity to serve domestic infrastructure demand.
Saudi Arabia
NEOM and Red Sea Development Authority procurement frameworks specify off-site fabrication for hospitality and residential volumes. SFDA-aligned building product certification requirements favor fabricators with Middle East logistics experience. Steel-frame specialists are securing contract entry through design-build partnerships with Saudi giga-project developers.
United States
OSHA and ICC code cycles elevate factory certification requirements for structural components, consolidating contract awards toward multi-facility fabricators. Skyline Champion Corporation sustains manufacturing density through factory-direct channels in southeastern and southwestern states. Healthcare and student housing verticals command premium pricing for schedule certainty in design-build procurement.
Prefabricated Building System Market Competitive Environment
On the supply side, the industry is consolidating around scaled fabricators with captive testing infrastructure and multi-regional logistics networks. Tiered competitive positioning separates premium-tier specialists in precision-engineered modular systems from volume-driven producers of standardized steel frames and concrete panels. Three strategic archetypes dominate: steel fabrication scale players, factory-direct residential specialists, and precision modular engineers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with design-build integration and green bond financing access serving as secondary differentiation vectors.
Among steel fabrication scale players, Kirby Building Systems exemplifies the archetype of large commercial contract anchoring across Middle East and Southeast Asian markets. Skyline Champion Corporation occupies a position within the factory-direct residential tier, sustaining manufacturing density through repetitive typology production. Sekisui House sits within the precision-engineered modular segment, representing the specialist archetype for urban infill applications where dimensional tolerance and rapid site integration command specification priority.
| Leading Market Players |
|---|
| Algeco Scotsman |
| Skyline Champion Corporation |
| Kirby Building Systems |
| Astron Buildings |
| Lindal Cedar Homes |
| ATCO |
| CIMC Modular Building |
| Laing O'Rourke |
| Sekisui House |
| Others |
Value Chain & Pricing Dynamics
North Sea container corridors linking German Baltic ports to Middle Eastern project sites transmit freight cost volatility directly into volumetric module pricing, compressing margins for fabricators without captive logistics networks while amplifying price spreads between certified and uncertified suppliers.
Pricing Analysis
Certification level creates the primary spread between contract tiers, with EU Green Deal-compliant fabricators commanding project-based premiums over uncertified competitors. Factory-direct channels for North American residential developers anchor the standard tier through repetitive single-family typologies, while Saudi giga-project procurement concentrates in the premium tier where SFDA-aligned certification and Middle East logistics experience filter out smaller players. Pricing pressure stems from electrified arc-furnace steel input-cost volatility tied to scrap availability and electricity tariffs, compressing margins on green-certified projects. Government project buyers exhibit lowest price sensitivity due to embodied-carbon disclosure mandates extending bid-to-award cycles, whereas residential developers in factory-direct channels face acute cost compression.
Supply Chain Analysis
Contract manufacturing for structural insulated panels concentrates among Austrian and German timber processors retrofitting production lines for pentane-blown alternatives ahead of EU F-Gas Regulation thresholds. Raw material dependencies center on cross-laminated timber feedstock from Bavarian forests, low-carbon steel billet from electric arc furnaces, and hydrofluorocarbon-free blowing agents. Single-source vulnerability runs through CLT panel production clusters creating geographic chokepoints for European modular builders. Distribution runs through design-build contractors consolidating specification authority into lump-sum proposals for healthcare and student housing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat: EU Green Deal carbon-accounting mandates and OSHA factory certification requirements erect compliance barriers that consolidate contract awards toward scaled multi-facility fabricators with captive testing infrastructure.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into low-carbon steel supply through offtake agreements with electric arc furnace operators, and anchor capacity expansion in Baden-Württemberg clusters to capture EU Green Deal compliance benchmarking premiums before 2027 threshold dates force competitor retrofits. For New Entrants and Emerging Players: Establish a beachhead in Chinese provincial infrastructure builds under GB standards acceleration, where domestic substitution mandates for precast concrete panels create white-space demand without requiring EU or US certification infrastructure. Target Yangtze River Delta fabricators seeking technology partnerships for precast panel systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction conglomerates with underutilized factory-fabrication assets in Germany and Japan. Five-to-ten-year viability hinges on positioning for hospitality and healthcare verticals where schedule certainty commands premium pricing. Monitor carbon-accounting audit timeline compression as the inflection signal—third-party verification cycles extending project financing closes indicate regulatory stringency accelerating competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Integration | Consolidates specification authority into lump-sum proposals for Saudi giga-project developers. |
| Green Bond Financing Access | Unlocks project capital for mass-timber hybrid frames in Bavarian commercial cores. |
| Digital-Twin Platform Deployment | Enables real-time dimensional tolerance tracking for hospitality developers with compressed payback. |
| Backward Integration into Low-Carbon Steel | Hedges input-cost volatility from scrap availability and electricity tariff swings. |
| Multi-Regional Logistics Network Expansion | Captures NEOM and Red Sea Development Authority procurement frameworks requiring Middle East experience. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with factory fabrication managers, design-build procurement leads, carbon-accounting auditors, and hospitality development executives. Secondary validation drew from EU Green Deal protocol documentation, OSHA factory certification registries, GB standards acceleration notices, Saudi SFDA building product requirements, and SEC filings of publicly traded modular fabricators. Bottom-up project pipeline tracking and top-down construction spend allocation were triangulated to anchor volume estimates.
Calibration against historical prefabrication adoption curves in Germany and Japan informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include material specification, end-user procurement channel, installation method logistics feasibility, and application margin structure. CAGRs were derived from slope analysis of government project pipeline commitments and commercial builder design-build procurement trends. Industry-specific inputs incorporated embodied-carbon threshold trajectories under EU F-Gas Regulation and METI approval timeline differentials for volumetric versus stick-built alternatives.
Macroeconomic conditions sit as an overlay; deviation in construction credit availability, green bond issuance volumes, or electricity tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and factory certification adoption curves. Cross-checking against national construction spending databases and regional prefabrication penetration benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Glue-Laminated Timber Market