
 Australia and New Zealand Plastic Bottles Market | 2026-2036
Australia and New Zealand Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Plastic Bottles Market Insights
Aftermarket recycling collection revenue is narrowing as virgin resin price volatility compresses margins for reclaimers. Visy Group leverages its integrated recycling and blow-molding footprint across Melbourne and Sydney to control feedstock costs. Synergy Packaging anchors its position through pharmaceutical-grade PET capacity that sustains premium contract stability with healthcare formulators.
Plastic bottles are hollow thermoplastic containers formed through extrusion blow molding, injection blow molding, or stretch blow molding, typically ranging from 50 milliliters to 20 liters in finished volume, designed for liquid containment, dispensing, and shelf-stable distribution. PET dominates beverage applications due to clarity, barrier performance, and established collection infrastructure, while HDPE competes aggressively in household and personal care segments where chemical resistance and squeezability command formulation loyalty. Pharmaceutical-grade bottles carry the tightest specification burdens and consequently defend the most durable margin pools across the value chain.
TGA in Australia and Medsafe in New Zealand enforce pharmacopeial packaging standards that dictate migration limits, child-resistance protocols, and stability testing documentation for pharmaceutical bottles. Australia's National Packaging Targets mandate 50% recycled content and 70% recovery rates, while New Zealand's Plastic Packaging Declaration pressures brand owners to eliminate problematic single-use formats. Stakeholders must monitor how container deposit scheme expansions and recycled content verification protocols reshape sourcing economics and competitive positioning.
Market Dynamics
Australia's National Packaging Targets and New Zealand's Plastic Packaging Declaration are forcing converters to reconfigure resin sourcing and blow-molding operations around verified recycled feedstock streams.
Growth Catalysts
- Container Deposit Scheme Expansion:New South Wales and Queensland are extending scheme coverage to wine and spirits bottles, pulling additional PET volumes into formal collection loops and stabilizing reclaimer feedstock economics.
- Pharmaceutical-grade PET Demand:TGA stability testing documentation requirements for oncology and biologic formulations are locking in multi-year supply contracts with certified blow-molders.
- Auckland Metropolitan Corridor Concentration:Beverage brand owners are clustering manufacturing and distribution nodes within 50 kilometers of New Zealand's largest port, compressing logistics costs for export-ready PET bottles.
Market Restraints
- Virgin Resin Price Volatility:Naphtha-linked PET pellet costs swing unpredictably, squeezing margin predictability for converters without backward integration into recycling operations.
- Recycled Content Verification Bottlenecks:Australia's 50 percent recycled content mandate lacks harmonized certification protocols, creating compliance friction for multi-site brand owners.
- HDPE Substitution in Personal Care:Squeezable HDPE bottles are displacing rigid PET in shampoo and conditioner segments where dispensability trumps clarity.
Strategic Opportunities
- South Australia Underpenetration:The state's container deposit scheme maturity and lower converter density present first-mover positioning for pharmaceutical-grade blow-molders.
- rPET Food-Contact Approval Pathway:Medsafe's evolving guidance on mechanically recycled PET for dairy applications opens margin expansion for early certifiers.
- Digital Watermark Sorting Integration:Convergence of near-infrared detection and blockchain traceability is enabling premium pricing for batch-verified recycled content claims.
Industry Challenges
- Blow-Molding Technician Scarcity:Stretch blow-molding process optimization for rPET requires specialized thermal profiling expertise that outpaces vocational training pipeline output.
- Pharmacopeial Migration Testing Timelines:TGA stability documentation for novel barrier coatings extends certification cycles beyond typical contract negotiation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Plastic Bottles Market |
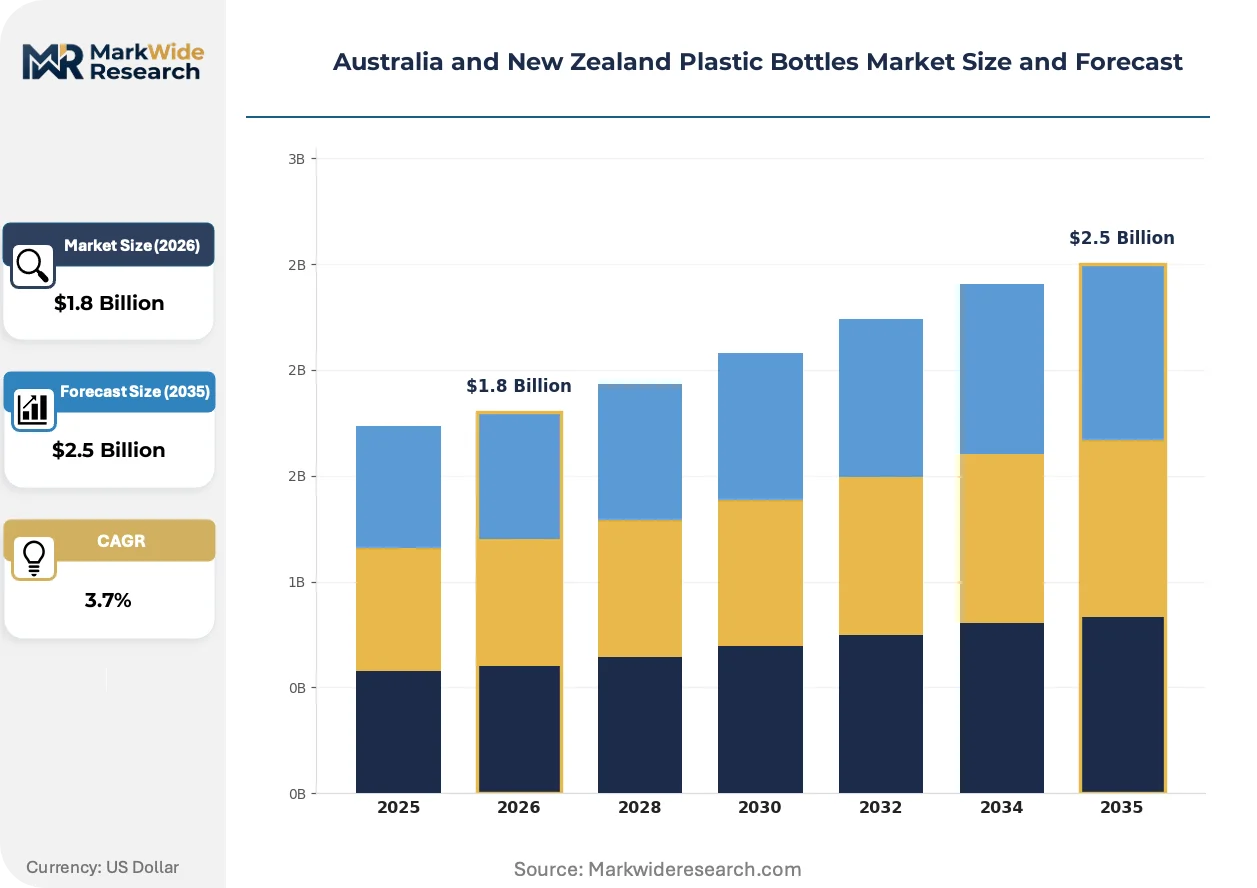
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC Application: Beverages, Personal Care, Household, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Wholesalers Distribution Channel: Online, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Visy Group, Synergy Packaging Pty Ltd (Pact Group Holdings Ltd), Plas-Pak (WA) Pty Ltd, Weltrade Packaging, Waipak NZ Ltd, Quality Blow Moulders, PB Packaging, Ant Packaging Pty Ltd, TSL Plastics Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Plastic Bottles Market Trends and Innovations
Converters across Australia and New Zealand are racing to deploy next-generation barrier technologies and digital traceability systems ahead of tightening recycled content verification deadlines.
Multilayer co-injection blow-molding is hybridizing oxygen scavenger functionality with rPET core structures, enabling beer and wine brands to meet 12-month shelf-life specifications while hitting 50 percent recycled content thresholds. Premium beverage formulators in Victoria and South Australia are piloting these bottles at commercial scale. The technology is compressing demand for traditional glass packaging in export-oriented craft brewing segments.
TGA's updated pharmacopeial packaging standards are mandating enhanced migration limit documentation for pharmaceutical bottles, forcing blow-molders to invest in gas chromatography testing infrastructure. Compliance costs are filtering contract awards toward converters with in-house analytical capabilities. Oncology and biologic drug packaging in Sydney and Melbourne manufacturing corridors faces the steepest documentation burden.
Brand owners are consolidating procurement around converters offering integrated recycling and blow-molding services, displacing fragmented spot-market resin purchasing. Healthcare and beverage multinationals in Auckland and Sydney are leading this consolidation. The shift is most visible in pharmaceutical-grade PET contracts where supply security trumps unit cost minimization.
Australia and New Zealand Plastic Bottles Market Segmentation
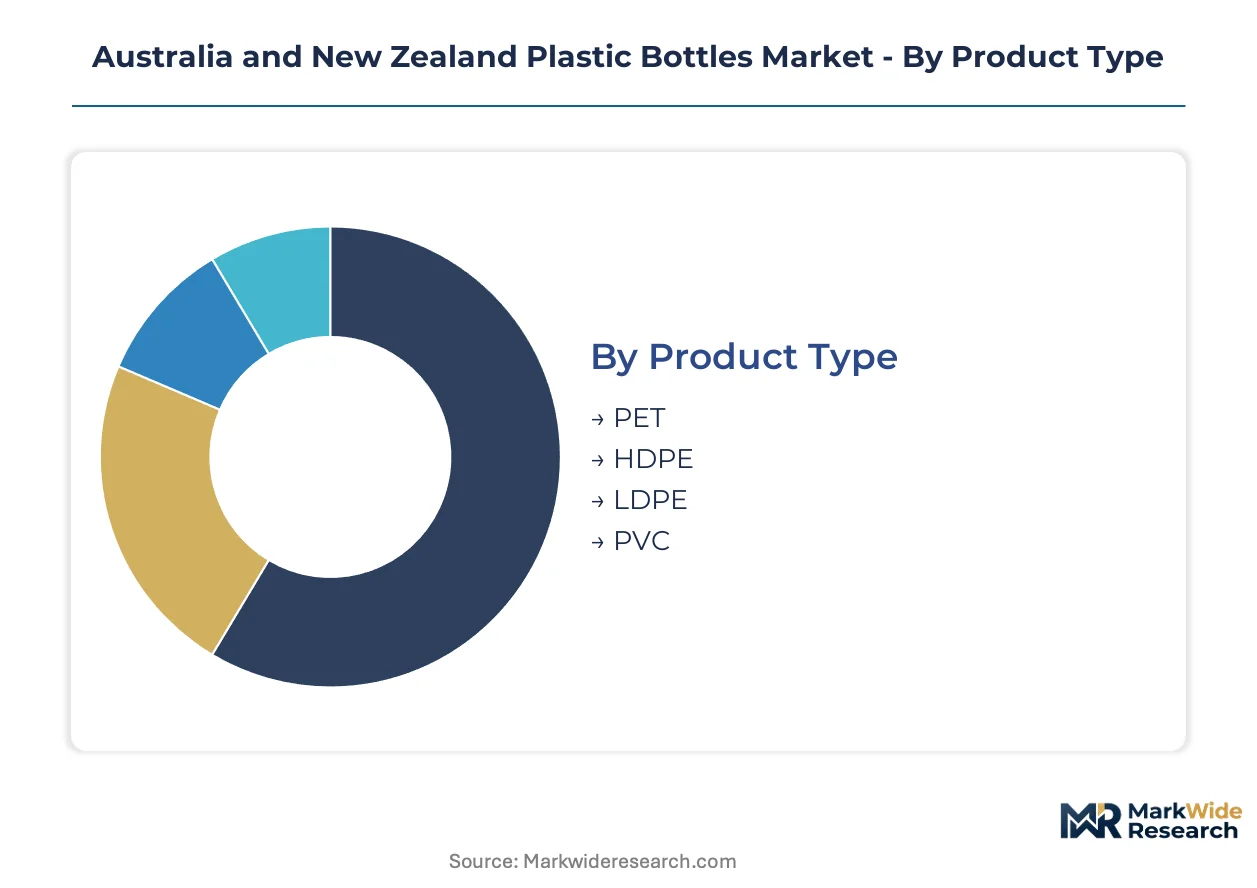
Segmentation in the Australia and New Zealand Plastic Bottles Market reveals how resin chemistry, application requirements, and channel economics create distinct competitive arenas. Understanding these divides exposes where margin pools concentrate and where converters must build specialized capabilities to defend positioning.
Product Type:
Mature resin technologies dominate beverage and pharmaceutical throughput, while emerging polymer grades carve niches in flexible and barrier-sensitive applications.
- PET:Polyethylene terephthalate delivers optical clarity, oxygen barrier performance, and established mechanical recycling compatibility. Beverage brand owners in Sydney and Melbourne manufacturing corridors lock in multi-year contracts for food-contact certified grades. Australia's container deposit scheme infrastructure stabilizes rPET feedstock economics for converters with backward integration into collection operations.
- HDPE:High-density polyethylene offers chemical resistance and squeezability that commands formulation loyalty in shampoo and conditioner segments. Auckland personal care manufacturers favor HDPE over rigid alternatives where dispensability trumps shelf visibility. Virgin resin price volatility squeezes margin predictability for converters without captive recycling capacity.
- LDPE:Low-density polyethylene serves squeeze-tube and flexible bottle applications where conformability matters. Pharmaceutical ointment packaging in New South Wales uses LDPE for controlled dispensing.
- PVC:Polyvinyl chloride retains limited presence in chemical-resistant industrial containers and specific barrier coatings. Regulatory pressure on chlorine-based chemistry constrains expansion.
PET handles the majority of throughput; HDPE is the fastest mover on share as personal care formulators prioritize squeezability.
Application:
Volume concentration tracks population density and export corridor proximity, while margin stratification follows pharmacopeial certification burdens.
- Beverages:Carbonated soft drinks, bottled water, and juice applications consume the largest resin volumes. Stretch blow-molding operations cluster within 50 kilometers of Auckland Port and Sydney's Port Botany to compress logistics costs for export-ready formats. New South Wales and Queensland container deposit scheme expansions are pulling wine and spirits bottles into formal collection loops.
- Pharmaceuticals:Oncology and biologic formulations demand TGA stability testing documentation that extends certification cycles. Sydney and Melbourne manufacturing corridors face the steepest compliance burden, filtering contract awards toward converters with in-house gas chromatography infrastructure.
- Personal Care:Shampoo, conditioner, and lotion bottles prioritize squeezability and chemical resistance over clarity. HDPE displacement of rigid PET is accelerating in this segment.
- Household:Cleaning product containers balance chemical resistance with cost minimization. Auckland metropolitan distribution nodes serve both domestic retail and Pacific Island export demand.
Beverages commands absolute volume; Pharmaceuticals delivers the steepest expansion trajectory as TGA documentation requirements deepen converter specialization.
End User:
Procurement authority concentrates with manufacturers and retailers, while distributors and wholesalers face margin compression from direct channel expansion.
- Manufacturers:Beverage and pharmaceutical formulators with captive filling lines negotiate multi-year supply contracts. These buyers prioritize supply security and recycled content verification over unit cost minimization.
- Retailers:Supermarket chains and pharmacy banners are consolidating procurement around converters offering integrated recycling and blow-molding services. Private-label volume is climbing fastest in this channel.
- Distributors:Independent packaging distributors serve mid-tier personal care and household brands with fragmented spot-market purchasing. Virgin resin volatility erodes margin stability.
- Wholesalers:Bulk resellers face displacement as brand owners bypass intermediaries for direct converter relationships. Surviving players specialize in rapid-turn, small-batch fulfillment.
Manufacturers lock in the longest contract tenures; Retailers are gaining procurement leverage fastest through sustainability-linked sourcing mandates.
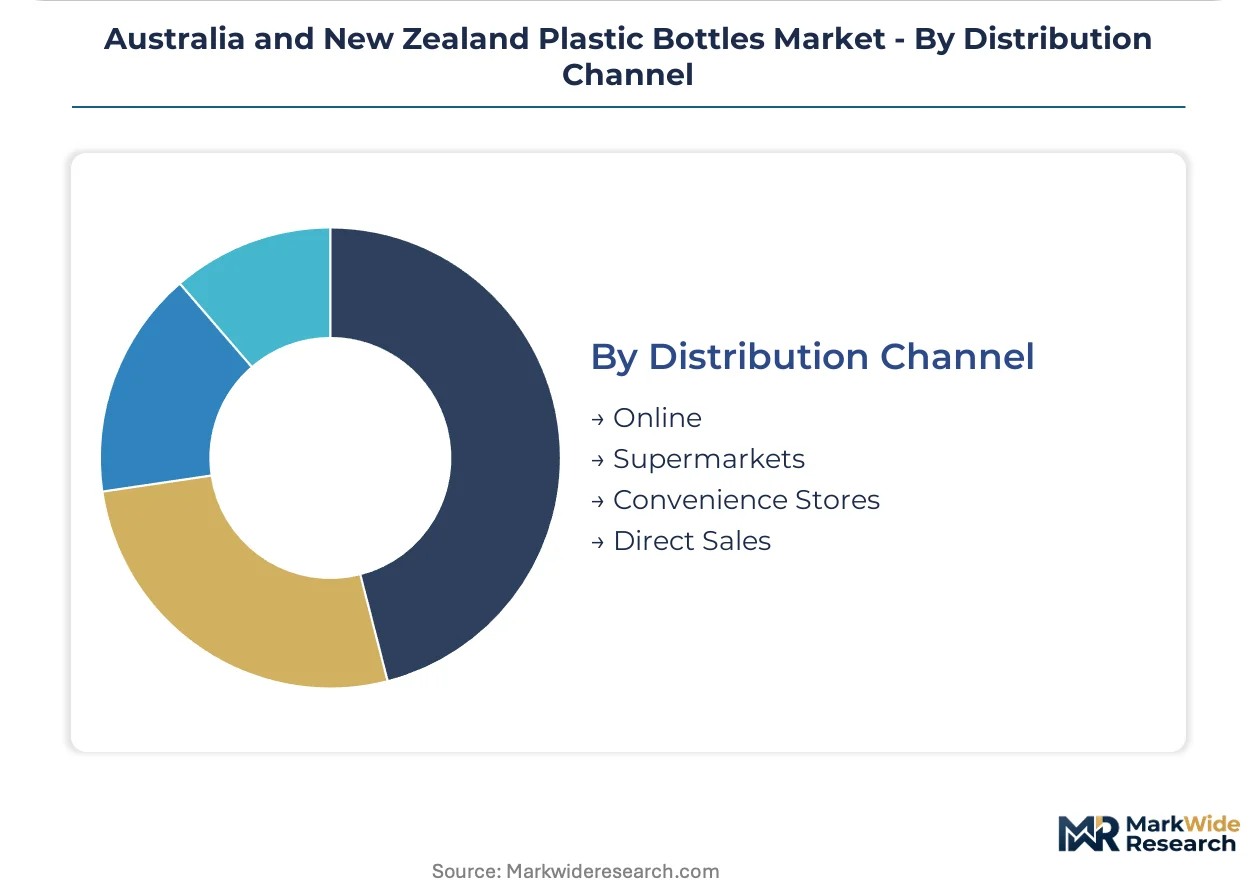
Distribution Channel:
Channel economics diverge between high-volume supermarket supply and specialized direct sales for pharmaceutical-grade certification.
- Supermarkets:Coles, Woolworths, and Countdown parent companies specify recycled content thresholds and digital traceability requirements. These buyers compress converter margins through volume concentration.
- Direct Sales:Pharmaceutical-grade PET contracts bypass intermediaries entirely. TGA documentation handoffs require converter-buyer technical collaboration that distributor channels cannot support.
- Online:E-commerce packaging procurement is emerging for specialty beverage and personal care startups. Batch size flexibility trumps unit cost in this channel.
- Convenience Stores:7-Eleven and independent petrol station networks source through consolidated distributor relationships. Format standardization limits customization requirements.
Supermarkets move the highest absolute volumes; Direct Sales is climbing fastest as pharmaceutical certification demands tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive beverage brand owners cluster in Queensland and Western Australia, while pharmaceutical formulators in Sydney and Melbourne accept steep premiums for TGA-certified supply security.
New South Wales
Sydney's Port Botany corridor anchors the highest PET bottle throughput in Australia, serving export-ready beverage manufacturers. The state's container deposit scheme expansion to wine and spirits bottles is pulling additional volumes into formal collection loops. Pharmaceutical-grade blow-molders concentrate in Sydney's western manufacturing belt to service oncology and biologic drug formulators.
Victoria
Melbourne's integrated recycling and blow-molding infrastructure supports Visy Group's captive feedstock operations across the metropolitan area. TGA stability testing documentation requirements filter contract awards toward converters with in-house gas chromatography capabilities. The state's craft brewing sector pilots multilayer co-injection bottles for 12-month shelf-life beer exports.
Queensland
Brisbane and Gold Coast beverage manufacturers drive HDPE demand for squeezable personal care formats where dispensability trumps clarity. The state's container deposit scheme maturity stabilizes reclaimer economics for backward-integrated converters. Southeast Queensland's lower converter density presents positioning opportunities for pharmaceutical-grade specialists.
South Australia
Adelaide's mature container deposit scheme and underpenetrated converter base attract first-mover pharmaceutical-grade blow-molders. The state's wine industry generates PET bottle demand for export-oriented packaging. Local reclaimer capacity outpaces blow-molding infrastructure, creating feedstock surplus conditions.
New Zealand
Auckland's metropolitan corridor concentrates beverage manufacturing within 50 kilometers of the country's largest port, compressing logistics costs for export-ready formats. Medsafe's evolving guidance on mechanically recycled PET for dairy applications opens certification pathways for early movers. The Plastic Packaging Declaration pressures brand owners to eliminate problematic single-use formats.
Australia and New Zealand Plastic Bottles Market Competitive Landscape
Capability concentration sits with pharmaceutical-grade specialists; scale advantage sits with integrated recycling and blow-molding operators. The market structures around three tiers: backward-integrated giants controlling resin feedstock, certified specialists defending TGA documentation moats, and regional fabricators competing on batch flexibility. Dominant competitive moves include captive recycling capacity expansion and multi-year pharmaceutical contract lock-ins.
Among Australia-based integrated operators, Visy Group exemplifies the backward-integrated archetype through its Melbourne and Sydney recycling-to-blow-molding footprint. Synergy Packaging occupies the pharmaceutical-grade specialist tier, anchoring premium contract stability through certified PET capacity. Waipak NZ Ltd represents the New Zealand-focused fabricator archetype, serving Auckland's export-oriented beverage cluster with regional logistics advantages.
| Leading Market Players |
|---|
| Visy Group |
| Synergy Packaging Pty Ltd (Pact Group Holdings Ltd) |
| Plas-Pak (WA) Pty Ltd |
| Weltrade Packaging |
| Waipak NZ Ltd |
| Quality Blow Moulders |
| PB Packaging |
| Ant Packaging Pty Ltd |
| TSL Plastics Ltd |
| Others |
Pricing and Supply Chain Analysis
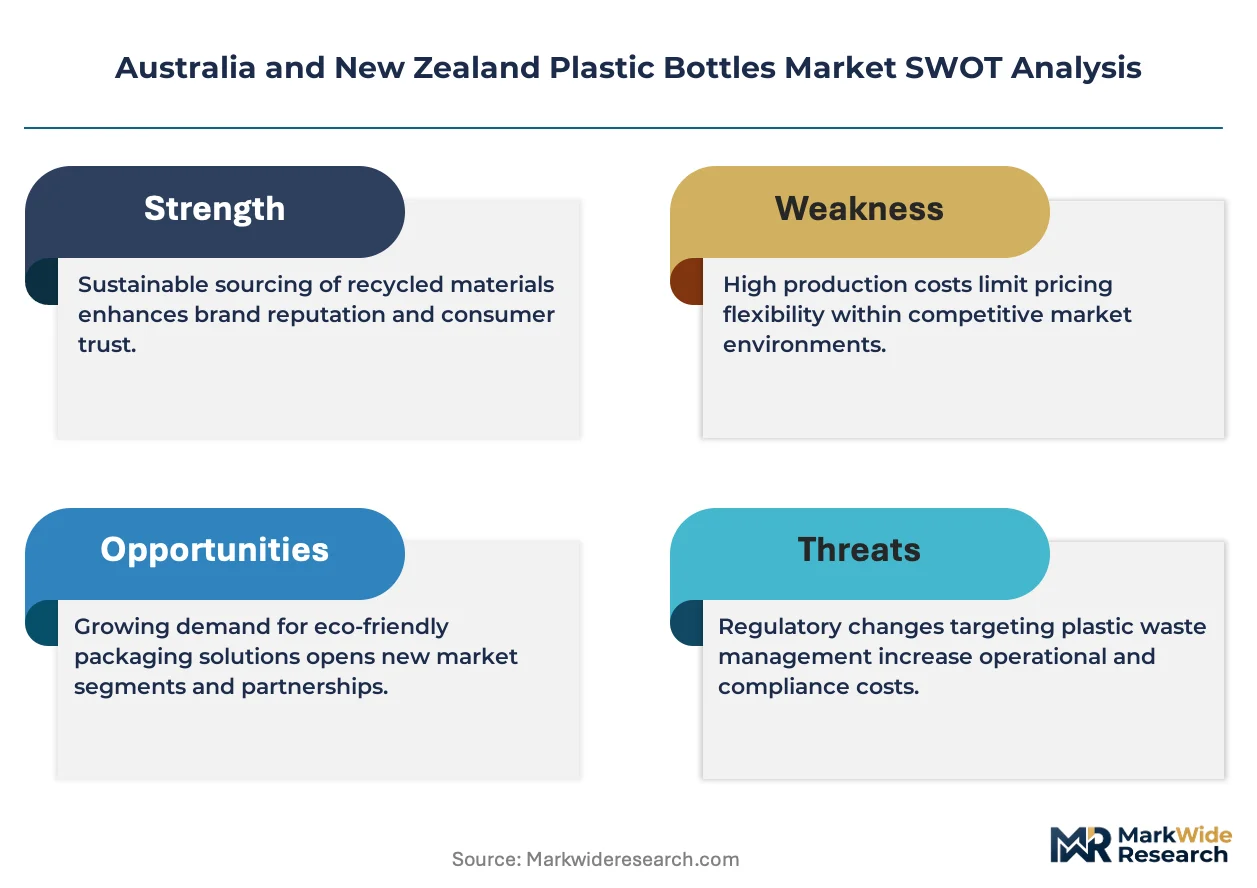
Virgin resin price volatility tied to naphtha feedstock swings compresses margin predictability for converters lacking backward integration into recycling operations, forcing a three-tier pricing structure across premium pharmaceutical-grade, standard beverage-grade, and economy personal care segments while simultaneously reshaping supply chain investments toward captive rPET collection infrastructure.
Pricing Analysis
Aftermarket recycling collection revenue drives lifetime value for integrated operators, with pharmaceutical-grade PET commanding premium contract stability through TGA certification requirements that filter awards toward converters with in-house gas chromatography capabilities. Price differentiation rests on certification grade and volume scale, with oncology and biologic drug packaging segments showing lowest price sensitivity due to supply security priorities. Cost compression in standard beverage-grade PET intensifies as supermarket chains consolidate procurement around sustainability-linked sourcing mandates. Personal care manufacturers exhibit highest price sensitivity, accelerating HDPE substitution where dispensability trumps barrier performance.
Supply Chain Analysis
Tariff exposure between Australia and Asian resin suppliers dominates supply chain risk assessment for non-integrated converters. Feedstock sourcing concentrates in Australia, New Zealand, and Southeast Asian petrochemical hubs. Raw material dependencies center on virgin PET pellets, rPET flake, and HDPE resin grades. Single-source vulnerability persists for pharmaceutical-grade blow-molding equipment requiring specialized thermal profiling expertise. Distribution runs through direct sales channels for certified pharmaceutical contracts and consolidated supermarket procurement for high-volume beverage formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across this market as container deposit scheme expansions and recycled content verification requirements create specialized niches for certified operators and integrated recyclers alike.
For Market Incumbents: Entrench positioning through captive rPET collection capacity expansion in New South Wales and Victoria manufacturing corridors, while deepening TGA documentation capabilities to defend pharmaceutical-grade contract moats against emerging certified entrants. Backward integration into recycling operations offsets virgin resin volatility threats from naphtha-linked feedstock markets. For New Entrants and Emerging Players: Establish a beachhead in South Australia's underpenetrated pharmaceutical-grade segment, where mature container deposit scheme infrastructure and local reclaimer surplus create favorable feedstock economics. Target early certification for Medsafe's evolving mechanically recycled PET dairy pathways as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated operators with proven rPET quality systems over fragmented spot-market resin purchasers. Long-term viability hinges on regulatory compliance infrastructure rather than unit cost minimization. Watch container deposit scheme harmonization across Australian states as the signal for feedstock economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Operations | Captive rPET supply secures margin stability against virgin resin volatility for New South Wales converters. |
| TGA Certification Investment | In-house gas chromatography infrastructure filters pharmaceutical contract awards toward compliant blow-molders. |
| Multilayer Co-Injection Technology Deployment | Oxygen scavenger functionality enables 12-month shelf-life beer exports for Victoria craft brewers. |
| Digital Watermark Sorting Integration | Blockchain traceability supports premium pricing for batch-verified recycled content claims in supermarket channels. |
| South Australia Manufacturing Footprint | First-mover positioning exploits mature container deposit scheme and underpenetrated converter base. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with blow-molding plant managers, pharmaceutical procurement leads, beverage brand sustainability officers, and supermarket category buyers; and secondary validation through TGA guidance documents, Medsafe consultation papers, Australian Packaging Covenant Organisation reports, and container deposit scheme operator disclosures. Bottom-up resin throughput modeling triangulated against top-down packaging value chain estimates.
Forecast inputs considered resin chemistry segments, application requirements, end-user procurement authority, and distribution channel economics across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by regional manufacturing corridor concentration. Industry-specific forecast inputs included container deposit scheme expansion timelines and pharmacopeial packaging standard revision cycles.
Stress conditions across virgin resin price bands, rPET availability thresholds, and regulatory compliance timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about recycled content mandate enforcement intensity and certification protocol harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Plastic Vials Market