
 Folding Plastic Crates Market | 2026-2036
Folding Plastic Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Plastic Crates Market Foresight
Skilled mold technicians and automation engineers is redrawing competitive boundaries across the folding plastic crates landscape. Schoeller Allibert leverages its European manufacturing footprint to sustain just-in-time contracts with major food retailers. ORBIS Corporation anchors North American automotive logistics through captive production of heavy-duty collapsible designs. Rehrig Pacific Company differentiates via proprietary hinge geometries that extend cycle life in dairy distribution.
Folding plastic crates are injection-molded polypropylene or high-density polyethylene containers with integrated hinge systems enabling flat-fold collapse to roughly one-fifth of assembled height. Wall thickness typically ranges from 2.5 to 4.5 millimeters, with vented or solid configurations matched to payload sensitivity; their primary purpose is to replace single-use corrugated packaging in closed-loop supply chains. Collapsible crates command premium positioning due to freight cost savings on return legs, while nestable designs dominate price-sensitive agricultural lanes. Polypropylene grades with UV stabilizers lead material selection for outdoor produce harvesting, though high-density polyethylene competes in cold-chain pharmaceutical applications where low-temperature impact resistance governs specification.
EU REACH compliance and FDA food-contact regulations under 21 CFR 177.1520 constrain base resin and additive selection, directly elevating testing costs for new entrants. The EU Green Deal's reuse targets and California's rigid plastic packaging regulations are forcing brand owners to specify returnable crates rather than expendable alternatives. Stakeholders must monitor how ECHA's microplastics restriction timeline affects hinge lubricant formulations and whether USDA organic handling rules expand crate sanitization requirements.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's reuse mandates are compressing converter margins while forcing rapid redesign cycles toward durable, multi-trip architectures.
Growth Catalysts
- EU Green Deal reuse targets:The regulation mandates minimum recycled content thresholds and returnable packaging ratios, compelling supermarkets to specify folding crates over corrugated alternatives.
- Polypropylene UV stabilization:Outdoor produce harvesting operations in Spain and Italy now require weather-resistant grades that extend field service life beyond 500 cycles.
- Automotive just-in-time logistics:German OEM assembly plants are consolidating supplier packaging standards around collapsible HDPE designs to reduce inbound freight cube by 80 percent on return legs.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and high-density polyethylene resin prices fluctuate with naphtha cracking economics, compressing molders' pass-through pricing power.
- Tooling capex concentration:Large-tonnage injection molds for 1200x800mm agricultural crates require 18-24 month lead times from specialized German and Austrian toolmakers.
- Corrugated substitution persistence:Export-oriented fruit exporters in developing markets continue specifying single-use fiberboard for one-way ocean freight to avoid reverse logistics costs.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-validated folding crates with integrated data loggers address FDA 21 CFR 211 distribution requirements for biologics.
- India FSSAI food safety modernization:The regulator's mandatory crate sanitization protocols for perishables create specification windows for antimicrobial additive formulations.
- RFID-embedded hinge systems:Convergence of injection molding with passive tagging enables real-time asset tracking across closed-loop pool systems.
Industry Challenges
- Mold technician scarcity:European toolrooms face retirement waves among skilled hot-runner specialists capable of maintaining 128-cavity production tools.
- REACH compliance timelines:ECHA's microplastics restriction proposal threatens hinge lubricant formulations, requiring 12-18 month reformulation cycles ahead of enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Plastic Crates Market |
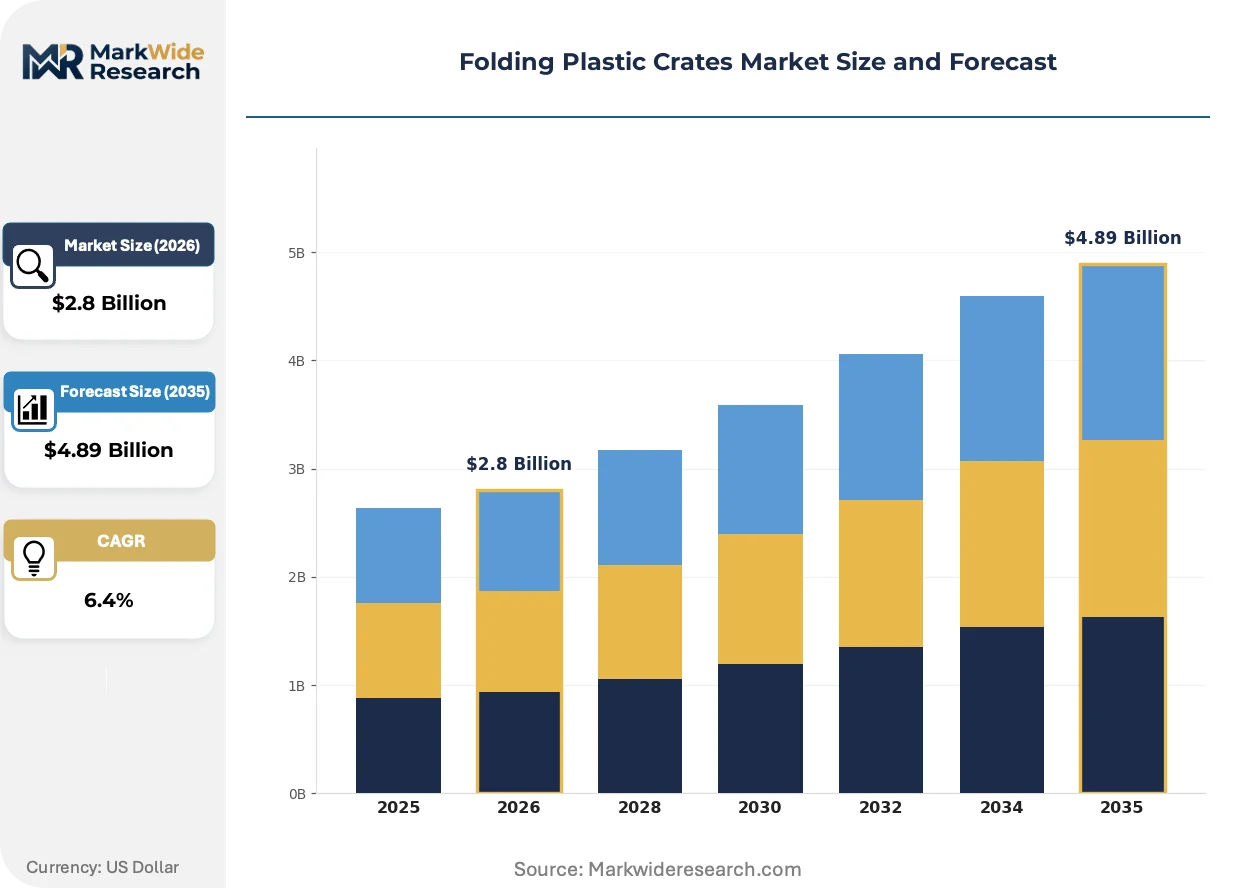
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Crates, Nestable Crates, Collapsible Crates, Tote Crates Material: Polypropylene, High-Density Polyethylene, Polycarbonate, ABS Application: Food Processing, Pharmaceuticals, Warehousing, Distribution Centers End User: Retail Chains, Packaging Manufacturers, Logistic Providers, Agricultural Cooperatives |
| Companies Covered | Schoeller Allibert, Rehrig Pacific Company, ORBIS Corporation, Monoflo International, Brambles Limited, DS Smith, SSI Schaefer, RPP Containers, Myers Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Plastic Crates Market Shifts & Advancements
Active redesign of material formulations and tracking architectures is compressing product lifecycles while elevating performance specifications across food, automotive, and pharmaceutical verticals.
Reinforced polypropylene compounds with glass-fiber loadings of 15-30 percent are fragmenting the traditional wall-thickness tradeoff between durability and collapse ratio. Tier-one automotive suppliers in Stuttgart and Wolfsburg specify these grades for engine component dunnage despite 40 percent material cost premiums. The technology enables thinner-wall designs that maintain 50-kilogram dynamic load ratings while achieving one-sixth collapsed height.
REACH Article 33 substance-of-very-high-concern disclosure requirements now extend to hinge lubricants and colorant masterbatches. Convertors must maintain 10-year supply chain documentation trails for SVHC concentrations above 0.1 percent weight-by-weight. Small and mid-sized molders in Portugal and Poland are outsourcing compliance management to specialized regulatory consultancies rather than building in-house toxicology capabilities.
Asset-pooling operators are unbundling crate provision from transport services, selling per-trip usage rights rather than unit sales. This model displaces capital purchase decisions from supermarket procurement teams to third-party pool managers. The shift is most advanced in France, where major retailers have outsourced entire reusable packaging fleets to specialized logistics platforms operating under multi-year service agreements.
Folding Plastic Crates Market Segmentation
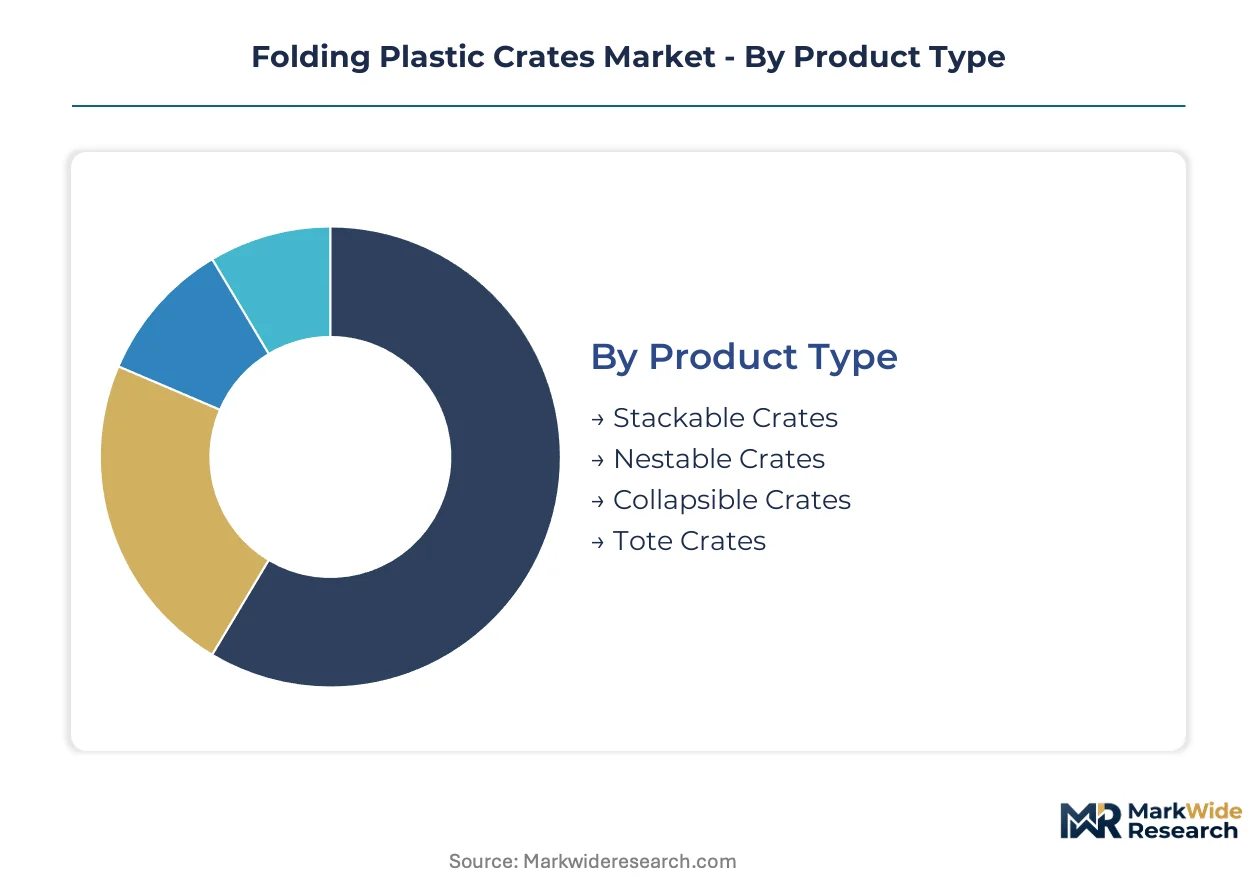
Segmentation in folding plastic crates reflects divergent durability requirements across regulatory regimes. Material selection and structural design vary sharply between EU REACH-governed food contact applications and FDA-regulated pharmaceutical distribution.
Product Type:
EU Packaging and Packaging Waste Regulation reuse mandates favor designs maximizing trip cycles, while corrugated substitution economics in developing markets sustain single-trip alternatives.
- Collapsible Crates:Hinge-integrated polypropylene or HDPE containers collapse to one-fifth assembled height. German automotive assembly plants specify these for 80 percent return-leg freight reduction in just-in-time supplier networks.
- Nestable Crates:Tapered-wall designs stack inside each other when empty, sacrificing collapse ratio for structural simplicity. Agricultural distribution in Spain and Italy absorbs volume here due to lower per-unit capital requirements and UV-stabilized resin availability.
- Stackable Crates:Rigid interlocking feet enable vertical loading without nesting or collapse capability. Dairy processors in France specify these for cold-chain stability where hinge fatigue would compromise hygiene protocols.
- Tote Crates:Smaller-footprint containers designed for manual handling in retail backrooms. E-commerce fulfillment centers in the Netherlands deploy these for last-mile sortation efficiency.
Collapsible crates handle the majority of throughput; nestable crates are expanding most quickly in agricultural applications.
Material:
Cost tiers separate commodity resins from engineering polymers, with regulatory compliance costs widening spreads between base grades.
- Polypropylene:Dominant selection for outdoor produce harvesting with UV stabilizers extending field service beyond 500 cycles. REACH SVHC disclosure requirements now cover additive packages, elevating documentation burdens for compounders.
- High-Density Polyethylene:Cold-chain pharmaceutical applications favor this resin for low-temperature impact resistance under FDA 21 CFR 211 distribution rules. Biologics shippers in Switzerland specify HDPE for temperature-validated folding designs.
- Polycarbonate:Transparent grades enable visual inspection without opening. Medical device sterilization cycles in Germany drive specification here despite 3x material cost premiums.
- ABS:Acrylonitrile butadiene styrene offers rigidity for lightweight electronic component dunnage. Polish contract electronics manufacturers source ABS crates for ESD-sensitive semiconductor transport.
Polypropylene commands volume leadership; polycarbonate is gaining share fastest in medical-grade applications.
Application:
Margin structures diverge between regulated verticals with validation requirements and commodity logistics where price drives procurement.
- Food Processing:FSSAI-mandated crate sanitization protocols in India create specification windows for antimicrobial additives. Fresh produce washing stations in Maharashtra require drainage-optimized vented designs.
- Pharmaceuticals:Temperature-validated folding crates with integrated data loggers address FDA distribution requirements. Cold-chain biologics expansion in Massachusetts and North Carolina concentrates demand here.
- Warehousing:High-velocity distribution centers prioritize collapse ratio for empty container storage density. Amazon fulfillment networks in Germany and Poland drive standardization around 1200x800mm footprints.
- Distribution Centers:Cross-dock operations favor rapid assembly without tools. Retail consolidation hubs in California specify color-coded crate systems for SKU segregation.
Food processing dominates unit shipments; pharmaceuticals shows the steepest expansion trajectory on value per trip.
End User:
Customer type determines contract structure, with asset-pooling models displacing capital purchases among multi-site retailers.
- Retail Chains:French supermarkets have outsourced entire reusable packaging fleets to third-party pool managers under per-trip service agreements. Carrefour and Intermarché contracts now specify RFID-embedded hinge systems.
- Logistic Providers:Asset-pooling operators unbundle crate provision from transport services. DHL Supply Chain and Kuehne+Nagel operate closed-loop systems across Benelux with real-time tracking platforms.
- Packaging Manufacturers:Converters serving brand owners face EU Green Deal recycled content thresholds. Schoeller Allibert and ORBIS Corporation invest in in-house regrind capabilities to meet supermarket procurement mandates.
- Agricultural Cooperatives:Price-sensitive procurement favors nestable designs with minimal feature sets. Spanish citrus cooperatives in Valencia specify vented HDPE for field-to-port harvest logistics.
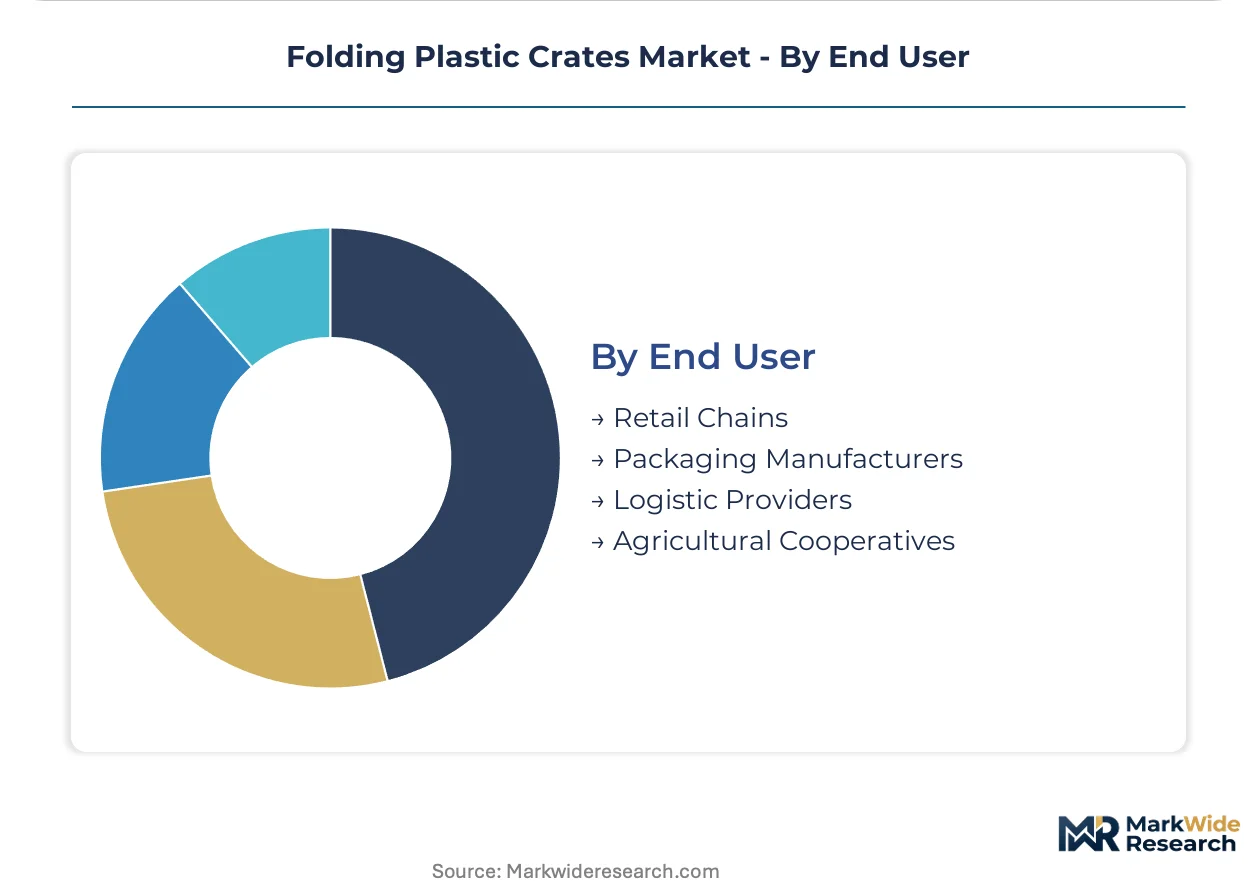
Retail chains control the largest installed base; logistic providers are climbing the fastest on pooled-fleet adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes folding plastic crates primarily for automotive logistics standardization, while India deploys them for FSSAI-mandated fresh produce hygiene compliance. This consumption-mix differential separates closed-loop industrial pooling from regulatory-driven food safety infrastructure.
Germany
Automotive just-in-time networks in Stuttgart and Wolfsburg specify collapsible HDPE crates to compress inbound freight cube by 80 percent on return legs. KBA vehicle safety standards indirectly govern transport packaging durability through load-securing regulations. Bavarian molders cluster around Ingolstadt supplier parks to serve Audi and BMW assembly lines with 24-hour replenishment cycles.
United States
Amazon fulfillment centers in Pennsylvania and Texas drive standardization around 1200x800mm footprints for high-velocity warehouse operations. FDA 21 CFR 177.1520 food-contact regulations constrain resin selection for dairy distribution crates. Cold-chain biologics expansion in Massachusetts concentrates pharmaceutical-grade demand for temperature-validated folding designs.
India
FSSAI-mandated crate sanitization protocols for perishables create specification windows for antimicrobial additive formulations. Maharashtra fresh produce washing stations require drainage-optimized vented designs for citrus and grape exports from Nashik. Agricultural cooperatives in Gujarat favor nestable HDPE configurations for field-to-port harvest logistics.
France
Carrefour and Intermarché have outsourced entire reusable packaging fleets to third-party pool managers under per-trip service agreements. EU Green Deal reuse targets mandate minimum recycled content thresholds for supermarket procurement. Paris-region logistics platforms now specify RFID-embedded hinge systems for real-time asset tracking.
Spain
Valencia citrus cooperatives specify UV-stabilized polypropylene for outdoor harvesting operations exceeding 500 field cycles. EU REACH SVHC disclosure requirements now extend to hinge lubricants and colorant masterbatches. Andalusian agricultural distributors concentrate procurement through Seville-based supply cooperatives serving export-oriented fruit operations.
Folding Plastic Crates Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with molders stratifying by captive resin compounding capabilities and toolroom scale. The upper tier commands multi-year pooling contracts through captive fleet management platforms, while mid-cap specialists defend position via proprietary hinge geometries and regional logistics density. Three archetypes dominate: European heritage manufacturers with automotive pedigree, North American industrial packaging conglomerates with distribution network scale, and Asian contract molders serving price-sensitive agricultural procurement. Consolidation pressure manifests through backward integration into regrind operations and strategic partnerships with asset-pooling operators.
Within the European heritage tier, Schoeller Allibert and SSI Schaefer exemplify molders with deep automotive supplier relationships and captive European manufacturing footprints. Among North American fabricators, ORBIS Corporation occupies a position representing heavy-duty collapsible designs for industrial logistics. Rehrig Pacific Company anchors the specialist tier through differentiated hinge system expertise. These three represent the competitive spectrum from integrated pooling platforms to component-focused engineering houses.
| Leading Market Players |
|---|
| Schoeller Allibert |
| Rehrig Pacific Company |
| ORBIS Corporation |
| Monoflo International |
| Brambles Limited |
| DS Smith |
| SSI Schaefer |
| RPP Containers |
| Myers Industries |
| Others |
Supply & Pricing Matrix
EU REACH SVHC disclosure requirements govern both supplier qualification thresholds and price stratification across the folding plastic crates landscape. Mold technicians capable of maintaining 128-cavity hot-runner tools command premium contract rates, while compounders with decade-long additive documentation trails price 15-25 percent above commodity resin suppliers.
Pricing Analysis
Long-term offtake agreements dominate procurement between automotive OEMs and captive molders serving just-in-time supplier parks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical grades from agricultural nestable designs. Cost compression in commodity polypropylene grades is intensifying because naphtha cracking economics transmit volatility directly to converter margins. Agricultural cooperatives in Spain and Italy exhibit highest price sensitivity, while German automotive logistics buyers prioritize collapse-ratio performance over per-unit cost.
Supply Chain Analysis
18-24 month lead times for large-tonnage injection molds from German and Austrian toolmakers strain inventory planning across European converter networks. Production gravity centers on Germany, China, and the United States, with Bavarian molders clustering around Ingolstadt supplier parks. Tool steel and hot-runner components draw from specialized metallurgical suppliers in Austria and Japan. Single-source vulnerability concentrates in 1200x800mm agricultural crate tooling where only three European toolrooms maintain relevant capacity. Distribution runs through asset-pooling operators in France and third-party logistics platforms across Benelux.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU REACH, FDA 21 CFR, and India FSSAI regimes fragments demand into specialized niches. Each compliance jurisdiction creates specification windows for additive formulations, validation protocols, and tracking architectures that reward focused specialists over generalist molders.
For Market Incumbents: Secure captive regrind capabilities to meet EU Green Deal recycled content mandates while locking in multi-year pooling contracts with French retail consortiums. Toolroom automation investments in Germany offset retiring hot-runner specialist cohorts threatening 128-cavity production continuity. Backward integration into UV-stabilized polypropylene compounding insulates margin pressure from petrochemical feedstock volatility. For New Entrants and Emerging Players: Lead with antimicrobial additive formulations targeting India FSSAI-mandated crate sanitization protocols for Maharashtra fresh produce operations. Pharmaceutical cold-chain expansion in Massachusetts offers lowest competitive density among regulated verticals. RFID-embedded hinge systems provide a hardware-software convergence angle distinct from commodity molding competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade validation infrastructure as FDA 21 CFR 211 distribution requirements harden. Five-to-ten year viability favors molders with captive European manufacturing footprints and automotive pedigree. The signal to watch is ECHA microplastics restriction enforcement timelines threatening hinge lubricant reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regrind Operations | EU Green Deal thresholds force captive recycled content capabilities at Schoeller Allibert scale. |
| RFID-Embedded Hinge System Development | Carrefour and Intermarché contracts now specify real-time asset tracking across pooled fleets. |
| Antimicrobial Additive Formulation Investment | FSSAI protocols in Maharashtra create specification windows for perishable logistics infrastructure. |
| Hot-Runner Toolroom Automation | Retirement waves among German specialists threaten 128-cavity production continuity at Bavarian clusters. |
| Temperature-Validation Infrastructure Buildout | FDA 21 CFR 211 distribution rules concentrate biologics demand in Massachusetts and North Carolina. |
Research Methodology
Desk research of trade association filings, customs databases, and regulatory submission records preceded structured interviews with mold technicians, automotive procurement leads, supermarket category managers, and pharmaceutical logistics directors. Primary fieldwork with Bavarian toolrooms and French pooling operators combined with secondary validation through ECHA SVHC disclosure databases and FDA 21 CFR guidance documents. Bottom-up shipment modeling triangulated against top-down resin consumption estimates.
Variance decomposition across material grades, end-use verticals, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, resin specification, application vertical, and customer contract structure. CAGRs derived from shipment trajectories weighted by value-per-trip differentials between pharmaceutical and agricultural use cases. Cold-chain biologics expansion and EU reuse mandate enforcement timelines served as scenario-input sensitivities.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or petrochemical price stability would require recalibration. Forecasts reflect documented assumptions regarding tooling lead times and pooling contract renewal rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market