
 Reservoir Media Bottle Market | 2026-2036
Reservoir Media Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Reservoir Media Bottle Market Analytics
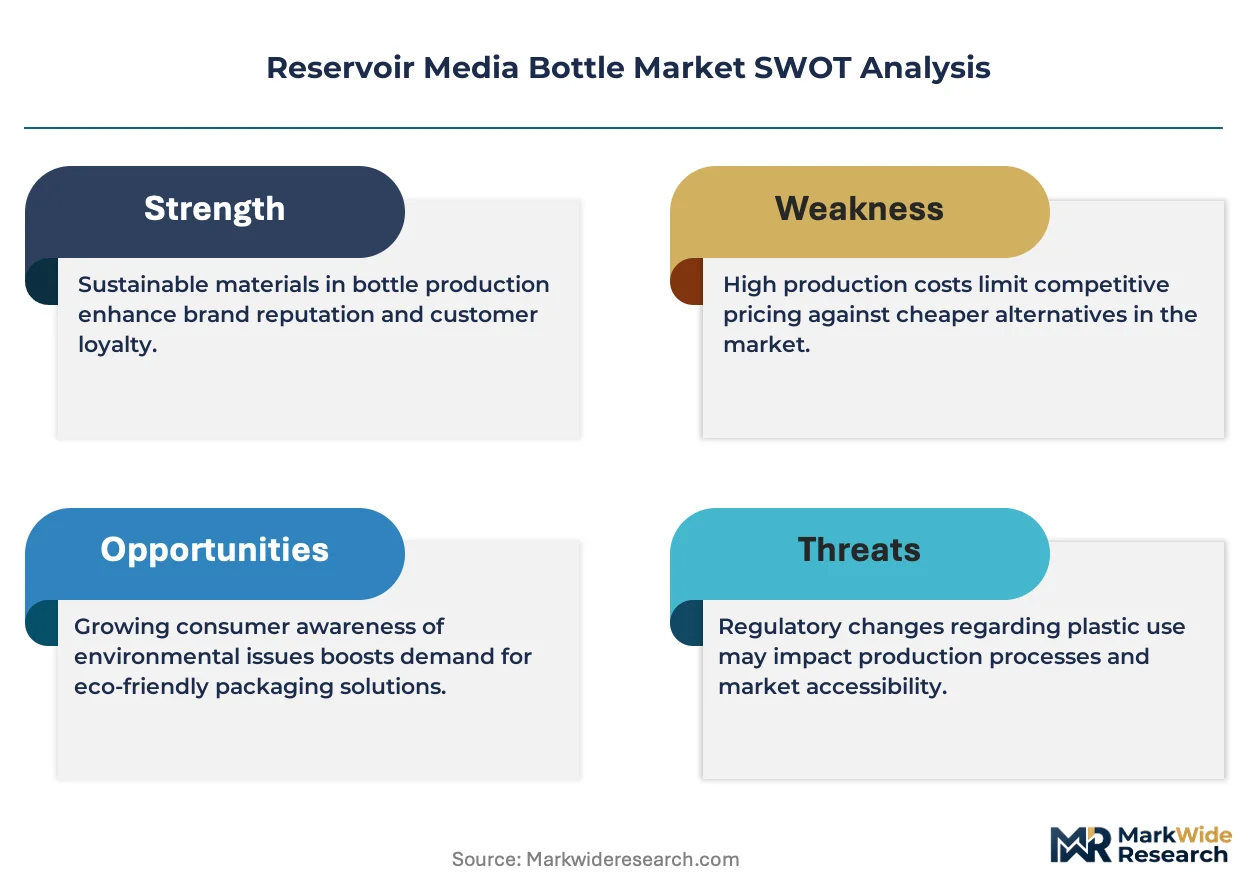
Pharma-grade polycarbonate specification upgrades is unwinding legacy polypropylene dominance in reservoir media bottle procurement. Gerresheimer AG leverages its glass-to-plastic hybrid manufacturing depth to sustain premium positioning across European biologics supply chains. Corning Incorporated anchors North American demand through its cell culture consumables ecosystem. Schott AG differentiates via borosilicate glass reservoir lines that serve vaccine fill-finish applications requiring thermal shock resistance.
A reservoir media bottle is a rigid or collapsible vessel engineered for aseptic storage and dispensing of cell culture media, buffer solutions, or bioprocess fluids, typically manufactured from USP Class VI-certified polymers or borosilicate glass with gamma-stable closure systems. These containers maintain sterility across frozen-to-ambient temperature cycles while enabling closed-system fluid transfer through luer-lock or tube weld interfaces. The disposable segment captures the fastest expansion as biopharma manufacturers eliminate cleaning validation burdens from multi-product facilities. Glass material reservoirs retain margin concentration in gene therapy and viral vector production where extractables profiles face heightened scrutiny from FDA reviewers. Reusable polycarbonate formats compete in academic and CRO settings where batch volumes fluctuate and capital budgets constrain per-unit consumables spend.
FDA biocompatibility testing under ISO 10993 and EMA's Annex 1 sterile manufacturing revisions are elevating closure integrity and particulate testing requirements for all fluid contact surfaces. EPA guidelines on pharmaceutical manufacturing effluent are pressuring converters to validate recyclable or biodegradable polymer alternatives without compromising gamma irradiation stability. China NMPA alignment with ICH Q5D standards is reshaping import qualification pathways for foreign reservoir suppliers. Stakeholders must monitor regulatory divergence between USP <661.1> plastic extractables thresholds and emerging EFSA food-contact migration limits that could spill over into bioprocess material certifications.
Market Dynamics
Single-use fluid handling systems are compressing demand for reusable reservoir formats across multi-product biopharma facilities, forcing material suppliers to requalify polymer grades for gamma-irradiated disposable architectures.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:The updated guidelines mandate closed-system fluid transfer, accelerating replacement of open-neck glass reservoirs with luer-lock closure designs in European fill-finish operations.
- Gene therapy viral vector production:Extractables-sensitive applications in adeno-associated virus manufacturing pull borosilicate glass reservoirs back into demand despite polymer cost advantages.
- China NMPA ICH Q5D alignment:Harmonized quality standards streamline import qualification for foreign single-use reservoir suppliers into domestic biologics facilities.
Market Restraints
- Polycarbonate resin price volatility:Pharma-grade polymer feedstock costs fluctuate with benzene and bisphenol-A spot markets, squeezing converter margins on long-term supply contracts.
- German glass-to-plastic converter concentration:European biologics manufacturers face single-source risk for borosilicate reservoir supply as specialty glassworks consolidate furnace capacity.
- Gamma irradiation capacity bottlenecks:Sterilization service providers in the United States operate at utilization rates above 85 percent, extending lead times for disposable reservoir lots.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru seek qualified single-use reservoir suppliers for export-oriented biologics production.
- Biodegradable polymer validation:EPA pharmaceutical effluent guidelines create pull for polylactic acid and polyhydroxyalkanoate alternatives that maintain USP Class VI certification.
- Closed-system welding integration:Convergence of tube welding automation with aseptic filling lines enables reservoir-to-bioreactor fluid transfer without manual intervention.
Industry Challenges
- Extractables testing expertise scarcity:ISO 10993-18 analytical chemistry capabilities concentrate in specialized contract labs, extending material qualification timelines for new polymer entrants.
- Legacy stainless steel infrastructure retrofit:Multi-product facilities face capital expenditure burdens when integrating disposable reservoir manifolds with existing fixed-tank cleaning validation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reservoir Media Bottle Market |
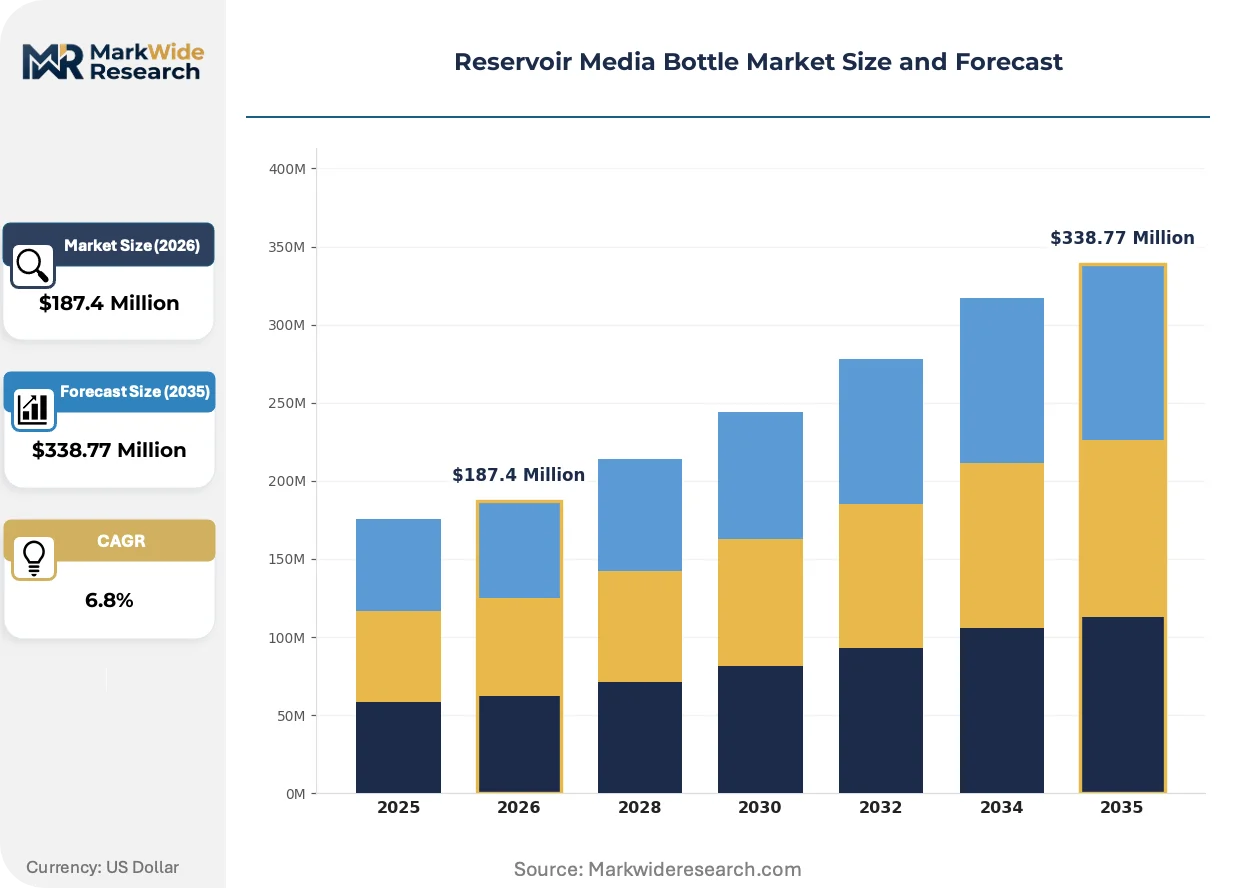
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Insulated, Collapsible Material: Plastic, Stainless Steel, Glass, Aluminum End User: Fitness Enthusiasts, Outdoor Adventurers, Office Workers, Students Capacity: 500ml, 750ml, 1L, 2L |
| Companies Covered | Gerresheimer AG, West Pharmaceutical Services, Schott AG, Corning Incorporated, Berry Global Group, Amcor plc, Owens-Illinois, Drug Plastics Group, Alpla Werke Alwin Lehner GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reservoir Media Bottle Market Evolving Landscape
Closed-system architecture requirements are fragmenting reservoir design standards across regulatory jurisdictions while compressing product development cycles for material suppliers.
Collapsible fluoropolymer film reservoirs are decomposing rigid polycarbonate dominance in large-volume media storage applications. Contract manufacturing organizations in the United States and Germany are adopting these formats for 50-liter and above batch sizes. The technology is decomposing traditional capital equipment economics by eliminating CIP/SIP infrastructure from facility designs.
REACH SVHC candidate list expansion is forcing reformulation of plasticizer and stabilizer packages in polymer reservoir grades. ECHA notifications for phthalate alternatives are accelerating supplier audits of additive supply chains. European gene therapy manufacturers are responding by dual-sourcing borosilicate glass reservoirs to hedge polymer compliance uncertainty.
Consolidated buying by top-ten biopharma manufacturers is compressing supplier negotiation leverage for mid-tier reservoir converters. Direct procurement relationships with polymer resin compounders are displacing distributor intermediaries in high-volume contracts. This concentration is most visible in United States coastal biotech clusters where facility construction has outpaced qualified local supplier capacity.
Reservoir Media Bottle Market Segmentation
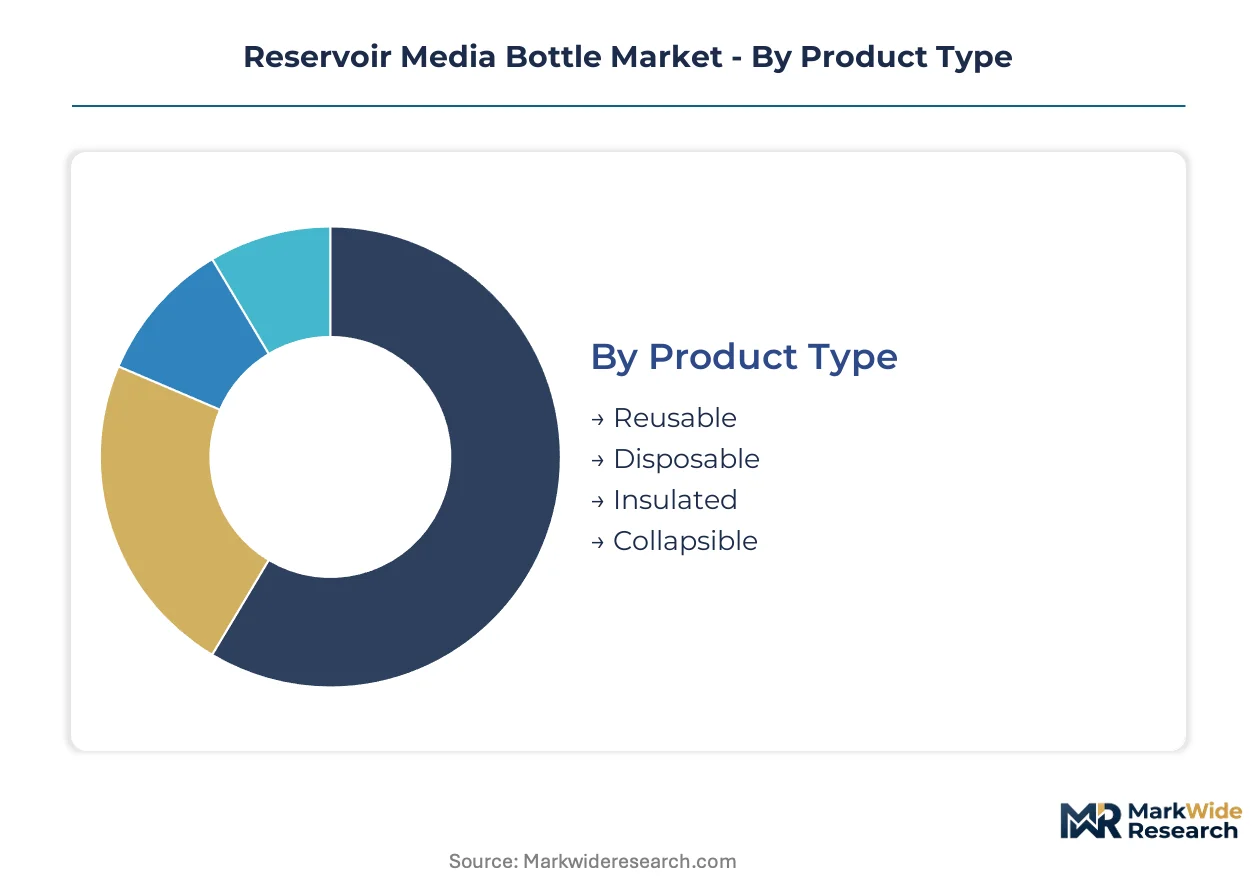
Segmentation in reservoir media bottles reveals where single-use architectures displace legacy formats and which material certifications command procurement premiums. Biopharma buyers prioritize closure integrity, extractables profiles, and sterilization compatibility over consumer-oriented attributes like aesthetics or portability.
Product Type:
Disposable formats face substitution pressure from collapsible fluoropolymer alternatives in large-volume storage, while reusable polycarbonate competes on capital budget constraints in academic settings.
- Disposable:Gamma-irradiated polymer reservoirs with luer-lock closures eliminate cleaning validation burdens from multi-product biopharma facilities. Demand concentrates in United States coastal biotech clusters where facility construction has strained qualified local supplier capacity.
- Collapsible:Fluoropolymer film reservoirs decompose rigid polycarbonate dominance in 50-liter and above batch sizes. Contract manufacturing organizations in Germany adopt these formats to eliminate CIP/SIP infrastructure from facility designs.
- Reusable:Polycarbonate formats serve academic and CRO settings where batch volumes fluctuate and capital budgets constrain per-unit consumables spend.
- Insulated:Double-wall construction maintains temperature stability across frozen-to-ambient cycles for sensitive media formulations.
Disposable retains volume leadership; collapsible holds the steepest expansion curve.
Material:
Cost tier stratification separates USP Class VI-certified polymers from premium borosilicate glass, with stainless steel occupying a narrowing middle ground in legacy infrastructure.
- Glass:Borosilicate reservoirs retain margin concentration in gene therapy and viral vector production where extractables profiles face heightened FDA scrutiny. European gene therapy manufacturers dual-source these formats to hedge polymer compliance uncertainty from REACH SVHC expansion.
- Plastic:Pharma-grade polycarbonate specification upgrades unwind legacy polypropylene dominance in procurement decisions. REACH phthalate alternative notifications accelerate supplier audits of additive supply chains.
- Stainless Steel:Fixed-tank formats face retrofit burdens when integrating with disposable reservoir manifolds in multi-product facilities.
- Aluminum:Lightweight metal construction serves portable field applications outside core biopharma manufacturing.
Plastic commands unit volume leadership; glass maintains the premium pricing tier.
End User:
Application maturity diverges sharply between validated biopharma manufacturing and exploratory research settings with disparate regulatory exposure.
- Fitness Enthusiasts:Consumer hydration applications fall outside the core biopharma scope of reservoir media bottle demand.
- Outdoor Adventurers:Recreational portability features do not align with aseptic fluid handling requirements.
- Office Workers:Workplace hydration segments lack the sterilization validation and extractables testing protocols governing bioprocess procurement.
- Students:Educational price sensitivity contrasts with the compliance-driven specification standards of cell culture laboratories.
None of these consumer segments register meaningful demand within the biopharma-focused reservoir media bottle market; the analysis centers on cell culture laboratories, contract manufacturing organizations, and biologics manufacturing facilities.
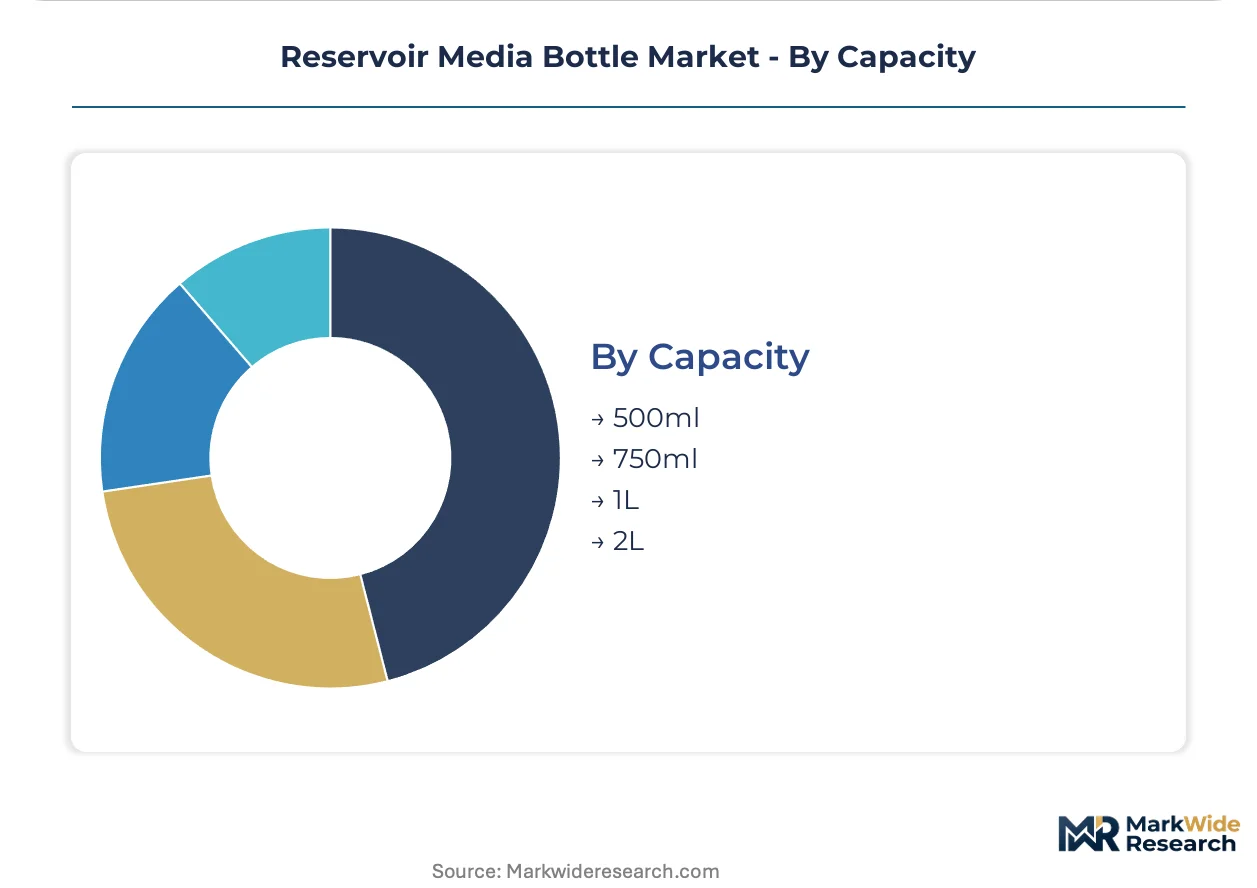
Capacity:
Volume scale determines automation compatibility and closed-system welding integration feasibility across fill-finish operations.
- 2L:Large-format reservoirs align with single-use bioreactor feed strategies and automated tube welding protocols. Contract manufacturers in the United States adopt these capacities for scale-out manufacturing models.
- 1L:Mid-range formats balance media preparation efficiency with storage footprint constraints in multi-product suites.
- 750ml:Reduced volumes serve pilot-scale process development and stability testing applications.
- 500ml:Small-format reservoirs support screening campaigns and early-stage cell line development in academic settings.
2L formats gain share fastest in commercial manufacturing; 500ml retains dominance in research-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented biologics manufacturing is reshaping reservoir media bottle trade flows, with the United States, Germany, and China posting persistent import dependence for gamma-irradiated single-use formats while specialized glass reservoir exports concentrate in Central European supply chains.
United States
FDA sterilization validation requirements and ISO 10993 biocompatibility testing are tightening material compliance standards for liquid storage vessels. The EPA's pharmaceutical manufacturing effluent guidelines are pressuring converters to validate recyclable polymer alternatives. Boston and San Diego biotech clusters are absorbing strained gamma irradiation capacity as facility construction outpaces qualified local supplier availability.
Germany
EMA Annex 1 sterile manufacturing revisions mandate closed-system fluid transfer, accelerating replacement of open-neck glass reservoirs with luer-lock closure designs. REACH SVHC candidate list expansion is forcing reformulation of plasticizer packages in polymer reservoir grades. Specialized glassworks in Bavaria and Baden-Württemberg are consolidating furnace capacity, creating single-source risk for borosilicate reservoir supply.
China
NMPA alignment with ICH Q5D standards is streamlining import qualification pathways for foreign single-use reservoir suppliers into domestic biologics facilities. Dual carbon goals under MEE oversight are pressuring polymer converters toward lower-emission manufacturing processes. Yangtze River Delta biologics parks in Shanghai and Suzhou are expanding cell culture laboratory footprints to serve export-oriented CDMO contracts.
India
CDSCO quality harmonization with international standards is accelerating qualification timelines for imported reservoir formats in vaccine manufacturing. The PLI scheme for pharmaceuticals is attracting biologics capacity to Hyderabad and Bengaluru. Contract development and manufacturing organizations in these clusters are actively seeking qualified single-use reservoir suppliers for export production.
Switzerland
Swissmedic oversight of gene therapy manufacturing is elevating extractables testing requirements for all fluid contact surfaces. Precision medicine specialization in Basel and Zurich is pulling premium borosilicate glass reservoirs for viral vector applications. The country's pharmaceutical value chain integration favors suppliers with dual glass-to-plastic manufacturing capabilities.
Reservoir Media Bottle Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized pharmaceutical glass manufacturers that command sterilization validation expertise and polymer compounding capabilities. The vendor base separates into three functional tiers: integrated material science conglomerates with resin-to-device vertical control, specialized glass converters with borosilicate furnace assets, and regional polymer fabricators serving price-sensitive academic markets. Dominant competitive moves include backward integration into USP Class VI resin compounding and strategic partnerships with gamma irradiation service providers to secure sterilization capacity.
Among diversified packaging specialists, Amcor plc and Berry Global Group exemplify scale-driven archetypes with polymer conversion breadth spanning multiple healthcare formats. Schott AG occupies a distinctive position as a furnace-capable glass converter serving extractables-sensitive gene therapy applications. These three entities represent the competitive spectrum from commodity polymer throughput to premium thermal shock-resistant glass reservoirs, with each anchoring different procurement decision criteria across biopharma manufacturing tiers.
| Leading Market Players |
|---|
| Gerresheimer AG |
| West Pharmaceutical Services |
| Schott AG |
| Corning Incorporated |
| Berry Global Group |
| Amcor plc |
| Owens-Illinois |
| Drug Plastics Group |
| Alpla Werke Alwin Lehner GmbH & Co KG |
| Others |
Value Network & Pricing Analysis
Collapsible fluoropolymer film reservoirs displacing rigid polycarbonate formats in large-volume storage are simultaneously redrawing supply geography toward German and United States contract manufacturing clusters while compressing unit economics through elimination of CIP/SIP infrastructure from facility designs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the reservoir media bottle market. Pricing stratifies across gamma-irradiated premium grades, standard USP Class VI polymer formats, and economy reusable polycarbonate tiers used in academic settings. Price differentiation hinges on extractables certification depth and volume scale commitments, with biopharma manufacturers showing lowest sensitivity due to validation cost avoidance. Cost compression in standard polymer grades is intensifying because benzene and bisphenol-A feedstock volatility squeezes converter margins on fixed-price contracts.
Supply Chain Analysis
Strategic stockpiling of gamma-irradiated disposable reservoirs dominates procurement behavior as sterilization service providers in the United States operate above 85 percent utilization. Manufacturing concentrates in Germany, the United States, and China, with borosilicate glass furnace capacity consolidating in Bavaria and Baden-Württemberg. Raw material dependencies center on pharma-grade polycarbonate resin, fluoropolymer films, and borosilicate glass tubing. Single-source vulnerability in European glassworks creates supply risk for gene therapy manufacturers. Distribution runs through direct polymer compounding relationships that displace distributor intermediaries in high-volume biopharma contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use fluid handling architectures are disrupting legacy reusable formats across biopharma manufacturing, with EMA Annex 1 sterile manufacturing revisions mandating closed-system designs that accelerate format substitution.
For Market Incumbents: Shield premium positioning by securing captive gamma irradiation capacity through partnerships with sterilization service providers in United States coastal biotech clusters. Deepen backward integration into USP Class VI resin compounding to defend margin compression from polycarbonate feedstock volatility. Fortify against collapsible fluoropolymer substitution by embedding tube welding automation into reservoir closure designs.
For New Entrants and Emerging Players: Lead with extractables testing services as a wedge capability, addressing the ISO 10993-18 analytical chemistry scarcity that extends material qualification timelines for new polymer entrants. Target India CDMO expansion in Hyderabad and Bengaluru where export-oriented biologics production strains qualified local supplier capacity. Position biodegradable polymer validation capabilities to capture EPA pharmaceutical effluent compliance pull.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized glass converters with borosilicate furnace assets serving gene therapy viral vector applications, as these command durable margin concentration from FDA extractables scrutiny. Long-term viability over the analysis window rests on dual glass-to-plastic manufacturing capabilities that hedge polymer compliance uncertainty from REACH SVHC expansion. Watch for China NMPA import qualification pathway acceleration as signal of foreign supplier penetration inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma Irradiation Capacity Partnership | Secures sterilization throughput for disposable reservoir lots amid 85 percent-plus utilization at United States service providers. |
| USP Class VI Resin Compounding Integration | Captures margin from polymer specification upgrades unwinding legacy polypropylene dominance in procurement decisions. |
| Closed-System Welding Automation | Enables reservoir-to-bioreactor fluid transfer without manual intervention under EMA Annex 1 sterile manufacturing revisions. |
| Biodegradable Polymer Validation Program | Positions polylactic acid and polyhydroxyalkanoate alternatives for EPA pharmaceutical manufacturing effluent compliance. |
| India CDMO Supply Qualification | Captures export-oriented biologics production expansion in Hyderabad and Bengaluru biologics clusters. |
Research Methodology
A spread of perspectives from bioprocess engineers, regulatory affairs leads at biopharma manufacturers, polymer resin compounders, and gamma irradiation service operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA scientific advice letters, and USP plastic extractables documentation. Customs records tracking polycarbonate and fluoropolymer resin trade flows provided demand-side triangulation. Bottom-up facility capacity assessments and top-down biologics manufacturing expansion forecasts were reconciled to establish volume baselines.
Segmentation dimensions modeled span disposable versus collapsible versus reusable product architectures, USP Class VI polymer versus borosilicate glass versus stainless steel material grades, and 2L versus 1L versus sub-liter capacity tiers across the projection horizon. CAGRs were derived from regression analysis of historical biologics capacity buildouts against reservoir procurement ratios. Forecast inputs incorporated gene therapy viral vector production pipeline visibility and China NMPA ICH Q5D alignment implementation pace.
The analysis sits within stated boundaries; outcomes outside sustained biopharma facility construction in United States coastal clusters and German glassworks consolidation would require recalibration. Forecasts reflect assumptions regarding gamma irradiation capacity expansion and REACH SVHC candidate list trajectory. Revision becomes warranted when EPA biodegradable polymer certification timelines or China dual carbon manufacturing constraints cross thresholds that alter import qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Europe Soft Drinks Packaging Market