
 Blow Molded Plastics Market | 2026-2036
Blow Molded Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Blow Molded Plastics Market Intelligence
The shift towards lightweighting and using recycled content in container packaging is realigning buyer choice away from traditional materials. Berry Global leverages its manufacturing scale to supply diverse end markets from automotive to healthcare. Amcor differentiates through its focus on innovative and sustainable packaging solutions, particularly for the fast-moving consumer goods sector.
Blow molded plastics are hollow plastic parts formed by inflating a heated plastic tube, or parison, inside a mold cavity. This process is essential for creating seamless containers and complex shapes. High-Density Polyethylene (HDPE) and Polyethylene Terephthalate (PET) lead material consumption due to their cost-effectiveness and recyclability. Extrusion Blow Molding is standard for large parts like industrial drums, while Injection Blow Molding serves high-precision applications such as personal care bottles.
Regulations such as the US FDA's rules for food-contact materials and Europe's REACH framework dictate material safety and composition. In China, compliance with national GB standards is mandatory for market access, influencing raw material choices. Navigating these varied international standards for recycled content and chemical safety is a critical capability for producers.
Market Dynamics
The central tension shaping the blow molded plastics market is the dual mandate for sustainability and performance. Regulatory frameworks like the EU Green Deal are forcing the integration of recycled content, while end-markets like pharmaceuticals demand uncompromised material purity and barrier properties.
Growth Catalysts
- Sustainability Mandates:Regulatory pressure, particularly from the EU Green Deal and similar initiatives, compels brands to increase the percentage of post-consumer recycled (PCR) content in packaging, directly stimulating demand for compliant blow molded products.
- Pharmaceutical Packaging:The pharmaceutical industry's need for lightweight, shatter-resistant, and sterile containers for liquids, solids, and biologics provides a high-value, non-cyclical demand stream for precision blow molded bottles and vials.
- Indian Consumer Market:India’s expanding middle class and rapid urbanization are accelerating demand for packaged foods, beverages, personal care items, and industrial chemicals, all of which rely heavily on blow molded containers.
Market Restraints
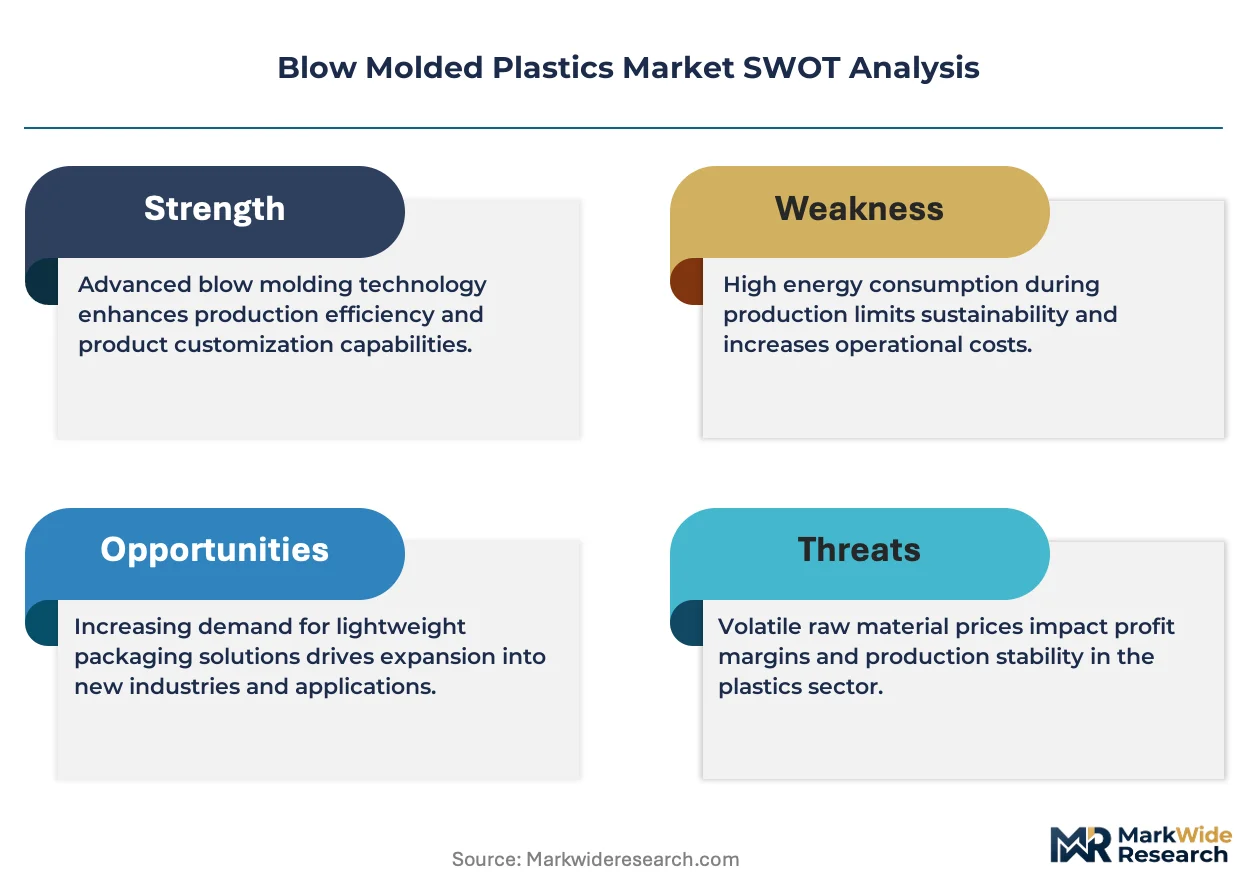
- Resin Price Volatility:The market is highly sensitive to fluctuations in the price of petroleum-based raw materials, specifically HDPE and PET, which can compress manufacturer margins and create pricing instability for buyers.
- Recycled Content Limitations:Incorporating high percentages of recycled material can compromise the structural integrity, color consistency, and aesthetic quality of final products, posing a technical barrier for premium applications.
- Divergent Regulations:Navigating the different requirements for food-contact plastics between jurisdictions, such as the US FDA's rules versus the European Food Safety Authority (EFSA) standards, adds complexity and cost to global supply.
Strategic Opportunities
- Automotive Lightweighting:Opportunities exist in producing complex, hollow automotive components, such as air ducts and fluid reservoirs for both internal combustion engine and electric vehicles, to reduce overall vehicle weight and improve efficiency.
- Advanced Barrier Layers:Developing and scaling co-extrusion processes that incorporate advanced barrier layers in PET containers creates opportunities in packaging for oxygen-sensitive products like beer, wine, and dairy.
- Southeast Asian Expansion:Beyond India, markets in countries like Indonesia and Vietnam present significant growth potential as rising disposable incomes drive consumption of fast-moving consumer goods requiring plastic packaging.
Industry Challenges
- Capital Investment Hurdles:The high upfront capital expenditure required for modern, energy-efficient, and high-speed blow molding machinery presents a significant barrier to entry and expansion for smaller producers.
- Feedstock Traceability:Establishing and documenting a compliant chain of custody for recycled feedstocks is a significant operational challenge, essential for verifying content claims to meet regulatory standards like those in the EU.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow Molded Plastics Market |
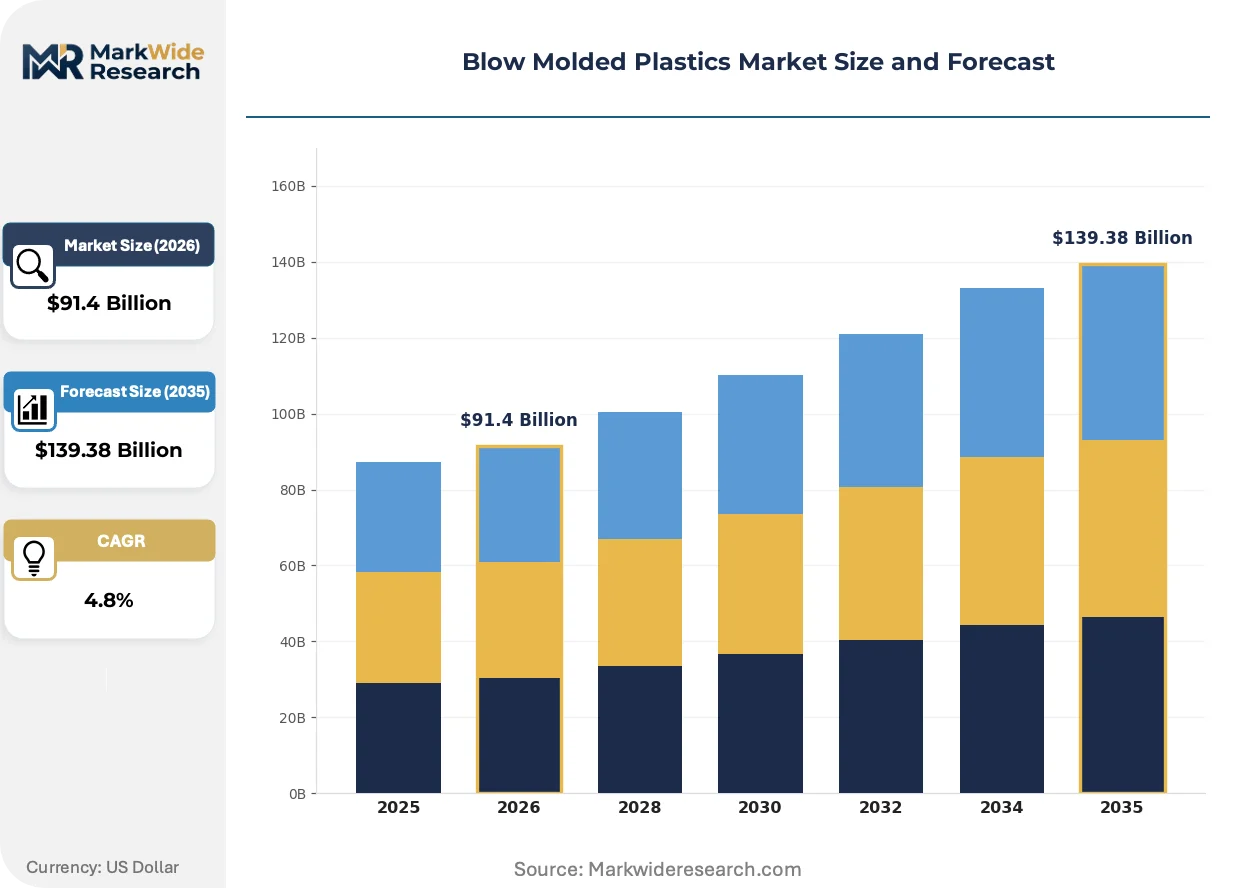
| Market Size in 2026 | $91.4 Billion |
| Market Size in 2035 | $139.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plastic Type: Polyethylene Terephthalate, High-Density Polyethylene, Polyvinyl Chloride, Low-Density Polyethylene, Polypropylene, Polystyrene Application: Container Packaging, Automotive Components, Personal Care Bottles, Industrial Drums, Household Products, Agricultural Tanks Manufacturing Technology: Extrusion Blow Molding, Injection Blow Molding, Stretch Blow Molding, Co-extrusion Blow Molding, Continuous Blow Molding End User Industry: Fast-Moving Consumer Goods, Vehicle Manufacturers, Chemical Storage, Construction Tools, Pharmaceutical Packaging, Food Processing |
| Companies Covered | Berry Global, Amcor, Graham Packaging, ALPLA, Plastipak Holdings, Comar, Magna International, IAC Group, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow Molded Plastics Market Strategic Shifts & Innovations
Material science advancements and the digitalization of manufacturing processes are defining the next generation of blow molded products. Innovations focus on enhancing sustainability without sacrificing performance, driven by both regulatory pressure and consumer preference for eco-conscious packaging solutions.
Digital twin simulation allows for the virtual modeling of the blow molding process, from parison formation to final part cooling. High-value sectors such as automotive and medical device manufacturing are adopting this technology to shorten development timelines and reduce material waste from physical trials. This capability is rewriting the economics of creating intricate, custom blow molded components at lower volumes.
The US EPA's evolving guidance on advanced recycling technologies is creating a new pathway for converting mixed plastic waste into virgin-quality resins. This regulatory development provides an alternative to mechanical recycling, enabling the production of food-grade PCR content. The beverage and personal care sectors are closely monitoring these policies to secure future supplies of FDA-compliant recycled materials.
A clear behavioral shift among brand owners involves specifying multi-layer containers designed for specific performance attributes. This change disrupts traditional supply chains focused on single-resin products and creates demand for converters with sophisticated co-extrusion blow molding capabilities. This trend is most pronounced in the European agrochemical and food sectors, where barrier protection is paramount.
Blow Molded Plastics Market Segmentation
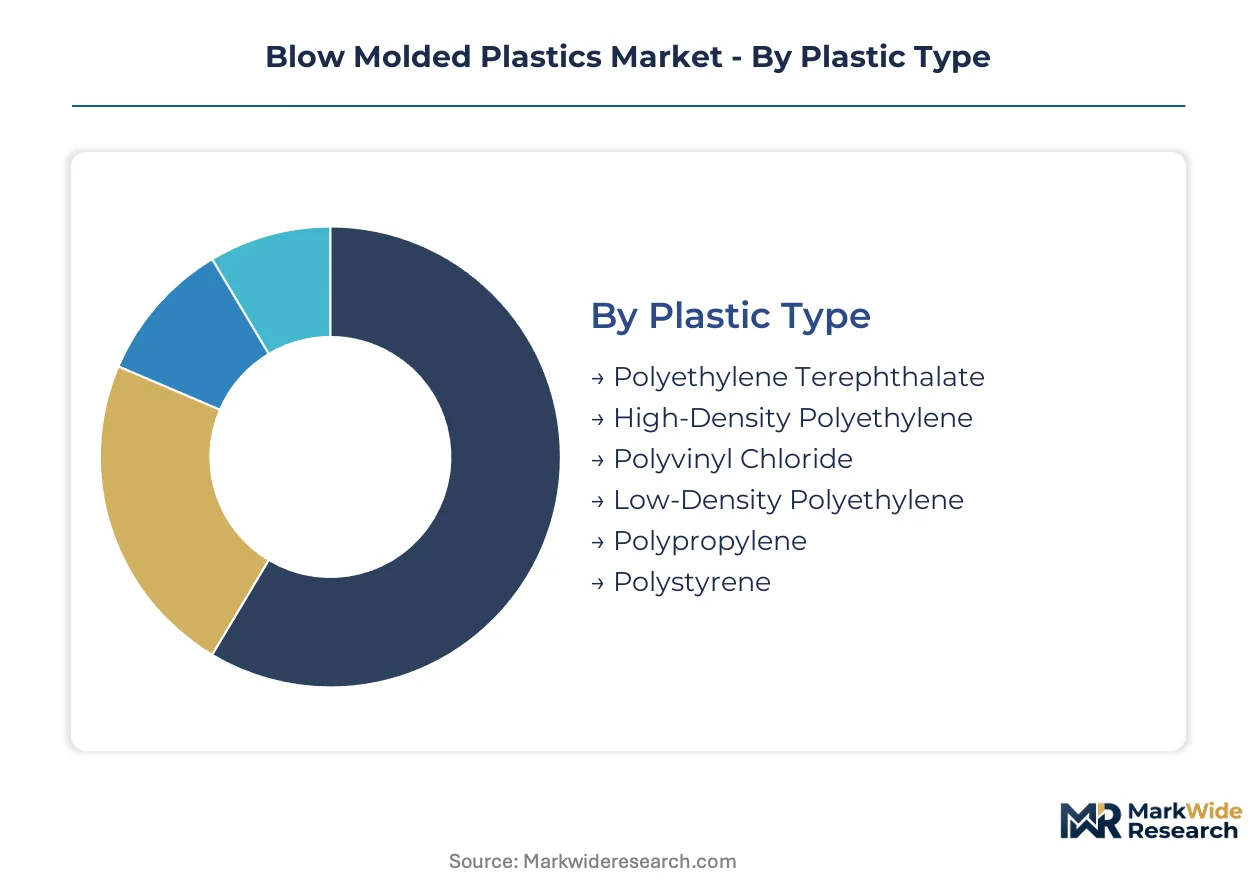
The blow molded plastics market is diverse, with segmentation crucial for understanding the varied material requirements, manufacturing processes, and end-user demands. Each segment reflects distinct challenges and opportunities, influencing product development and strategic investments across the value chain.
Plastic Type:
The choice of plastic type for blow molded products often balances material standardization for cost efficiency against customization needs for specific performance attributes.
- Polyethylene Terephthalate:This transparent, lightweight thermoplastic offers excellent barrier properties against gases and moisture, making it ideal for beverage bottles and food containers. Demand for PET is concentrating in the pharmaceutical packaging sector due to its clarity and recyclability.
- High-Density Polyethylene:HDPE is a durable and chemical-resistant polymer widely used for milk jugs, detergent bottles, and industrial drums. Its cost-effectiveness and good processability drive its high consumption in consumer goods and chemical storage applications.
- Polyvinyl Chloride:PVC is known for its rigidity and chemical resistance, finding applications in specific industrial and medical containers requiring robust material integrity.
- Low-Density Polyethylene:LDPE offers flexibility and impact strength, primarily used for squeeze bottles, liners, and some agricultural films where pliability is essential.
- Polypropylene:PP provides high heat resistance and stiffness, making it suitable for hot-fill containers, automotive fluid reservoirs, and medical device packaging.
- Polystyrene:PS is a rigid, transparent plastic often used for clear food containers and medical packaging where visual appeal and stiffness are important.
Most installed capacity flows through High-Density Polyethylene. Expansion is steepest in Polyethylene Terephthalate.
Application:
Application segments differentiate by the cost sensitivity and performance demands of the final product, from commodity containers to specialized components.
- Container Packaging:This broad category includes bottles, jars, and other hollow forms for beverages, food, and household products. Demand for container packaging is high in India's expanding consumer goods market, driven by urbanization and rising disposable incomes.
- Automotive Components:Blow molded plastics form complex, hollow parts such as air ducts, fluid reservoirs, and spoilers for vehicles. The push for automotive lightweighting in both internal combustion engine and electric vehicles is a significant driver in this segment.
- Personal Care Bottles:This segment encompasses bottles for shampoos, lotions, and cosmetics, prioritizing aesthetics, ergonomic design, and material compatibility with diverse formulations.
- Industrial Drums:Large-volume containers for chemicals, oils, and other industrial liquids require robust construction and chemical resistance, often using HDPE.
- Household Products:This includes packaging for cleaning supplies, gardening products, and other consumer household items, balancing cost, durability, and child-safety features.
- Agricultural Tanks:Blow molded tanks store water, fertilizers, and pesticides for agricultural use, demanding UV resistance and chemical inertness.
Container packaging applications generate the largest volumes. Automotive components require the most stringent material specifications.
Manufacturing Technology:
Different manufacturing technologies are optimized for specific application requirements, from large industrial parts to intricate precision components.
- Extrusion Blow Molding:This versatile process inflates a parison inside a mold, suitable for high-volume production of diverse shapes, including large industrial drums and bottles. This technology is standard for producing large parts and offers design flexibility.
- Injection Blow Molding:Known for producing high-precision, dimensionally stable containers with excellent neck finishes, primarily for personal care bottles and pharmaceutical vials. This method ensures consistent wall thickness and minimal material waste for exacting applications.
- Stretch Blow Molding:This technology enhances the barrier properties and strength of PET containers by stretching the preform before final blowing, common for beverage bottles.
- Co-extrusion Blow Molding:This advanced process creates multi-layer structures within a single part, incorporating barrier layers for oxygen-sensitive products like food and chemicals.
- Continuous Blow Molding:A high-speed variant of extrusion blow molding, often used for smaller, high-volume containers where efficiency is paramount.
Extrusion blow molding remains the most versatile method for diverse forms. Co-extrusion blow molding is gaining traction for advanced barrier solutions.
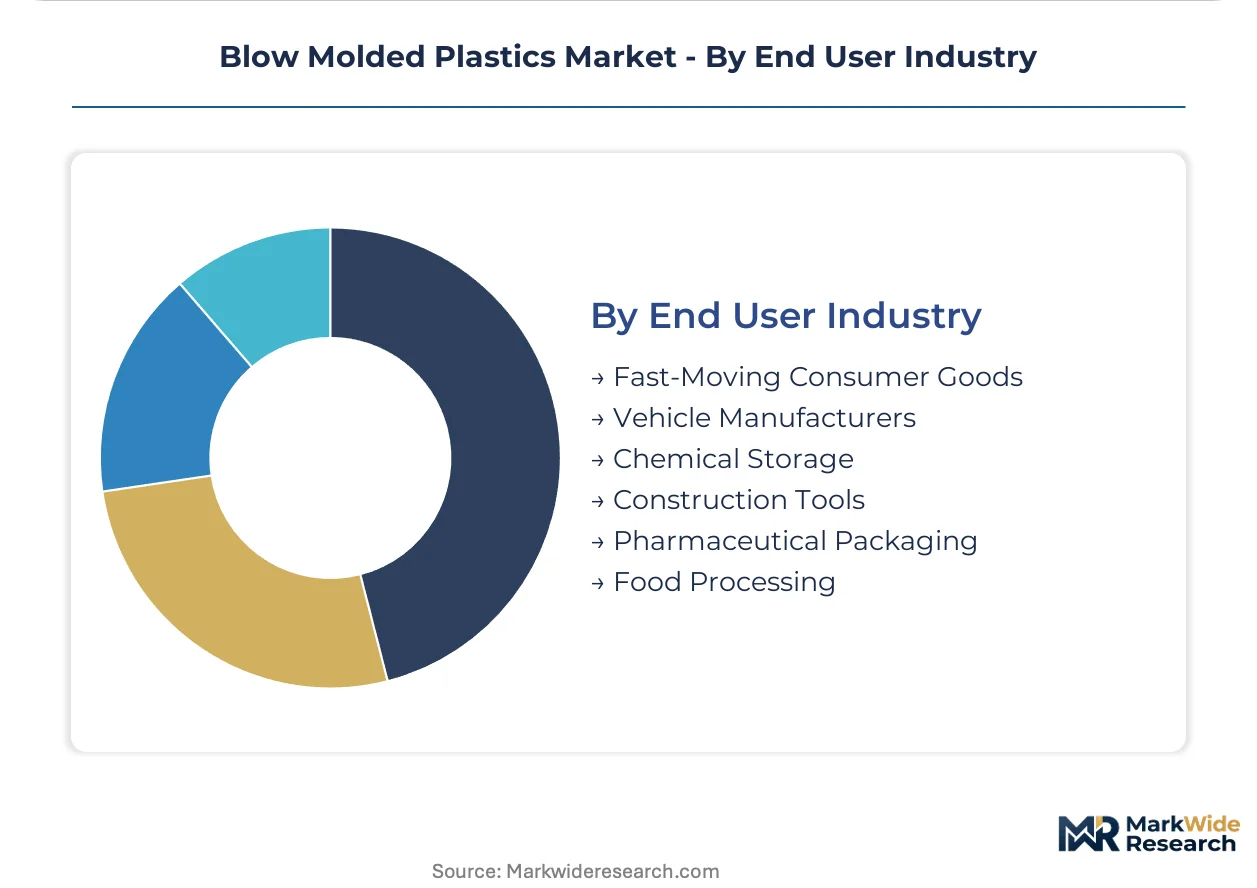
End User Industry:
End-user industries present varied demands, ranging from high-volume, low-margin packaging to specialized, high-margin industrial applications.
- Fast-Moving Consumer Goods:This segment includes food, beverages, and personal care products, characterized by high volume, competitive pricing, and a strong emphasis on consumer appeal. The Indian consumer market drives significant demand here.
- Pharmaceutical Packaging:This sector demands sterile, precise, and highly regulated containers for medicines and biologics, prioritizing material purity and barrier properties. Regulations from the US FDA and Europe's EMA dictate material choices.
- Vehicle Manufacturers:This industry uses blow molded parts for automotive fluid systems, air ducts, and other components, focusing on lightweighting and durability.
- Chemical Storage:Industrial chemicals require robust, chemically resistant containers, often large drums or tanks, adhering to stringent safety regulations.
- Construction Tools:Blow molded cases and components are used for power tools and other construction equipment, providing impact resistance and ergonomic design.
- Food Processing:This industry relies on blow molded containers for various food products, emphasizing food safety, shelf-life extension, and compliance with regulations like those from EFSA.
Fast-moving consumer goods drive significant market volume. Pharmaceutical packaging applications command premium pricing due to strict regulatory demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The blow molded plastics industry, initially scaled in industrial manufacturing hubs, has evolved into a global enterprise. This transformation supports diverse end-use sectors, from automotive components to pharmaceutical packaging. Regulatory frameworks and local demand dynamics significantly influence regional market trajectories.
United States
United States demand for blow molded plastics stems from its robust pharmaceutical and automotive sectors. The US FDA regulations for food-contact materials and medical devices dictate material purity and safety standards. Automotive clusters in Michigan drive innovation for lightweight components.
Germany
Germany's market for blow molded plastics is driven by its advanced automotive industry and chemical manufacturing base. Europe's REACH framework and the EU Green Deal mandate increased recycled content and chemical safety. Chemical parks in Bavaria and North Rhine-Westphalia concentrate industrial drum production.
China
China's vast consumer goods market and expanding industrial sector fuel significant demand for blow molded containers. Compliance with national GB standards is mandatory for market access and influences raw material choices. Manufacturing hubs in the Yangtze River Delta region produce high volumes of packaging.
India
India's rapidly expanding middle class and urbanization accelerate demand for packaged foods and personal care items. The Bureau of Indian Standards (BIS) governs product quality and safety for various plastic applications. Metropolitan areas like Mumbai and Delhi-NCR are centers for consumer goods packaging production.
Japan
Japanese manufacturers prioritize precision blow molded components for automotive and medical device applications. The Ministry of Economy, Trade and Industry (METI) promotes advanced material research and sustainable manufacturing practices. The Kanto region hosts numerous high-tech plastics conversion facilities.
Blow Molded Plastics Market Key Industry Players
Premium-margin players sit above commodity-margin players across the capability spectrum, influencing market structure. The blow molded plastics market exhibits a tiered competitive landscape, with large integrated manufacturers alongside specialized niche players. Strategic archetypes include global packaging conglomerates, automotive component specialists, and regional custom molders. Competitive moves frequently involve capacity expansion to meet demand and strategic partnerships for sustainable material sourcing.
Global packaging conglomerates, such as Berry Global, leverage extensive manufacturing scale to serve diverse end markets from automotive to fast-moving consumer goods. These firms often differentiate through innovative and sustainable packaging solutions, including advanced barrier layers and high recycled content. Amcor, another prominent player, occupies a position focused on consumer goods and pharmaceutical packaging, exemplifying a strategy centered on sustainability and design. Graham Packaging, a specialized entity, represents a strong presence in the container packaging segment, highlighting efficiency and specific application performance across various industries, including food and household products.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Graham Packaging |
| ALPLA |
| Plastipak Holdings |
| Comar |
| Magna International |
| IAC Group |
| Dow |
| Others |
Cost & Logistics Intelligence
Blow molding technicians in high-wage regions like Germany and Japan drive labor-cost differentials, directly influencing pricing-tier spreads for specialized components. These regional labor dynamics significantly affect final cost structures.
Pricing Analysis
Contract-based long-term offtake agreements dominate the blow molded plastics market, particularly for high-volume applications. Material quality grade, especially for food-contact and pharmaceutical uses, and volume scale represent key price differentiation drivers. Pricing softness in commodity segments stems from intense competition among regional manufacturers. Fast-moving consumer goods manufacturers are highly price-sensitive, while pharmaceutical packaging buyers prioritize material purity and regulatory compliance.
Supply Chain Analysis
Raw material supply for blow molded plastics draws heavily from petrochemical production hubs in China, the Middle East, and North America. The market relies significantly on High-Density Polyethylene (HDPE) and Polyethylene Terephthalate (PET) resins, which are petroleum-based inputs. Commodity price volatility for these resins presents a significant structural risk for manufacturers. Distribution runs through a fragmented network of resin distributors, compounders, and direct sales channels to converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blow molded plastics market acts as a regulatory compounder, with frameworks like the EU Green Deal driving demand for increased recycled content. This regulatory push reshapes material choices and manufacturing processes across the industry.
For Market Incumbents:Extend co-extrusion blow molding capabilities to offer advanced barrier solutions, mitigating the threat from alternative packaging materials. Consolidate regional manufacturing footprints to optimize logistics and reduce operational costs. The shift towards increased recycled content poses a technical challenge for maintaining product integrity. Incumbents should invest in advanced recycling technologies to secure a captive supply of FDA-compliant recycled materials.
For New Entrants and Emerging Players:The price-point gap between premium pharmaceutical packaging and economy consumer goods containers offers opportunities for specialized players. New entrants should target the personal care bottle segment in Southeast Asian markets like Indonesia and Vietnam. Focus on high-precision injection blow molding for niche medical device components. Differentiate through rapid prototyping and digital twin simulation services for custom part development.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional custom molders with established client bases and specialized machinery. The market demonstrates long-term viability driven by essential consumer and industrial applications. Target firms with robust intellectual property in co-extrusion or advanced barrier technologies. Monitor the increasing adoption rates of advanced recycling technologies as an inflection indicator for feedstock security.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume for high-demand consumer goods in India. |
| Green Manufacturing Transition | Aligns operations with EU Green Deal mandates for recycled content. |
| Long-term Supply Agreement | Secures stable supply of petroleum-based resins amidst price volatility. |
| Product Launch | Introduces new advanced barrier containers for oxygen-sensitive products. |
| Geographic Manufacturing Footprint | Establishes production facilities in Southeast Asian growth markets. |
Research Approach
Bottom-up end-use application modeling reconciled against top-down raw material supply tracking forms the analytical core for this study. Primary interviews with plant managers, procurement leads, and R&D directors across the value chain informed demand drivers. Secondary validation drew from customs data, industry association reports, and regulatory filings. This dual approach ensures robust market sizing and forecasting.
An input-output matrix links raw material consumption to finished product output across the analysis window. Segmentation dimensions modeled include plastic type, application, manufacturing technology, and end-user industry, along with regional regulatory frameworks. Compound annual growth rates were derived by analyzing historical trends and projected economic indicators. Forecast inputs include anticipated shifts in recycled content mandates and petroleum feedstock prices.
Caveats apply where significant shifts in global petrochemical supply or major regulatory changes could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements in recycling and stable geopolitical conditions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Asia Pacific Plastic Bottles Market