
 Large Blow Molded Products Market | 2026-2036
Large Blow Molded Products Market Size, Share, and Industry Trends Forecast 2026-2036
Large Blow Molded Products Market Outlook
Automotive lightweighting is repositioning large blow molded products toward structural fuel-tank and air-duct applications. Berry Global leverages captive resin compounding and North American plant density to dominate automotive fuel-system supply. Greiner Packaging anchors European demand through specialized technical blow molding for HVAC housings and fluid reservoirs. Sidel competes in high-volume packaging with stretch-blow and extrusion-blow hybrid lines serving beverage and industrial container markets.
Large blow molded products are hollow plastic forms exceeding 20 liters in volume, produced by extruding molten thermoplastic into a parison and inflating it within a cooled mold cavity to achieve precise wall-thickness distribution and dimensional stability. These parts serve primarily as fluid containment vessels, protective housings, and structural components where weight reduction and corrosion resistance outweigh metal alternatives. Containers lead product-type revenue due to pervasive use in chemical and food-grade bulk packaging, while automotive components represent the fastest-expanding segment as OEMs pursue gram-per-mile emission reductions. Polyethylene occupies the dominant material position by tonnage because of its impact resistance and chemical inertness, though polypropylene is displacing it in under-hood applications requiring higher thermal tolerance.
The US EPA tailpipe emission standards and NHTSA corporate average fuel economy rules directly shape automotive blow molded content by mandating lighter vehicle architectures. Europe's REACH chemicals regime and F-Gas Regulation restrict certain polymer additives and blowing agents, redirecting formulation R&D toward compliant catalytic systems and physical foaming. China's GB standards and MIIT energy-efficiency directives enforce recycled-content thresholds in industrial packaging, tightening material traceability requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded tooling investments and qualify products for multiple certification schemes simultaneously.
Market Dynamics
Automotive lightweighting mandates from the US EPA and NHTSA are forcing HDPE and PP substitution for metal fuel tanks and air ducts, compressing design cycles and rewiring tier-1 procurement specifications across OEM supply chains.
Growth Catalysts
- US EPA tailpipe standards:Gram-per-mile emission targets accelerate blow molded fuel-system adoption as OEMs shed metal weight from vehicle architectures.
- China's industrial packaging belt:GB standards enforcing recycled-content thresholds in chemical bulk containers tighten material traceability and expand technical blow molding demand.
- Physical foaming R&D:REACH and F-Gas Regulation restrictions on chemical blowing agents redirect formulation investment toward compliant catalytic systems and nitrogen-based processes.
Market Restraints
- Resin price volatility:HDPE and PP feedstock costs track naphtha and natural gas liquids, exposing converters to margin compression when olefin spreads widen.
- Tooling concentration in Germany:Precision mold fabrication for complex automotive ducts clusters with specialized suppliers in Baden-Württemberg, creating single-source vulnerability.
- Metal substitution limits:Structural load-bearing chassis components resist polymer conversion due to creep resistance and crash-safety certification barriers.
Strategic Opportunities
- Underpenetrated HVAC housings:India's automotive corridor shows low technical blow molding penetration for climate-control modules, presenting first-mover expansion potential.
- EU Green Deal circularity mandates:Recycled-content quotas for industrial packaging create certified-recycled HDPE premium tiers and closed-loop service models.
- 3D-printed mold cores converging with simulation:Rapid tooling iteration for low-volume automotive prototypes compresses development timelines and opens specialty contract manufacturing.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and GB standard compliance requires parallel testing protocols that strain quality-assurance bandwidth.
- Parison programming expertise gap:Advanced wall-thickness control for complex automotive ducts demands specialized process engineers in short supply across North American operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Blow Molded Products Market |
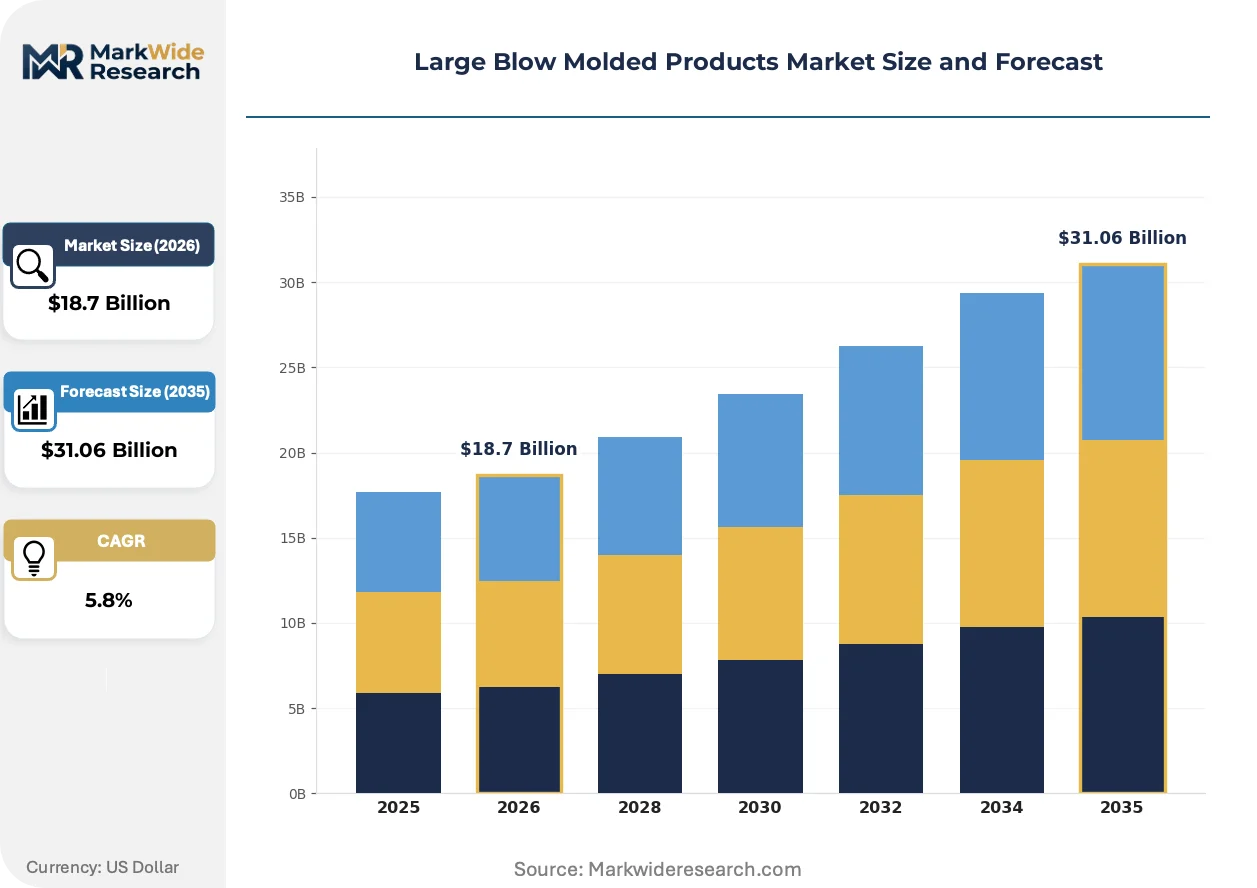
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Tanks, Housings, Automotive Components Material: Polyethylene, Polypropylene, PVC, PET End User: Packaging, Automotive, Consumer Goods, Industrial Application: Retail, E-Commerce, Agriculture, Waste Management |
| Companies Covered | Berry Global, Agri-Industrial Plastics, APEX Plastics, Comar, Plastipak, Alpla, Sidel, Greiner Packaging, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Blow Molded Products Market Strategic Shifts
Material science advances and digital manufacturing tools are compressing development cycles while regulatory chemistry restrictions force formulation reinvention across automotive and packaging applications.
Co-extrusion barrier technology is converging with fuel-permeation standards to enable monolayer tank replacement in hybrid vehicle architectures. Tier-1 suppliers in Germany's automotive corridor adopt these structures at pilot scale. The technology is converging with crash-safety simulation to reduce wall thickness without compromising burst-test performance.
REACH authorization requirements for phthalate plasticizers and specific polymer additives restrict formulation flexibility for flexible industrial containers. ECHA's SVHC candidate list expansion forces compounders toward bio-based alternatives and non-phthalate catalytic systems. European packaging converters face reformulation costs and requalification delays that favor larger integrated resin producers with captive R&D.
Specification consolidation among OEM procurement teams compresses supplier qualification cycles and elevates performance-guarantee requirements. Tier-2 blow molders face consolidation pressure as Volkswagen, BMW, and Mercedes-Benz centralize fuel-system sourcing through fewer approved vendors. This concentration is most visible in Germany's supplier ecosystem, where mid-cap specialists must demonstrate captive resin compounding or risk exclusion from platform bids.
Large Blow Molded Products Market Segmentation
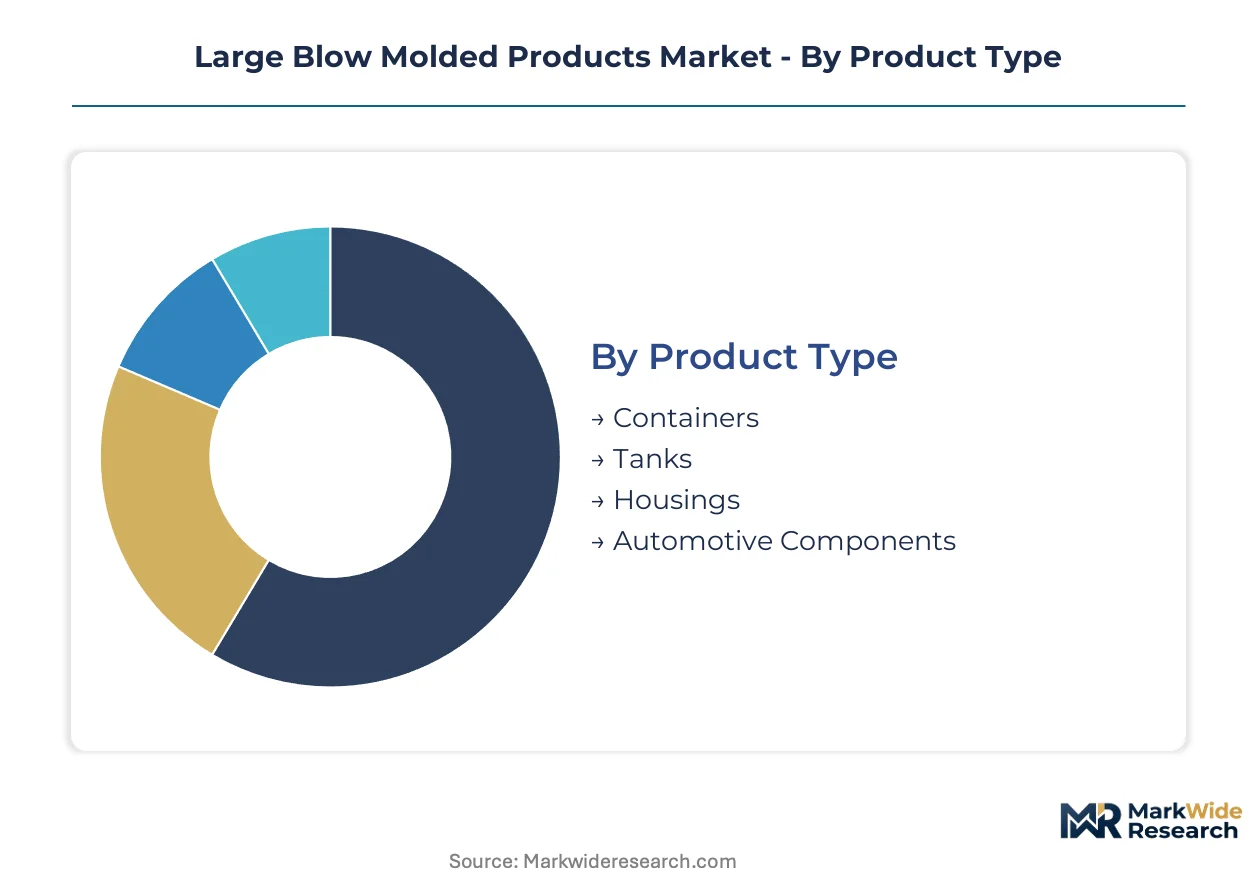
Large blow molded products span divergent performance specifications across containment, structural, and protective functions. Material selection and wall-thickness programming separate commodity packaging from automotive fuel-system applications. Understanding segment boundaries clarifies where resin substitution, barrier technology, and recycled-content mandates apply differential pressure.
Product Type:
Product architecture determines mold complexity, parison programming requirements, and post-mold assembly integration. Technical blow molding for automotive applications demands multi-layer co-extrusion capabilities absent in commodity container production.
- Containers:Bulk chemical and food-grade vessels dominate tonnage, utilizing monolayer HDPE with standard parison control. China's industrial packaging belt concentrates demand for intermediate bulk containers under GB recycled-content thresholds. REACH-compliant formulations redirect European converter investment toward certified-recycled feedstock streams.
- Automotive Components:Fuel tanks, air ducts, and fluid reservoirs require precision wall-thickness distribution and permeation barriers. Germany's automotive corridor anchors specification development for hybrid-vehicle tank architectures. US EPA gram-per-mile mandates accelerate metal substitution in under-hood applications.
- Tanks:Agricultural and industrial storage vessels emphasize UV stabilization and impact resistance over barrier properties. Demand clusters in US Midwest agricultural equipment supply chains.
- Housings:HVAC and appliance enclosures utilize PP for thermal tolerance, with India's automotive corridor showing low penetration for climate-control modules.
Mature deployment sits with Containers. Newer deployment is concentrated in Automotive Components.
Material:
Resin selection tracks thermal requirements, chemical resistance, and regulatory chemistry restrictions. Polyolefin dominance reflects cost-performance positioning, though formulation flexibility narrows under additive authorization pressures.
- Polyethylene:HDPE and LLDPE grades command volume leadership through impact resistance and chemical inertness. Automotive fuel tanks in Germany's supplier ecosystem adopt co-extrusion barrier technology to meet permeation standards. ECHA SVHC list expansion forces compounders toward non-phthalate catalytic systems.
- Polypropylene:Higher thermal tolerance enables under-hood applications where HDPE softens. China's MIIT energy-efficiency directives enforce recycled-content thresholds that PP compounders address through closed-loop service models. India's automotive corridor presents first-mover expansion potential for climate-control housings.
- PVC:Rigid formulations persist in specific agricultural and waste management applications despite REACH plasticizer restrictions limiting flexible variants.
- PET:Stretch-blow and extrusion-blow hybrid lines serve beverage and high-clarity packaging segments where barrier and aesthetic requirements converge.
Polyethylene anchors established specification regimes. Polypropylene is climbing the fastest as thermal performance requirements intensify.
End User:
Customer procurement patterns separate specification-heavy automotive qualification from volume-driven packaging tenders. Certification bandwidth and resin traceability requirements scale with end-use regulatory exposure.
- Packaging:Chemical, food, and pharmaceutical bulk containers drive standard extrusion-blow volumes. EU Green Deal circularity mandates create certified-recycled HDPE premium tiers.
- Automotive:OEM fuel-system and HVAC sourcing concentrates through fewer approved vendors, elevating performance-guarantee requirements. Volkswagen, BMW, and Mercedes-Benz procurement consolidation pressures mid-cap specialists.
- Industrial:Material handling and storage applications emphasize durability over permeation control.
- Consumer Goods:Appliance housings and recreational products utilize lower-specification grades with shorter qualification cycles.
Specification maturity concentrates in Automotive. Volume expansion is fastest in Packaging.
Application:
Application context determines distribution channel structure and service-model requirements. E-Commerce and retail diverge sharply from agricultural and waste management in delivery cadence and customization depth.
- Retail:Point-of-sale display and consumer packaging applications prioritize aesthetic finish and label adhesion.
- Agriculture:Crop protection and fertilizer containers require UV stabilization and chemical compatibility. US Midwest equipment manufacturers anchor regional demand.
- Waste Management:Roll-out carts and collection bins emphasize impact resistance and wheel-attachment structural integrity.
- E-Commerce:Protective dunnage and returnable packaging formats gain specification traction as fulfillment networks optimize cube utilization.
Established application infrastructure sits with Retail. Steepest expansion trajectory is in E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast petrochemical zones in the United States concentrate resin supply for large blow molded products, while China's industrial packaging belt and Germany's automotive corridor anchor demand-side specification development.
United States
EPA tailpipe standards and NHTSA fuel-economy mandates accelerate HDPE substitution for metal fuel tanks and air ducts. The IRA's domestic content provisions incentivize captive resin compounding near Houston and Baton Rouge. Gulf Coast petrochemical complexes supply feedstock to automotive tier-1 clusters in Michigan and Ohio.
Germany
REACH chemical restrictions and EU Green Deal circularity mandates redirect formulation R&D toward compliant catalytic systems. Baden-Württemberg's precision mold fabricators serve BMW, Mercedes-Benz, and Volkswagen procurement consolidation. The automotive corridor anchors specification development for hybrid-vehicle tank architectures.
China
MIIT energy-efficiency directives and GB standards enforce recycled-content thresholds in chemical bulk containers. The Yangtze River Delta industrial packaging belt concentrates intermediate bulk container production. NMPA traceability requirements tighten material certification for pharmaceutical packaging applications.
India
Automotive climate-control modules show low technical blow molding penetration despite expanding OEM assembly capacity. BIS standards for industrial packaging create compliance barriers for imported containers. The Chennai-Bangalore automotive corridor presents first-mover expansion potential for HVAC housing specialists.
Japan
METI carbon-neutrality roadmaps pressure resin suppliers toward bio-based feedstock integration. JIS standards for automotive fuel-system components maintain stringent permeation and crash-safety requirements. The Nagoya-Toyota supplier ecosystem concentrates precision blow molding for hybrid and electric vehicle architectures.
Large Blow Molded Products Market Competitive Environment
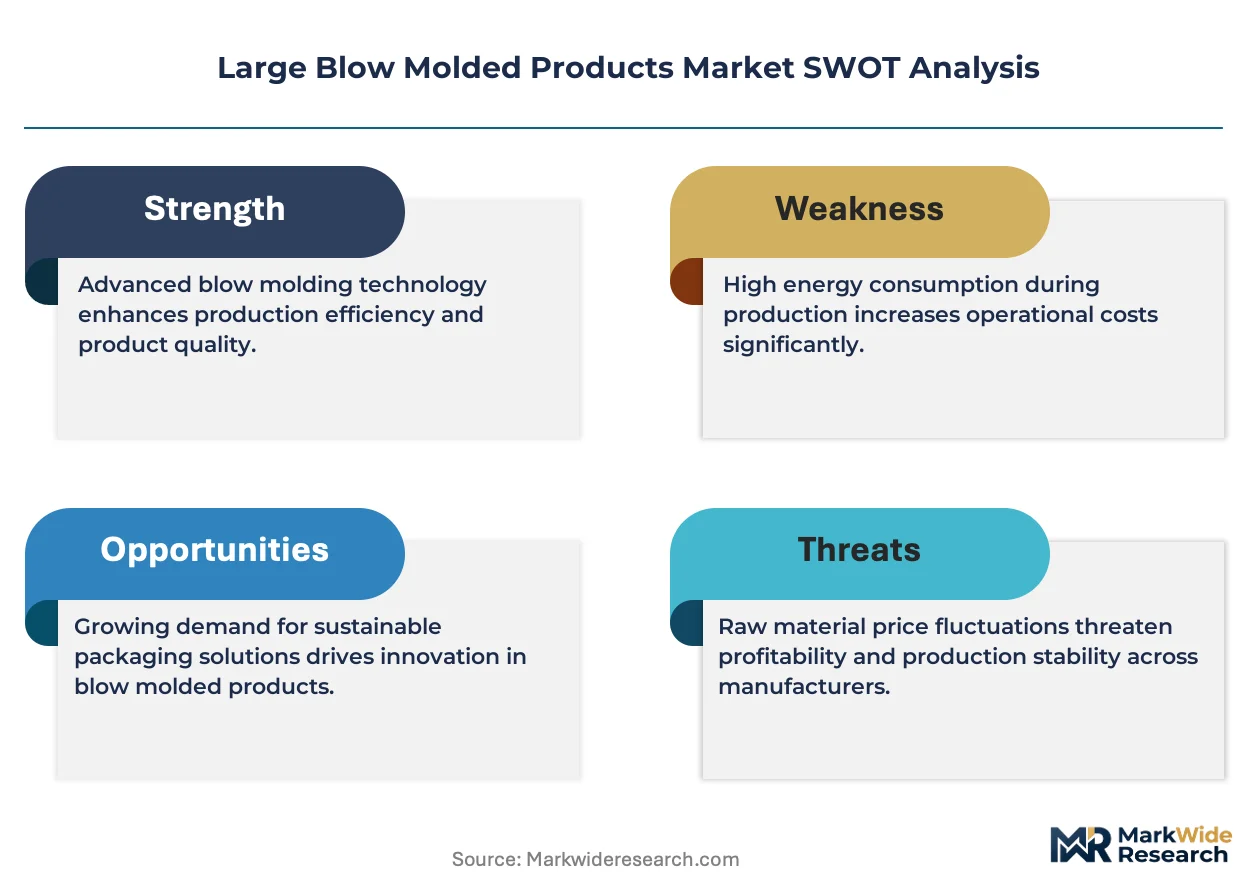
Branded specialists and contract manufacturers split share differently across segments, with integrated resin producers dominating automotive fuel-system supply while regional converters capture packaging volume. Tier-1 automotive procurement consolidation compresses supplier qualification cycles and elevates performance-guarantee requirements. Three archetypes define competitive positioning: captive resin compounders with North American plant density, European technical blow molding specialists, and high-volume packaging operators with stretch-blow hybrid capabilities. Strategic moves center on backward integration into resin compounding and geographic expansion into underpenetrated HVAC housing markets.
Among North American integrated producers, Berry Global exemplifies the captive resin compounder archetype through its Gulf Coast feedstock access and automotive fuel-system concentration. Greiner Packaging represents European technical specialization with its Baden-Württemberg mold-fabrication proximity. Sidel occupies a position at the high-volume packaging intersection, leveraging stretch-blow and extrusion-blow hybrid process capabilities.
| Leading Market Players |
|---|
| Berry Global |
| Agri-Industrial Plastics |
| APEX Plastics |
| Comar |
| Plastipak |
| Alpla |
| Sidel |
| Greiner Packaging |
| AptarGroup |
| Others |
Value Chain & Pricing Dynamics
OEM procurement consolidation around Volkswagen, BMW, and Mercedes-Benz fuel-system specifications forces tier-2 blow molders toward captive resin compounding investments or exclusion from platform bids, compressing margins for non-integrated converters while elevating pricing power for compounders with Gulf Coast feedstock access.
Pricing Analysis
Short lead-time premiums for automotive prototype tooling command 15-25% markups over standard production schedules, while spot resin purchases expose converters to olefin spread volatility. Three-tier pricing structure separates certified-recycled HDPE premiums from virgin commodity grades and economy-tier industrial packaging. Cost compression in standard containers intensifies as Chinese industrial packaging belt capacity expands. Packaging converters show highest price sensitivity due to tender-based procurement, while automotive tier-1 suppliers prioritize performance guarantees over unit cost.
Supply Chain Analysis
HDPE and PP resin supply rests on Gulf Coast petrochemical complexes in the United States, German chemical producers in Ludwigshafen, and Sinopec integrated refineries along China's Yangtze River Delta. Precision mold fabrication draws from Baden-Württemberg tooling clusters, while blow molding equipment sources from German and Italian machinery builders. Single-source vulnerability concentrates in specialized automotive duct molds from Stuttgart-area fabricators. Distribution runs through regional converter networks serving automotive OEM clusters in Michigan, Ohio, and Lower Saxony.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions and ECHA SVHC list expansion erect compliance moats favoring integrated resin producers with captive R&D, while mid-cap specialists face stranded formulation investments without reformulation capabilities.
For Market Incumbents: Anticipate procurement consolidation by deepening backward integration into resin compounding near Houston and Baton Rouge to defend automotive fuel-system share. Accelerate co-extrusion barrier technology deployment for hybrid-vehicle tank architectures before specification windows close. Counter emerging Asian packaging converters by locking long-term offtake agreements with Gulf Coast ethylene crackers. For New Entrants and Emerging Players: Digital direct-to-OEM prototyping platforms offer low-capital entry into automotive HVAC housing development for India's Chennai-Bangalore corridor. Target climate-control module supply chains where technical blow molding penetration remains under 15% versus European benchmarks. Pursue certified-recycled HDPE closed-loop service models under EU Green Deal circularity mandates as the fastest qualification pathway. For Investors and Strategic Acquirers: The window for entry favors European technical blow molding specialists with Baden-Württemberg mold-fabrication proximity and established OEM qualification. Mid-cap German tier-2 suppliers face consolidation pressure from Volkswagen procurement centralization, creating distressed acquisition targets with stranded tooling. Watch NHTSA fuel-economy mandate tightening as the signal for accelerated metal substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Gulf Coast ethylene access secures margin control against olefin spread volatility for automotive fuel-system suppliers. |
| Co-Extrusion Barrier Technology Deployment | Hybrid-vehicle tank permeation standards in Germany's automotive corridor demand multi-layer structural investment. |
| Certified-Recycled HDPE Service Models | EU Green Deal circularity mandates create premium tier separation from virgin commodity packaging competition. |
| Geographic Expansion into HVAC Housings | India's Chennai-Bangalore automotive corridor presents first-mover climate-control module penetration opportunity. |
| 3D-Printed Mold Core Convergence | Rapid tooling iteration compresses automotive prototype development timelines for low-volume specialty manufacturing. |
Study Parameters
Multi-period observation of OEM platform engineering specifications, resin price spreads, and regulatory chemistry restrictions anchored the trend analysis, supplemented by interviews with tier-1 automotive procurement managers, blow molding plant engineers, resin compounder technical directors, and precision mold fabricators in Baden-Württemberg. Secondary validation drew from EPA fuel-economy rulemakings, ECHA SVHC candidate list updates, MIIT energy-efficiency directives, customs trade data for HDPE and PP resin flows, and SEC filings from integrated resin producers. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrix modeling connected resin feedstock availability to converter capacity utilization and end-use demand segments including automotive fuel systems, industrial packaging containers, and HVAC housings. Segmentation dimensions spanned product architecture, material grade tier, end-use industry, and regional production cluster. CAGRs derived from elasticity-adjusted volume projections incorporating substitution rates for metal-to-polymer conversion and recycled-content mandate compliance timelines. Industry-specific inputs included parison programming complexity indices and permeation barrier technology adoption curves.
The model holds under stable olefin feedstock pricing and gradual regulatory tightening; deviation in abrupt REACH authorization bans or Gulf Coast hurricane disruptions would shift volume and value trajectories. A small set of triggers—NHTSA mandate acceleration, ECHA SVHC expansion scope, and Chinese dual carbon policy enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Hazardous Goods Packaging Market