
 Indonesia Plastic Packaging Market | 2026-2036
Indonesia Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plastic Packaging Market Foresight
Food-grade specification tiers is rotating toward higher-barrier multilayer structures as processors seek longer shelf life for tropical distribution. PT. Indorama Ventures Indonesia leverages its integrated PET resin-to-preform chain to sustain cost leadership across Java-based beverage accounts. Amcor Plc anchors premium healthcare and pharmaceutical blister formats through its technical film capabilities. PT Panca Budi Idaman differentiates in woven polypropylene bags for agricultural export logistics.
Indonesia plastic packaging encompasses films, containers, closures, and formed articles manufactured from thermoplastic resins through extrusion, blow molding, injection molding, or thermoforming processes, typically specified by barrier performance, seal integrity, and migration limits for food contact compliance. Its primary purpose is to protect perishable goods from humidity, oxidation, and mechanical damage across archipelago logistics. Flexible formats lead volume in snack and instant noodle wrapping where downgauging reduces material cost per unit. Rigid bottles dominate edible oils and condiments where clarity and stackability drive retail shelf appeal. PE and PP together capture the dominant material share, with linear low-density PE preferred for stretch and shrink films due to puncture resistance.
BIS-equivalent national standards and the Ministry of Environment and Forestry's waste reduction roadmaps shape material choices, pushing converters toward recyclable mono-material structures and verified recycled content claims. The Indonesian Food and Drug Administration's food contact regulations enforce migration testing protocols that favor established resin suppliers with documented compliance trails. Stakeholders must monitor how provincial plastic bag bans and emerging chemical recycling infrastructure alter feedstock economics and collection system viability.
Market Dynamics
Indonesia's Ministry of Environment and Forestry has tightened extended producer responsibility rules, forcing converters to redesign packaging formats around recyclability mandates while maintaining barrier performance for tropical distribution.
Growth Catalysts
- EPR Regulation Enforcement:The Ministry of Environment and Forestry's waste reduction roadmaps are accelerating adoption of mono-material structures among converters seeking compliance certification.
- Food Processing Expansion:Instant noodle and snack manufacturers are scaling flexible pouch volumes to serve archipelago logistics and modern retail penetration.
- Jakarta-Bandung Cluster Density:Conversion capacity concentration near Java's consumer markets reduces freight costs and enables just-in-time supply to beverage bottlers.
Market Restraints
- Resin Import Dependency:Polyethylene and polypropylene feedstock relies on regional petrochemical suppliers, exposing converters to naphtha price volatility and currency fluctuation.
- Collection Infrastructure Gaps:Provincial waste management systems lack standardized sorting protocols, undermining mechanical recycling economics and verified recycled content claims.
- Multilayer Technical Lock-in:High-barrier food specifications currently require incompatible polymer combinations that municipal recycling streams cannot process.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi and Papua present underdeveloped packaging demand as cold chain infrastructure expands for processed food distribution.
- Chemical Recycling Integration:Emerging pyrolysis facilities could unlock feedstock from contaminated flexible films currently rejected by mechanical recyclers.
- Healthcare Format Premiumization:Blister and vial demand from pharmaceutical manufacturing is creating technical film opportunities with higher margin profiles than commodity food wrapping.
Industry Challenges
- Migration Testing Bottlenecks:BPOM food contact certification timelines stretch 6-12 months, delaying new resin qualification and product launches.
- Mono-material Redesign Complexity:Reformulating barrier properties without aluminum or PET layers requires capital investment in coextrusion equipment and film metallization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plastic Packaging Market |
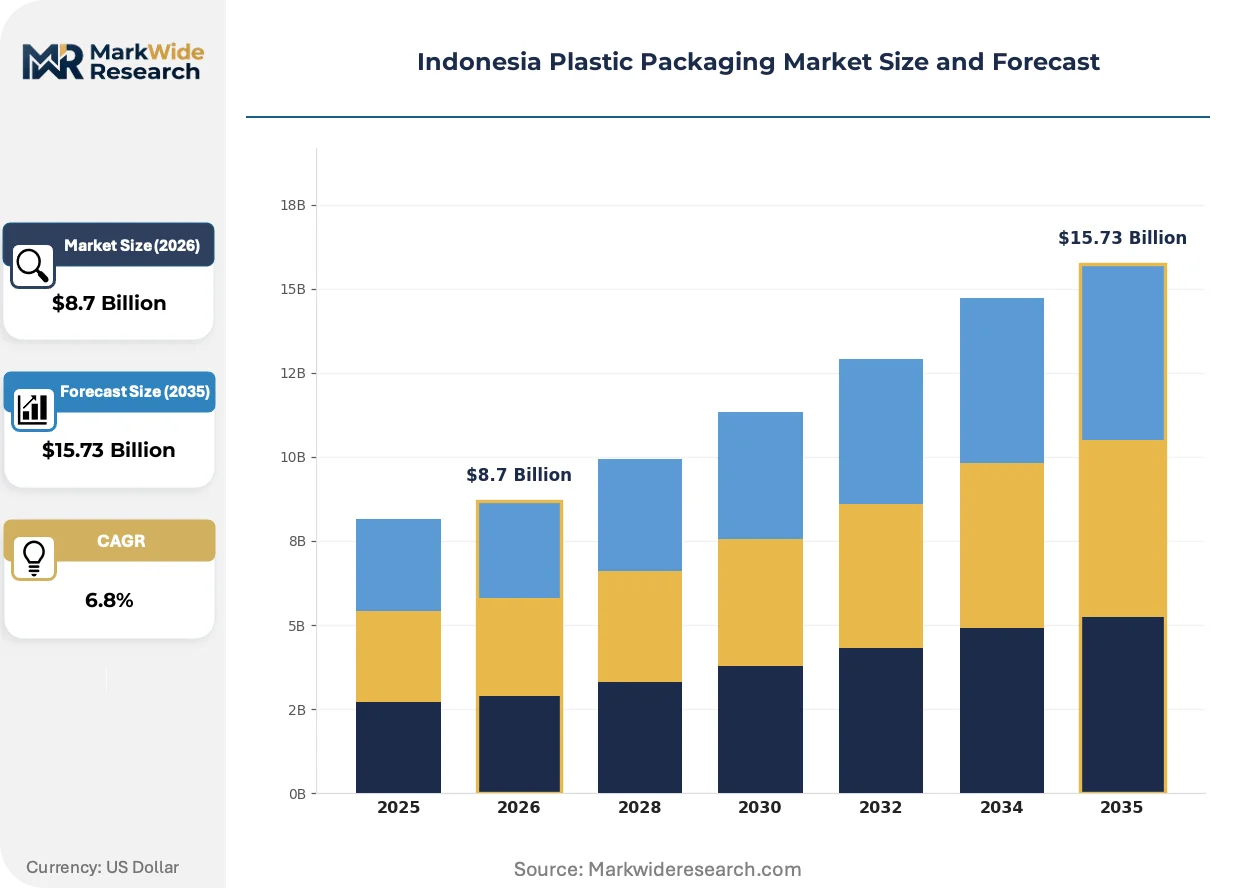
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Containers, Wraps Material: PE, PP, PVC, PS End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Form: Rigid, Flexible, Semi-Rigid, Laminated |
| Companies Covered | PT. Solusi Prima Packaging, PT Panca Budi Idaman, PT. Indorama Ventures Indonesia, PT Toppan Indonesia Printing, Amcor Plc, PT. Berlina Tbk, Indo Cap Closures, PT ARTEC PACKAGE INDONESIA, PT Indo Tirta Abadi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plastic Packaging Market Shifts & Advancements
Material science advances and regulatory compliance pressures are converging to reshape converter capabilities and customer specifications across Indonesia's archipelago logistics.
Digital printing on flexible films is fragmenting traditional rotogravure dominance in snack and confectionery wrapping. Mid-tier food brands are adopting short-run customized pouches to test regional flavor variants without plate-changeover delays. This capability is compressing minimum order quantities and enabling distributed manufacturing closer to provincial markets.
Indonesia's Ministry of Environment and Forestry has mandated recycled content verification protocols that align with BIS-equivalent national standards. Converters must now document polymer chain-of-custody from collection through reprocessing to claim recyclability credentials. Food-grade rPET flake supply remains constrained, pushing beverage brands toward deposit-return pilot programs in Jakarta and Surabaya.
Brand procurement teams are consolidating supplier panels and demanding packaging-as-a-service arrangements that transfer inventory risk to converters. Instant noodle manufacturers now specify vendor-managed stock levels at their distribution centers rather than owning raw material positions. This shift concentrates volume with integrated resin-to-film operators while squeezing standalone converters in secondary cities.
Indonesia Plastic Packaging Market Segmentation
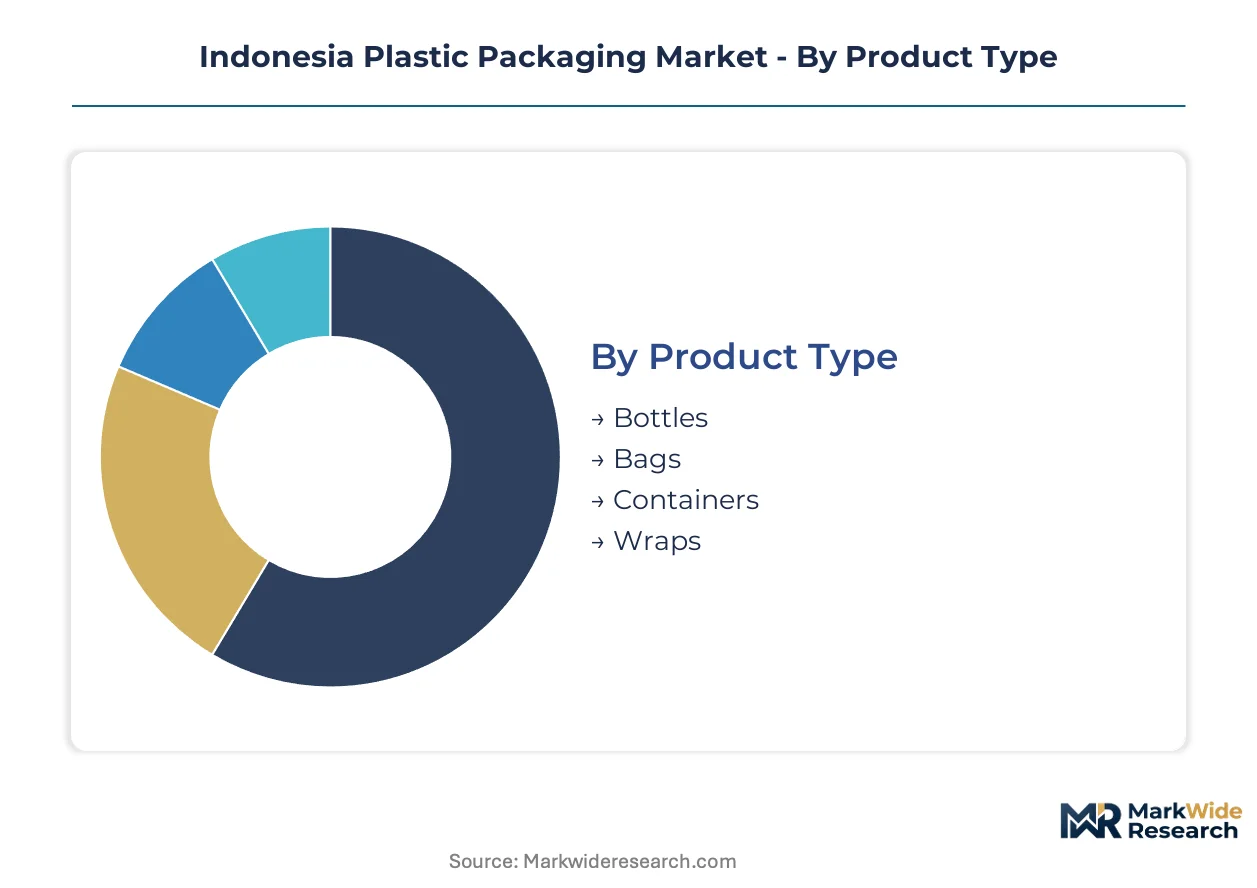
Indonesia's plastic packaging market fragments across material chemistry, structural form, and end-use specifications that determine barrier performance requirements and regulatory compliance pathways. Each segmentation axis carries distinct substitution pressures from paper, aluminum, and emerging bioplastics that reshape converter investment priorities.
Product Type:
Substitution pressure from fiber-based alternatives and aluminum formats varies sharply across container geometries, with thin-gauge wraps facing the strongest displacement threat from compostable films.
- Bottles:Blow-molded HDPE and PET containers dominate edible oil and condiment distribution across Java's retail networks. Jakarta-Bandung beverage bottlers specify preform-based PET for carbonated drinks where clarity and pressure resistance command premium placement.
- Bags:Woven polypropylene sacks anchor agricultural export logistics for palm oil and rubber shipments through Surabaya and Belawan ports. Downgauging initiatives in T-shirt and carrier bags respond to provincial plastic bag bans in Jakarta and Bali.
- Containers:Injection-molded tubs and pails serve instant noodle seasoning and dairy applications where stackability reduces distribution cube.
- Wraps:Cast and blown films wrap snack multipacks and fresh produce with modified atmosphere properties; multilayer structures face mechanical recycling incompatibility.
Bottles retain volume leadership among product types; wraps hold the steepest expansion curve as snack manufacturers scale flexible pouch formats.
Material:
Cost tier stratification separates commodity resins from specialty grades, with import-dependent feedstock economics squeezing margin structures for smaller converters outside Java.
- PE:Linear low-density grades dominate stretch film for palletized exports through Tanjung Priok. LLDPE puncture resistance specifications favor Indonesian rubber and palm oil logistics where load containment prevents transit damage.
- PP:Homopolymer and copolymer grades split between rigid containers and woven sacks. Random copolymer PP clarity grades capture yogurt and dairy cup demand from Bandung processors.
- PVC:Rigid and plasticized formulations persist in blister packs and medical tubing despite healthcare sector migration toward PETG alternatives.
- PS:Expandable polystyrene trays protect electronics shipments through Batam's free trade zone; food service disposables face Jakarta's single-use restrictions.
PE captures the dominant material position by tonnage; PP demonstrates the most rapid demand acceleration through woven sack and rigid container applications.
End User:
Application-driven specification divergence separates food-contact compliance requirements from industrial durability standards, with healthcare and electronics commanding technical premiums over commodity food wrapping.
- Food & Beverage:Instant noodle, snack, and edible oil manufacturers specify barrier films and rigid bottles for tropical shelf stability. BPOM migration testing protocols favor established resin suppliers with documented compliance trails.
- Healthcare:Pharmaceutical blister packs and medical device pouches demand cleanroom film conversion capabilities with particulate contamination controls.
- Consumer Goods:Personal care bottles and household chemical containers balance chemical resistance with retail shelf aesthetics.
- Electronics:Antistatic films and foamed protective packaging serve Batam semiconductor and appliance assembly operations.
Food and Beverage anchors volume demand; Healthcare generates the most rapid margin expansion through technical film specifications.
Form:
Structural flexibility determines logistics efficiency and retail presentation tradeoffs, with rigid formats offering stackability against flexible formats' source reduction advantages.
- Rigid:Bottles, jars, and trays provide dimensional stability for retail shelf display and automated filling lines. PET preform-based beverage containers dominate Jakarta-Bandung bottling corridors.
- Flexible:Pouches, films, and bags reduce material weight per unit shipped across Indonesia's archipelago distribution. Stand-up pouches gain share in sauce and condiment segments.
- Semi-Rigid:Thermoformed trays and tubs bridge rigidity and lightweight properties for fresh produce and deli applications.
- Laminated:Multilayer coextrusions and adhesive laminations combine barrier polymers for oxygen-sensitive foods; EPR regulations pressure redesign toward mono-material alternatives.
Flexible formats lead tonnage consumption; rigid containers gain share fastest through beverage and dairy segment premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conversion capacity clusters along Java's northern corridor, with resin supply chains and beverage bottling operations concentrating within 200 kilometers of Jakarta. Provincial waste regulations and port access shape where flexible film and rigid container investments locate.
Java
Instant noodle manufacturers in Bekasi and Karawang drive flexible pouch demand for tropical shelf-stable distribution. The Ministry of Environment and Forestry's EPR enforcement tightest here, pushing converters toward mono-material redesigns. The Jakarta-Bandung industrial corridor hosts PET preform injection and blow molding operations serving Coca-Cola and Indofood bottling networks.
Sumatra
Palm oil export logistics through Belawan and Dumai ports sustain woven polypropylene sack demand for bulk commodity shipment. North Sumatra's provincial plastic bag restrictions preceded national EPR rules, conditioning local converters for compliance documentation. Medan-based film extruders supply barrier wraps for processed rubber and coffee exports to European markets.
Sulawesi
Expanding cold chain infrastructure for frozen seafood and tropical fruit exports generates rigid container and modified atmosphere film demand. The national waste reduction roadmap extends producer responsibility obligations to this region by 2026. Makassar's emerging conversion cluster serves Cargill and local processors with thermoformed trays and lidding films.
Kalimantan
Coal and palm kernel logistics sustain industrial bulk packaging demand despite limited consumer goods manufacturing. East Kalimantan's provincial capital relocation to Nusantara is driving construction materials packaging and food service disposables for worker housing. Balikpapan converters supply stretch film for mining equipment and palletized agricultural exports.
Papua
Isolated geography and underdeveloped collection infrastructure create premium pricing for imported packaging materials. Special autonomous region status delays full implementation of national EPR compliance timelines. Jayapura's small converter base relies on Surabaya supply chains with 14-day shipping cycles for flexible film and rigid containers.
Indonesia Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Indonesia's plastic packaging sector. The market structures around three tiers: integrated petrochemical-to-conversion conglomerates, standalone flexible film specialists, and foreign multinationals with technical film capabilities. Strategic moves concentrate on backward integration into resin compounding, forward integration into preform and container manufacturing, and portfolio shifts toward healthcare and pharmaceutical formats.
Among Indonesia-based converters, PT. Indorama Ventures Indonesia exemplifies the integrated archetype with captive PET resin supply, while PT Panca Budi Idaman occupies a position within woven industrial packaging. Amcor Plc represents the multinational technical film tier serving premium healthcare applications. These three anchors illustrate how scale, specialization, and global technology access segment competitive positioning across food, industrial, and pharmaceutical end uses.
| Leading Market Players |
|---|
| PT. Solusi Prima Packaging |
| PT Panca Budi Idaman |
| PT. Indorama Ventures Indonesia |
| PT Toppan Indonesia Printing |
| Amcor Plc |
| PT. Berlina Tbk |
| Indo Cap Closures |
| PT ARTEC PACKAGE INDONESIA |
| PT Indo Tirta Abadi |
| Others |
Supply & Pricing Matrix
rPET flake substitution for virgin PET resin simultaneously redraws feedstock sourcing maps and compresses margin structures across Java-based beverage packaging tiers. The Ministry of Environment and Forestry's recycled content mandates force converters to absorb premium pricing for verified food-grade reprocessed material while provincial collection infrastructure gaps sustain supply volatility.
Pricing Analysis
The Ministry of Environment and Forestry's extended producer responsibility rules dictate the pricing tier structure across Indonesia's plastic packaging landscape. Three-tier pricing structure across premium, standard, and economy levels separates healthcare-certified multilayer films from commodity food wraps and industrial woven sacks. Price differentiation hinges on BPOM migration certification status and volume scale commitments to instant noodle manufacturers. Cost compression in standard-grade flexible packaging is intensifying because standalone converters outside the Jakarta-Bandung corridor lack captive resin supply. Small and mid-sized food processors exhibit the highest price sensitivity, while pharmaceutical blister pack buyers prioritize technical compliance over unit economics.
Supply Chain Analysis
Singapore, Thailand, and South Korea anchor polyethylene and polypropylene resin supply to Indonesian converters. The archipelago's packaging sector draws from regional naphtha-based petrochemical output, imported masterbatch additives, and domestically compounded recycled flake. Single-source vulnerability concentrates in LLDPE stretch film grades specified for palm oil export logistics. Distribution runs through Tanjung Priok and Surabaya port clusters, with just-in-time delivery networks radiating toward Bekasi-Karawang conversion corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized coextrusion and metallization capabilities remain scarce across Indonesia's converter base, creating structural bottlenecks for mono-material barrier redesigns demanded by tightened EPR enforcement.
For Market Incumbents: Fortify backward integration into resin compounding to insulate margin structures from naphtha price volatility and currency fluctuation. Expand preform injection capacity within 100 kilometers of Jakarta-Bandung bottling clusters to capture vendor-managed inventory contracts from instant noodle and beverage manufacturers. Prioritize BPOM certification investment for food-contact barrier films before provincial EPR deadlines accelerate compliance requirements. For New Entrants and Emerging Players: Differentiate on chemical recycling feedstock partnerships that unlock contaminated flexible film streams mechanical recyclers reject. Target Sulawesi and Papua cold chain infrastructure buildouts where established Java-based converters face freight cost disadvantages. Pursue healthcare blister pack qualification as the most penetrable premium segment, leveraging cleanroom film capabilities absent from commodity-focused competitors. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors integrated resin-to-preform operators with documented compliance trails. Long-term viability over the next decade hinges on captive recycling infrastructure and pharmaceutical format diversification. Watch for deposit-return system pilot expansion in Jakarta and Surabaya as the inflection signal for rPET feedstock economics normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PE and PP supply shields converters from naphtha volatility and import tariff exposure. |
| Mono-Material Barrier Redesign | Coextrusion equipment investment enables EPR compliance without sacrificing tropical shelf-life performance. |
| Chemical Recycling Partnership | Pyrolysis feedstock agreements unlock flexible film waste streams currently rejected by mechanical recyclers. |
| Healthcare Format Qualification | Cleanroom film capabilities capture pharmaceutical blister demand with margin profiles exceeding commodity food wrapping. |
| Eastern Indonesia Distribution Expansion | Makassar and Jayapura warehousing reduces freight days for Sulawesi and Papua processed food manufacturers. |
Research Methodology
Cross-validation between primary interviews with plant managers at Bekasi and Karawang conversion facilities and secondary trade data anchors the qualitative findings. Conversations with procurement leads at instant noodle manufacturers, technical directors at woven sack exporters, and regulatory affairs specialists at resin suppliers combined with customs records, Ministry of Environment and Forestry circular economy reports, and BPOM food contact guidance documents. Bottom-up capacity assessments at Tanjung Priok and Surabaya port zones triangulate against top-down demand modeling from food processing and pharmaceutical manufacturing output.
Sensitivity analysis around naphtha price bands, rPET flake availability scenarios, and provincial EPR implementation timelines shapes the analytical framework. Segmentation dimensions span material chemistry, structural form, end-use specification tiers, and regional production clusters across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating archipelago logistics cost structures and cold chain infrastructure buildout rates.
Material uncertainties — naphtha price shocks, rPET feedstock shortfalls, and provincial plastic bag ban expansion — sit outside the modeled envelope. Forecasts reflect assumptions about EPR enforcement consistency and chemical recycling facility commissioning schedules. Recalibration cycles align with material shifts in Ministry of Environment and Forestry regulatory guidance and BPOM certification protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Plastic Packaging Market