
 Middle East and Africa Single-Use Plastic Packaging Market | 2026-2036
Middle East and Africa Single-Use Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Single-Use Plastic Packaging Market Insights
REACH is shifting compliance burdens onto importers serving European-owned retail chains operating in Morocco and Tunisia. Amcor Group GmbH leverages its European regulatory certification infrastructure to sustain premium supply relationships with multinational food brands across the Gulf. Falcon Pack anchors regional manufacturing scale through its UAE-based extrusion and thermoforming operations. Hotpack Packaging Industries LLC differentiates via healthcare-grade sterilization compatibility in its polypropylene container lines.
Middle East and Africa single-use plastic packaging comprises disposable vessels, films, and receptacles manufactured from thermoplastic resins through extrusion, injection molding, or thermoforming processes, typically designed for one consumer interaction before disposal. Polyethylene dominates material selection for flexible bags and wraps due to its moisture barrier properties and cost-efficient blow-film extrusion. Food service end users command the largest volume share, though healthcare-grade polystyrene containers carry superior margin pools attributable to sterilization validation requirements. Supermarket distribution channels face margin compression from direct-sales arrangements between manufacturers and quick-service restaurant chains.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks that obligate brand owners to fund post-consumer collection infrastructure. Saudi Arabia's Saudi Standards, Metrology and Quality Organization issues technical regulations for food-contact plastics that restrict certain phthalate additives in polyethylene formulations. Stakeholders must monitor divergence between Gulf harmonization initiatives and sub-Saharan national standards that lack mutual recognition agreements.
Market Dynamics
Extended producer responsibility frameworks across the Gulf Cooperation Council and South Africa are restructuring cost allocation from municipalities to brand owners, forcing upstream investment in collection infrastructure and material recovery systems.
Growth Catalysts
- Quick-service restaurant expansion:Chains penetrating secondary cities in Saudi Arabia and the UAE are scaling polyethylene container procurement for delivery and takeaway formats.
- REACH compliance infrastructure:European-owned retail chains operating in Morocco and Tunisia require importer-side certification, creating barrier-protected supply relationships for certified manufacturers.
- Healthcare sterilization standards:Polypropylene container lines validated for gamma and ethylene oxide sterilization are capturing premium positioning in hospital and pharmaceutical distribution.
Market Restraints
- Feedstock cost volatility:Ethylene and propylene prices tied to regional naphtha cracking economics create margin compression for non-integrated converters.
- Collection infrastructure gaps:Sub-Saharan markets outside South Africa lack post-consumer recovery systems, limiting circular material feedstock availability.
- Paper and molded fiber substitution:Quick-service chains in the UAE and Qatar are piloting fiber-based alternatives for cold beverage cups and clamshell containers.
Strategic Opportunities
- Nigeria's modern retail corridor:Lagos-Abuja supermarket and food service growth outpaces domestic packaging supply capacity, creating import substitution potential.
- Healthcare-grade certification:ISO 13485 and Saudi FDA medical device packaging registrations open pharmaceutical and diagnostic segments with superior margin profiles.
- Direct manufacturer-to-chain arrangements:Bypassing traditional distribution layers via dedicated supply contracts with quick-service restaurant operators captures margin otherwise lost to intermediaries.
Industry Challenges
- Regulatory divergence management:Gulf harmonization initiatives lack mutual recognition with sub-Saharan national standards, forcing multi-jurisdiction compliance architectures.
- Skilled thermoforming technician scarcity:Precision tool design and process optimization expertise concentrates in UAE and South Africa, constraining expansion in secondary markets.
- Extended producer responsibility capital deployment:South Africa's Department of Forestry, Fisheries and the Environment mandates require brand owners to fund collection infrastructure ahead of proven revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Single-Use Plastic Packaging Market |
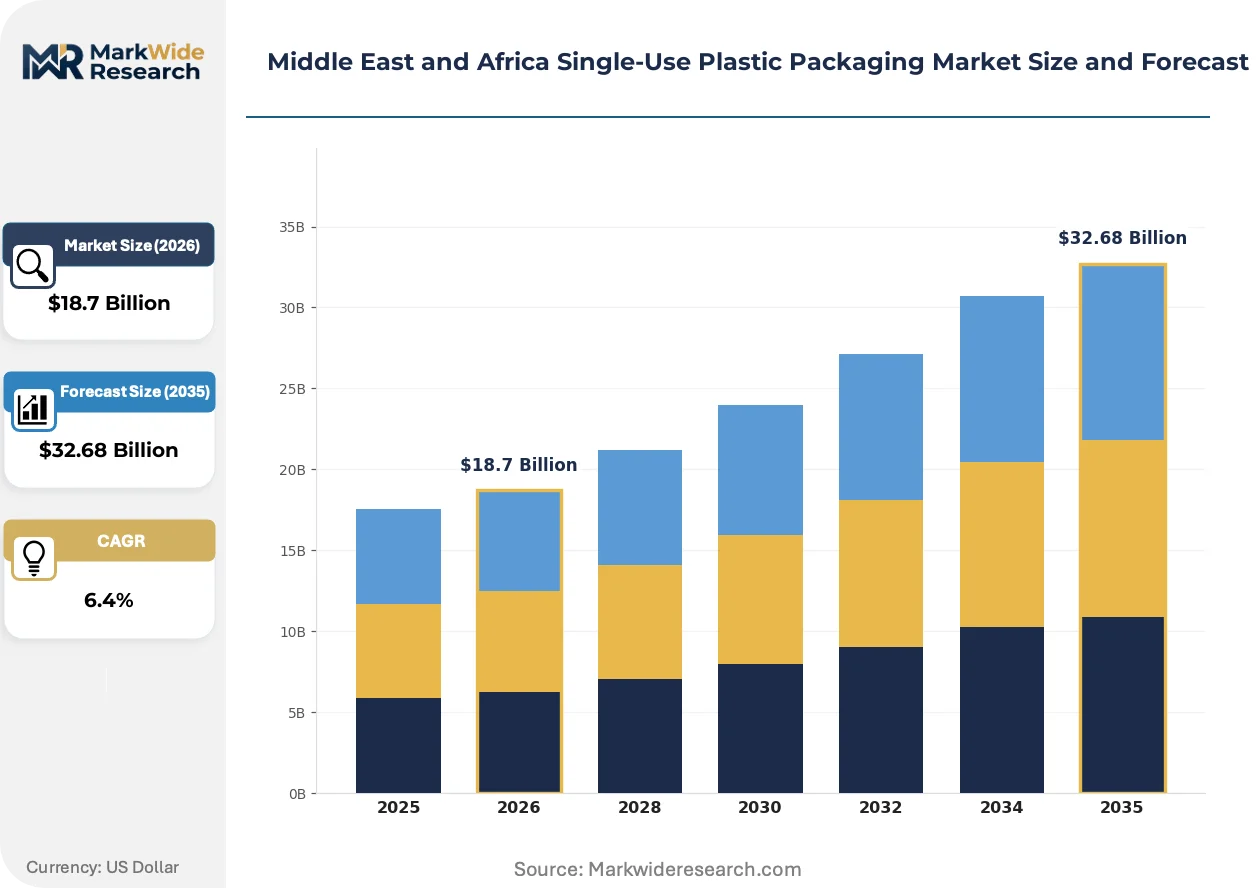
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Wraps, Cups, Containers Material: Polyethylene, Polypropylene, Polystyrene, PET End User: Food Service, Retail, Healthcare, Consumer Goods Distribution Channel: Online, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Amcor Group GmbH, Falcon Pack, Huhtamaki Oyj, Cristal Plastic Industrial LLC, Al Bayader International, Hotpack Packaging Industries LLC, Gulf East Paper and Plastic Industries LLC, Detpak - Detmold Group, Berry Global Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Single-Use Plastic Packaging Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape converter capabilities and buyer procurement criteria across the Middle East and Africa region.
Multi-layer coextrusion technology is modularizing flexible packaging production by enabling custom barrier-property configurations without complete formulation redesign. Food processors in Saudi Arabia and the UAE are adopting these systems to extend shelf life for export-oriented dairy and meat products. The technology is compressing product development cycles from months to weeks while reducing scrap rates during format transitions.
Saudi Standards, Metrology and Quality Organization technical regulations for food-contact plastics are restricting phthalate additives in polyethylene formulations. Converters serving the Saudi market are reformulating plasticizer packages and resubmitting migration test documentation. The regulations are most affecting flexible film producers supplying dairy and edible oil sectors, where compliance documentation now precedes contract renewal.
Centralized procurement by multinational quick-service restaurant chains is consolidating supplier bases and unbundling after-sales technical support. Direct manufacturer relationships are displacing traditional distributor networks in the UAE and Qatar. The shift is most visible in the Gulf Cooperation Council states, where chains now require dedicated account engineering and just-in-sequence delivery capabilities as standard contract terms.
Middle East and Africa Single-Use Plastic Packaging Market Segmentation
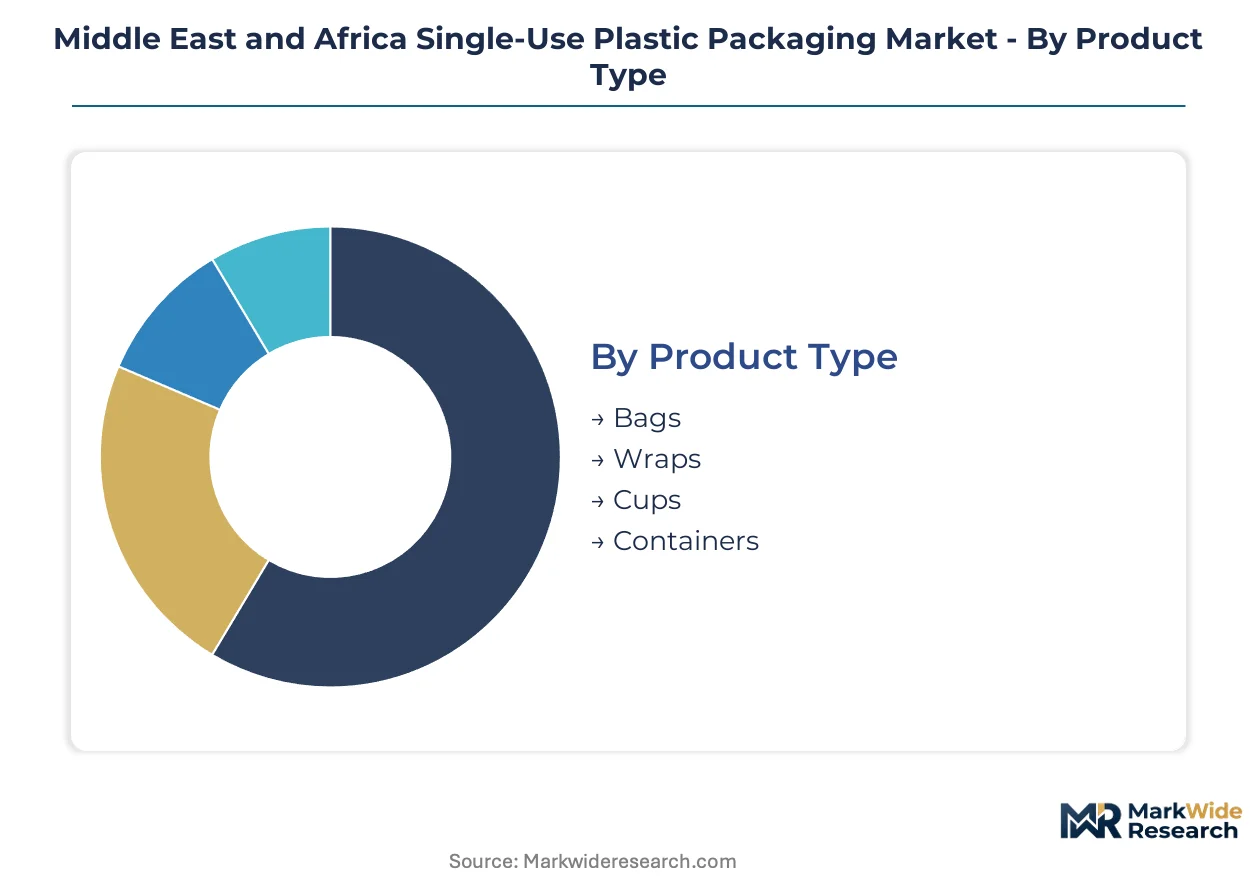
Segmentation in Middle East and Africa single-use plastic packaging reveals distinct capital requirements, margin profiles, and regulatory exposure across material grades and end-use applications. Understanding these structural differences enables targeted capacity deployment and compliance architecture design.
Product Type:
Extrusion and thermoforming equipment scales vary dramatically across formats, with injection molding systems for rigid containers demanding the highest upfront capital outlays.
- Bags:Blown film extrusion lines produce polyethylene carry bags and wicketed formats at high throughput rates. Demand concentrates in Nigeria's Lagos-Abuja corridor, where modern retail expansion outpaces domestic supply capacity and import substitution opportunities are emerging.
- Containers:Thermoformed and injection-molded rigid vessels require precision tooling and multi-cavity molds for cost efficiency. Quick-service restaurant chains across Saudi Arabia and the UAE are scaling procurement of polyethylene-based containers as delivery formats penetrate secondary cities.
- Wraps:Cast film and shrink formats serve food processor needs for palletization and retail display.
- Cups:Thin-wall injection molding and thermoforming lines produce cold and hot beverage formats for food service.
Containers absorb the bulk of installed capacity; bags are expanding most quickly.
Material:
Resin selection determines barrier performance, sterilization compatibility, and compliance with Saudi Standards, Metrology and Quality Organization technical regulations.
- Polyethylene:LDPE and HDPE grades dominate flexible packaging through cost-efficient blow-film extrusion with excellent moisture barrier properties. Food service operators across Gulf Cooperation Council states are expanding procurement of polyethylene-based containers and wraps.
- Polystyrene:Crystal and high-impact grades enable rigid, lightweight containers with clarity for retail presentation. Healthcare-grade polystyrene containers carry superior margin pools attributable to sterilization validation requirements and pharmaceutical distribution needs.
- Polypropylene:Offers higher temperature resistance and gamma sterilization compatibility for medical applications.
- PET:Provides clarity and oxygen barrier for beverage and food tray applications.
Polyethylene commands the largest volume position; polypropylene is gaining share fastest in healthcare applications.
End User:
Customer procurement patterns range from centralized multinational contracts to fragmented municipal purchasing, reshaping sales force deployment and technical service requirements.
- Food Service:Quick-service restaurant chains and catering operations require high-volume, standardized formats with just-in-sequence delivery capabilities. Direct manufacturer-to-chain arrangements are bypassing traditional distribution layers and capturing margin otherwise lost to intermediaries.
- Healthcare:Hospitals, pharmaceutical manufacturers, and diagnostic laboratories demand ISO 13485-validated packaging with gamma and ethylene oxide sterilization compatibility. Healthcare-grade certification opens segments with superior margin profiles and long-term contract stability.
- Retail:Supermarket and hypermarket channels face margin compression from direct-sales arrangements between manufacturers and food service chains.
- Consumer Goods:Personal care and household product brands require custom printed formats with shorter run lengths.
Food Service generates the highest absolute volume; Healthcare delivers the steepest margin expansion trajectory.
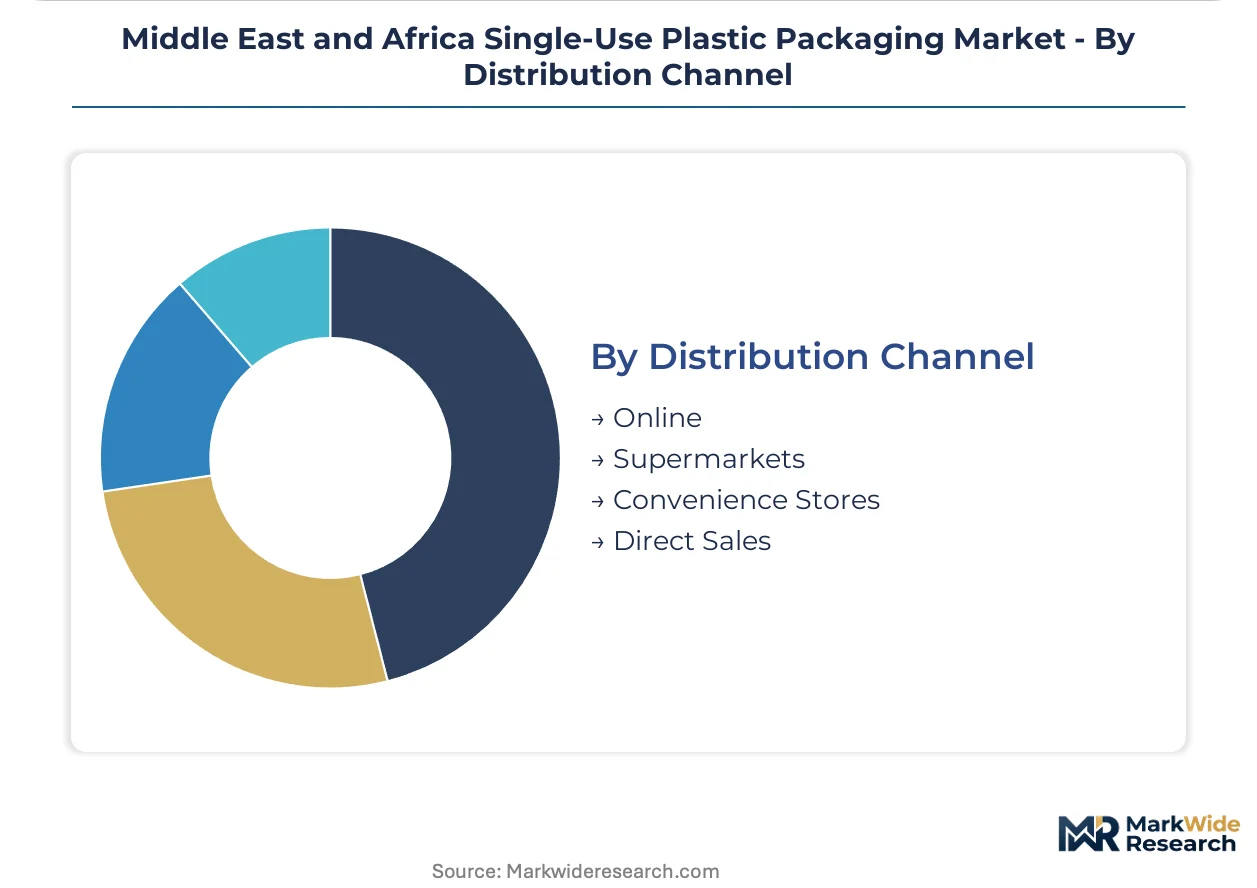
Distribution Channel:
Channel economics vary by working capital intensity, technical support requirements, and concentration of buying power among key accounts.
- Direct Sales:Manufacturer relationships with multinational quick-service restaurant chains consolidate supplier bases and demand dedicated account engineering. Centralized procurement in the UAE and Qatar is displacing traditional distributor networks and unbundling after-sales technical support.
- Supermarkets:Modern retail formats in Nigeria's Lagos-Abuja corridor are outpacing national packaging supply capacity, creating supply gaps and import dependency.
- Online:E-commerce platforms serve small and mid-sized food processors with shorter lead times and lower minimum order quantities.
- Convenience Stores:Fragmentated purchasing across independent operators requires distributor intermediaries and higher logistics costs.
Direct Sales captures the most favorable margin structure; Online is climbing the fastest as digital procurement penetrates mid-market accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for single-use plastic packaging concentrates in the Gulf Cooperation Council corridor and Nigeria's urban belt, with regulatory divergence between sub-Saharan and Middle Eastern jurisdictions reshaping supply chain configurations.
Saudi Arabia
Quick-service restaurant chains expanding into secondary cities like Jeddah and Dammam are scaling polyethylene container procurement for delivery formats. The Saudi Standards, Metrology and Quality Organization restricts phthalate additives in food-contact polyethylene, forcing converters to reformulate plasticizer packages. Riyadh anchors the kingdom's extrusion capacity, with manufacturers clustering around industrial zones to serve centralized quick-service procurement.
United Arab Emirates
Dubai and Abu Dhabi food service operators command the region's highest per-capita consumption of polypropylene containers and sterilization-grade packaging. The Emirates Authority for Standardization and Metrology enforces technical regulations that align with Gulf harmonization initiatives. Jebel Ali industrial corridor hosts thermoforming and injection molding operations serving multinational quick-service chains with just-in-sequence delivery requirements.
South Africa
Extended producer responsibility frameworks are shifting compliance costs from municipalities to brand owners, mandating upstream investment in collection infrastructure. The Department of Forestry, Fisheries and the Environment enforces these obligations ahead of proven revenue models. Gauteng province concentrates precision thermoforming expertise, though technician scarcity constrains expansion into secondary markets.
Nigeria
The Lagos-Abuja corridor's modern retail and food service expansion outpaces domestic packaging supply capacity, creating import dependency and substitution opportunities. National Agency for Food and Drug Administration and Control regulations govern food-contact materials, though enforcement capacity varies by state. Lagos anchors West African distribution, with supermarket chains sourcing polyethylene bags and containers from regional exporters.
Morocco
European-owned retail chains operating in Casablanca and Tangier require REACH-compliant packaging certification from importers, creating barrier-protected supply relationships. The country's national standards body implements technical regulations that lack mutual recognition with Gulf frameworks. Casablanca industrial zones host converters serving Spanish and French retail supply chains with migration-tested polyethylene formulations.
Middle East and Africa Single-Use Plastic Packaging Market Competitive Landscape
Gulf-based producers anchor one tier; European and Asia-Pacific specialists hold certification-advantaged positions serving multinational accounts. The vendor base splits between integrated extrusion-thermoforming operations and import-dependent distributors. Three archetypes dominate: regional scale players with captive resin conversion, European-certified suppliers leveraging regulatory infrastructure, and healthcare-grade specialists validated for sterilization protocols. Competitive moves concentrate on direct manufacturer-to-chain contracting and healthcare certification acquisition.
Within the European-certified tier, Amcor Group GmbH and Huhtamaki Oyj occupy positions defined by regulatory infrastructure and multinational supply relationships. Among Gulf-based fabricators, Falcon Pack and Hotpack Packaging Industries LLC exemplify regional scale archetypes with integrated manufacturing footprints. These groupings represent the structural split between compliance-driven premium positioning and volume-driven regional supply.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Falcon Pack |
| Huhtamaki Oyj |
| Cristal Plastic Industrial LLC |
| Al Bayader International |
| Hotpack Packaging Industries LLC |
| Gulf East Paper and Plastic Industries LLC |
| Detpak - Detmold Group |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
South Africa's extended producer responsibility mandates gate qualified supply and premium-tier pricing access by forcing brand owners to fund collection infrastructure ahead of proven revenue models. Converters with compliant material recovery systems command pricing premiums from multinational food brands, while non-compliant suppliers face margin compression from regulatory exclusion.
Pricing Analysis
Short lead-time premiums apply to healthcare-grade polypropylene containers validated for gamma sterilization, with spot inventory discounts available for standard polyethylene bags. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical packaging from food-contact grades and commodity carry bags. Cost compression in commodity polyethylene runs through naphtha-linked ethylene volatility and non-integrated converter vulnerability. Quick-service restaurant chains demonstrate highest price sensitivity through centralized procurement auctions, while pharmaceutical distributors accept premium pricing for sterilization-validated formats.
Supply Chain Analysis
Direct-to-chain channels handle hyperscale quick-service restaurant demand across Saudi Arabia and the UAE, bypassing traditional distributor markups. Raw material supply concentrates in Saudi Arabia's petrochemical corridor, South Africa's polymer distribution hubs, and UAE-based resin import terminals. Feedstock dependencies include naphtha-derived ethylene, propylene monomer, and imported polystyrene resin. Single-source vulnerability persists in precision thermoforming tool supply, with skilled technician scarcity constraining expansion beyond Gauteng and Dubai industrial zones. Distribution runs through Jebel Ali and Lagos ports serving sub-Saharan markets with limited domestic extrusion capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility capital deployment requirements are forcing consolidation as smaller converters lack balance sheet depth to fund compliance infrastructure ahead of revenue generation.
For Market Incumbents: Extend healthcare-grade certification coverage to capture pharmaceutical margin pools and sterilization-validated contract stability. Backward integration into resin compounding reduces naphtha price volatility exposure for polyethylene converters serving Gulf quick-service chains. Falcon Pack and Hotpack anchor regional manufacturing scale against European-certified competitors through integrated extrusion-thermoforming footprints and dedicated account engineering capabilities. For New Entrants and Emerging Players: Saudi Standards, Metrology and Quality Organization phthalate restrictions in food-contact polyethylene open a window for compliant formulation specialists to displace legacy suppliers during contract renewal cycles. Nigeria's Lagos-Abuja corridor presents the most penetrable geography, with modern retail expansion outpacing domestic packaging supply capacity and creating import substitution opportunities. Target hospital procurement committees and diagnostic laboratory supply chains with ISO 13485-validated polypropylene containers as the primary go-to-market angle. For Investors and Strategic Acquirers: REACH compliance infrastructure acquisition by Amcor Group GmbH is the leading indicator that European regulatory certification commands persistent valuation premiums in Morocco and Tunisia supply relationships. Mid-term viability over the coming decade hinges on circular material feedstock access and extended producer responsibility scheme participation. Acquisition targets should display integrated manufacturing footprints with Gulf Cooperation Council regulatory alignment. Monitor Saudi FDA medical device packaging registration filings as the signal for healthcare segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Certification Acquisition | ISO 13485 and Saudi FDA registrations unlock pharmaceutical margins and long-term contract stability. |
| Direct Manufacturer-to-Chain Contracting | Bypassing distributor layers captures margin from centralized quick-service procurement in UAE and Qatar. |
| Extended Producer Responsibility Compliance | South Africa's Department of Forestry, Fisheries and the Environment mandates create barrier-protected supply positions. |
| Multi-Layer Coextrusion Technology Deployment | Modular barrier configurations compress product development cycles for Saudi and UAE food processors. |
| Nigeria Import Substitution Capacity | Lagos-Abuja corridor supply gaps enable domestic extrusion investment to displace regional exporters. |
Research Methodology
Multi-period observation of quick-service restaurant procurement patterns, healthcare sterilization validation filings, and extended producer responsibility scheme participation anchored the trend analysis, supplemented by interviews with plant managers at Gulf-based extrusion facilities, procurement leads at multinational food brands, distribution channel partners serving Nigeria's modern retail corridor, and technical R&D directors at thermoforming operations. Secondary validation drew from Saudi Standards, Metrology and Quality Organization technical regulations, South Africa's Department of Forestry, Fisheries and the Environment policy frameworks, customs and trade data for polyethylene resin flows, and SEC filings of listed packaging converters. Bottom-up capacity assessments and top-down demand triangulation cross-verified volume estimates.
Input-output matrices modeled polyethylene, polystyrene, polypropylene, and PET consumption across bags, containers, wraps, and cups through food service, healthcare, retail, and consumer goods end uses. CAGRs were derived from segmented demand elasticity analysis and capacity expansion pipelines throughout the forecast period. Industry-specific forecast inputs included quick-service restaurant outlet expansion rates in Saudi secondary cities and healthcare infrastructure investment trajectories across the Gulf Cooperation Council.
Caveats apply where feedstock cost volatility, regulatory divergence between Gulf harmonization and sub-Saharan national standards, or collection infrastructure deployment delays could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
United States Plastic Bottles Market