
 Compostable Plastic Packaging Material Market | 2026-2036
Compostable Plastic Packaging Material Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Plastic Packaging Material Market Analysis
Aftermarket composting infrastructure revenue is reconfiguring how packaging producers capture lifetime value from material flows. BASF SE leverages its PBAT production network to anchor supply security across European conversion plants. NatureWorks LLC specializes in PLA resin grades that dominate high-clarity food service applications. TIPA Ltd competes through proprietary compostable film formulations that meet home and industrial composting certifications.
Compostable plastic packaging materials are thermoplastic formulations engineered from renewable feedstocks such as corn starch, sugarcane, or microbial fermentation products, designed to disintegrate into carbon dioxide, water, and biomass under controlled composting conditions within 180 days. These materials serve the primary commercial purpose of replacing petroleum-based plastics in single-use applications where mechanical recycling infrastructure proves inadequate or economically unviable. PLA resin grades currently occupy the largest production volume position due to mature fermentation technology and cost-competitive feedstock access, while PHA segments represent the fastest-expanding category owing to marine biodegradability properties that command premium positioning in coastal regulatory jurisdictions. Starch blends sustain significant penetration in loose-fill and food tray formats where moisture resistance requirements remain moderate, and PBAT copolyesters capture margin pools in flexible film laminates requiring elasticity and tear resistance comparable to conventional polyethylene.
The European Union's Packaging and Packaging Waste Regulation alongside REACH chemical safety protocols and FDA food contact substance notifications in the United States are reshaping material approval pathways and end-of-life labeling requirements for compostable packaging entrants. ECHA bio-based substance registrations and ASTM D6400 certification standards in North America create differentiated market access tiers that filter supplier participation by testing capacity and capital intensity. Stakeholders must monitor evolving home composting certification fragmentation between OK Compost HOME, BPI, and regional municipal facility acceptance criteria to avoid stranded inventory in jurisdictions with mismatched infrastructure capabilities.
Market Dynamics
PBAT production concentration in northwestern Europe is forcing downstream converters to secure multi-year offtake agreements, reshaping contractual relationships across the flexible film supply chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated recyclability and compostability targets for food contact applications are accelerating certified film adoption across German and French retail supply chains.
- Marine biodegradability certification:PHA resin grades meeting coastal disposal standards command premium positioning in Mediterranean fishing and aquaculture packaging segments.
- Starch fermentation technology maturation:Corn-derived PLA production scale-up in the US Midwest is compressing unit economics for high-clarity thermoformed trays.
Market Restraints
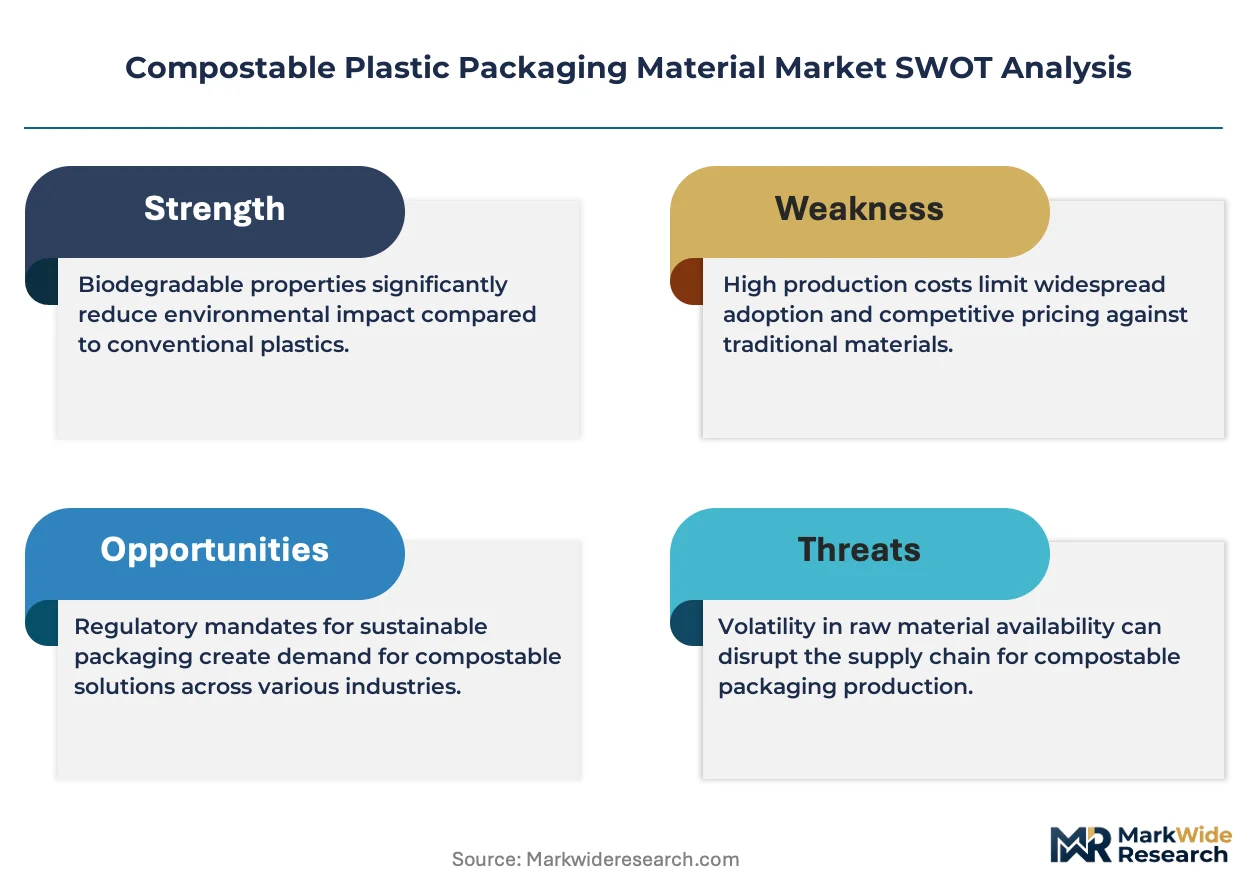
- Feedstock cost volatility:Corn starch and sugarcane price swings directly transmit to PLA and PHA resin contract pricing, squeezing converter margins.
- Industrial composting infrastructure gaps:Facility concentration in northern Italy and the Netherlands leaves southern European markets with stranded compostable packaging volumes.
- Mechanical recycling competition:Improved polyethylene film collection economics in Germany threaten compostable alternatives in non-food contact applications.
Strategic Opportunities
- Home composting certification expansion:OK Compost HOME uptake in French and Italian suburban markets opens distribution channels bypassing industrial facility dependency.
- Agricultural film replacement:Mulch and silage wrap applications in Spain and Portugal present underpenetrated volume pools for soil-biodegradable formulations.
- Digital printing convergence:Water-based ink compatibility with PLA substrates enables short-run customization for craft food brands seeking differentiated shelf presence.
Industry Challenges
- Composting certification fragmentation:Divergent ASTM D6400, EN 13432, and home composting timelines create SKU complexity and inventory stranding risk.
- Thermal processing retrofit costs:Conventional extrusion lines require screw and cooling modifications to handle PLA's lower thermal stability versus polyolefins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Plastic Packaging Material Market |
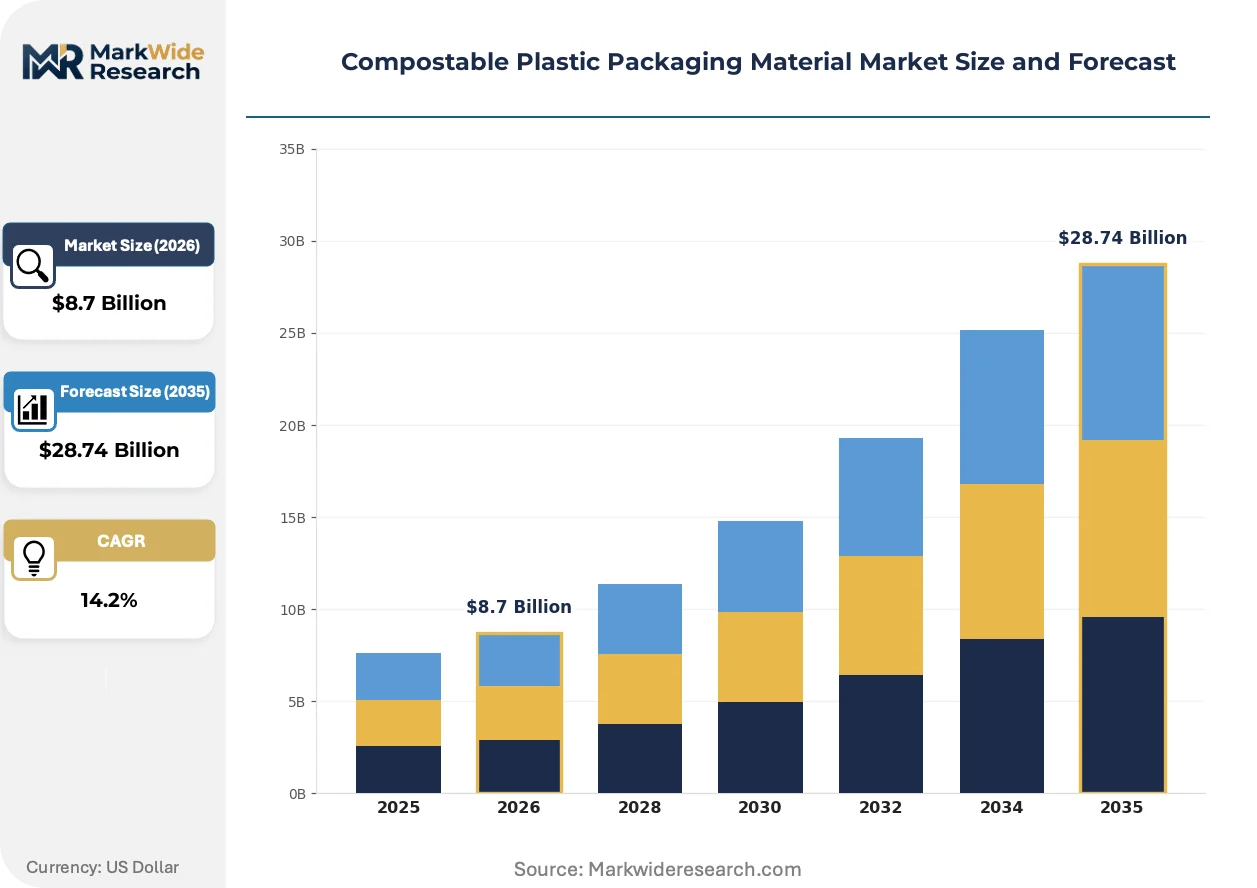
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, PBAT End Use Industry: Food & Beverage, Consumer Goods, Healthcare, Personal Care Form: Films, Bags, Trays, Containers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | NatureWorks LLC, BASF SE, Mondi, Amcor plc, TIPA Ltd, WestRock Company, SmartSolve Industries, Tetra Pak International SA, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Plastic Packaging Material Market Emerging Trajectories
Material formulation priorities are pivoting from industrial-only compostability toward dual-certification films that satisfy both facility and home composting standards without performance trade-offs.
PHA copolyesters derived from microbial fermentation are migrating from marine-degradable niche applications into mainstream food service ware as production scale reaches cost parity with premium PLA grades. Quick-service restaurant chains in coastal US markets are piloting PHA-coated paperboard for hot beverage cups. This migration is compressing the historical price premium between marine-certified and industrial-only compostable materials.
REACH bio-based substance registration requirements are tightening documentation burdens for European compounders importing fermentation-derived resins from non-EU production sites. ECHA substance volume tracking now extends to polymer additives and processing aids previously exempt from full dossier submission. Small and mid-scale compounders in Poland and the Czech Republic are consolidating testing resources through shared service consortia to manage compliance costs.
Certification-driven procurement specifications now dominate RFP evaluation criteria for French and Italian supermarket private-label packaging contracts. Buyers are weighting OK Compost HOME or BPI certification equally with unit price and minimum order quantities. This behavioral shift favors compounders with in-house testing laboratories capable of accelerating certification timelines versus competitors reliant on third-party facilities.
Compostable Plastic Packaging Material Market Segmentation
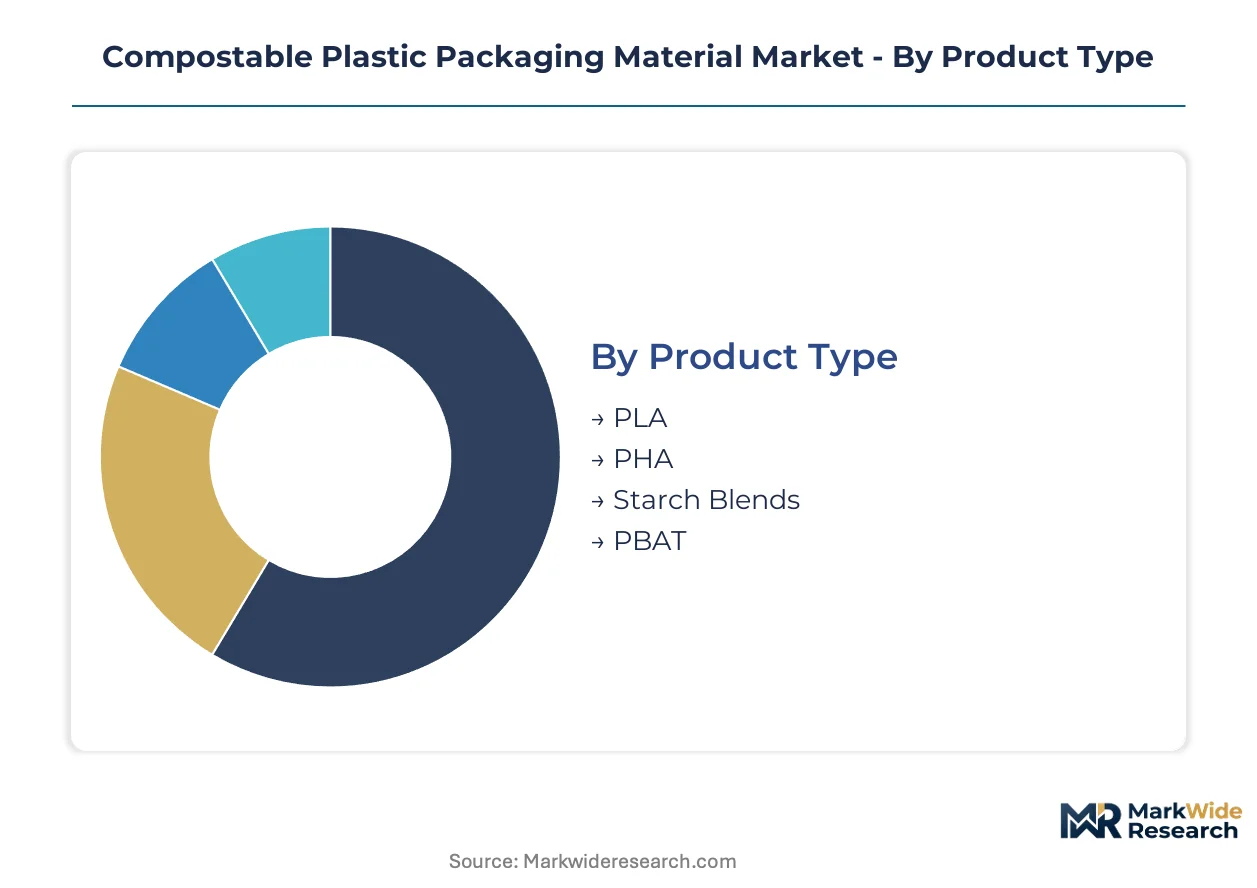
Material chemistry, end-use performance requirements, and composting certification pathways create distinct competitive arenas within compostable packaging. Each segmentation dimension carries different margin structures, regulatory exposure, and infrastructure dependencies that reshape supplier positioning.
Product Type:
Mature fermentation platforms dominate volume positions while novel biopolymer chemistries capture premium niches through differentiated degradation profiles.
- PLA:Polylactic acid derives from corn starch fermentation into lactic acid monomer, polymerized into high-clarity thermoplastic with glass transition temperatures suited to cold-fill food trays. Demand concentrates in German and French retail supply chains where EN 13432 certification is mandatory for private-label food contact applications, though thermal sensitivity above 60°C limits hot-fill adoption.
- PHA:Microbial fermentation of sugar feedstocks yields polyhydroxyalkanoates with marine biodegradability certification that commands 40-60% price premiums over industrial-only compostable alternatives. Mediterranean fishing and aquaculture packaging segments in Spain and Portugal are absorbing initial production volumes as coastal disposal regulations tighten.
- Starch Blends:Thermoplastic starch compounded with biodegradable polyesters serves loose-fill cushioning and molded food trays where moisture barriers remain secondary to cost minimization.
- PBAT:Aliphatic-aromatic copolyesters deliver polyethylene-like elasticity and tear resistance in flexible film laminates, anchoring supply security through BASF's northwestern European production network.
PLA handles the majority of throughput; PHA is the fastest mover on share.
End Use Industry:
Regulatory pressure intensity and contamination risk tolerance stratify adoption timelines across customer verticals.
- Food & Beverage:Single-use cutlery, cups, and fresh produce films face mandatory compostability targets under EU Packaging and Packaging Waste Regulation implementation, with German supermarket chains now specifying OK Compost HOME certification for ready-meal packaging to bypass industrial facility dependency.
- Consumer Goods:Electronics cushioning and retail carry bags compete directly with mechanically recycled polyethylene, squeezing compostable alternatives in non-food applications where collection infrastructure favors conventional materials.
- Healthcare:Sterile barrier packaging for disposable medical devices requires migration testing under ECHA bio-based substance registrations, slowing certification timelines versus food contact pathways.
- Personal Care:Cosmetic jars and tubes leverage PLA's aesthetic clarity for premium brand positioning, though pump mechanism compatibility remains a formulation challenge.
Food & Beverage absorbs the dominant revenue share; Healthcare is climbing the fastest as regulatory clarity emerges.
Form:
Processing technology requirements and shelf-life performance create distinct equipment investment thresholds across format categories.
- Films:Thin-gauge flexible packaging for fresh produce and snack foods requires blown film extrusion lines with modified screw geometries to handle PLA's narrow processing window, concentrating converter capacity in northern Italy and the Netherlands where industrial composting infrastructure is densest.
- Trays:Thermoformed PLA containers for ready meals and deli applications command premium positioning in French hypermarkets, though crystallization treatments are necessary to withstand microwave reheating.
- Bags:T-shirt and refuse sacks utilize PBAT-starch blends for tear resistance, competing with conventional polyethylene on unit economics where extended producer responsibility fees internalize end-of-life costs.
- Containers:Rigid jars and tubs for yogurt and spreads face blow molding equipment retrofit requirements that favor large-scale converters with capital access.
Films carry the volume base; Containers are expanding most quickly as hot-fill barrier coatings mature.
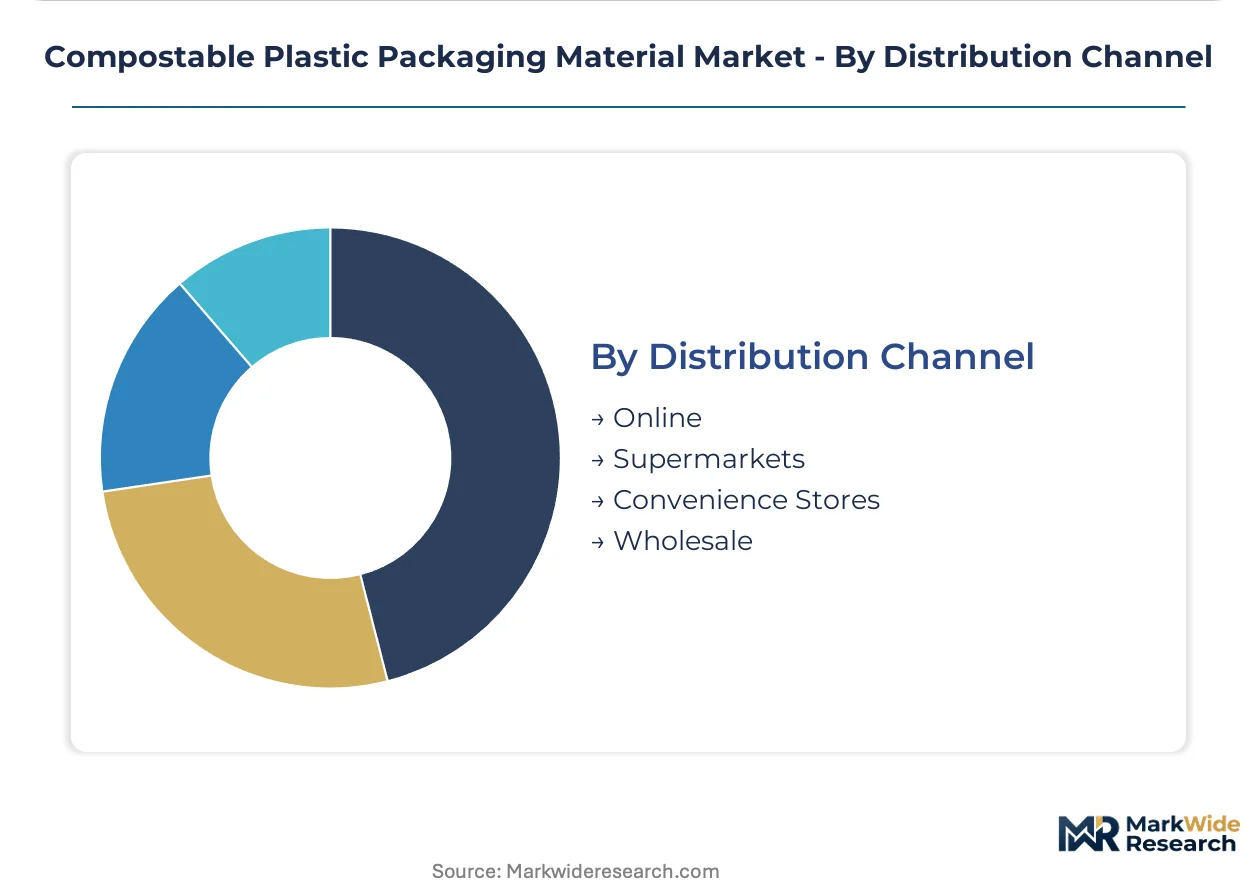
Distribution Channel:
Customer scale and certification documentation requirements reshape channel economics and working capital intensity.
- Supermarkets:Centralized procurement by Carrefour, E. Leclerc, and REWE Group drives specification standardization around dual-certification films, with private-label packaging RFPs weighting OK Compost HOME equally with unit price.
- Online:E-commerce protective packaging faces fragmented demand from direct-to-consumer food brands seeking short-run customization enabled by digital printing convergence with PLA substrates.
- Convenience Stores:Impulse food service applications favor pre-formed cups and cutlery in standardized SKUs with rapid inventory turns.
- Wholesale:Institutional catering and foodservice distributors purchase pallet-scale volumes with extended payment terms that strain working capital for mid-scale compounders.
Supermarkets dominate procurement volume; Online is gaining share fastest as craft brand fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in southern European markets exhibit acute price sensitivity due to sparse industrial composting infrastructure, while German and French purchasers absorb premiums for dual-certification films that bypass facility dependency.
Germany
REWE Group and Edeka Zentrale specify OK Compost HOME certification for private-label ready-meal packaging, eliminating reliance on sparse rural composting facilities. The country's Packaging Act implements extended producer responsibility fees that internalize end-of-life costs for conventional plastics. Converter clusters around Düsseldorf and Hamburg concentrate blown film capacity serving northern European retail supply chains.
France
Carrefour and E. Leclerc procurement teams weight certification documentation equally with unit price in RFP evaluations for fresh produce films. The national anti-waste law mandates phased elimination of single-use petroleum-based plastics in food service applications by 2025. Thermoforming specialists in the Île-de-France region scale crystallized PLA tray production for microwaveable ready-meal segments.
Italy
Northern Italian industrial composting density supports flexible film adoption, while southern markets face stranded inventory risks from infrastructure gaps. The national waste management framework delegates certification acceptance criteria to regional authorities, creating compliance fragmentation. Converter concentration around Bologna and Milan supplies thermoformed trays to central European supermarket chains.
United States
Midwest corn belt proximity compresses PLA feedstock costs for domestic compounders serving food service ware segments. FDA food contact substance notifications create documentation burdens for imported fermentation-derived resins that domestic producers circumvent. NatureWorks operates fermentation and polymerization capacity in Blair, Nebraska, anchoring regional supply security for high-clarity thermoformed applications.
Spain
Mediterranean fishing and aquaculture packaging segments absorb PHA premiums for marine biodegradability certification as coastal disposal regulations tighten. The national circular economy strategy targets 2030 compostability benchmarks for single-use food contact materials. Agricultural film demand concentrates in Valencia and Murcia for soil-biodegradable mulch applications in intensive horticulture.
Compostable Plastic Packaging Material Market Vendor Landscape
Resin producers and downstream converters split the market along feedstock control versus formulation specialization lines. The vendor base concentrates around fermentation-derived polymer suppliers with captive raw material access and compounders with certification laboratory capabilities. Three archetypes dominate: integrated biopolymer producers, specialized film converters, and diversified packaging conglomerates with compostable product lines. Capacity expansion in PBAT and PLA resin grades accelerates as converters secure multi-year offtake agreements, while strategic partnerships between compounders and certification bodies compress approval timelines.
Within the integrated biopolymer tier, NatureWorks LLC and BASF SE exemplify divergent feedstock strategies. The former anchors PLA supply security through Midwest corn belt fermentation infrastructure, while the latter leverages northwestern European petrochemical networks for PBAT copolyester production. TIPA Ltd occupies a position among specialized film formulators competing through proprietary compostable laminate structures. These three represent distinct archetypes: fermentation-based resin integration, petrochemical-adjacent biopolymer production, and downstream formulation specialization.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| Mondi |
| Amcor plc |
| TIPA Ltd |
| WestRock Company |
| SmartSolve Industries |
| Tetra Pak International SA |
| Berry Global |
| Others |
Supply Flow & Price Mechanics
PBAT production concentration in northwestern Europe anchors pricing power for flexible film laminates, pushing margin pools toward converters with multi-year offtake security rather than spot-market participants.
Pricing Analysis
Aftermarket composting infrastructure revenue drives lifetime value capture for packaging producers with facility partnerships or collection network stakes. Three-tier pricing structure across marine-certified, dual-certification, and industrial-only grades separates PHA premiums from PBAT-PLA mid-tier and starch-blend economy positioning. Cost compression in PLA resin contracts is intensifying because Midwest corn belt fermentation scale-up feeds converter margin pressure. Small craft food brands exhibit acute price sensitivity versus centralized supermarket procurement teams that absorb certification premiums for supply security.
Supply Chain Analysis
Tariff exposure between non-EU fermentation-derived resin sources and European compounders dominates supply chain risk planning under REACH bio-based substance registration requirements. Raw material flows draw from US Midwest corn starch, Brazilian sugarcane, and northwestern European petrochemical networks for PBAT copolyesters. Single-source vulnerability concentrates in lactic acid fermentation capacity controlled by NatureWorks and select Asian producers. Distribution runs through converter clusters in northern Italy and the Netherlands with dense industrial composting infrastructure, bypassing southern European markets with facility gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through centralized supermarket procurement by Carrefour, REWE Group, and E. Leclerc, fragmenting converter negotiating leverage across private-label packaging contracts.
For Market Incumbents: Entrench supply security through captive PBAT production or backward integration into lactic acid fermentation, defending against starch blend substitutes in loose-fill segments. Priority investment targets crystallized PLA tray capacity for French microwaveable ready-meal specifications and in-house OK Compost HOME certification laboratories to compress approval timelines versus third-party dependent competitors.
For New Entrants and Emerging Players: Build out soil-biodegradable agricultural film formulations for Spanish and Portuguese horticulture markets where conventional polyethylene faces extended producer responsibility cost internalization. Target Mediterranean fishing and aquaculture packaging with PHA marine biodegradability certification, leveraging coastal disposal regulation tightening as the primary go-to-market angle through regional distributor partnerships.
For Investors and Strategic Acquirers: Capital is best deployed toward compounders with dual-certification film capabilities and shared testing consortium membership in Poland or the Czech Republic, capturing consolidation value as REACH documentation burdens filter out small-scale competitors. The inflection signal to monitor is home composting certification harmonization between OK Compost HOME, BPI, and municipal facility acceptance criteria, which would unlock stranded inventory value in southern European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive PLA feedstock supply secures margin pools against corn price volatility transmitted by NatureWorks contract structures. |
| Dual-Certification Film Development | OK Compost HOME plus EN 13432 compliance opens French and Italian supermarket procurement channels bypassing industrial facility dependency. |
| Shared Testing Consortium Formation | Polish and Czech compounders pool ECHA bio-based substance registration costs to manage REACH compliance burdens. |
| Agricultural Film Market Entry | Soil-biodegradable mulch formulations capture volume pools in Valencia and Murcia intensive horticulture segments. |
| Digital Printing Convergence Investment | Water-based ink compatibility with PLA substrates enables short-run customization for craft food brand differentiation. |
Methodological Framework
Initial hypotheses were tested against primary input from resin procurement managers at flexible film converters, ECHA regulatory affairs specialists, supermarket private-label packaging buyers, and industrial composting facility operators, then refined through secondary validation against EN 13432 certification databases, REACH bio-based substance registration filings, EU Packaging and Packaging Waste Regulation implementation timelines, and customs trade data for fermentation-derived polymer imports. Bottom-up volume estimates from converter capacity utilization and top-down demand projections from food packaging substitution rates were triangulated for convergence.
Demand-supply balance dynamics across material chemistry segments, end-use industry verticals, composting certification pathways, and regional infrastructure maturity shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume build-ups and price trajectory assumptions, with specific inputs including corn starch and sugarcane feedstock cost indices, industrial composting facility capacity expansion pipelines, and supermarket private-label packaging RFP specification trends.
Stress conditions across corn price volatility bands, REACH registration timeline delays, and home composting certification fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU regulatory implementation pacing and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Nigeria Plastic Bottles Market