
 PCR Bottles Market | 2026-2036
PCR Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Bottles Market Analytics
Multi-source resin procurement is recalibrating how PCR bottle manufacturers secure post-consumer feedstock. Amcor plc leverages its global recycling partnerships to secure certified PCR streams across multiple continents. Berry Global Group anchors North American supply through integrated collection infrastructure. ALPLA Group specializes in closed-loop systems that link retail collection directly to bottle production.
PCR bottles are rigid containers manufactured from post-consumer recycled polymers, typically containing 25-100% reclaimed resin content and engineered to meet dimensional tolerances of ±0.2mm for automated filling lines. Their primary purpose is to replace virgin plastic packaging in sectors where regulatory mandates or corporate sustainability targets require verified recycled content. Round bottles lead laboratory and pharmaceutical segments due to uniform wall thickness and consistent thermal stability during autoclaving. PCR PET material is expanding fastest in personal care applications where clarity requirements approach virgin-grade performance. Custom shapes command premium positioning in branded cosmetic lines where differentiation justifies higher tooling investment.
The EPA oversees post-consumer resin certification in US packaging applications, while ECHA enforces REACH registration for recycled polymer additives entering European circulation. FDA guidelines on food-contact recycled plastics shape which PCR streams qualify for beverage and food storage bottling. Stakeholders must monitor evolving state-level extended producer responsibility laws that will determine minimum recycled content thresholds and acceptable feedstock verification protocols.
Market Dynamics
Post-consumer resin certification protocols are forcing PCR bottle manufacturers to restructure feedstock verification systems. The EU Green Deal mandates traceable recycled content claims, compelling producers to deploy blockchain-linked material passports across multi-tier supplier networks.
Growth Catalysts
- REACH Registration Requirements:ECHA mandates on recycled polymer additives are accelerating investment in certified purification systems for pharmaceutical-grade PCR streams entering European circulation.
- Autoclave-Compatible PET Formulations:Laboratory end-users in Germany and Switzerland are specifying PCR bottles that withstand 121°C sterilization cycles without dimensional distortion.
- Personal Care Clarity Standards:Cosmetic brands in France and Italy are sourcing near-virgin optical-grade PCR PET for transparent serum and toner packaging.
Market Restraints
- Feedstock Price Volatility:Baled PET flake costs fluctuate with crude oil parity, compressing margins when virgin resin undercuts reclaimed material by double-digit percentages.
- Collection Infrastructure Gaps:Curbside recycling participation rates below 35% in Southern and Eastern European markets constrain regional PCR supply security.
- FDA Food-Contact Barriers:The agency's stringent contaminant thresholds exclude most mechanically recycled PET from direct beverage applications, limiting addressable market scope.
Strategic Opportunities
- Deposit-Return Scheme Expansion:Germany's DRS infrastructure generates high-purity PET streams with sub-1% contamination rates, creating feedstock arbitrage potential for premium PCR bottle grades.
- Closed-Loop Hospital Contracts:Medical waste sterilization and reprocessing partnerships with university hospital networks in the Netherlands and Belgium secure captive PCR feedstock channels.
- AI-Powered Sorting Convergence:Near-infrared polymer identification combined with robotic separation is enabling multi-resin bottle production from mixed post-consumer waste streams.
Industry Challenges
- Certification Timeline Compression:EFSA novel food contact approvals for enzymatically recycled PET require 18-24 month evaluation windows, delaying product launches.
- Legacy Blow-Molding Retrofit Costs:Existing equipment designed for virgin resin tolerances demands screw and die modifications to process higher-moisture PCR feedstock without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Bottles Market |
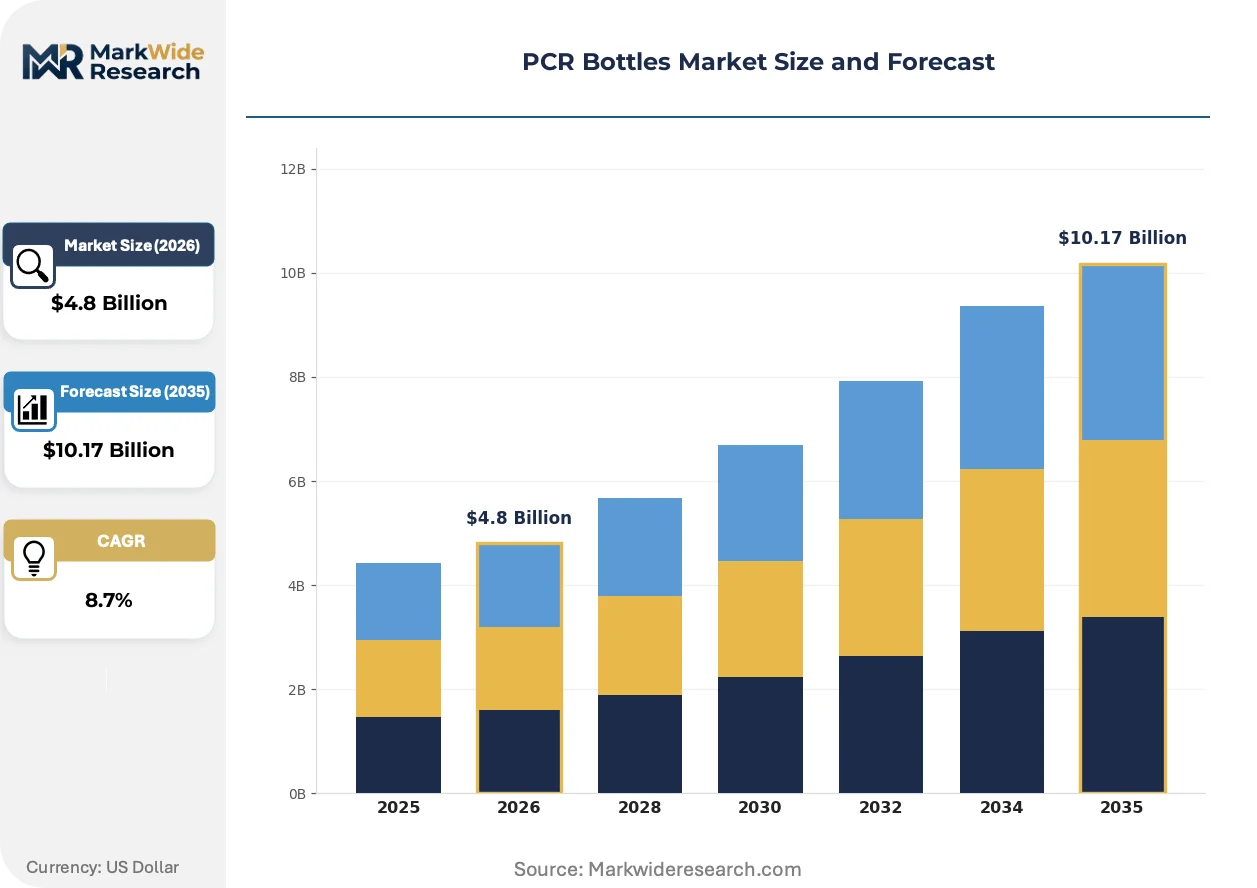
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Bottles, Square Bottles, Cylindrical Bottles, Custom Shapes Material: Polypropylene, Polyethylene, PCR PET, Glass Closure Type: Screw Caps, Snap Caps, Dropper Caps, Tamper-evident Caps Application: Laboratory Use, Pharmaceutical Packaging, Food Storage, Personal Care Products |
| Companies Covered | Amcor plc, Berry Global Group, Sealed Air Corporation, Mondi Group, ALPLA Group, Graham Packaging, Sonoco Product Company, ePac Holdings, Transcontinental Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Bottles Market Evolving Landscape
Distributed recycling infrastructure is collapsing the traditional separation between collection and conversion. Producers are deploying containerized processing units at retail and institutional collection points.
Decontamination technology is decentralizing quality control in PCR bottle manufacturing. Super-cleaning systems using CO2 or nitrogen flushing now operate at satellite facilities rather than centralized plants. Pharmaceutical contract packagers in Bavaria and North Rhine-Westphalia are installing in-house bottle production lines fed by regional medical waste reprocessors. This geographic compression eliminates trans-shipment contamination risks while shortening batch traceability chains.
The EU Green Deal's packaging and packaging waste regulation is tightening recycled content verification requirements. Member states must implement harmonized calculation methodologies for post-consumer recycled content claims by 2025. German chemical processors are pre-emptively adopting mass-balance accounting for pyrolysis-derived PCR streams. French cosmetic houses are requiring third-party audited chain-of-custody documentation for all PCR packaging suppliers.
Direct contracting between brand owners and waste management operators is displacing traditional resin merchant intermediaries. Large personal care multinationals in Italy and Spain are negotiating multi-year offtake agreements with municipal sorting facilities. This channel consolidation secures volume commitments while transferring price risk to integrated operators. The Benelux region exhibits the most advanced vertical coordination, with retail chains operating captive bottle production fed by their own store-collection programs.
PCR Bottles Market Segmentation
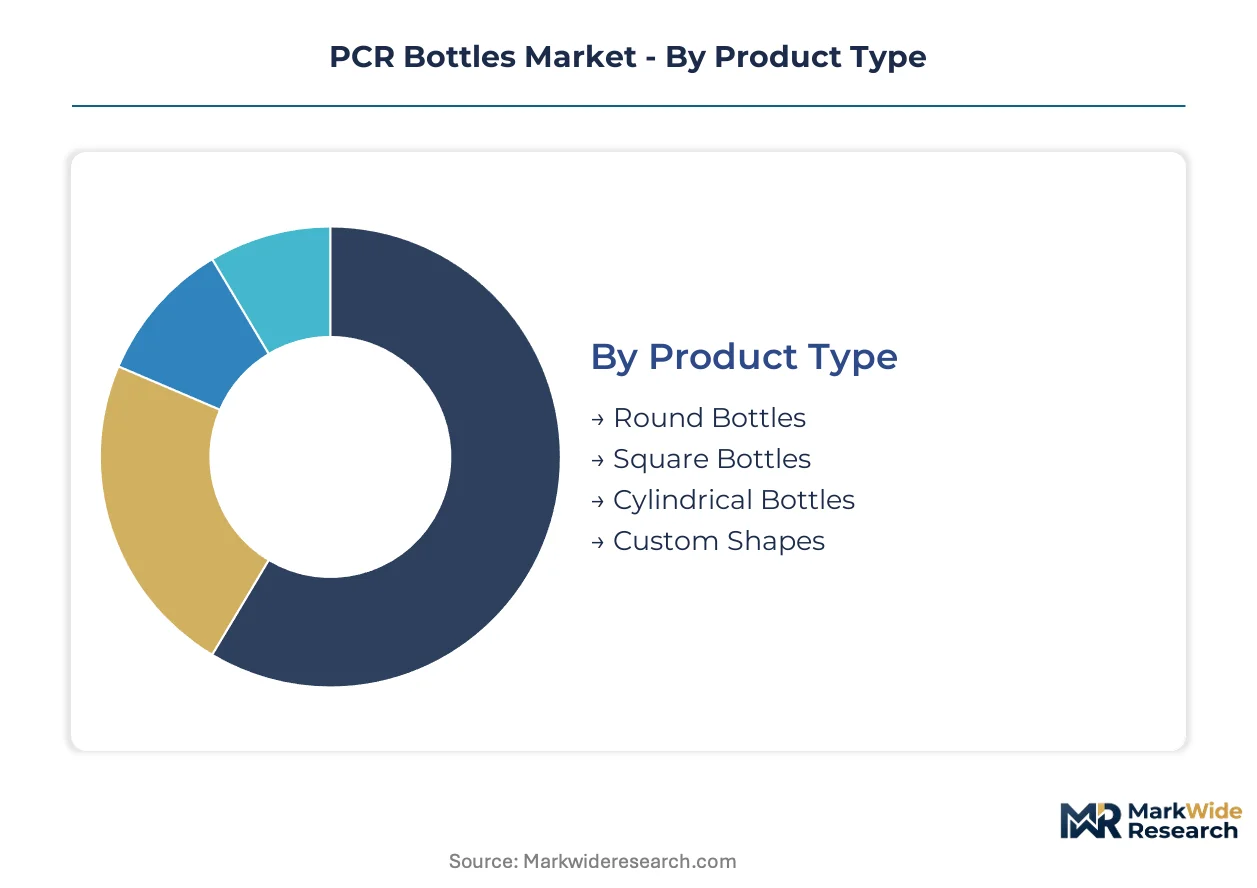
PCR bottle manufacturers configure production lines around distinct performance tiers rather than uniform specifications. Pharmaceutical and laboratory end-users impose the tightest dimensional tolerances, while personal care brands prioritize optical clarity over structural rigidity. Material selection and closure integration determine which segments command premium positioning versus commodity pricing.
Product Type:
Round bottles dominate high-volume pharmaceutical filling operations where automated capping lines demand consistent neck finish geometry. Custom shapes capture premium shelf positioning in cosmetic applications where tooling investment amortizes across branded product lines.
- Round Bottles:Uniform wall thickness distribution enables autoclave sterilization cycles at 121°C without thermal distortion. Demand concentrates in German and Swiss laboratory supply chains where automated liquid handling systems require ±0.2mm dimensional repeatability. REACH-compliant resin traceability mandates favor established round bottle suppliers with certified purification systems.
- Custom Shapes:Proprietary mold designs differentiate cosmetic serum packaging in French and Italian markets. L'Oréal and Estée Lauder subsidiaries specify unique shoulder geometries and embossed branding elements that justify 40-60% tooling premiums. Lead times extend to 16-20 weeks for complex multi-cavity molds.
- Square Bottles:Maximize pallet density for chemical reagent shipping, reducing freight costs 15-20% versus cylindrical equivalents.
- Cylindrical Bottles:Standard intermediate geometry for industrial solvent containment where label adhesion and stacking stability balance cost efficiency.
Today's leader: Round Bottles. Tomorrow's challenger: Custom Shapes.
Material:
Resin selection determines regulatory clearance pathways and end-use accessibility. PCR PET offers the broadest application range but faces FDA food-contact restrictions that polypropylene avoids.
- PCR PET:Near-virgin optical clarity after super-cleaning decontamination enables transparent personal care packaging. Demand concentrates in French cosmetic houses requiring third-party audited chain-of-custody documentation. EFSA novel food contact approvals for enzymatically recycled grades remain pending, delaying beverage market entry.
- Polypropylene:Superior chemical resistance against acids and organic solvents makes it the default for laboratory reagent storage. Bavarian pharmaceutical contract packagers specify autoclavable PP grades for parenteral solution containment. FDA clearance for food-contact applications exceeds mechanically recycled PET flexibility.
- Polyethylene:Lower melt temperature reduces energy consumption in blow-molding operations, favoring cost-sensitive industrial chemical applications.
- Glass:Inert surface properties retain dominance for highly sensitive pharmaceutical compounds where polymer leachables pose stability risks.
PCR PET is climbing the fastest as cosmetic brands accelerate sustainable packaging commitments. Polypropylene maintains defensive positioning in regulated medical applications.
Closure Type:
Closure integration complexity separates commodity bottle supply from value-added packaging systems. Tamper-evident features command regulatory mandates in pharmaceutical distribution while dropper assemblies enable precise dosing in premium personal care.
- Screw Caps:Universal threading standards (GL18, GL25, GL45) enable interchangeability across laboratory equipment brands. Demand concentrates in German research institute procurement where Sartorius and Eppendorf pipetting systems require compatible neck finishes.
- Tamper-evident Caps:Ring-break mechanisms satisfy EU Falsified Medicines Directive requirements for prescription drug packaging. Benelux pharmaceutical distributors specify integrated holographic verification features that add €0.08-0.12 per unit.
- Snap Caps:Single-action opening suits high-throughput diagnostic reagent kits where technician efficiency outweighs child-resistance requirements.
- Dropper Caps:Pipette assembly integration commands 25-35% packaging cost share in serum and essential oil applications.
Screw Caps retain volume leadership. Tamper-evident assemblies gain share through regulatory compliance expansion.
Application:
End-use specifications diverge sharply between regulated pharmaceutical environments and discretionary personal care markets. Laboratory and pharmaceutical segments demand batch-level traceability that food and cosmetic applications rarely require.
- Pharmaceutical Packaging:EMA Annex 1 compliance mandates particulate contamination controls exceeding standard industrial packaging. Dutch and Belgian hospital networks negotiate closed-loop contracts with sterilization reprocessors for captive PCR feedstock. Serialization requirements under the EU Falsified Medicines Directive add €0.15-0.25 per bottle for track-and-trace integration.
- Personal Care Products:Optical-grade clarity specifications approach virgin PET performance thresholds. Italian cosmetic manufacturers source from German DRS-derived feedstock with sub-1% contamination rates, paying 12-18% premiums over standard PCR grades.
- Laboratory Use:Autoclave compatibility and chemical resistance specifications narrow qualified supplier pools to specialized converters.
- Food Storage:FDA mechanical recycling restrictions limit addressable scope to non-contact applications and caps/closure components.
Pharmaceutical Packaging anchors revenue stability. Personal Care Products offer the steepest expansion trajectory as sustainability commitments harden into procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laboratory equipment clusters anchor PCR bottle procurement across European pharmaceutical supply chains. REACH compliance requirements and the EU Green Deal are tightening material traceability standards, while deposit-return schemes in Northern Europe generate premium feedstock streams.
Germany
Bavarian pharmaceutical contract packagers and North Rhine-Westphalia chemical processors drive specialized bottle demand for autoclave-compatible applications. The EU Green Deal mandates blockchain-linked material passports for recycled content claims. DRS infrastructure generates PET streams with sub-1% contamination rates, creating feedstock arbitrage for premium PCR grades serving laboratory markets.
United States
FDA food-contact barriers constrain mechanically recycled PET in beverage applications, diverting supply toward pharmaceutical and personal care packaging. EPA oversees post-consumer resin certification protocols that shape qualifying feedstock streams. California and Northeastern state-level extended producer responsibility laws are determining minimum recycled content thresholds for packaging procurement.
France
Cosmetic houses in Île-de-France require third-party audited chain-of-custody documentation for all PCR packaging suppliers. ECHA REACH registration requirements accelerate investment in certified purification systems. L'Oréal and Estée Lauder subsidiaries specify unique shoulder geometries and embossed branding elements that justify tooling premiums in branded serum packaging.
Italy
Personal care multinationals negotiate multi-year offtake agreements with municipal sorting facilities to secure volume commitments. EFSA novel food contact approvals for enzymatically recycled PET remain pending, delaying beverage market entry. Northern Italian converters source optical-grade PCR PET from German DRS-derived feedstock, paying premiums for near-virgin clarity performance.
Netherlands
Medical waste sterilization and reprocessing partnerships with university hospital networks secure captive PCR feedstock channels. The Benelux region exhibits advanced vertical coordination, with retail chains operating captive bottle production fed by store-collection programs. Dutch and Belgian hospital networks negotiate closed-loop contracts that eliminate trans-shipment contamination risks while shortening batch traceability chains.
PCR Bottles Market Competitive Landscape
Global majors compete with regional champions across feedstock security and certification capabilities. Market structure consolidates around integrated converters with captive collection infrastructure and specialized merchants serving premium pharmaceutical segments. Three archetypes dominate: multinational packaging conglomerates with global recycling partnerships, regional specialists in closed-loop systems, and mid-scale converters targeting autoclave-compatible laboratory grades. Competitive moves center on multi-year offtake agreements with municipal sorters and retrofit investments for super-cleaning decontamination systems.
Within the multinational tier, Amcor plc and Berry Global Group exemplify scale-driven positioning through global recycling partnerships and North American integrated collection infrastructure respectively. ALPLA Group occupies a specialist position, representing the closed-loop archetype that links retail collection directly to bottle production. These three anchors demonstrate how geographic coverage and feedstock control separate premium-tier suppliers from commodity converters in certification-intensive segments.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Sealed Air Corporation |
| Mondi Group |
| ALPLA Group |
| Graham Packaging |
| Sonoco Product Company |
| ePac Holdings |
| Transcontinental Inc. |
| Others |
Value Network & Pricing Analysis
Skilled polymer chemists concentrated in Bavaria and North Rhine-Westphalia command wage premiums that widen spreads between pharmaceutical-grade and commodity PCR bottle tiers. Labor-cost differentials compound feedstock volatility, forcing converters to tier pricing around certification depth rather than volume scale alone.
Pricing Analysis
Input-cost pass-through from baled PET flake volatility structures contract pricing around oil-indexed adjustments. Three-tier pricing separates EFSA-pending enzymatic grades from REACH-registered pharmaceutical streams and uncertified industrial grades. Price differentiation centers on chain-of-custody audit depth and autoclave validation documentation. Cost compression in standard PCR tiers is intensifying because virgin resin parity swings erode converter margins. Laboratory procurement in Germany and Switzerland shows lowest price sensitivity, while Southern European personal care brands negotiate aggressively on volume commitments.
Supply Chain Analysis
Dual-sourcing requirements from Dutch and Belgian hospital networks mandate qualified backup suppliers for all pharmaceutical-grade PCR streams. Geographic supply concentrates in Germany, Italy, and the Netherlands, with German DRS infrastructure feeding premium optical-grade feedstock. Raw material dependencies center on post-consumer PET flake, pyrolysis-derived synthetic intermediates, and certified additive packages. Single-source vulnerability runs through centralized super-cleaning facilities in Bavaria. Distribution runs through pharmaceutical contract packagers and direct brand-owner agreements displacing traditional resin merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR bottle economics favor margin expansion as super-cleaning technology cost curves decline and pharmaceutical buyers accept premiums for validated autoclave performance. Certification investment separates sustainable profitability from commodity margin compression.
For Market Incumbents: Hedge feedstock exposure through multi-year offtake agreements with German DRS operators and Dutch hospital sterilization reprocessors. Deepen backward integration into collection infrastructure before municipal sorters consolidate negotiating power. Defend margin position by accelerating EFSA novel food contact submissions ahead of enzymatic recycling competitors. For New Entrants and Emerging Players: AI-powered polymer identification systems offer a technology-first wedge into mixed-waste feedstock processing underserved by incumbent super-cleaning capacity. Target Italian and Spanish personal care markets where cosmetic houses seek audited chain-of-custody documentation but lack qualified domestic suppliers. Pursue direct contracting with retail chains operating captive collection programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Packaging conglomerates with global recycling partnerships are the most active acquirer in this space, seeking regional specialists with closed-loop hospital contracts. Five-to-ten year viability hinges on regulatory enforcement of recycled content mandates rather than voluntary brand commitments. Monitor EFSA approval timelines for enzymatically recycled PET as the critical inflection signal for beverage market expansion and feedstock demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Feedstock Offtake Agreement | Secures German DRS-derived PET streams with sub-1% contamination rates for premium grades. |
| In-house Super-cleaning Installation | Eliminates trans-shipment contamination risks for Bavarian pharmaceutical contract packagers. |
| Blockchain-linked Material Passport | Satisfies EU Green Deal traceability mandates across multi-tier supplier networks. |
| Closed-loop Hospital Partnership | Captures sterilized medical waste streams from Dutch university hospital networks. |
| EFSA Novel Food Contact Submission | Unlocks beverage market entry pending enzymatic recycling approval timelines. |
Research Methodology
Coverage spans Germany, France, Italy, the Netherlands, and the United States, with primary inputs from each. The analysis combines executive interviews with pharmaceutical contract packagers, cosmetic packaging procurement leads, laboratory supply chain managers, and polymer recycling technology specialists. Secondary validation draws from EFSA novel food contact filings, ECHA REACH registration databases, EPA post-consumer resin certification records, and EU packaging waste directive implementation reports. Bottom-up segment modeling triangulates against top-down macroeconomic drivers.
Granularity-level modeling distinguishes pharmaceutical-grade, personal care-grade, and industrial-grade PCR bottles across material type, closure integration complexity, and regional regulatory cluster. Volume and value outputs reflect segment-level CAGRs derived from feedstock availability projections, certification timeline assumptions, and end-use demand elasticity. Industry-specific forecast inputs include German DRS participation rates, EFSA approval pipeline status, and autoclave validation protocol adoption curves.
The model holds under sustained EU Green Deal enforcement and stable pyrolysis technology cost curves; deviation in EFSA enzymatic recycling approval timelines or crude oil price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Plastic Buckets Market