
 China Plastic Packaging Market | 2026-2036
China Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Plastic Packaging Market Analysis
Buyer concentration in China's e-commerce and fresh-food delivery sectors is pivoting toward fewer platform giants placing massive consolidated orders for standardized packaging formats. Berry Global Inc. leverages its multinational technical base to serve tier-one brands with high-barrier films, while Shangdong Haishengyu Plastic Industry Co. Ltd anchors domestic supply through cost-competitive rigid container lines for regional food processors. ALPLA Werke Alwin Lehner GmbH & Co KG differentiates via preform and bottle manufacturing scale that supports beverage customers across coastal provinces.
China plastic packaging encompasses polymer-based containment and protection systems—typically formed through extrusion, blow molding, or thermoforming processes with thickness tolerances ranging from microns to millimeters—engineered to preserve product integrity through moisture barriers, impact resistance, and seal integrity across supply chains. Flexible packaging leads volume due to its material efficiency and suitability for snack and instant-food formats, while pharmaceutical packaging commands premium positioning as end-users demand compliance-grade barrier properties. Rigid containers remain mature in beverage applications though growth in healthcare end-use is accelerating demand for sterilizable polymer formats.
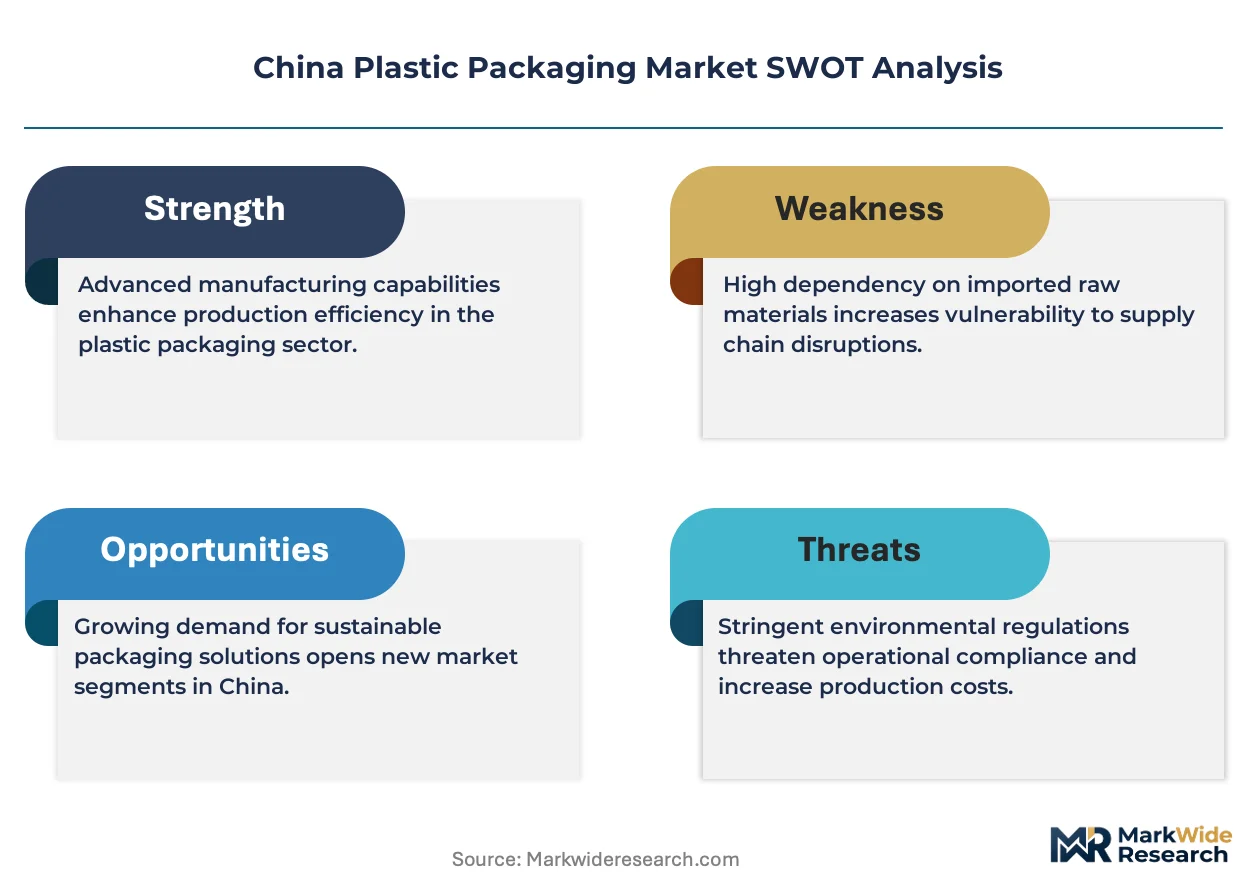
SAMR enforces food-contact material safety standards that reshape resin selection and additive formulations, while MEE implements waste-sorting and extended producer responsibility rules that force redesign of multi-layer structures. GB standards on recyclability and the dual carbon goals are pushing converters toward mono-material constructions and post-consumer recycled content integration. Stakeholders must monitor how provincial enforcement of these frameworks varies between manufacturing hubs like Guangdong and Zhejiang.
Market Dynamics
China's plastic packaging sector is undergoing a structural recalibration as MEE's extended producer responsibility rules force converters to redesign multi-layer films into mono-material formats compatible with municipal sorting infrastructure. This regulatory compression is reshaping resin selection, additive formulations, and converter capital allocation across the Yangtze River Delta manufacturing cluster.
Growth Catalysts
- E-commerce logistics expansion:Platform giants in fresh-food and consumer goods delivery are consolidating orders for standardized protective formats, driving volume through automated fulfillment centers in Jiangsu and Zhejiang provinces.
- GB standards evolution:National recyclability mandates under the dual carbon goals are accelerating post-consumer recycled content integration, creating compliant supply channels for export-oriented brands.
- Healthcare sterilizable formats:Pharmaceutical packaging demand for barrier-grade polymer containers is expanding as domestic drug manufacturing scales under NMPA quality reforms.
Market Restraints
- Petrochemical input volatility:Crude-linked resin pricing exposes converters to margin compression, particularly for polypropylene and polyethylene grades used in rigid container production.
- Multi-layer technical lock-in:Existing high-barrier film assets cannot easily retrofit to mono-material constructions, stranding capital in legacy extrusion lines across Guangdong province.
- Substitution by fiber-based formats:Molded pulp and paperboard alternatives are capturing premium food-service applications as SAMR tightens single-use plastic restrictions in urban consumption zones.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization infrastructure development in Shandong province offers closed-loop feedstock security for converters facing virgin resin cost pressure.
- Smart packaging integration:QR-traceable films combining polymer substrates with printed electronics are enabling anti-counterfeiting and supply-chain visibility for pharmaceutical and luxury goods clients.
- Inland manufacturing relocation:Central China provinces including Henan and Hubei offer labor cost advantages and proximity to emerging consumption centers as coastal wages rise.
Industry Challenges
- Mono-material R&D talent scarcity:Formulation chemists capable of matching multi-layer barrier performance in single-polymer constructions command premium compensation, constraining mid-tier converter technical capacity.
- GB certification timeline compression:Accelerated standard revisions for food-contact safety require rapid requalification of additive packages, disrupting production schedules for regional processors.
- Sorting infrastructure misalignment:Municipal waste systems in lower-tier cities lack optical separation capability, rendering technically recyclable formats non-viable in practice despite material compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plastic Packaging Market |
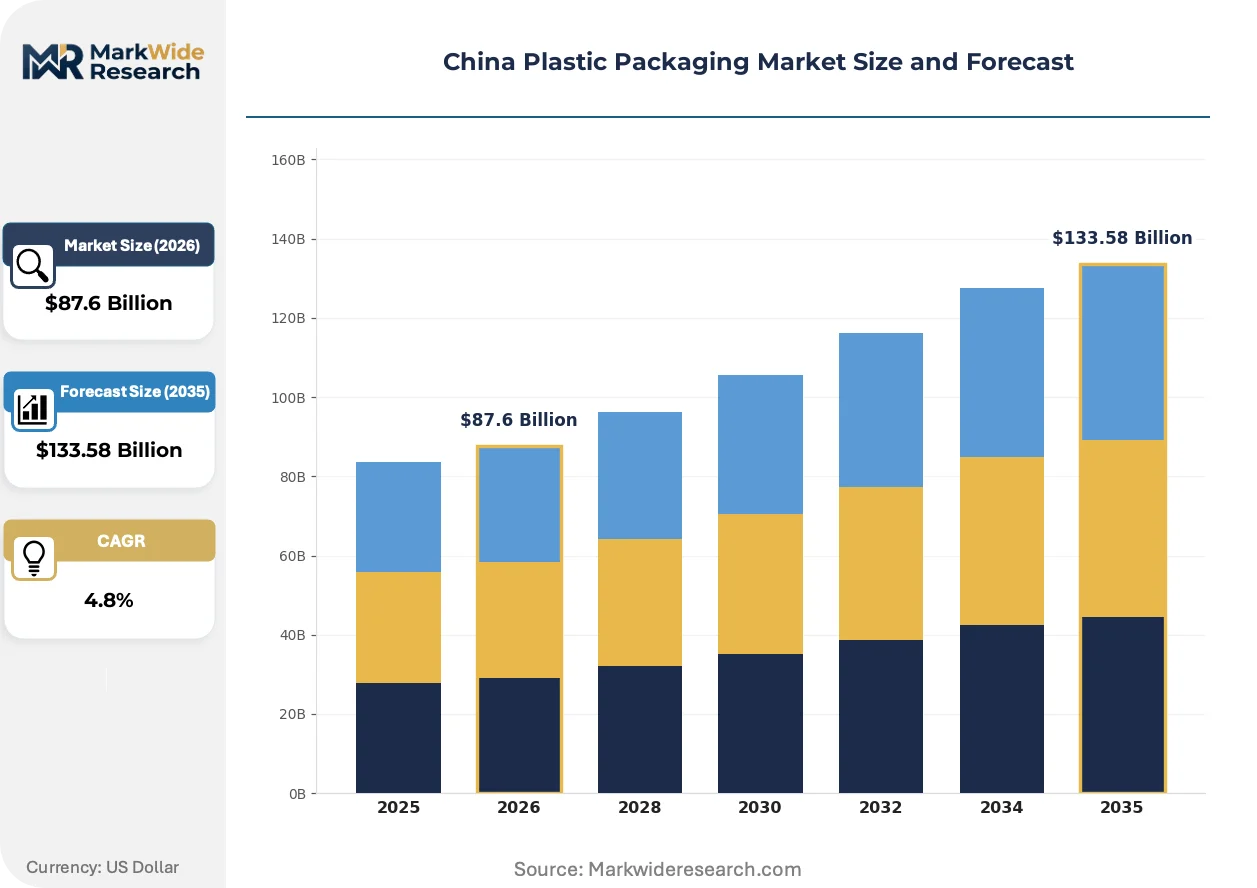
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Film & Sheet, Edge Boards End User: Food & Beverage, Healthcare, Consumer Goods, Industrial Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Retail Packaging, Pharmaceutical Packaging, Industrial Packaging, Food Packaging |
| Companies Covered | Berry Global Inc., Taizhou Huangyan Baitong Plastic Co. Ltd, Shangdong Haishengyu Plastic Industry Co. Ltd, Jieshou Tianhong New Material Co. Ltd, Shenyang Powerful Packing, Co., Ltd., ALPLA Werke Alwin Lehner GmbH & Co KG, Silgan Holdings Inc., Qingdao Haoyu Packing Co. Ltd, Amcor Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plastic Packaging Market Emerging Trajectories
Digital printing and material informatics are converging to compress development cycles and enable mass customization in a market historically dominated by long-run commodity formats. These shifts are redistributing value capture toward equipment suppliers and design-service intermediaries.
Digitally printed flexible packaging is decentralizing production geography by eliminating plate costs and enabling economically viable runs below five thousand units. Regional food brands in Sichuan and Hunan provinces are adopting this capability to support SKU proliferation in spicy snack and fermented food categories. The technology is compressing lead times from weeks to days and enabling converters to site production closer to dispersed agricultural processing clusters rather than centralized coastal hubs.
MEE's waste-sorting regulations are mandating standardized resin identification and mono-material constructions for household packaging by 2025. This policy is forcing reformulation of laminated snack bags and multi-layer pharmaceutical blisters into separable or single-polymer alternatives. Beverage and personal care segments in Shanghai and Jiangsu are responding fastest, with preform and bottle converters already certifying recycled-content PET streams through SAMR compliance pathways.
Platform-driven consolidated procurement is compressing supplier bases as e-commerce giants standardize specifications across private-label and third-party vendor networks. Tier-one converters with certified quality systems and national logistics coverage are displacing fragmented regional suppliers in fresh-food delivery and electronics protective packaging. This concentration is most visible in the Yangtze River Delta, where Alibaba and JD.com fulfillment networks have reduced active film suppliers by half over three contract cycles.
China Plastic Packaging Market Segmentation
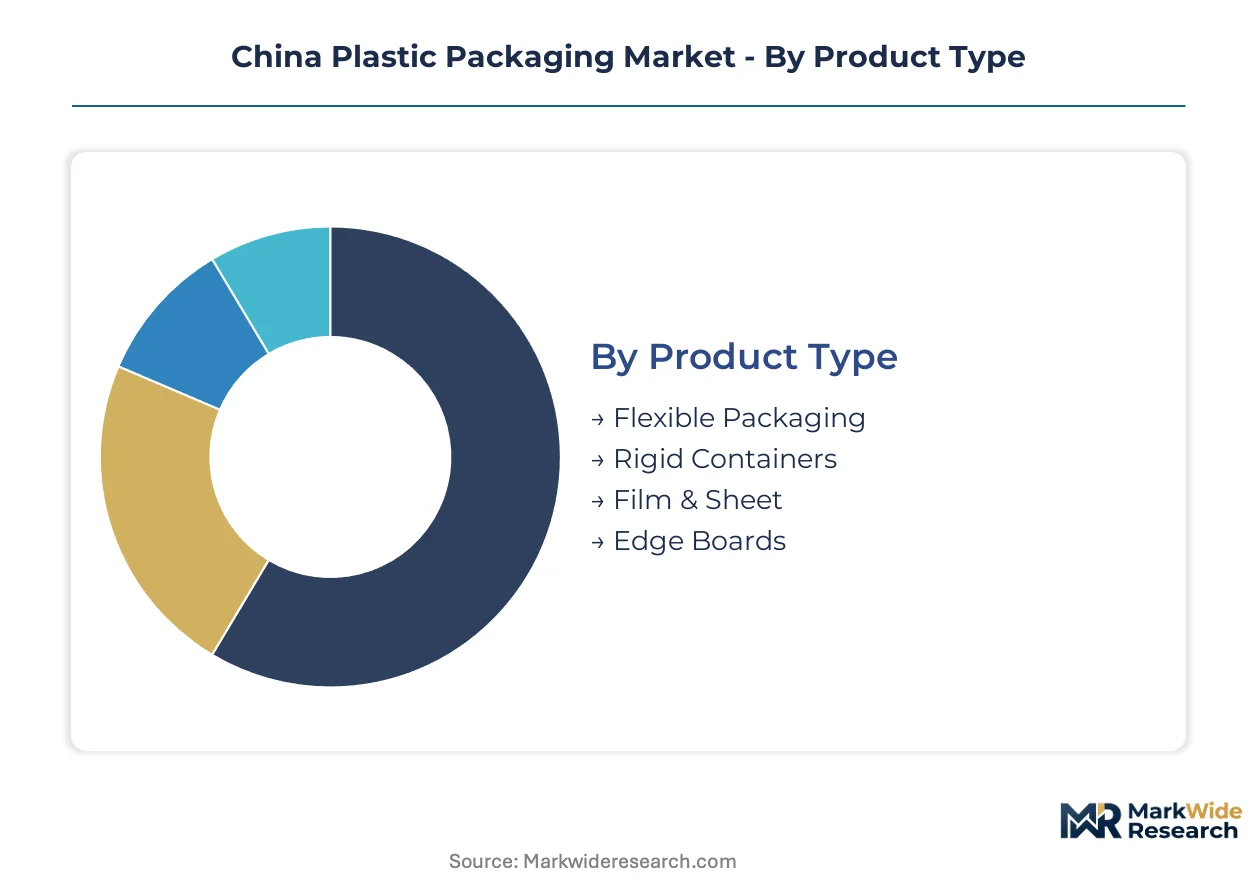
Segmentation in China's plastic packaging market reveals how regulatory pressure and end-use specialization are fragmenting converter capabilities. Each dimension—product format, material chemistry, and application—carries distinct compliance burdens and margin profiles under evolving GB standards.
Product Type:
Standalone protective formats dominate high-volume placements, while embedded barrier systems serve precision end-uses demanding integration with filling equipment.
- Flexible Packaging:Multi-layer films and pouches formed through blown or cast extrusion with thickness ranging from 20 to 150 microns. Demand concentrates in Yangtze River Delta snack manufacturers and fresh-food delivery platforms as SAMR tightens food-contact migration limits. MEE's mono-material mandates are forcing rapid redesign of laminated structures.
- Rigid Containers:Injection or blow-molded vessels with wall thickness above 0.5 millimeters engineered for stack strength and seal integrity. Beverage bottlers in Guangdong and Shandong provinces anchor volume, though pharmaceutical sterilizable formats are climbing fastest under NMPA quality reforms.
- Film & Sheet:Flat extruded or calendered polymer webs serving thermoforming feedstock and surface protection applications.
- Edge Boards:Angular extruded profiles protecting palletized cargo corners during e-commerce fulfillment transit.
Volume placements concentrate in Flexible Packaging; the faster expansion belongs to Rigid Containers.
End User:
Cost-tier stratification separates commodity processors from compliance-grade buyers, with certification requirements widening the margin gap between tiers.
- Food & Beverage:Processors of instant noodles, dairy, and ready-to-eat meals requiring oxygen and moisture barriers. Platform giants in Jiangsu and Zhejiang provinces are consolidating procurement for standardized delivery formats under SAMR's evolving safety standards.
- Healthcare:Sterilizable polymer containers and barrier blisters for domestic drug manufacturing. NMPA's quality reforms are accelerating substitution of glass with polymer formats in Shanghai and Jiangsu pharmaceutical clusters.
- Consumer Goods:Personal care and electronics protective packaging serving premium brand positioning.
- Industrial:Chemical containment and component protection for manufacturing supply chains.
Food & Beverage captures the largest volume base; Healthcare is expanding most quickly.
Material:
Application maturity dictates resin selection, with established grades serving scale markets and specialty polymers penetrating compliance-driven niches.
- Polyethylene:LDPE and LLDPE films dominate flexible formats due to sealability and puncture resistance. Fresh-food delivery platforms in the Yangtze River Delta are standardizing PE-based mono-material pouches to meet MEE sorting requirements.
- Polypropylene:High-clarity grades serve rigid containers and microwaveable trays. Snack and dairy processors in Guangdong province prefer PP for heat resistance and recyclability certification under dual carbon goals.
- Polyvinyl Chloride:Pharmaceutical blister packs and medical tubing requiring rigidity and chemical stability.
- Polystyrene:Foam protective formats and clear rigid trays for electronics and food service applications.
Polyethylene holds the dominant volume position; Polypropylene is gaining share fastest.
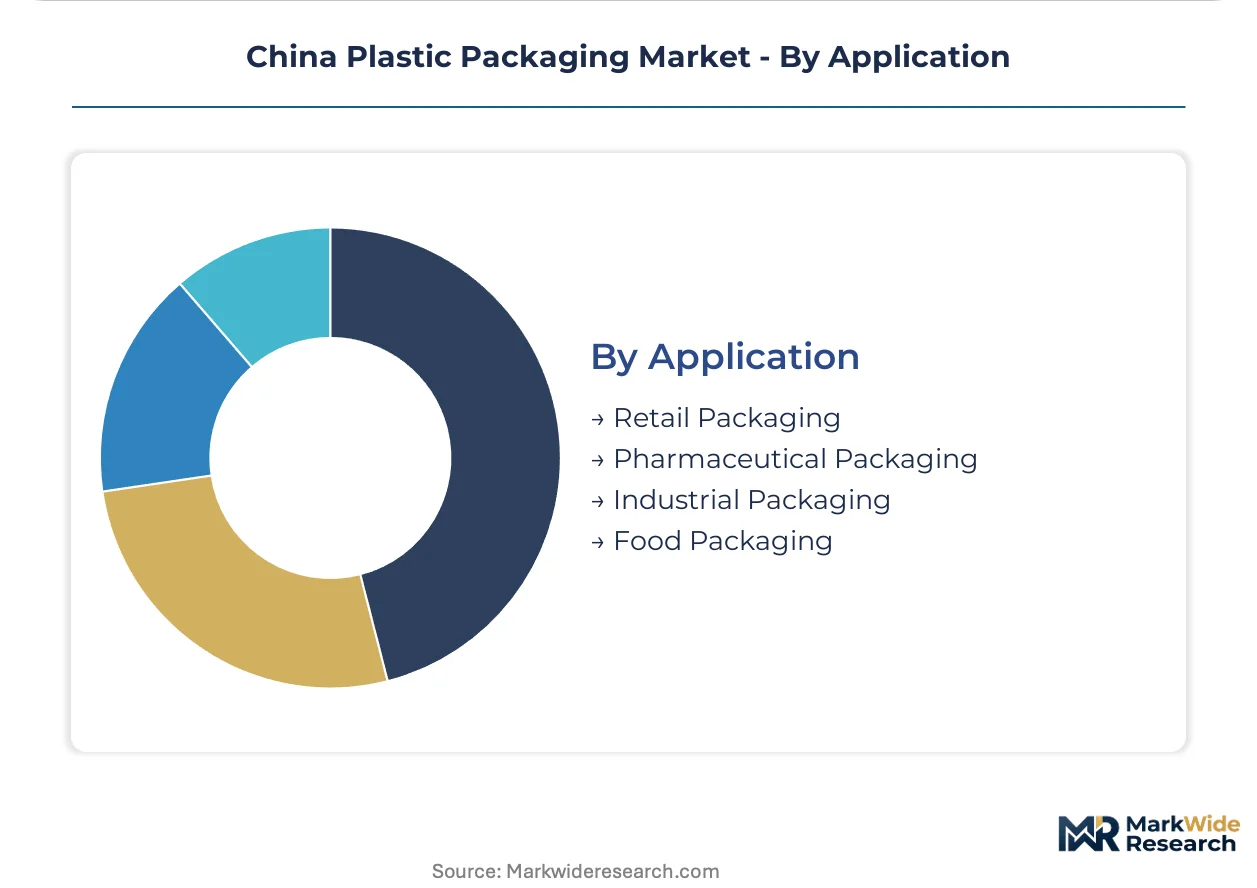
Application:
Customer-type differentiation separates mass retail from institutional procurement, with specification depth varying sharply between channels.
- Retail Packaging:Shelf-ready formats combining barrier performance with printable surfaces. FMCG brands in coastal provinces are adopting digitally printed flexible films to support SKU proliferation.
- Pharmaceutical Packaging:Compliance-grade containers and blisters meeting NMPA stability and sterility requirements. Domestic drug manufacturers are scaling polymer format adoption as quality reforms tighten.
- Industrial Packaging:Bulk containment and protective systems for manufacturing and logistics.
- Food Packaging:Direct-contact formats spanning flexible pouches, rigid trays, and modified-atmosphere structures.
Retail Packaging commands the highest placement volume; Pharmaceutical Packaging follows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock access along China's eastern seaboard anchors converter concentration, with resin supply chains clustering around Ningbo, Dalian, and Maoming refining complexes. Provincial enforcement of MEE waste-sorting mandates varies sharply between manufacturing hubs.
Yangtze River Delta
E-commerce fulfillment networks in Jiangsu and Zhejiang provinces drive standardized protective packaging procurement. SAMR's food-contact migration limits tighten additive specifications for snack and dairy processors. Shanghai-based converters are certifying mono-material film constructions ahead of GB recyclability deadlines.
Pearl River Delta
Guangdong's beverage bottlers and electronics assemblers sustain rigid container demand. MEE extended producer responsibility rules force redesign of multi-layer structures in Shenzhen and Dongguan. Legacy extrusion assets face stranded capital risk as mono-material mandates accelerate.
Shandong Peninsula
Chemical recycling infrastructure development in Qingdao and Yantai offers pyrolysis-based feedstock alternatives. Provincial industrial policy supports closed-loop resin recovery for converters facing virgin polyethylene cost pressure. Regional food processors are qualifying post-consumer recycled content streams.
Sichuan-Chongqing
Inland consumption growth in Chengdu and Chongqing attracts packaging converters seeking labor cost relief from coastal wage inflation. Digitally printed flexible formats enable shorter runs for regional spicy snack brands. Provincial logistics networks remain less integrated with automated sorting infrastructure.
Beijing-Tianjin-Hebei
Pharmaceutical packaging demand concentrates under NMPA quality reforms in Beijing's drug development corridor. Sterilizable polymer container adoption accelerates as domestic manufacturers substitute glass formats. Municipal waste systems in Tianjin lag in optical separation capability despite material compliance advances.
China Plastic Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digitally enabled customization and chemical recycling integration. Market structure tilts toward consolidation as platform giants consolidate supplier bases through standardized procurement. Three archetypes dominate: multinational technical specialists, domestic scale players, and regional cost-competitive fabricators. Competitive dynamics center on backward integration into resin recovery and geographic expansion toward inland consumption centers.
Among multinational specialists, Berry Global Inc. and ALPLA Werke Alwin Lehner GmbH & Co KG exemplify technical-grade positioning, while Shangdong Haishengyu Plastic Industry Co. Ltd anchors domestic supply capacity. These three occupy distinct tier positions that reflect divergent capital intensity and certification requirements under evolving SAMR and MEE frameworks.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Taizhou Huangyan Baitong Plastic Co. Ltd |
| Shangdong Haishengyu Plastic Industry Co. Ltd |
| Jieshou Tianhong New Material Co. Ltd |
| Shenyang Powerful Packing, Co., Ltd. |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Silgan Holdings Inc. |
| Qingdao Haoyu Packing Co. Ltd |
| Amcor Group |
| Others |
Supply Flow & Price Mechanics
Polypropylene spot price movements on the Dalian Commodity Exchange cascade through converter tiers, compressing margins for rigid container producers while rewarding flexible film specialists with backward integration into resin trading. SAMR certification requirements and MEE sorting mandates add compliance premiums that stratify pricing across coastal and inland manufacturing clusters.
Pricing Analysis
After-sales technical support and SAMR requalification services are bundled into premium tier contracts, while standard tiers strip these to compete on unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in economy-tier rigid containers is intensifying because of petrochemical input volatility and stranded multi-layer asset depreciation. Fresh-food delivery platforms in Jiangsu province exhibit highest price sensitivity; pharmaceutical sterilizable format buyers show least.
Supply Chain Analysis
Regional distribution centers in Ningbo, Qingdao, and Maoming form a hub-and-spoke pattern feeding converters across coastal provinces. Raw material supply draws from Saudi ethylene crackers, South Korean polyethylene exports, and domestic Sinopec refining complexes. Single-source vulnerability concentrates in high-barrier additive imports from German and Japanese specialty chemical suppliers. Distribution runs through bonded warehouse networks serving Yangtze River Delta export-oriented brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's plastic packaging sector sits in a materials-transition phase as mono-material films displace multi-layer laminates under MEE sorting mandates. Digital printing and chemical recycling infrastructure are replacing legacy extrusion and mechanical recycling assets.
For Market Incumbents: Anticipate stranded asset risk in Guangdong's multi-layer film capacity by accelerating mono-material R&D partnerships with polymer suppliers. Secure SAMR pre-approval for additive packages before GB standard revisions tighten. Defensive consolidation through captive pyrolysis feedstock in Shandong province hedges virgin resin cost exposure.
For New Entrants and Emerging Players: Launch via digitally printed flexible packaging services targeting Sichuan and Hunan spicy snack brands with sub-five-thousand-unit runs. White-space concentrates in inland provinces lacking automated fulfillment integration. Partner with agricultural processing clusters bypassing centralized coastal converter networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with SAMR-certified mono-material lines in Henan and Hubei provinces facing liquidity pressure from coastal wage inflation. Long-term viability hinges on chemical recycling feedstock integration and NMPA pharmaceutical packaging qualification. Watch MEE provincial enforcement variance between manufacturing hubs as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format Conversion | MEE sorting mandates force redesign of laminated structures into recyclable single-polymer alternatives. |
| Chemical Recycling Infrastructure Buildout | Pyrolysis capacity in Shandong province offers closed-loop feedstock security against virgin resin volatility. |
| Digital Printing Capability Deployment | Plateless production enables economically viable short runs for regional food brands in inland provinces. |
| SAMR Certification Pre-Positioning | Early additive package requalification secures supply relationships ahead of accelerated GB standard revisions. |
| Inland Manufacturing Relocation | Central China provinces offer labor cost relief and proximity to emerging consumption centers as coastal wages rise. |
Methodological Framework
Multi-period observation of resin price indices, SAMR certification timelines, and MEE enforcement variance anchored the trend analysis, supplemented by interviews with converter plant managers, polymer procurement leads at downstream food processors, distribution channel partners in bonded warehouse networks, and technical R&D directors at flexible film specialists. Secondary validation drew from customs trade data, Sinopec production disclosures, GB standard revision drafts, and provincial environmental bureau filings. Bottom-up capacity modeling and top-down demand estimation were triangulated against e-commerce fulfillment network expansion metrics.
Segment-weighting across product format, material chemistry, end-use industry, and regional regulatory cluster shaped the analytical framework throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Industry-specific inputs included platform procurement consolidation rates and NMPA pharmaceutical packaging adoption curves.
Petrochemical price volatility, SAMR standard acceleration, and provincial MEE enforcement inconsistency are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around resin supply continuity and sorting infrastructure deployment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
GCC PET Packaging Market