
 Europe Plastic Bottles Market | 2026-2036
Europe Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Bottles Market Insights
Pharmaceutical and personal care buyers is reorganizing demand patterns across Europe, pulling volume away from traditional beverage-centric procurement. Amcor Group GmbH leverages its continental manufacturing footprint to serve these shifting buyers. Gerresheimer AG specializes in high-barrier pharmaceutical-grade formats that meet stringent EU compliance. ALPLA Group anchors supply through its extensive recycling infrastructure network.
Europe plastic bottles are hollow containers formed through extrusion blow molding, injection blow molding, or stretch blow molding, typically ranging from 10 milliliters to 20 liters in capacity, with wall thickness calibrated for specific barrier requirements against moisture, oxygen, or UV light. They serve as primary packaging for liquid and semi-solid goods across consumer and industrial supply chains. PET dominates the product type landscape due to its clarity, lightweight properties, and established recycling streams, while HDPE retains strength in household and chemical applications where chemical resistance outweighs transparency needs. The application split reveals beverages as the mature volume base, with pharmaceuticals and personal care representing faster-margin expansion zones where regulatory compliance commands premium positioning.
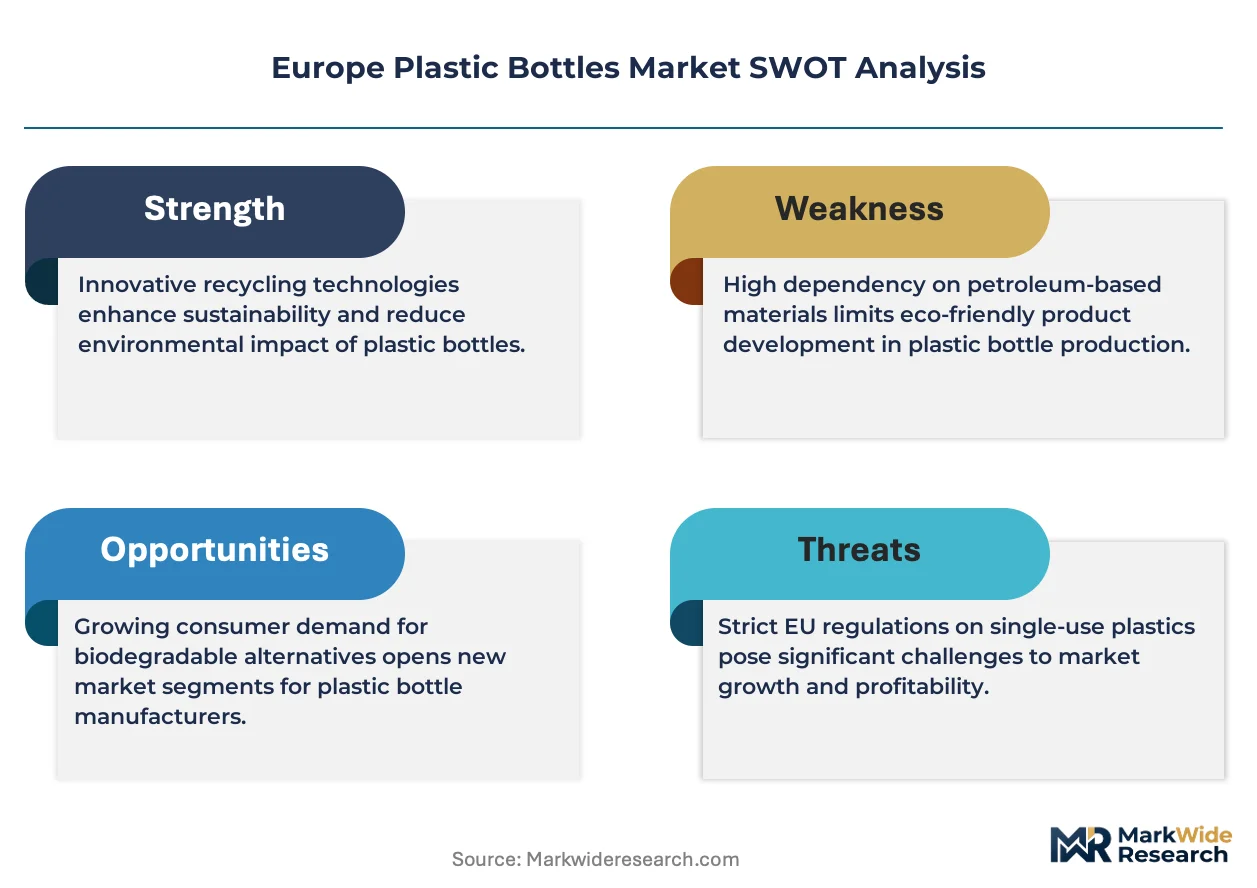
REACH, the EU Green Deal, and the Packaging and Packaging Waste Regulation shape material selection, recyclability mandates, and extended producer obligations across member states. ECHA enforcement of substance restrictions limits certain additives, while the EU Green Deal's circular economy targets push minimum recycled content thresholds. Stakeholders must weigh recycling technology investments against reformulation costs as compliance timelines tighten.
Market Dynamics
REACH substance restrictions and the EU Green Deal's recycled content mandates are forcing converters to re-engineer material formulations and retrofit extrusion lines simultaneously, compressing margins while opening premium positioning for compliant suppliers.
Growth Catalysts
- Pharmaceutical packaging migration:EU MDR compliance requirements and serialization mandates drive demand for high-barrier PET and COP bottles across German and French drug manufacturers.
- rPET infrastructure scale-up:Mechanical and chemical recycling capacity expansion in Italy, Spain, and the Netherlands enables food-grade recycled content integration at industrial volumes.
- Extended Producer Responsibility tightening:The Packaging and Packaging Waste Regulation shifts cost burdens upstream, incentivizing lightweighting and design-for-recycling investments among converters.
Market Restraints
- Feedstock cost volatility:Purified terephthalic acid and ethylene glycol prices track naphtha and paraxylene markets, exposing converters to petrochemical cycle swings without pass-through mechanisms.
- Recycling technology concentration:Advanced rPET decontamination and chemical recycling assets cluster in Germany, Benelux, and northern Italy, creating supply bottlenecks for southern and eastern European converters.
- Glass substitution in premium segments:Cosmetics and spirits brands in France and Italy revert to glass for perceived sustainability, eroding PET's share in high-margin decorative formats.
Strategic Opportunities
- Central and Eastern Europe penetration:Poland, Czech Republic, and Romania show underdeveloped pharmaceutical-grade blow molding capacity relative to growing CMO and generics manufacturing.
- Refill and reuse system integration:Concentrate and dilutable formulations for home care and personal care create demand for durable HDPE bottles engineered for 20+ use cycles.
- Digital watermarking and AI sorting:HolyGrail 2.0 tracer technologies converge with near-infrared sorting infrastructure to enable closed-loop food-grade recovery at scale.
Industry Challenges
- Food contact notification timelines:ECHA's novel substance evaluation and EFSA migration testing protocols extend rPET approval cycles to 18-24 months, delaying commercialization.
- Legacy extrusion asset retrofitting:Converters face capital intensity for barrier co-injection and multilayer blow molding upgrades required for oxygen-sensitive pharmaceuticals.
- Recyclate quality variability:Input stream inconsistency from municipal collection systems forces real-time process adjustments, degrading yield rates and mechanical properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Bottles Market |
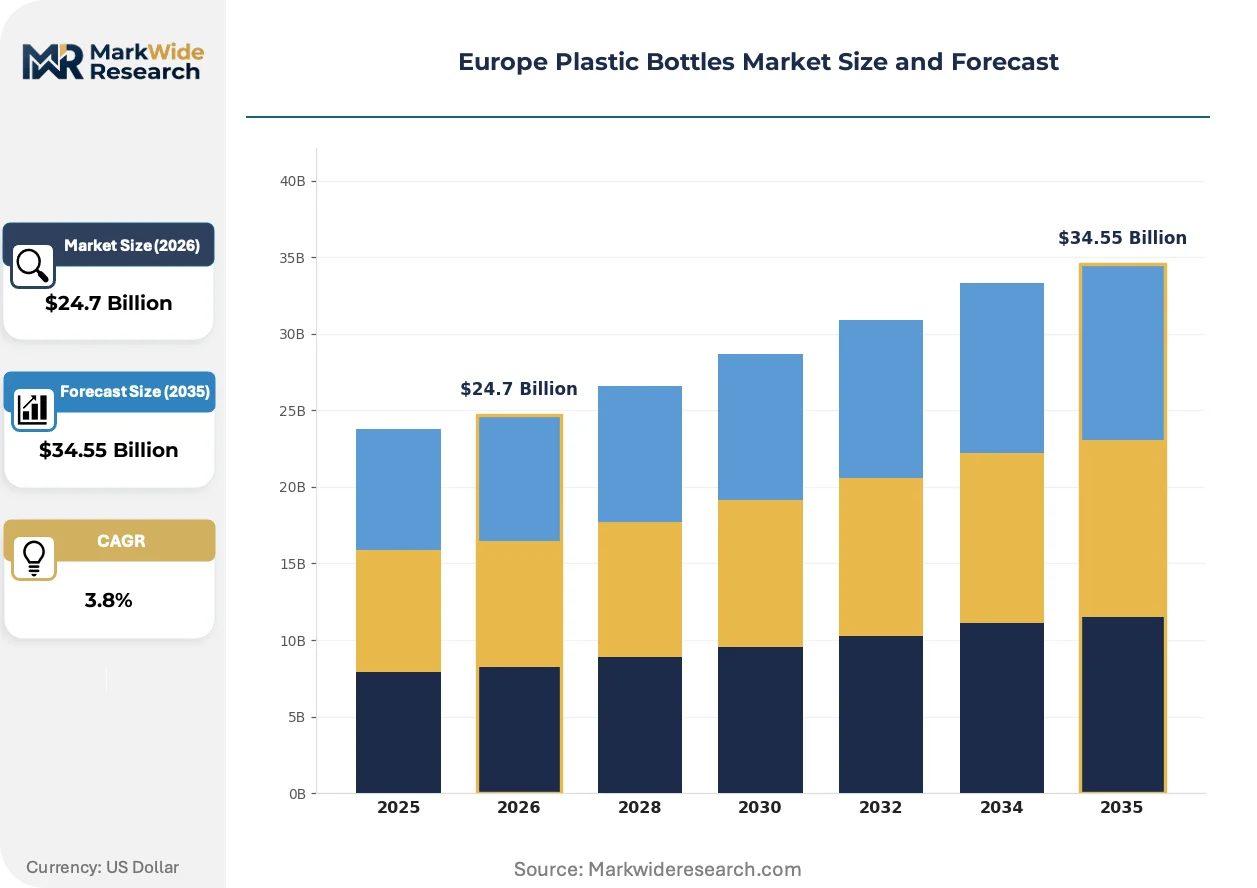
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $34.55 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC Application: Beverages, Personal Care, Household Products, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Consumers Cap Type: Screw Caps, Snap Caps, Pump Dispensers, Others |
| Companies Covered | Amcor Group GmbH, Gerresheimer AG, ALPLA Group, Berry Global Inc., Plastipak Holdings Inc., Resilux NV, Greiner Packaging International GmbH, Graham Packaging Company LP, Alpha Packaging Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Bottles Market Trends and Innovations
Material science breakthroughs and regulatory compliance automation are converging to redefine bottle performance specifications and manufacturing economics across European conversion facilities.
Mono-material barrier structures incorporating plasma-enhanced chemical vapor deposition coatings are displacing multilayer coextrusion for oxygen-sensitive applications. Pharmaceutical and nutraceutical packagers in Germany and Switzerland are qualifying these formats for 24-month shelf life requirements. The technology is displacing EVOH and nylon interlayers that complicate mechanical recycling streams, enabling single-polymer recovery without separation.
The EU Green Deal's 2030 recycled content targets and the Packaging and Packaging Waste Regulation's extended producer responsibility framework are mandating mass-balance accounting and digital product passports. Converters must deploy blockchain-tracked feedstock certification and automated compliance documentation systems. Small and mid-sized Italian and Spanish blow molders face disproportionate adaptation costs relative to integrated multinational competitors with captive recycling assets.
Brand-led packaging reduction commitments are compressing specification cycles and unbundling traditional converter-distributor relationships. Personal care multinationals now direct-source specialized formats through platform-based procurement, bypassing regional distributors. This pattern concentrates in the UK, Nordics, and Benelux where sustainability transparency requirements are most stringent and retailer private-label penetration is highest.
Europe Plastic Bottles Market Segmentation
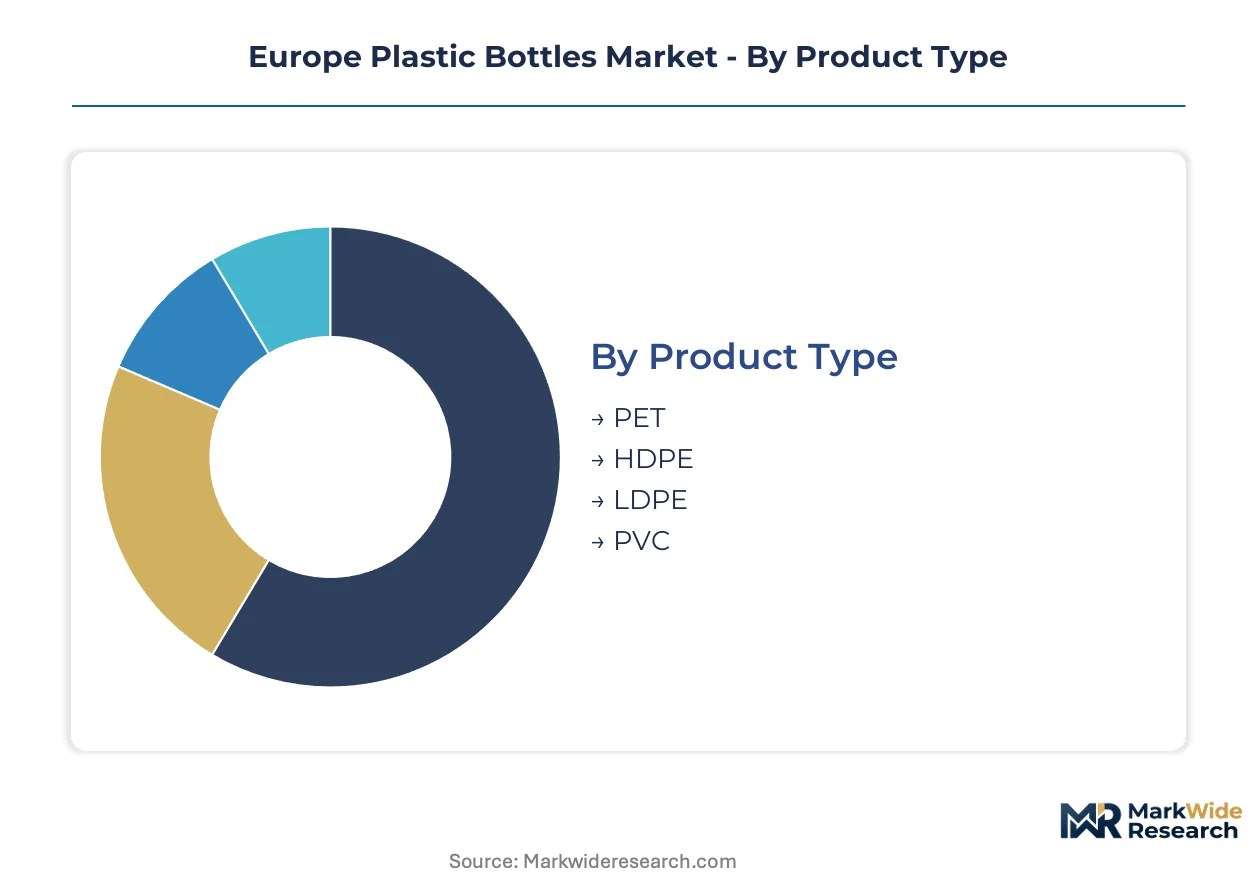
Segmentation in the Europe plastic bottles market reveals how regulatory pressure and end-use specialization fragment converter capabilities. Material choices and closure systems now carry compliance implications that reshape procurement patterns across member states.
Product Type:
Domestic demand concentrates in PET and HDPE formats serving continental beverage and pharmaceutical supply chains, while LDPE and PVC volumes skew toward export-oriented chemical and industrial applications from Benelux and German production hubs.
- PET:Clear, lightweight polyester resin dominates beverage and pharmaceutical primary packaging due to established mechanical recycling infrastructure and EFSA food-contact approvals. German and Italian converters leverage rPET integration to meet EU Green Deal mandates for minimum recycled content in single-use applications.
- HDPE:High-density polyethylene offers chemical resistance and durability for household cleaners, industrial chemicals, and durable refillable formats. French and Benelux demand concentrates in concentrate-and-dilute home care systems requiring 20+ use-cycle structural integrity.
- LDPE:Flexible low-density formats serve squeeze bottles and industrial lubricant containers where deformation tolerance outweighs barrier requirements.
- PVC:Chlorinated polymer retains niche presence in chemical-resistant industrial applications despite REACH substance restriction pressures and limited recycling compatibility.
PET holds the largest share; momentum sits with HDPE as refill system adoption accelerates.
Application:
Cost tier differentiation separates commodity beverage volumes from premium-margin pharmaceutical and personal care formats where compliance documentation commands price premiums.
- Beverages:Mature volume base spanning carbonated soft drinks, water, and juices. Italian and Spanish converters face margin compression from lightweighting mandates and rPET feedstock competition.
- Personal Care:Shampoo, lotion, and cosmetic formats require aesthetic clarity and decoration compatibility. French and UK brands drive specification toward mono-material structures compatible with HolyGrail 2.0 digital watermarking for sorting automation.
- Household Products:Cleaners, detergents, and disinfectants prioritize chemical resistance and child-resistant closure integration. German retailers enforce design-for-recycling standards through private-label procurement.
- Pharmaceuticals:High-barrier bottles for oral solids and liquids demand EU MDR compliance, serialization readiness, and oxygen/moisture protection. Swiss and German drug manufacturers qualify specialized COP and barrier-coated PET formats.
Beverages maintains volume dominance; pharmaceuticals climbs fastest on regulatory premium capture.
End User:
Customer type determines order structure, with manufacturers driving bulk specification and retailers enforcing sustainability transparency through direct platform procurement.
- Manufacturers:Food, beverage, and pharmaceutical producers specify technical requirements and audit converter compliance systems. German automotive chemical manufacturers and French cosmetics formulators maintain captive packaging engineering teams.
- Retailers:Supermarket chains and drugstore networks in the UK, Nordics, and Benelux bypass distributors for direct converter relationships, mandating digital product passports and blockchain-tracked recycled content certification.
- Distributors:Regional packaging wholesalers serve mid-sized Italian and Spanish converters lacking multinational compliance infrastructure, consolidating fragmented demand.
- Consumers:End purchasers influence specification indirectly through refill system participation and deposit-return scheme behavior in Germany, Scandinavia, and the Netherlands.
Retailers are capturing specification authority fastest; manufacturers retain the largest procurement volume.
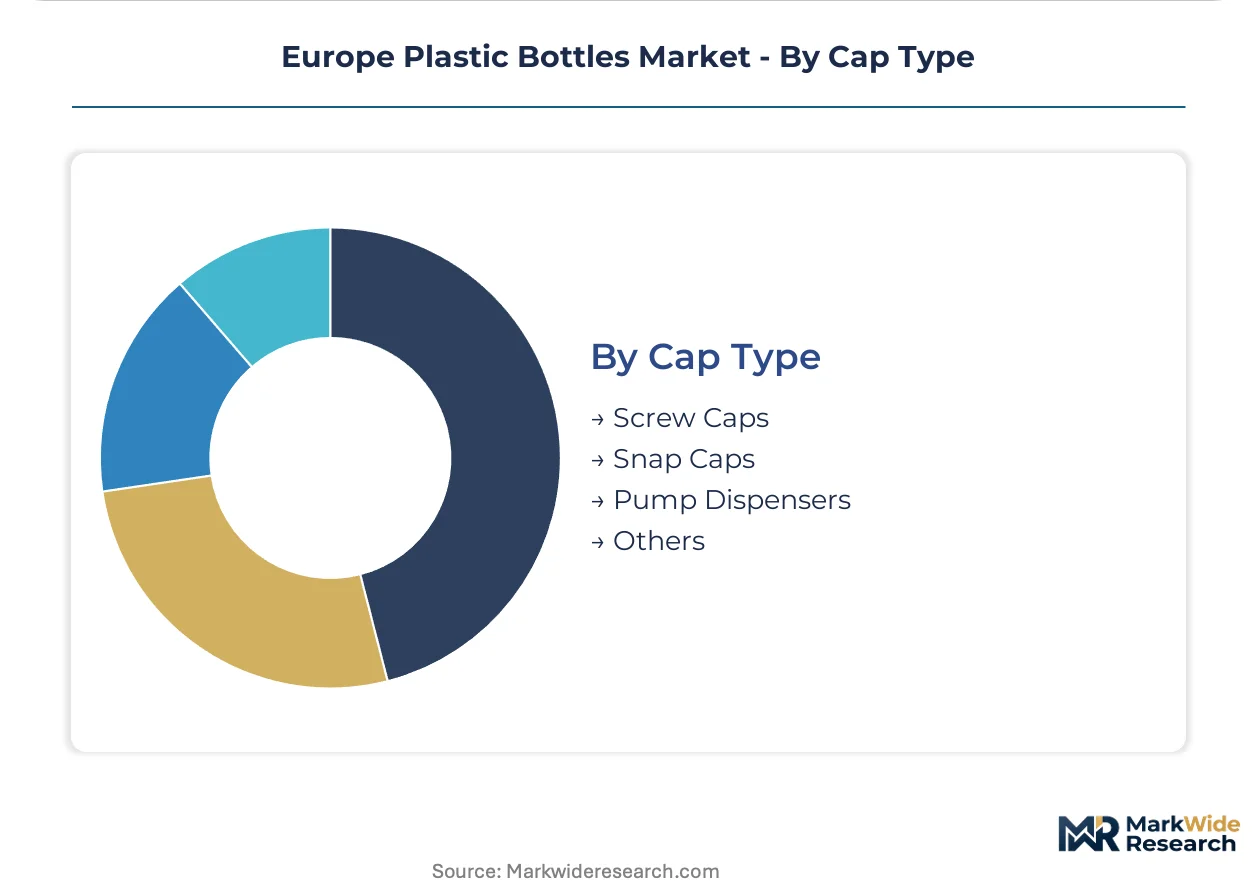
Cap Type:
Closure functionality aligns with application safety and dispensing requirements, with child-resistant and precision-dosing formats commanding engineering premiums.
- Screw Caps:Threaded polyethylene or polypropylene closures dominate beverage and chemical applications. German converters integrate tethered designs to meet Single-Use Plastics Directive requirements.
- Snap Caps:Hinged or push-fit closures serve personal care wipes and convenience food formats where resealability matters less than access speed.
- Pump Dispensers:Precision-metering systems for personal care and pharmaceutical liquids require multi-component assembly and spring compatibility with product chemistry. Swiss and French dispensary manufacturers specialize in high-cycle durability.
- Others:Trigger sprayers, dropper inserts, and specialized pharmaceutical closures serve niche compliance requirements.
Screw caps hold the largest installed base; pump dispensers gain share fastest on personal care premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters along the Rhine corridor and northern Italian industrial zones, with regulatory enforcement intensity varying across member states. National implementation of EU Green Deal targets creates divergent compliance timelines for cross-border suppliers.
Germany
Pharmaceutical-grade blow molding demand from Bavarian and Baden-Württemberg drug manufacturers drives specialized PET and COP format qualification. ECHA substance restriction enforcement tightens additive approval timelines for converters serving medical device packaging. The Düsseldorf-Cologne corridor hosts integrated rPET decontamination assets supplying food-grade recycled content to beverage packagers.
France
Cosmetics and spirits brands in Île-de-France revert to glass for premium positioning, eroding PET share in decorative high-margin formats. The Packaging and Packaging Waste Regulation shifts extended producer responsibility cost burdens onto converters supplying Paris-based retailers. Lyon and Marseille production hubs face margin compression from lightweighting mandates and tethered closure requirements under the Single-Use Plastics Directive.
Italy
Mechanical recycling infrastructure in Lombardy and Emilia-Romagna enables industrial-scale rPET integration for beverage and food contact applications. REACH compliance documentation requirements extend approval cycles for converters serving export-oriented pharmaceutical customers. The Bologna-Modena corridor concentrates barrier coating technology development for oxygen-sensitive nutraceutical packaging.
Netherlands
Chemical recycling pilot plants in Rotterdam and Eindhoven process contaminated PET waste streams unsuitable for mechanical routes. The EU Green Deal's circular economy targets accelerate minimum recycled content mandates for converters supplying Dutch retailer private-label programs. Randstad distribution networks enable just-in-time delivery to Benelux beverage bottlers with stringent carbon footprint reporting requirements.
Poland
Underdeveloped pharmaceutical-grade blow molding capacity relative to growing contract manufacturing organization demand creates supply gaps for oral solid dosage packaging. Warsaw and Łódź converters face technical upgrading costs for EU MDR compliance and serialization infrastructure. Central European logistics positioning attracts German and French brand owners seeking nearshoring alternatives to Asian supply sources.
Europe Plastic Bottles Market Competitive Landscape
Concentration sits with integrated multinational converters possessing captive recycling assets and pan-European manufacturing footprints. Tiered competitive structure separates premium pharmaceutical-grade specialists from commodity beverage-focused volume players. Strategic archetypes include full-service packaging conglomerates, regional recycling-integrated specialists, and niche pharmaceutical barrier technology developers. Capacity expansion and M&A consolidation dominate competitive moves as converters seek scale economies for compliance technology investments.
Among Germany-based pharmaceutical packaging specialists, Gerresheimer AG exemplifies the high-barrier compliance tier with COP and coated PET formats meeting Swissmedic and EMA requirements. Amcor Group GmbH anchors the multinational integrated archetype through continental manufacturing scale and mass-balance rPET certification capabilities. ALPLA Group represents the recycling-integrated model with extensive mechanical and chemical recycling infrastructure spanning Austria, Germany, and Italy.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Gerresheimer AG |
| ALPLA Group |
| Berry Global Inc. |
| Plastipak Holdings Inc. |
| Resilux NV |
| Greiner Packaging International GmbH |
| Graham Packaging Company LP |
| Alpha Packaging Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal recycled content mandates and REACH substance restrictions gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant converters while rewarding integrated players with captive rPET assets and mass-balance certification capabilities.
Pricing Analysis
REACH and the EU Green Deal dictate the pricing tier structure across European plastic bottles, separating pharmaceutical-grade barrier formats from commodity beverage volumes. Three-tier pricing stratifies across premium certified rPET, standard virgin PET, and economy non-food-grade recyclate tiers. Price differentiation rests on EFSA food-contact approval status and mass-balance certification tier. Cost compression in standard beverage-grade PET is intensifying because Italian and Spanish converters compete for limited food-grade rPET feedstock. Brand owners in German retail private-label programs show least price sensitivity for blockchain-tracked recycled content documentation.
Supply Chain Analysis
Germany, Italy, and the Netherlands anchor European plastic bottle supply through integrated blow molding and recycling infrastructure clusters. Raw material flows draw from purified terephthalic acid and ethylene glycol producers in the ARA refining hub, plus mechanical and chemical recycling facilities in Lombardy and Rotterdam. Single-source vulnerability concentrates in advanced rPET decontamination assets clustered along the Rhine corridor. Distribution runs through Randstad logistics networks serving Benelux beverage bottlers with just-in-time carbon footprint reporting requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-based procurement systems and digital product passport interoperability are reconfiguring converter-distributor relationships across European plastic bottles, creating winner-take-most dynamics for compliance-automation leaders.
For Market Incumbents: Consolidate through selective acquisition of Central and Eastern European blow molders lacking EU MDR compliance infrastructure, capturing contract manufacturing organization demand in Poland and Romania. Prioritize backward integration into chemical recycling assets to secure food-grade rPET supply independence from mechanical recycling bottlenecks. Defend margin position by deploying blockchain-tracked mass-balance certification systems that German and Benelux retailers now mandate for direct platform procurement. For New Entrants and Emerging Players: EFSA fast-track approval for novel barrier coating technologies opens white-space penetration in oxygen-sensitive pharmaceutical and nutraceutical packaging. Target underdeveloped pharmaceutical-grade blow molding capacity in Poland, Czech Republic, and Romania where CMO demand outpaces qualified supply. Pursue co-development partnerships with Swiss and German drug manufacturers seeking COP and coated PET alternatives to glass for serialization-ready oral solid dosage formats. For Investors and Strategic Acquirers: The Packaging and Packaging Waste Regulation's extended producer responsibility implementation reshapes the acquisition landscape toward recycling-integrated converters with digital compliance infrastructure. Five-to-ten-year viability favors mid-cap Italian and Spanish blow molders possessing mechanical recycling assets but lacking capital for chemical recycling and AI sorting technology upgrades. Watch for inflection in HolyGrail 2.0 digital watermarking adoption rates as signal for sorting infrastructure monetization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Capacity Buildout | Enables food-grade rPET supply independence from mechanical recycling quality constraints. |
| Barrier Coating Technology Licensing | Positions converters for EU MDR-compliant pharmaceutical packaging qualification. |
| Digital Product Passport Integration | Meets German retailer blockchain-tracked recycled content certification requirements. |
| Central European Manufacturing Footprint | Captures Polish and Romanian CMO demand with nearshored EU MDR compliance. |
| HolyGrail 2.0 Tracer Partnership | Aligns with Dutch and Belgian AI sorting infrastructure for closed-loop recovery. |
Research Methodology
Initial hypotheses were tested against primary input from blow molding plant managers, pharmaceutical packaging procurement leads at German drug manufacturers, retail category buyers in Benelux, and ECHA regulatory affairs specialists, then refined through secondary validation against EU Packaging and Packaging Waste Regulation implementation documents, EFSA food-contact notification databases, Cefic plastics trade statistics, and SEC filings of listed packaging conglomerates. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Variance decomposition across material type, application end-use, and country-level regulatory enforcement intensity shaped the analytical framework throughout the forecast period. CAGRs were derived from installed capacity expansion schedules, rPET integration timelines, and pharmaceutical packaging migration patterns. Industry-specific inputs included ECHA substance restriction amendment pipelines and EU Green Deal minimum recycled content threshold trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and EU Green Deal target adherence; material deviation in chemical recycling cost curves or EFSA approval timelines would warrant model refresh. Recalibration cycles align with material shifts in ECHA restriction list updates and Packaging and Packaging Waste Regulation delegated act implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
PET Preforms Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Global Micro Injection Molded Plastic Market