
 Latin America Single-Use Plastic Packaging Market | 2026-2036
Latin America Single-Use Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Single-Use Plastic Packaging Market Insights
Food-grade specification upgrades across polyethylene and polypropylene grades is bifurcating the Latin America single-use plastic packaging competitive landscape. Amcor Group GmbH leverages its multilayer coextrusion expertise to supply high-barrier flexible formats for protein and dairy applications across Brazilian retail chains. Berry Global Inc anchors regional rigid container production through its thermoforming and injection molding footprint in Mexico and Brazil. Huhtamäki Oyj differentiates via fiber-based and plastic hybrid solutions targeting quick-service restaurant chains seeking operational efficiency in food delivery logistics.
Latin America single-use plastic packaging encompasses disposable containers, films, and wraps engineered from thermoplastic resins—primarily low-density polyethylene, polypropylene homopolymer, and expanded polystyrene—manufactured through extrusion, thermoforming, or injection molding processes designed for one-cycle containment and protection of consumable and industrial goods. Flexible packaging leads volume throughput across the region due to its material efficiency and adaptability to fresh produce and snack food distribution, while rigid packaging commands premium positioning in dairy, ready-meal, and pharmaceutical applications where dimensional stability and seal integrity prove critical. Bioplastics represent the fastest-expanding material segment, though polyethylene retains dominant share across bags and wraps for retail and food service end users where cost thresholds and existing recycling infrastructure govern procurement decisions.
Brazil's ANVISA and Mexico's COFEPRIS enforce food-contact compliance standards that dictate resin purity, additive migration limits, and labeling requirements for single-use plastic packaging serving consumer and healthcare applications. Chile's Ministry of Environment and Peru's OEFA administer extended producer responsibility regulations and single-use restriction schedules that reshape product design priorities and market access conditions for imported and domestically manufactured packaging. Stakeholders must monitor regulatory divergence across Mercosur and Pacific Alliance frameworks, as harmonization failures would fragment compliance costs and sourcing strategies for converters operating multi-country supply networks.
Market Dynamics
Extended producer responsibility mandates across Chile, Argentina, and Peru are forcing converters to reengineer material formulations and establish reverse logistics networks, compressing margins for polyethylene-dependent operations while opening premium positioning for compliant alternatives.
Growth Catalysts
- Food service expansion:Quick-service restaurant chains in Brazil and Mexico are scaling delivery-optimized packaging procurement, driving volume for flexible pouches and rigid clamshells designed for thermal retention and leak resistance.
- ANVISA compliance upgrades:Brazil's food-contact safety standards are accelerating resin purity investments, creating competitive separation for converters with certified polyethylene and polypropylene supply chains.
- Bioplastic feedstock access:Sugarcane-derived ethanol availability in São Paulo state's industrial corridor is enabling local polylactic acid production, reducing import dependency for sustainable packaging alternatives.
Market Restraints
- Petrochemical input volatility:Naphtha and ethylene price swings tied to global crude markets destabilize converter cost structures, particularly for small and mid-scale thermoforming operations in Mexico's Bajío region.
- Recycling infrastructure gaps:Mechanical recycling capacity for multilayer films remains concentrated in Brazil's southeastern states, leaving Andean markets dependent on landfill or export disposal routes.
- Performance limitations of bioplastics:Polylactic acid barrier properties against oxygen and moisture trail conventional polyethylene, restricting adoption in protein and dairy applications requiring extended shelf life.
Strategic Opportunities
- Colombia's Pacific port corridor:Buenaventura's expanding logistics hub offers distribution access to Andean markets with lighter regulatory enforcement, enabling cost-competitive penetration before EPR regimes mature.
- Quick-commerce channel expansion:Fifteen-minute grocery delivery platforms are creating demand for compact, lightweight primary packaging formats optimized for automated picking and last-mile efficiency.
- Peru's OEFA compliance timelines:Staged single-use restriction schedules provide runway for converters to retrofit lines toward paper-plastic hybrid structures ahead of mandatory phase-outs.
Industry Challenges
- Multilayer film reprocessing complexity:Separating polyethylene tie layers from polyamide or EVOH barrier films requires specialized delamination equipment scarce across Latin American recycling facilities.
- Migration testing bottlenecks:ANVISA and COFEPRIS certification queues for novel bioplastic additives extend product launch timelines by eight to fourteen months, freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Single-Use Plastic Packaging Market |
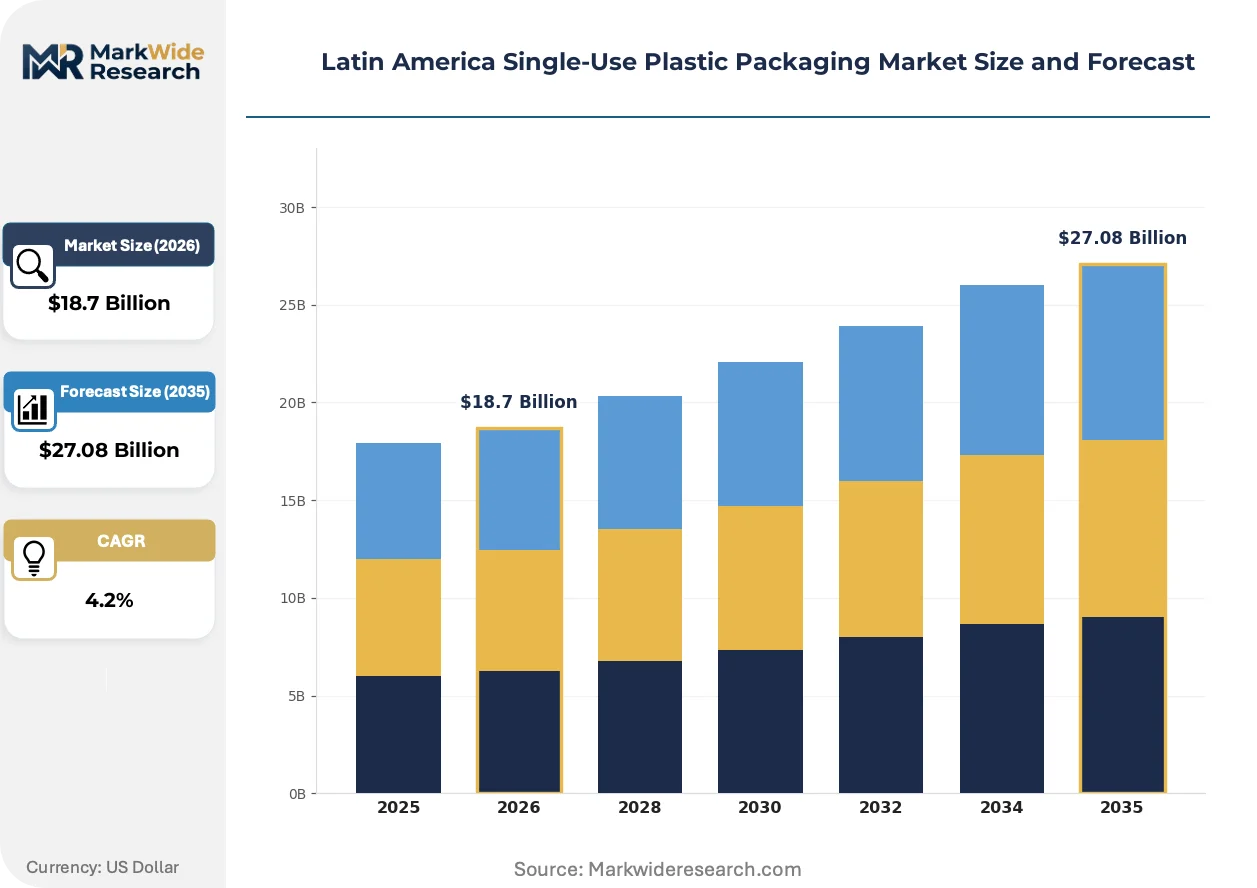
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Bags, Wraps End User: Food Service, Retail, Consumer Goods, Healthcare Material: Polyethylene, Polypropylene, Polystyrene, Bioplastics Application: Food Packaging, Beverage Packaging, Personal Care, Industrial |
| Companies Covered | Dart Container Corporation, Winpak Ltd., Berry Global Inc, Amcor Group GmbH, Huhtamäki Oyj, Sealed Air Corporation, Sonoco Products Company, Mondi Group, ALPLA Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Single-Use Plastic Packaging Market Trends and Innovations
Material-lightening technologies and regulatory compliance automation are restructuring competitive advantage, separating converters with integrated formulation capabilities from commodity-dependent processors.
Mono-material polyethylene structures with enhanced barrier coatings are supplanting conventional multilayer laminates in snack food and frozen vegetable applications. Brazilian retail chains are accelerating qualification timelines for these formats to meet internal sustainability targets. The shift is compressing demand for polyamide and EVOH resin imports while elevating specification requirements for metallocene polyethylene grades.
Chile's Ministry of Environment enforcement protocols for extended producer responsibility are mandating verified recycling content certificates for all imported flexible packaging. Converters serving the Santiago metropolitan market are reconfiguring supply chains to incorporate post-industrial scrap from local collection cooperatives. The policy is most acute for imported films from Asia-Pacific suppliers lacking traceability documentation.
Direct sourcing agreements between quick-service restaurant chains and packaging converters are displacing traditional distributor intermediaries across Mexico's central region. Operators like Alsea and FEMSA are consolidating procurement under master service contracts with volume guarantees and design exclusivity clauses. The pattern is most visible in Mexico City and Guadalajara, where delivery-platform growth has concentrated buyer power among three national account holders.
Latin America Single-Use Plastic Packaging Market Segmentation
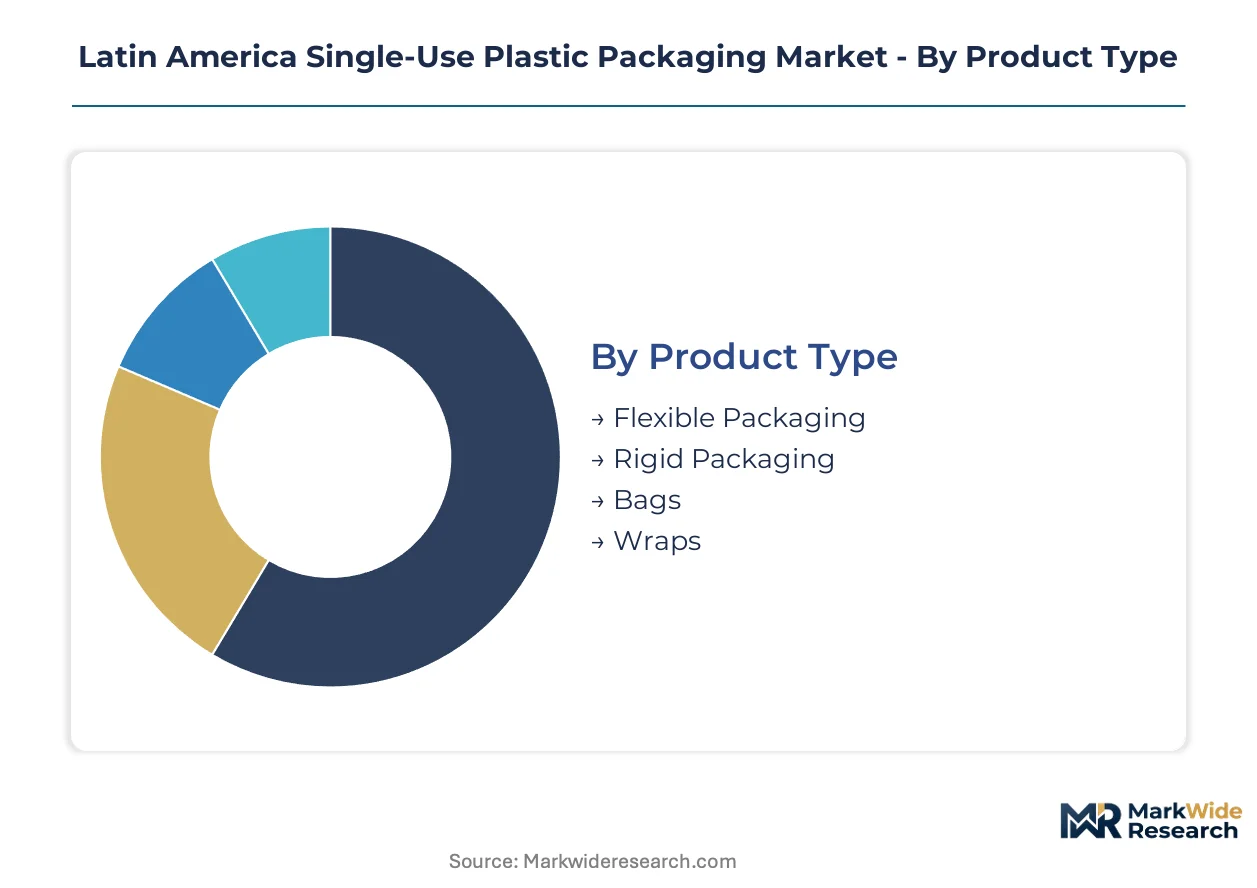
Segmentation in Latin American single-use plastic packaging reveals where substitution pressure from paper, fiber, and reusable alternatives is reshaping procurement priorities. Understanding these fault lines helps converters allocate reformulation investments and identify which product categories retain defensive positioning against regulatory phase-outs.
Product Type:
Substitution pressure from paper-based and reusable alternatives varies sharply across product formats, with flexible films facing lighter immediate threat than rigid containers targeted by municipal bans.
- Flexible Packaging:Multilayer polyethylene and polypropylene films dominate fresh produce and snack food distribution across Brazilian retail chains. São Paulo state's converting corridor supplies the bulk of regional capacity, though Chile's EPR mandates are forcing redesign toward mono-material structures compatible with existing recycling infrastructure.
- Rigid Packaging:Thermoformed clamshells and injection-molded containers serve prepared meals, dairy, and pharmaceutical applications where dimensional stability matters. Mexico's quick-service restaurant expansion is concentrating demand in the Mexico City-Guadalajara corridor, while Colombia's Pacific port access offers distribution arbitrage for cost-sensitive formats.
- Bags:Polyethylene retail and food service bags face the most acute regulatory pressure, with national bans operative in Chile and staged restrictions advancing in Peru and Argentina. Lightweighting and bioplastic blends represent the primary compliance pathways.
- Wraps:Stretch and shrink films for palletization and fresh food overwrap retain stronger defensive positioning due to functional performance requirements. Brazilian meat export processors anchor regional demand for high-clarity polyethylene grades.
Flexible packaging retains volume leadership; bioplastic-compatible rigid formats hold the steepest expansion curve.
End User:
Customer-type segmentation exposes diverging cost sensitivities and sustainability mandates, with food service operators facing the most compressed timelines for packaging redesign.
- Food Service:Quick-service restaurant chains and delivery platforms across Brazil and Mexico are consolidating procurement under direct converter contracts. Thermal retention and leak resistance specifications dominate, though operator sustainability commitments are accelerating qualification of fiber-plastic hybrid formats.
- Retail:Supermarket chains in the São Paulo-Rio de Janeiro corridor drive specification upgrades for fresh produce films, with private-label packaging teams mandating post-industrial recycled content thresholds.
- Consumer Goods:Personal care and household product brands source bottles, tubes, and sachets primarily from Mexican converters serving both domestic and export markets. E-commerce penetration is elevating damage-resistance requirements.
- Healthcare:Sterile barrier packaging for medical devices and pharmaceuticals operates under ANVISA and COFEPRIS compliance regimes that slow material transitions. Migration testing bottlenecks extend bioplastic adoption timelines.
Food service channels concentrate procurement reform pressure; healthcare applications maintain the most defensive regulatory moats.
Material:
Feedstock cost trajectories and regulatory acceptance thresholds are fragmenting material selection, with sugarcane-derived alternatives gaining traction where local ethanol supply exists.
- Polyethylene:Low-density and linear low-density grades retain dominant share across bags, wraps, and flexible films. Brazilian petrochemical infrastructure in São Paulo state and Rio de Janeiro provides cost-advantaged feedstock access for regional converters.
- Polypropylene:Homopolymer and copolymer grades serve rigid containers, caps, and high-temperature food service applications. Mexican thermoforming operations in the Bajío region concentrate injection molding capacity for dairy and ready-meal packaging.
- Polystyrene:Expanded polystyrene food service containers face the most severe restriction schedules across Chile, Peru, and Argentina. Conversion to polypropylene or fiber alternatives is accelerating in advance of mandatory phase-outs.
- Bioplastics:Polylactic acid derived from Brazilian sugarcane ethanol is reducing import dependency for sustainable alternatives. Barrier limitations against oxygen and moisture restrict adoption in protein and dairy applications requiring extended shelf life.
Polyethylene maintains cost leadership; bioplastics climb the fastest on regulatory tailwinds.
Application:
Application-level segmentation tracks where functional performance requirements create defensive value against material substitution, with beverage and personal care formats facing lighter immediate pressure than food packaging targeted by waste reduction policies.
- Food Packaging:Primary and secondary packaging for fresh, processed, and prepared foods constitutes the largest addressable demand pool. Brazilian retail chain sustainability targets are accelerating mono-material polyethylene qualification for snack and frozen vegetable applications.
- Beverage Packaging:Bottles, caps, and multi-pack wraps for carbonated and non-carbonated drinks. Mexican Coca-Cola FEMSA procurement patterns influence regional PET and HDPE specification trends, though single-use plastic bottle restrictions are advancing in select municipalities.
- Personal Care:Sachets, tubes, and rigid containers for cosmetics and hygiene products. E-commerce fulfillment requirements are elevating damage-resistance specifications while lightweighting pressure competes for design priority.
- Industrial:Pallet wrap, drum liners, and component packaging for manufacturing supply chains. Stretch film demand tracks industrial production indices in Brazil's southeastern manufacturing corridor.
Food packaging anchors regional volume; personal care applications offer the most resilient margin structure against substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Latin American procurement channels. Brazilian retail chains absorb moderate premiums for certified food-contact grades, while Colombian food service operators prioritize cost minimization. Mexican quick-service restaurant chains occupy the middle ground, balancing thermal performance specifications with unit economics.
Brazil
São Paulo state's petrochemical corridor anchors regional polyethylene supply, with Braskem's integrated complexes feeding downstream converters. ANVISA's food-contact migration limits are accelerating resin purity investments among flexible film producers. The greater Rio de Janeiro industrial zone concentrates thermoforming capacity for dairy and ready-meal applications.
Mexico
Quick-service restaurant chains in Mexico City and Guadalajara are consolidating procurement under direct converter contracts with volume guarantees. COFEPRIS certification queues for novel bioplastic additives extend product launch timelines. The Bajío region's injection molding cluster serves dairy packaging demand across central Mexico.
Chile
Santiago metropolitan retailers are mandating verified recycling content certificates for imported flexible packaging. The Ministry of Environment's extended producer responsibility enforcement is compelling converters to establish reverse logistics networks. Local collection cooperatives are supplying post-industrial scrap to compliant film producers.
Colombia
Buenaventura's Pacific port corridor offers distribution access to Andean markets with lighter regulatory enforcement. Food service operators prioritize cost-competitive polyethylene formats over bioplastic alternatives. Bogotá's converting sector is expanding capacity to serve quick-commerce grocery delivery platforms.
Argentina
Buenos Aires province manufacturers are retrofitting lines toward paper-plastic hybrid structures ahead of staged single-use restriction schedules. Stretched consumer purchasing power is compressing demand for premium sustainable formats. The Rosario industrial corridor maintains thermoforming capacity for regional protein export packaging.
Latin America Single-Use Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Latin American single-use plastic packaging market. Multinational converters with integrated formulation capabilities command premium positioning in high-barrier applications, while regional specialists compete on polyethylene film throughput and logistics efficiency. Three archetypes dominate: integrated multinationals with coextrusion expertise, regional scale players with petrochemical feedstock access, and hybrid material specialists bridging fiber and plastic formats. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct sourcing agreements displacing traditional distributor channels.
Among integrated multinationals, Amcor Group GmbH and Berry Global Inc exemplify contrasting geographic emphases within Latin America. Amcor's multilayer coextrusion capabilities position it within the high-barrier flexible packaging tier serving protein and dairy applications. Berry Global anchors regional rigid container production through thermoforming and injection molding infrastructure concentrated in Mexico and Brazil. Huhtamäki Oyj occupies a distinct position bridging fiber-based and plastic hybrid solutions, targeting quick-service restaurant chains with operational efficiency priorities in food delivery logistics. These three companies represent the spectrum of strategic positioning available to converters navigating regulatory fragmentation and end-user consolidation.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Winpak Ltd. |
| Berry Global Inc |
| Amcor Group GmbH |
| Huhtamäki Oyj |
| Sealed Air Corporation |
| Sonoco Products Company |
| Mondi Group |
| ALPLA Group |
| Others |
Pricing and Supply Chain Analysis
Braskem's integrated petrochemical complexes in São Paulo state generate feedstock cost advantages that cascade through Brazil's converting corridor, compressing price floors for polyethylene-based formats while elevating margin pressure on smaller Mexican thermoformers lacking comparable scale.
Pricing Analysis
ANVISA and COFEPRIS food-contact compliance mandates dictate the pricing tier structure across Latin American single-use plastic packaging, separating certified converters commanding premium positioning from uncertified competitors facing market exclusion. Three-tier pricing structure across premium, standard, and economy levels reflects migration testing investment, resin purity grades, and volume scale commitments. Pricing pressure stems from extended producer responsibility compliance costs in Chile and Peru, where reverse logistics investments compress margins for polyethylene-dependent operations. Colombian food service operators exhibit the highest price sensitivity, prioritizing cost-competitive formats over bioplastic alternatives, while Brazilian retail chains absorb moderate premiums for certified grades.
Supply Chain Analysis
Brazil and Mexico anchor regional polyethylene and polypropylene resin production, with São Paulo state's petrochemical infrastructure feeding downstream flexible film converters and Mexico's Bajío region concentrating injection molding capacity for rigid containers. Naphtha and ethylene feedstock draws from global crude markets, while sugarcane-derived ethanol supplies local polylactic acid production. Single-source vulnerability runs through multilayer film barrier resin imports, particularly polyamide and EVOH grades lacking regional manufacturing alternatives. Distribution runs through direct sourcing agreements between quick-service restaurant chains and converters, displacing traditional distributor intermediaries across Mexico City and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American single-use plastic packaging operates as a regulatory entrenchment market, where ANVISA and COFEPRIS certification queues create switching costs that freeze out unqualified competitors and defend incumbent positioning.
For Market Incumbents: Compound defensive positioning by deepening backward integration into sugarcane-derived ethanol feedstocks for bioplastic production, securing captive polylactic acid supply ahead of EPR mandate acceleration in Peru and Argentina. Add metallocene polyethylene coextrusion capacity in São Paulo state's manufacturing corridor to capture mono-material qualification demand from Brazilian retail chains. ANVISA migration testing bottlenecks threaten smaller competitors with fourteen-month launch delays, creating acquisition opportunities for certified converters. For New Entrants and Emerging Players: COFEPRIS fast-track certification for novel bioplastic additives offers the most penetrable entry pathway, targeting Mexico's quick-commerce grocery delivery platforms with lightweight primary packaging formats optimized for automated picking. Colombia's Pacific port corridor at Buenaventura provides distribution arbitrage into Andean markets with lighter regulatory enforcement, enabling cost-competitive penetration before EPR regimes mature. Direct converter contracts with quick-service restaurant chains displace distributor channels, requiring volume guarantee capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated multilayer coextrusion capabilities serving high-barrier protein and dairy applications, as mono-material transition investments favor technical specialists over commodity processors. Long-term viability rests on regulatory compliance infrastructure and feedstock integration rather than volume scale alone. Watch staged single-use restriction schedules in Argentina and Peru as inflection indicators for paper-plastic hybrid format adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioplastic Feedstock | Brazilian sugarcane ethanol access reduces import dependency for PLA production in São Paulo corridor. |
| Mono-Material Polyethylene Line Retrofit | Chile's EPR mandates force redesign away from multilayer structures incompatible with existing recycling infrastructure. |
| Direct Sourcing Agreement with QSR Chains | Alsea and FEMSA procurement consolidation in Mexico City displaces traditional distributor intermediaries. |
| ANVISA-COFEPRIS Dual Certification Investment | Migration testing capabilities extend competitive moats through fourteen-month launch barriers for uncertified rivals. |
| Pacific Port Distribution Hub Establishment | Buenaventura logistics access enables cost-competitive Andean penetration before EPR enforcement matures. |
Research Methodology
A standing panel of flexible film plant managers, quick-service restaurant procurement directors, retail category buyers, and ANVISA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from Brazilian petrochemical trade association disclosures, Chilean Ministry of Environment EPR enforcement protocols, Mexican customs import data for barrier resin grades, and COFEPRIS certification queue records. Bottom-up converter capacity surveys triangulated against top-down end-use demand estimates from quick-commerce platform fulfillment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type segmentation, material grade tiers, end-use industry channels, and regional regulatory cluster divergence. CAGRs derived from elasticity-adjusted demand curves incorporating petrochemical feedstock price volatility and EPR compliance cost pass-through assumptions. Industry-specific inputs included sugarcane ethanol spot pricing, multilayer film delamination equipment capacity counts, and quick-service restaurant outlet expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA enforcement intensity, sugarcane ethanol price stability, or EPR mandate implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding migration testing queue durations, bioplastic barrier property improvement curves, and quick-commerce platform market penetration rates. Recalibration cycles align with material shifts in regulatory enforcement protocols and feedstock cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Global Plastic Packaging Sacks Market