
 E-Commerce Plastic Packaging Market | 2026-2036
E-Commerce Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Plastic Packaging Market Foresight
The EU Packaging and Packaging Waste Regulation is recalibrating design priorities across European e-commerce channels, forcing converters to eliminate excess void fill and demonstrate recyclability. Amcor plc leverages its European film extrusion network to supply pre-certified recyclable mailer formats. Berry Global anchors North American demand through blown film operations scaled for high-velocity fulfillment. Sealed Air Corporation differentiates via automated inflatable systems that cut dimensional weight penalties.
E-commerce plastic packaging encompasses protective and containment structures—predominantly polyethylene mailers, polypropylene air pillows, and polystyrene foam inserts—engineered to survive single-use transit stress while minimizing cube and weight. These materials typically range from 25 to 150 microns in film gauge, with bubble or foam geometries absorbing impact energy across last-mile distribution networks. Bags dominate volume flows in apparel and soft-goods fulfillment, where flexibility and low per-unit cost override structural rigidity. Polyethylene commands the largest material share due to its sealability, puncture resistance, and established mechanical recycling streams. Third-party logistics channels represent the fastest-growing distribution vector as outsourced fulfillment operators consolidate packaging procurement across multiple e-tailers.
REACH restricts phthalate plasticizers and SVHC additives in films entering European consumer goods supply chains, while ECHA's microplastics restriction targets loose-fill formats. The EU Green Deal's packaging waste targets mandate minimum recycled content thresholds that reshape resin sourcing economics. Stakeholders must monitor how EMA, ECHA, and national enforcement bodies calibrate compliance timelines against converter capacity to certify recycled feedstock traceability.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for e-commerce plastic packaging, forcing converters to eliminate excess void fill and certify recyclability before products reach European fulfillment networks. This regulatory compression intersects with fulfillment center automation, where dimensional weight penalties and throughput speeds reshape material specifications.
Growth Catalysts
- REACH SVHC restrictions:ECHA's evolving substance restrictions are accelerating substitution of conventional plasticizers with bio-based alternatives in polyethylene films, opening certified supply channels for compliant converters.
- Last-mile robotics:Automated sortation systems in high-velocity fulfillment centers are automating material handling specifications, driving demand for standardized mailer formats that interface with robotic grippers.
- German sustainability procurement:Berlin and Hamburg municipal purchasing mandates for recycled content are concentrating demand among converters with pre-certified mechanical recycling feedstock.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock swings compress converter margins, particularly for blown film operations without captive cracker access.
- Mechanical recycling contamination:Multi-layer barrier films and adhesive labels degrade reprocessed polyethylene quality, limiting closed-loop supply availability.
- ECHA microplastics restriction:Pending loose-fill format bans create compliance uncertainty for air pillow converters serving cross-border e-tailers.
Strategic Opportunities
- India BIS standards alignment:Emerging e-commerce logistics hubs in Maharashtra and Karnataka present first-mover openings for pre-certified recyclable mailer formats ahead of mandatory recycled content thresholds.
- Returnable packaging integration:Convergence of RFID tracking and durable polypropylene totes is automating reverse logistics for apparel fulfillment, displacing single-use formats in premium channels.
- EU Green Deal packaging waste targets:Minimum recycled content mandates are reshaping resin sourcing economics, rewarding converters with verified mass-balance certification.
Industry Challenges
- Mass-balance auditor scarcity:Limited certification body capacity for recycled content verification is extending compliance timelines for converters seeking EU market access.
- Legacy warehouse management integration:ERP system reconfiguration for dimensional weight optimization creates implementation friction for mid-tier 3PL operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Plastic Packaging Market |
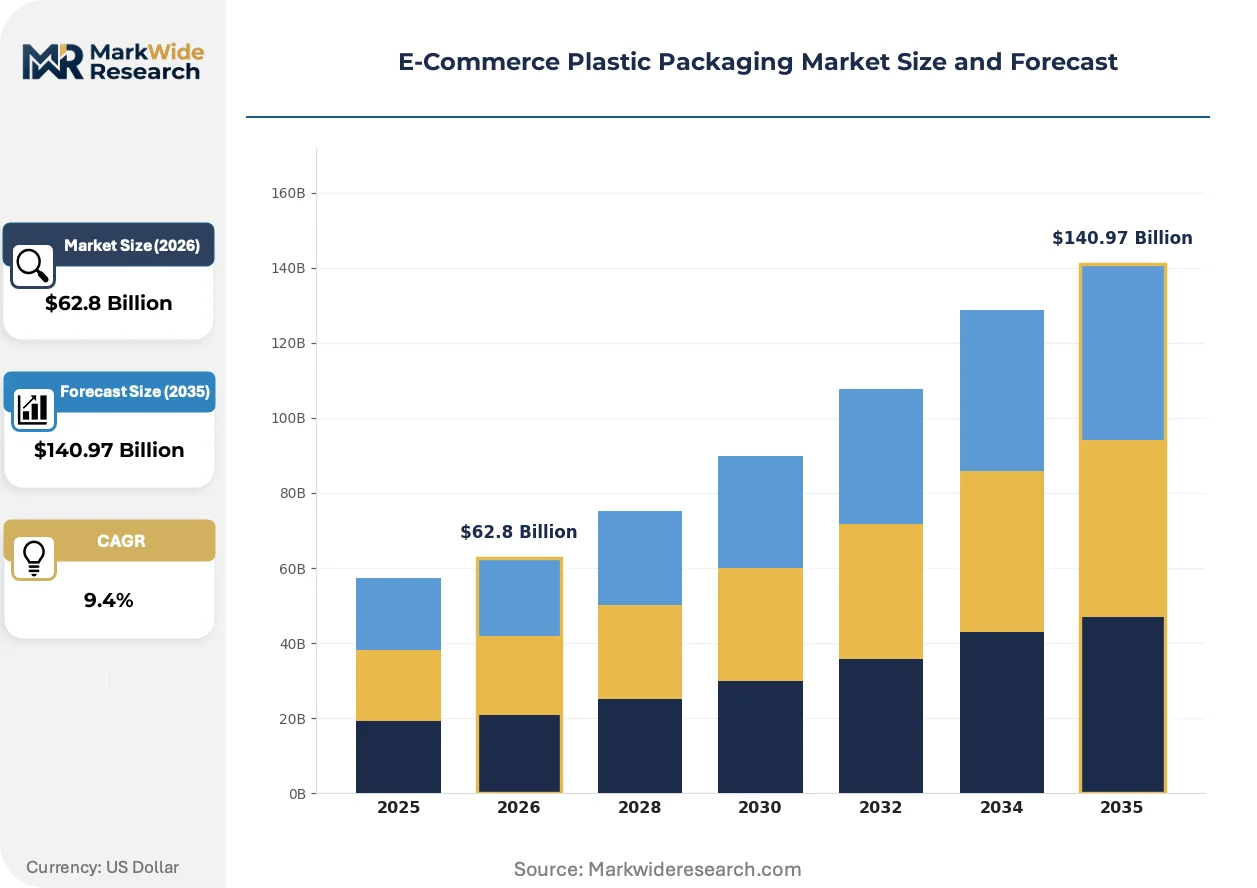
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $140.97 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Containers, Wraps Material: Polyethylene, Polypropylene, Polyester, Polystyrene End User: E-Tailers, Consumer Goods, Food Services, Cosmetics Distribution Channel: Online Retail, Wholesale, Direct Sales, Third-Party Logistics |
| Companies Covered | Amcor plc, Sealed Air Corporation, Pregis LLC, Berry Global, Mondi Group, Sonoco Products Company, Storopack Hans Reichenecker GmbH, Smurfit Westrock, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Plastic Packaging Market Shifts & Advancements
Automated fulfillment infrastructure is compressing packaging specification windows, forcing material science convergence with robotics compatibility. Three developments are reshaping competitive positioning.
Machine-vision-guided sortation is automating dimensional weight verification in real-time, enabling dynamic packaging selection based on actual item geometry rather than static box sizes. Amazon and Zalando fulfillment networks are deploying these systems at scale in Germany and Poland. The technology is automating void elimination, compressing material usage per shipment while accelerating throughput.
REACH authorization procedures for phthalate plasticizers are tightening additive specifications for films entering European consumer goods channels. Industrial consequence includes accelerated migration to bio-based sealant layers and mono-material constructions. Flexible packaging converters serving German fashion e-tailers are responding with pre-certified recyclable mailer formats ahead of enforcement timelines.
Consolidated procurement by third-party logistics operators is displacing brand-direct packaging sourcing across European e-commerce. DHL Supply Chain and Geodis are centralizing specifications across multiple e-tailer clients, compressing supplier diversity. This concentration is most visible in Benelux and Northern France, where 3PL hub density enables pooled purchasing leverage.
E-Commerce Plastic Packaging Market Segmentation
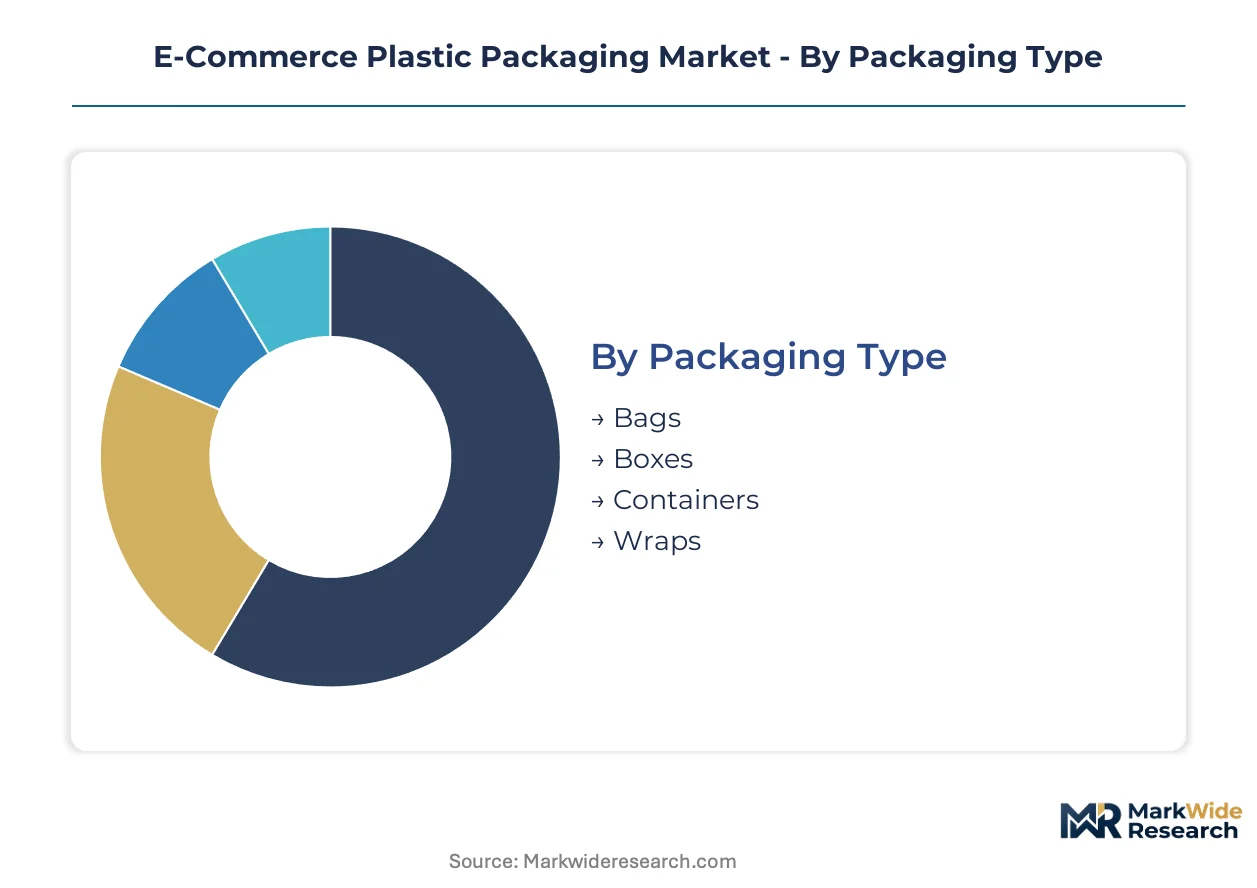
E-commerce plastic packaging segments diverge sharply in capital requirements and automation compatibility. Material thickness, barrier complexity, and fulfillment velocity dictate which formats justify extrusion line investment versus off-the-shelf procurement.
Packaging Type:
Capital intensity peaks with rigid formats requiring thermoforming or injection molding infrastructure, while flexible formats demand less fixed asset commitment but higher throughput volumes to amortize film extrusion costs.
- Bags:Polyethylene mailers dominate apparel and soft-goods fulfillment through sealability and puncture resistance. German fashion e-tailers are standardizing on 60-80 micron co-extruded formats to satisfy EU Packaging and Packaging Waste Regulation recyclability mandates while maintaining dimensional weight efficiency.
- Boxes:Corrugated-plastic hybrid constructions absorb electronics and premium cosmetics shipments where structural rigidity prevents damage. Demand concentrates in automated fulfillment centers where robotic grippers require standardized geometries.
- Containers:Reusable polypropylene totes with RFID tracking integrate into closed-loop logistics for high-value apparel returns.
- Wraps:Stretch film and bubble formats protect irregular geometries in cross-border fulfillment.
Bags absorb the bulk of installed capacity; containers are expanding most quickly through returnable packaging integration.
Material:
Resin selection determines recycling pathway compatibility and regulatory compliance cost, with mono-material constructions commanding premium positioning against multi-layer alternatives facing ECHA microplastics scrutiny.
- Polyethylene:Linear low-density and high-density grades provide sealability, puncture resistance, and established mechanical recycling infrastructure. REACH SVHC restrictions are accelerating bio-based sealant layer adoption in films entering European consumer goods channels.
- Polypropylene:Air pillow and durable tote applications leverage stiffness-to-weight ratios and thermal stability. ECHA's pending loose-fill format restrictions are compressing demand timelines for inflatable systems in cross-border fulfillment.
- Polyester:High-clarity formats serve cosmetics and premium electronics where visual presentation matters.
- Polystyrene:Foam inserts retain niche protective applications despite mechanical recycling limitations and regulatory pressure.
Polyethylene claims the deepest installed base; polypropylene is climbing the fastest through automation-compatible rigid formats.
End User:
Procurement scale and sustainability mandate stringency separate enterprise e-tailers from fragmented consumer goods channels, with compliance certification costs filtering supplier access.
- E-Tailers:Amazon, Zalando, and vertically integrated fashion platforms centralize specifications across fulfillment networks. Machine-vision-guided sortation is automating dimensional weight verification in German and Polish distribution centers, compressing material usage per shipment.
- Consumer Goods:Brand-direct packaging requirements fragment across product categories with varying barrier needs.
- Food Services:Temperature-sensitive formats face additional EFSA compliance layers for direct food contact.
- Cosmetics:Premium unboxing experiences sustain higher per-unit packaging investment with decorative finishing requirements.
E-tailers command the largest procurement volumes; food services is gaining share fastest through meal-kit subscription expansion.
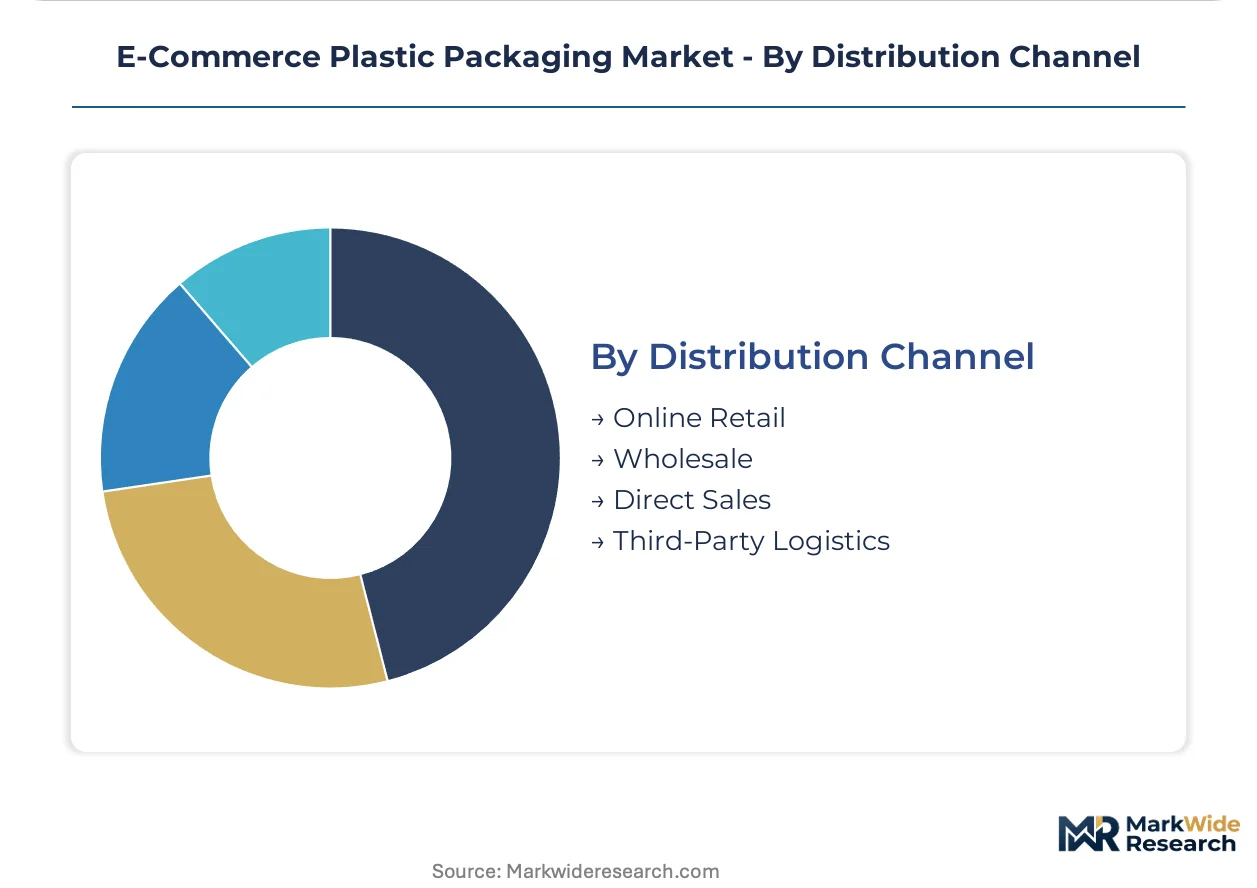
Distribution Channel:
Channel concentration determines specification authority, with consolidated 3PL procurement displacing fragmented brand-direct sourcing across European logistics hubs.
- Third-Party Logistics:DHL Supply Chain and Geodis are centralizing mailer specifications across multiple e-tailer clients in Benelux and Northern France. Pooled purchasing leverage is compressing supplier diversity while accelerating standardized format adoption for robotic handling compatibility.
- Online Retail:Platform-controlled fulfillment dictates packaging specifications through vendor compliance programs.
- Wholesale:Bulk shipment formats prioritize pallet stability over individual unit presentation.
- Direct Sales:Brand-controlled unboxing experiences sustain premium format investment with lower volume scale.
Third-party logistics channels are expanding most quickly; wholesale retains the deepest legacy infrastructure footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor concentrates European e-commerce fulfillment infrastructure, with automated distribution centers driving standardized mailer specifications across Germany, Poland, and the Netherlands.
Germany
Berlin and Hamburg municipal procurement mandates for recycled content are concentrating converter demand among suppliers with pre-certified mechanical recycling feedstock. The EU Packaging and Packaging Waste Regulation is eliminating excess void fill requirements before enforcement deadlines. The Rhine-Ruhr industrial corridor hosts dense fulfillment center clusters where DHL Supply Chain and Geodis centralize specifications across multiple e-tailer clients.
United States
Amazon's fulfillment network expansion across the Midwest and Southeast is automating dimensional weight verification systems that compress material usage per shipment. EPA state-level waste reduction targets are pressuring converters to demonstrate recyclability certification. The Chicago-Detroit industrial corridor anchors blown film production capacity serving high-velocity 3PL channels.
China
Cross-border e-commerce logistics hubs in the Yangtze River Delta and Pearl River Delta are scaling polyethylene mailer production for export-oriented fulfillment. MIIT circular economy directives are mandating recycled content thresholds in packaging materials. The Shenzhen-Dongguan manufacturing corridor supplies automated inflatable systems to regional 3PL operators.
India
Maharashtra and Karnataka are emerging as e-commerce logistics hubs where BIS standards alignment creates first-mover openings for pre-certified recyclable formats. The PLI scheme for manufacturing is incentivizing domestic converter capacity expansion ahead of mandatory recycled content thresholds. The Mumbai-Pune industrial corridor is consolidating fulfillment infrastructure for fashion and consumer goods e-tailers.
Poland
Zalando's automated fulfillment centers in Lower Silesia are deploying machine-vision-guided sortation systems that standardize mailer formats for robotic handling compatibility. EU Green Deal packaging waste targets are reshaping resin sourcing economics for converters serving cross-border e-commerce channels. The Wrocław-Łódź logistics corridor is attracting 3PL investment from Western European operators seeking cost-advantaged distribution.
E-Commerce Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with integrated film extrusion networks and specialized protective packaging innovators. Tier-one players leverage European and North American manufacturing footprints to serve high-velocity fulfillment channels with pre-certified recyclable formats. Strategic moves center on backward integration into resin sourcing and automated packaging system partnerships that lock in 3PL procurement relationships.
Among diversified packaging conglomerates, Amcor plc and Berry Global exemplify scale-driven archetypes with broad geographic manufacturing presence. Sealed Air Corporation occupies a position within the specialized protective packaging tier, anchoring automated inflatable system supply to fulfillment operators. Storopack Hans Reichenecker GmbH represents the European mid-cap specialist archetype with concentrated regional expertise in molded foam and air pillow formats.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Pregis LLC |
| Berry Global |
| Mondi Group |
| Sonoco Products Company |
| Storopack Hans Reichenecker GmbH |
| Smurfit Westrock |
| International Paper |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation mandates for recycled content are forcing converters to absorb certification costs or pass them downstream, reshaping procurement economics for polyethylene mailer supply. This specification pressure concentrates pricing power among suppliers with pre-certified mechanical recycling feedstock and mass-balance auditor relationships.
Pricing Analysis
Throughput-linked pricing for automated fulfillment compatibility anchors converter revenue models, with dimensional weight efficiency and robotic handling certification commanding premiums over commodity mailer alternatives. Price differentiation separates certified recyclable formats from conventional multi-layer constructions facing ECHA microplastics scrutiny. Cost compression in standard-grade polyethylene film is intensifying because ethylene feedstock volatility and mechanical recycling contamination limits squeeze converter margins. Third-party logistics operators demonstrate highest price sensitivity through pooled procurement leverage, while premium cosmetics e-tailers absorb certification premiums for unboxing presentation quality.
Supply Chain Analysis
Polyethylene resin supply rests on petrochemical complexes in Germany, the United States, and China, with linear low-density grades dominating e-commerce film extrusion. Blown film operations draw from ethylene feedstock anchored in the Rhine-Ruhr corridor, the US Gulf Coast, and the Yangtze River Delta, while additive masterbatches for sealant layers source from specialty chemical producers in Belgium and Japan. Single-source vulnerability concentrates in mass-balance certification body capacity, extending compliance timelines for EU market access. Distribution runs through third-party logistics hub networks in Benelux and Northern France, where consolidated procurement compresses supplier diversity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical recycling feedstock scarcity props pricing for certified converters, creating a supply-constrained environment where mass-balance auditor capacity bottlenecks filter market access.
For Market Incumbents: Hedge resin price exposure through long-term offtake agreements with European mechanical recyclers ahead of EU Green Deal recycled content threshold enforcement. Backward integration into film extrusion networks in Poland and Germany locks in fulfillment center proximity, while pre-certification investments defend against emerging Asian converters with cost-advantaged virgin resin access. For New Entrants and Emerging Players: Enter via Maharashtra and Karnataka logistics corridors in India, where BIS standards alignment creates first-mover positioning before mandatory recycled content thresholds take effect. White-space concentrates in pre-certified recyclable mailer formats for mid-tier fashion e-tailers lacking direct converter relationships, with private-label supply to 3PL operators offering the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors converters with verified mass-balance certification and established relationships with DHL Supply Chain or Geodis procurement teams. Long-term viability hinges on automation-compatible format development and captive recycling feedstock access. Watch ECHA enforcement timelines for loose-fill format restrictions as the inflection signal for air pillow converter restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Recycling | Captive feedstock supply secures EU Green Deal compliance ahead of certification bottlenecks. |
| Automated Packaging System Partnership | Integration with machine-vision sortation networks locks in 3PL procurement specifications. |
| Mass-Balance Certification Investment | Pre-certified status filters supplier access for German municipal procurement mandates. |
| Geographic Expansion into India | Maharashtra and Karnataka hub development captures BIS alignment first-mover advantage. |
| Mono-Material Construction R&D | Eliminates adhesive label contamination that degrades mechanical recycling quality. |
Research Methodology
Multi-period observation of fulfillment center automation deployment, EU regulatory enforcement timelines, and resin price volatility anchored the trend analysis, supplemented by interviews with blown film plant managers, 3PL procurement leads at DHL Supply Chain and Geodis, sustainability directors at German fashion e-tailers, and mass-balance certification auditors. Secondary validation drew from ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation draft texts, customs trade data for polyethylene film imports, and SEC filings of diversified packaging conglomerates. Bottom-up capacity modeling triangulated against top-down e-commerce shipment volume projections.
Segment-weighting across packaging type, material resin, end-user category, and distribution channel shaped the analytical framework, with polyethylene mailer volumes, polypropylene air pillow adoption rates, and 3PL channel concentration serving as primary forecast inputs. CAGRs were derived from elasticity modeling against e-commerce penetration rates and regulatory compliance cost absorption capacity throughout the forecast period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA microplastics restriction acceleration or mass-balance auditor capacity collapse. Forecasts reflect documented assumptions on resin price normalization and mechanical recycling feedstock availability. A small set of named triggers—REACH SVHC list expansion, EU Green Deal threshold calibration, and India BIS enforcement timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market