
 Vacuum Sealing Machine Market | 2026-2036
Vacuum Sealing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Sealing Machine Market Analytics
China is tilting toward automated packaging equipment manufacturing, with coastal provinces adding vacuum sealer assembly capacity for both domestic food processors and export markets. MULTIVAC Sepp Haggenmüller GmbH & Co. KG leverages its chamber sealer specialization to dominate European meat processing installations. Sealed Air Corporation anchors North American demand through its Cryovac brand strength in retail protein packaging. ULMA Packaging, S. Coop. competes on modular gas-flush configurations for ready-meal producers.
A vacuum sealing machine evacuates air from a flexible pouch or rigid chamber before heat-sealing the closure, typically achieving residual oxygen levels below 0.5% to inhibit microbial growth and oxidative degradation. Chamber vacuum sealers occupy the industrial core due to their ability to process liquids and maintain consistent vacuum depth across high-volume food processing lines. External vacuum sealers sustain faster growth in small commercial kitchens and artisan food producers where capital budgets constrain chamber unit adoption. Gas flush technology differentiates premium configurations, enabling modified atmosphere packaging that extends red meat color stability and bakery product freshness.
USDA meat inspection protocols and FDA food contact substance regulations shape equipment material specifications and sanitation design requirements for vacuum sealers serving American protein processors. EU REACH restrictions on phthalate plasticizers and F-Gas Regulation limits on synthetic refrigerants constrain seal bar component sourcing and cooling system choices for equipment marketed in Europe. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to redesign for recyclable mono-material films or invest in chemical recycling partnerships.
Market Dynamics
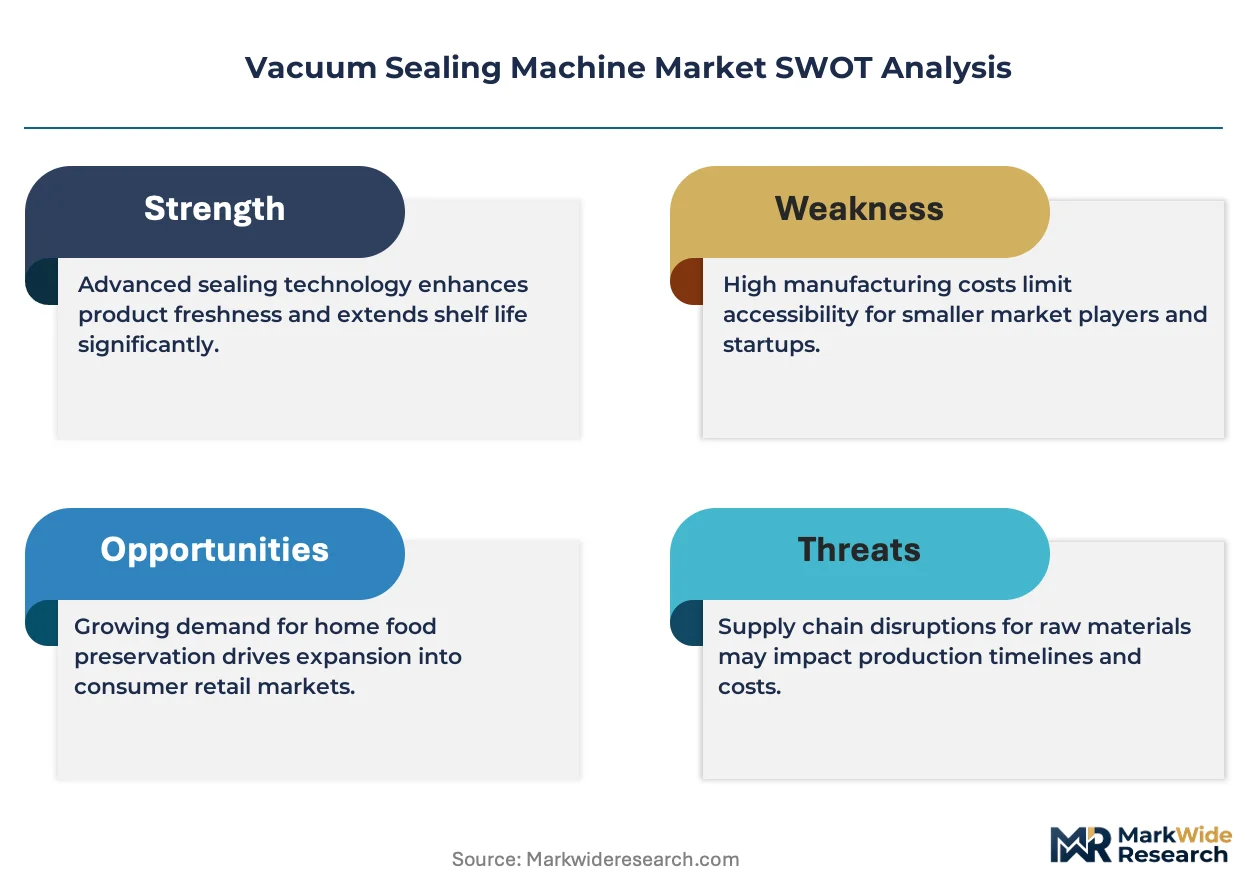
EU REACH restrictions on phthalate plasticizers and F-Gas Regulation limits on synthetic refrigerants are forcing equipment redesigns across sealing bar component sourcing and cooling system architectures, compressing supplier margins while accelerating material substitution timelines.
Growth Catalysts
- Modified atmosphere packaging adoption:Gas-flush configurations enable red meat color stability extension and bakery freshness preservation, driving replacement demand from protein processors and artisan bakeries seeking shelf-life differentiation.
- Thailand food processing expansion:Southeast Asian food processing plants are adding vacuum sealing lines specifically to reduce spoilage rates and extend export-ready shelf life for tropical fruit and seafood products.
- EU Green Deal packaging mandates:Extended producer responsibility frameworks push equipment manufacturers toward mono-material film compatibility and chemical recycling partnership models.
Market Restraints
- Stainless steel price volatility:Chamber sealer fabrication depends heavily on 304 and 316-grade stainless input costs, exposing European and North American manufacturers to nickel and chromium supply fluctuations from Indonesian and South African concentrate markets.
- Fluorinated refrigerant phase-down:F-Gas Regulation constraints limit cooling system choices for vacuum pump configurations, forcing costly engineering pivots for equipment marketed across EU member states.
- External sealer performance ceiling:External vacuum sealers cannot achieve consistent sub-0.5% residual oxygen levels with liquid-containing products, restricting their penetration in high-volume food processing lines.
Strategic Opportunities
- India cold-chain infrastructure gaps:Underpenetrated domestic food processing and emerging organized retail create vacuum sealing equipment demand for dairy, spice, and ready-to-eat meal packaging applications.
- Smart sensor integration:Convergence of vacuum level sensors with IoT connectivity enables predictive maintenance and vacuum cycle optimization for industrial chamber installations.
- Brazil protein export compliance:ANVISA sanitary requirements and USDA equivalence protocols drive equipment upgrades in Brazilian beef and poultry processing facilities serving North American and Asian export markets.
Industry Challenges
- Multi-jurisdiction certification complexity:FDA food contact substance approvals, EU CE marking, and country-specific electrical safety certifications create 18-24 month equipment launch timelines for multinational suppliers.
- Legacy system integration friction:Automated vacuum sealing lines must interface with existing ERP and MES platforms in meat processing plants, requiring custom software bridges and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Sealing Machine Market |
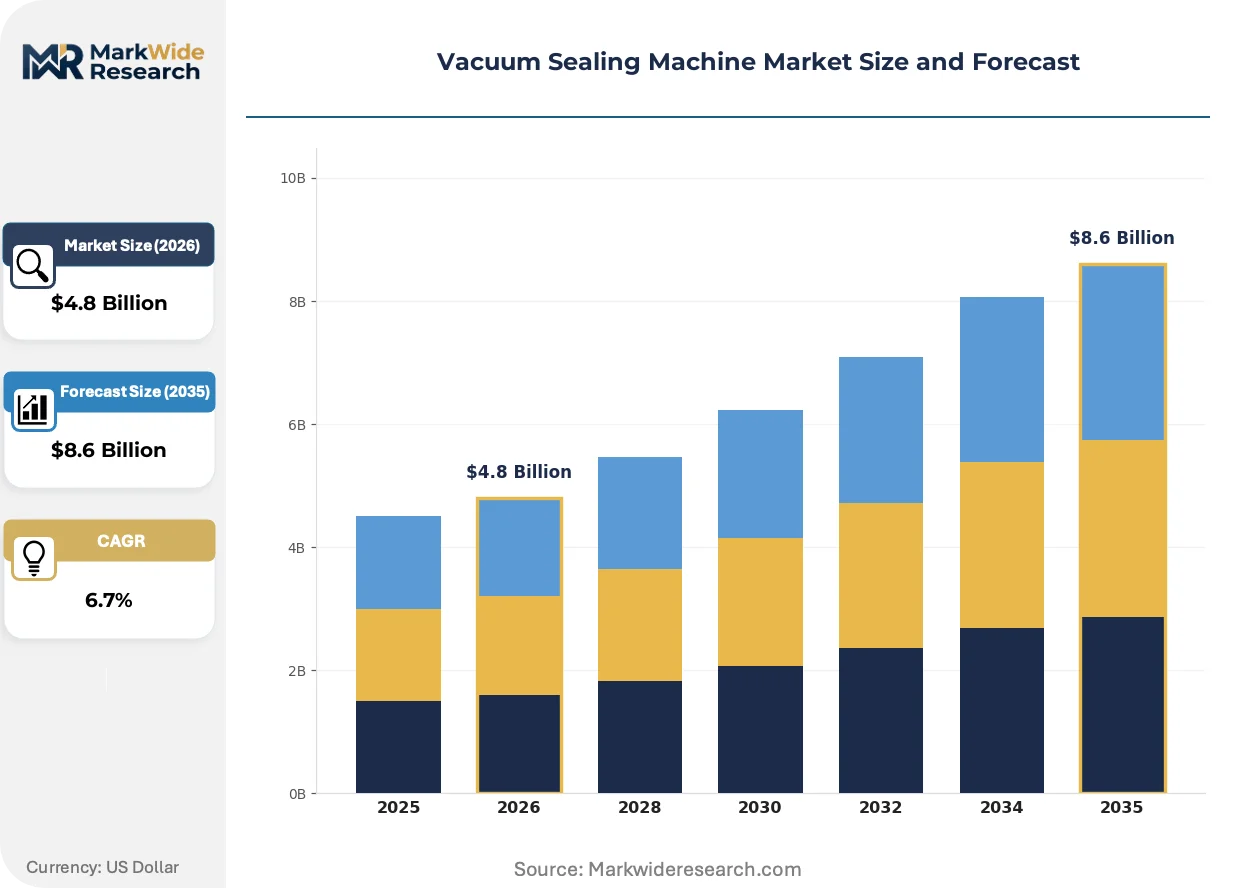
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chamber Vacuum Sealers, External Vacuum Sealers, Handheld Vacuum Sealers, Commercial Vacuum Sealers End User: Households, Food Processing, Pharmaceuticals, Packaging Industry Technology: Automatic, Semi-Automatic, Manual, Gas Flush Application: Food Preservation, Sous Vide Cooking, Medical Supplies, Retail Packaging |
| Companies Covered | IMA S.p.A., Henkelman B.V., MULTIVAC Sepp Haggenmüller GmbH & Co. KG, Hawo Verarbeitungsmaschinen GmbH, ORVED S.r.l., Sealed Air Corporation, ULMA Packaging, S. Coop., JBT Corporation, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Sealing Machine Market Evolving Landscape
Sensor-enabled vacuum cycle optimization and cloud-connected maintenance systems are compressing downtime windows and reshaping service revenue models across industrial installations. Equipment differentiation now hinges on data integration depth rather than mechanical reliability alone.
IoT-enabled vacuum monitoring is digitizing predictive maintenance protocols for chamber sealers in high-throughput meat processing facilities. German industrial bakeries and Dutch cheese cooperatives are piloting connected systems that transmit vacuum level deviations and seal bar temperature anomalies to centralized maintenance dashboards. This connectivity is digitizing traditional break-fix service relationships into subscription-based uptime guarantees, compressing vendor margins on discrete parts sales while locking in multi-year service contracts.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon and CO2-based vacuum pump adoption in equipment destined for European protein processors. The industrial consequence is a bifurcation in cooling system architectures between EU-compliant models and legacy refrigerant configurations for export markets. Chamber sealer lines serving German meat processors and Dutch ready-meal facilities face the most acute redesign pressure, with several manufacturers advancing air-cooled pump alternatives to sidestep synthetic refrigerant dependency entirely.
Artisan food producers and small commercial kitchens are consolidating equipment purchases through foodservice distributor channels rather than direct manufacturer relationships. WebstaurantStore and regional equipment dealers now curate external vacuum sealer assortments with bundled consumable programs, displacing traditional capital-equipment sales motions. This channel shift is most visible in the United States, where independent charcuterie producers and farmstead cheese operations prioritize local service availability over manufacturer brand prestige.
Vacuum Sealing Machine Market Segmentation
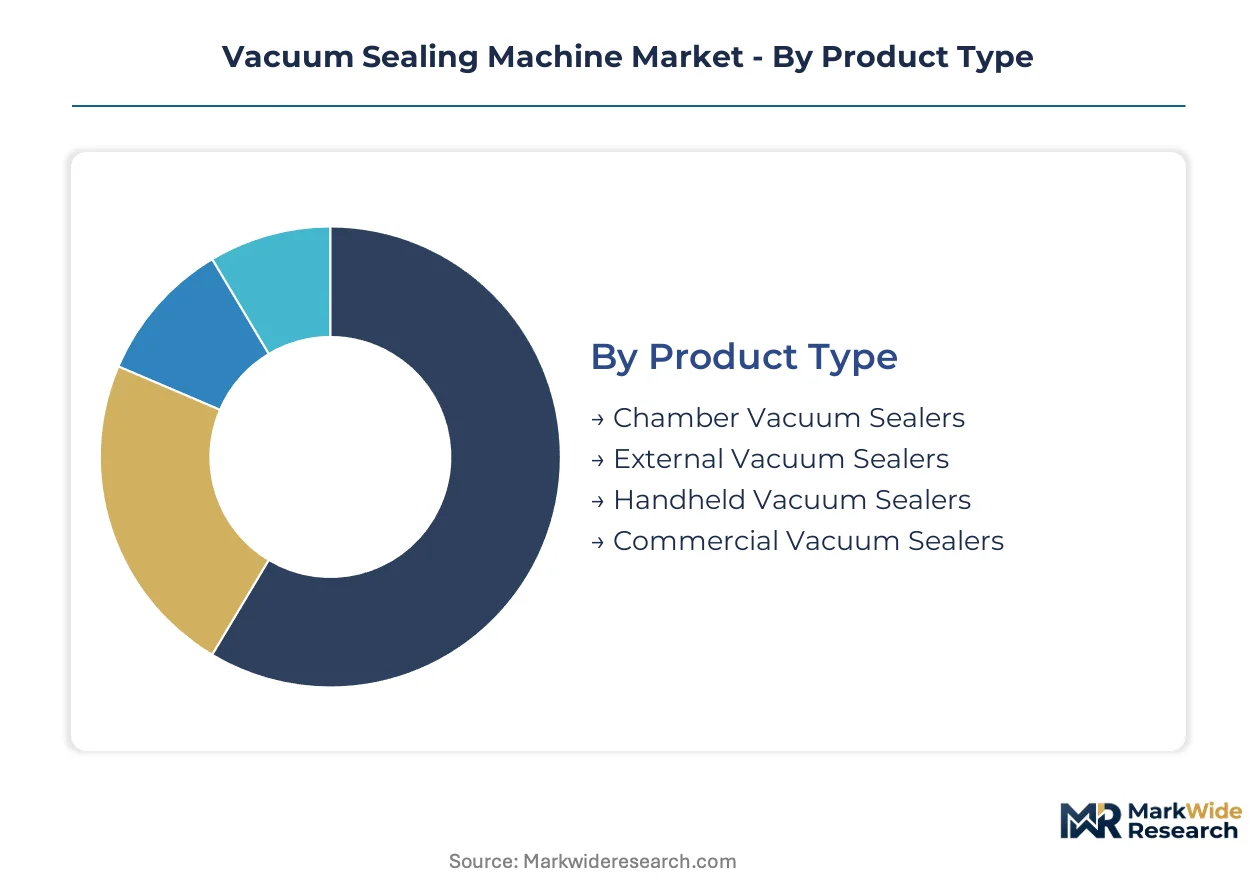
Equipment selection in vacuum sealing hinges on throughput requirements, product consistency demands, and capital recovery timelines. Segmentation reveals where chamber systems command premium pricing versus where external sealers penetrate cost-constrained operations. Technology choices increasingly bifurcate between legacy mechanical controls and sensor-integrated automation platforms.
Product Type:
Replacement cycles vary dramatically: chamber units in industrial protein processing turn over every 7-10 years under continuous duty, while handheld and external models in commercial kitchens cycle faster at 3-5 years due to wear and feature obsolescence.
- Chamber Vacuum Sealers:These systems evacuate air from within a rigid chamber before heat-sealing, achieving sub-0.5% residual oxygen consistently. German meat processors and Dutch ready-meal facilities drive replacement demand as F-Gas Regulation compliance forces cooling system redesigns.
- External Vacuum Sealers:Portable units draw air directly from bags through external nozzles, sacrificing vacuum depth for speed and capital efficiency. Thailand seafood processors and US artisan charcuterie producers favor these for lower-volume export and direct-to-retail packaging lines.
- Handheld Vacuum Sealers:Battery-operated devices target household sous vide preparation and small-batch food preservation. These units concentrate in North American and European consumer channels where meal-kit subscription growth sustains accessory demand.
- Commercial Vacuum Sealers:Heavy-duty external configurations bridge the gap between handheld portability and chamber performance. Brazilian beef processors deploy these for mid-volume operations awaiting full chamber line upgrades to meet ANVISA export compliance.
Chamber vacuum sealers dominate installed base across industrial food processing. External vacuum sealers are where expansion concentrates in emerging market small-to-medium enterprises.
End User:
Margin structures diverge sharply: pharmaceutical and food processing installations command premium pricing with attached service contracts, while household and general packaging segments compete on equipment cost alone with thinner aftermarket revenue.
- Households:Consumer demand centers on countertop external sealers for meal prep and bulk purchasing optimization. US and German markets show strongest penetration where sous vide cooking adoption and warehouse club shopping patterns intersect.
- Food Processing:Industrial protein, bakery, and ready-meal operations require chamber systems with validated sanitation protocols. EU EFSA material compliance and USDA meat inspection specifications shape equipment procurement in this segment.
- Pharmaceuticals:Sterile packaging applications demand validated vacuum cycles with full batch documentation. This segment concentrates in Switzerland, Germany, and the US where FDA 21 CFR Part 11 and Swissmedic guidance enforce data integrity requirements.
- Packaging Industry:Contract packagers serving multiple end-use categories prioritize modular equipment with quick changeover capability. Southeast Asian co-packers expanding into tropical fruit exports drive regional demand for gas-flush compatible systems.
Food processing commands the largest equipment revenue pool. Pharmaceuticals deliver the steepest expansion trajectory as biologics packaging requirements tighten.
Technology:
Capital intensity scales predictably: manual and semi-automatic configurations minimize upfront outlay but constrain throughput, while automatic and gas-flush systems recover premium pricing through labor reduction and shelf-life extension.
- Automatic:Programmable logic controllers manage vacuum levels, dwell times, and seal temperatures without operator intervention. High-volume German industrial bakeries and Brazilian poultry processors specify these for 24-hour production schedules.
- Semi-Automatic:Operator-initiated cycles with automated vacuum and seal phases balance labor input with consistency. Mid-sized US meat processors and Indian dairy cooperatives favor this tier for flexible batch sizing.
- Manual:Foot-pedal or lever-actuated systems dominate entry-level commercial kitchens and developing market small processors. These units concentrate where technician availability and spare parts logistics constrain automated equipment adoption.
- Gas Flush:Modified atmosphere packaging technology injects inert gases post-evacuation to preserve color and texture. Red meat processors in the US and EU deploy these configurations for retail case-ready packaging with extended display life.
Semi-automatic systems dominate current installed base. Gas flush technology is where expansion concentrates as protein processors seek shelf-life differentiation.
Application:
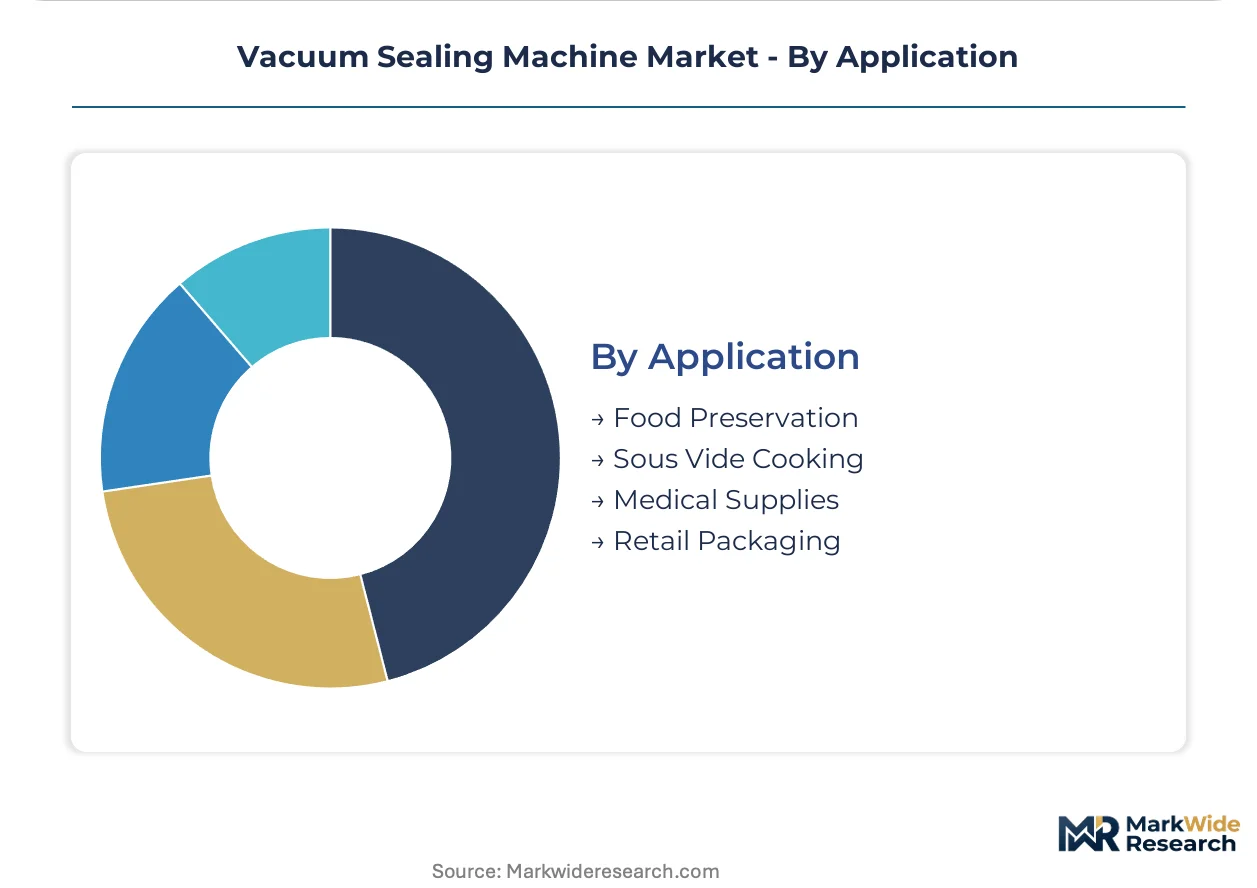
Performance requirements stratify by oxygen sensitivity: medical supplies and sous vide cooking demand sub-0.5% residual oxygen, while retail packaging tolerates wider variation in exchange for speed and film compatibility.
- Food Preservation:Long-term storage applications span household freezing to commercial cold-chain distribution. Southeast Asian tropical fruit exporters and Indian spice processors drive demand for moisture-resistant barrier film compatibility.
- Sous Vide Cooking:Precision temperature cooking requires complete air evacuation to ensure heat transfer uniformity. US and European restaurant chains and home cooking enthusiasts sustain demand for compact external sealers with dedicated sous vide modes.
- Medical Supplies:Sterile barrier packaging for surgical instruments and pharmaceutical devices demands validated seal integrity with full traceability. FDA and ISO 11607 compliance requirements concentrate demand in US, German, and Swiss manufacturing clusters.
- Retail Packaging:Case-ready meat and modified atmosphere bakery packaging prioritizes visual appeal and shelf-life extension. EU Green Deal packaging mandates are pushing this segment toward mono-material film compatibility and chemical recycling integration.
Food preservation commands the broadest installed base. Medical supplies represent the fastest-climbing trajectory as healthcare supply chain resilience priorities elevate domestic packaging capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary distribution hub for European vacuum sealing equipment, while the Yangtze River Delta's manufacturing density anchors Chinese export capacity for both domestic food processors and Southeast Asian markets.
United States
USDA meat inspection protocols and FDA food contact substance regulations shape equipment specifications for protein processors across the Midwest and Southeast. Chicago's industrial corridor hosts major meatpacking operations driving chamber sealer replacement cycles. California's Central Valley dairy cooperatives and Texas beef processors sustain demand for gas-flush configurations with validated sanitation protocols.
Germany
Industrial bakeries in Bavaria and meat processors in Lower Saxony anchor European replacement demand as F-Gas Regulation compliance forces cooling system redesigns. ECHA REACH restrictions on phthalate plasticizers constrain seal bar component sourcing for equipment marketed across EU member states. The Stuttgart industrial cluster concentrates precision engineering capacity for high-throughput chamber systems.
China
Coastal provinces in the Yangtze River Delta and Pearl River Delta are adding vacuum sealer assembly capacity for domestic food processors and export markets. SAMR food safety standards and GB technical regulations govern equipment certification for protein and ready-meal packaging applications. Shanghai's manufacturing base supplies Southeast Asian food processing expansion with mid-tier external sealer configurations.
Thailand
Seafood processors in Samut Sakhon and tropical fruit exporters in Chanthaburi are expanding vacuum sealing lines to reduce spoilage rates and extend export-ready shelf life. Thai FDA food contact material regulations align with EU EFSA compliance requirements for equipment serving European-bound shipments. Bangkok's industrial estates concentrate contract packaging operations serving Japanese and South Korean retail chains.
Brazil
ANVISA sanitary requirements and USDA equivalence protocols drive equipment upgrades in São Paulo and Paraná beef and poultry processing facilities. SIF export certification mandates validated vacuum cycles for protein shipments to North American and Asian markets. The Serra Gaúcha region's meatpacking cluster sustains replacement demand for semi-automatic systems bridging manual and fully automated lines.
Vacuum Sealing Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying vacuum pumps, seal bars, and control modules. The vendor base stratifies between multinational packaging conglomerates with full-line integration capabilities and regional fabricators serving cost-constrained small-to-medium processors. Three archetypes dominate: German-engineered precision specialists, North American retail packaging platform providers, and Chinese scale manufacturers. Competitive moves concentrate on geographic expansion through distributor network consolidation and technology licensing arrangements for gas-flush system integration.
Among German-engineered precision specialists, MULTIVAC Sepp Haggenmüller GmbH & Co. KG and Hawo Verarbeitungsmaschinen GmbH exemplify the chamber sealer archetype with deep European meat processing installation bases. Sealed Air Corporation anchors the North American retail packaging platform tier through brand strength in protein case-ready applications. These three occupy positions spanning premium industrial configurations through mid-tier commercial systems, with each representing distinct competitive vectors in material compliance, connected service models, and channel reach.
| Leading Market Players |
|---|
| IMA S.p.A. |
| Henkelman B.V. |
| MULTIVAC Sepp Haggenmüller GmbH & Co. KG |
| Hawo Verarbeitungsmaschinen GmbH |
| ORVED S.r.l. |
| Sealed Air Corporation |
| ULMA Packaging, S. Coop. |
| JBT Corporation |
| Syntegon Technology GmbH |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta's vacuum sealer assembly capacity expansion directly compresses pricing power for European and North American equipment manufacturers serving mid-tier external sealer segments. Stainless steel input costs from Indonesian nickel and South African chromium concentrate markets transmit volatility downstream, forcing chamber sealer fabricators to absorb margin compression or pass through to protein processors with long replacement cycles.
Pricing Analysis
Volume-discount tiering separates premium German-engineered chamber systems with F-Gas-compliant cooling architectures from standard Chinese-assembled external units and economy-grade handheld configurations. Price differentiation rests on CE marking depth, USDA meat inspection protocol validation, and attached multi-year service contracts. Pricing pressure stems from Thai and Indian food processors consolidating purchases through distributor channels that bundle consumables at compressed equipment margins. Small commercial kitchens exhibit highest price sensitivity, while pharmaceutical sterile packaging operations accept premium positioning for validated batch documentation capabilities.
Supply Chain Analysis
Supplier-financing facilities from Yangtze River Delta component vendors extend payment terms to 90-120 days, enabling Southeast Asian distributor networks to carry inventory without capital strain. Vacuum pump manufacturing concentrates in Germany, China, and Japan, with seal bar component sourcing fragmented across Italian and Taiwanese precision metalwork specialists. Raw material dependencies center on 304/316-grade stainless steel, fluoropolymer seal coatings, and copper motor windings. Single-source vulnerability runs through Indonesian nickel concentrate supply for corrosion-resistant chamber fabrication. Distribution runs through Hamburg's port logistics for European protein processors and Bangkok's industrial estates for Southeast Asian seafood exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Thai and Brazilian meatpacking conglomerates consolidating multi-line equipment purchases, fragmenting vendor pricing leverage across smaller artisan producers.
For Market Incumbents: Build switching-cost moats through IoT-enabled predictive maintenance subscriptions that digitize traditional break-fix relationships. Deepen backward integration into vacuum pump manufacturing to sidestep F-Gas Regulation refrigerant constraints. Anchor capacity in Stuttgart's precision engineering cluster for high-throughput chamber systems serving German industrial bakeries. Certification investment in ANVISA and USDA equivalence protocols defends position against emerging Chinese scale manufacturers targeting Brazilian export compliance upgrades. For New Entrants and Emerging Players: Build out modular gas-flush configurations for India's underpenetrated dairy and spice processing cooperatives, where organized retail expansion creates vacuum sealing equipment demand without incumbent service infrastructure. Target mid-volume Brazilian beef processors awaiting full chamber line upgrades through semi-automatic commercial systems bridging manual and automated operations. Go-to-market runs through WebstaurantStore and regional foodservice distributor channels displacing direct manufacturer relationships in US artisan charcuterie segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-integrated automation platform providers over legacy mechanical control specialists. Long-term viability hinges on data integration depth rather than mechanical reliability alone, compressing pure-hardware valuations while elevating connected service revenue multiples. Acquisition targets should concentrate on German precision engineering firms with deep European meat processing installation bases and proprietary vacuum cycle optimization software. Monitor EU extended producer responsibility framework implementation as inflection indicator for mono-material film compatibility investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Predictive Maintenance Platform | Converts break-fix service relationships into multi-year uptime guarantees for German industrial bakeries. |
| F-Gas-Compliant Cooling System Redesign | Enables continued EU market access for chamber sealer lines serving Dutch ready-meal facilities. |
| Mono-Material Film Compatibility Investment | Aligns equipment configurations with EU Green Deal extended producer responsibility mandates. |
| Distributor Network Consolidation | Captures Thailand seafood processor demand through Bangkok industrial estate service proximity. |
| ANVISA and USDA Certification Pathway | Unlocks Brazilian beef and poultry export access to North American and Asian markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement managers at German meat processors, maintenance directors at US industrial bakeries, and aftermarket service heads at Southeast Asian distributor networks; and secondary validation through customs trade data, EU EFSA material compliance filings, and SEC equipment manufacturer disclosures. Bottom-up triangulation across plant-level capacity assessments and top-down validation against national food processing industry association statistics anchored volume estimates.
Forecast inputs considered equipment replacement cycles, regulatory compliance deadlines, and channel shift velocities across the projection horizon. Segmentation modeling spanned product type, end-use industry, automation technology tier, and geographic regulatory cluster. CAGRs derived from installed base turnover analysis and penetration rate trajectories in emerging market cold-chain infrastructure buildouts. Industry-specific inputs included F-Gas Regulation phase-down schedules and ANVISA sanitary upgrade timelines.
Practitioners should monitor stainless steel price volatility, EU extended producer responsibility implementation pace, and IoT platform adoption rates among mid-sized processors for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Deblistering Machines Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market