
 Mexico Plastic Bottles Market | 2026-2036
Mexico Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Plastic Bottles Market Insights
Multi-source resin procurement is repositioning how converters manage polyethylene terephthalate feedstock exposure across Mexico's central highlands. ALPLA Group leverages its captive preform operations to sustain margin stability amid volatile PTA pricing cycles. Indorama Ventures Public Company Limited anchors the upstream supply base through its integrated PTA-PET complexes serving domestic blow molders. Berry Global Inc. differentiates via pharmaceutical-grade barrier bottle technologies that meet COFEPRIS serialization requirements.
Mexico plastic bottles are hollow thermoplastic containers typically blow-molded from polyethylene terephthalate, high-density polyethylene, or polypropylene resins with capacities ranging from 50 milliliters to 20 liters, designed for liquid containment, shelf-life extension, and controlled dispensing across consumer and industrial applications. PET dominates beverage packaging due to its clarity, carbonation retention, and established recycling infrastructure through Ecoce and PetStar collection networks. HDPE occupies the personal care and household chemical segments where chemical resistance and squeezability command premium positioning. The flip-top closure category is gaining traction in on-the-go food formats as convenience-driven consumption patterns reshape single-serve packaging specifications.
SEMARNAT enforces NOM-161 packaging waste standards while COFEPRIS mandates pharmaceutical primary container validation protocols that elevate barrier performance thresholds for domestic manufacturers. The Secretariat of Economy's alignment with USMCA rules of origin influences resin sourcing decisions for exporters serving United States beverage brands. Stakeholders must monitor EPR implementation timelines and rPET mandate developments to calibrate capital allocation between virgin and recycled feedstock streams.
Market Dynamics
SEMARNAT's evolving EPR mandates are compressing converter margins while forcing rapid feedstock recalibration across Mexico's blow molding sector. The regulatory pressure is accelerating capital redeployment toward rPET integration before mandate deadlines crystallize.
Growth Catalysts
- Beverage bottler capacity expansion:Carbonated soft drink and bottled water brands are commissioning new PET lines in Querétaro and Guanajuato, pulling resin demand upward through dedicated supply agreements.
- NOM-161 compliance upgrades:Packaging waste standards under SEMARNAT are triggering replacement cycles for non-compliant legacy equipment, creating equipment and resin specification refresh demand.
- Automotive supplier park co-location:Blow molding investments are clustering alongside OEM assembly plants in the Bajío corridor, reducing logistics costs for coolant and washer fluid containers.
Market Restraints
- PTA price volatility:Purified terephthalic acid feedstock swings transmit directly to PET bottle economics, squeezing converter margins when upstream aromatics spike.
- Captive resin concentration:Integrated PTA-PET complexes control domestic feedstock availability, limiting bargaining power for independent blow molders without backward supply arrangements.
- Glass substitution in premium spirits:Tequila and mezcal exporters retain glass for heritage positioning, capping PET penetration in high-margin alcoholic beverage segments.
Strategic Opportunities
- Pharmaceutical barrier bottles:COFEPRIS serialization requirements are elevating technical specifications for domestic drug packaging, opening premium positioning for validated container suppliers.
- Flip-top closure food formats:On-the-go consumption patterns are expanding addressable demand for single-serve sauces and condiments in convenience retail channels.
- USMCA rules alignment:Exporters serving United States beverage brands can capture tariff-advantaged volume by certifying North American resin content in their supply chains.
Industry Challenges
- Rapid EPR implementation timelines:Stakeholders face compressed windows to validate rPET feedstock streams and requalify container performance before mandate enforcement begins.
- Barrier technology integration:Pharmaceutical-grade multilayer and scavenger systems require capital-intensive equipment upgrades that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Plastic Bottles Market |
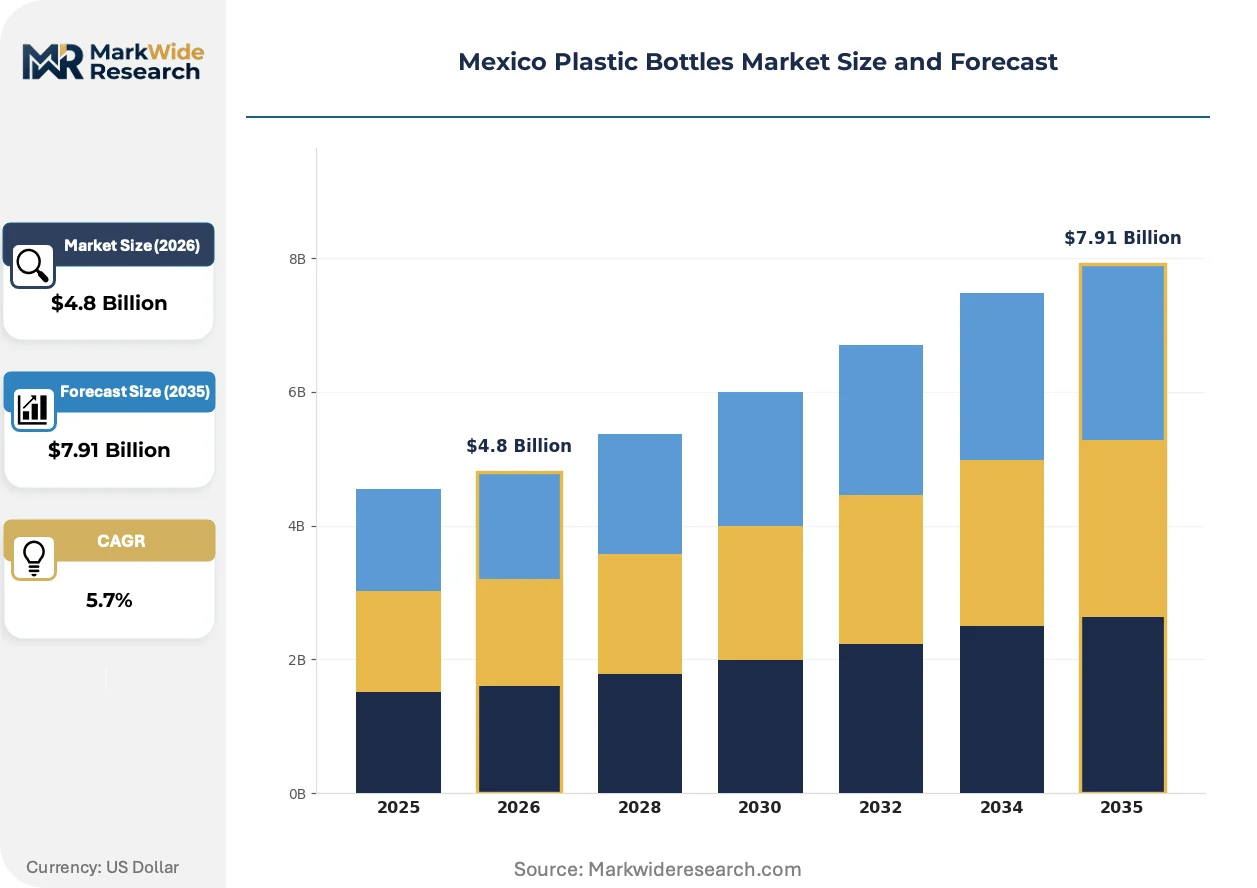
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PP Closure Type: Screw Cap, Snap Cap, Flip Top, Sports Cap End User: Food & Beverage, Personal Care, Household, Pharmaceutical Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Plastimax, S.A., Gerresheimer AG, ALPLA Group, Maxipet S.A de C.V., Indorama Ventures Public Company Limited, Amcor Group, Pretium Packaging, VALGROUP, Berry Global Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Plastic Bottles Market Trends and Innovations
Lightweighting and circular feedstock integration are converging to redefine competitive technical specifications across Mexico's packaging value chain. Material science advances and regulatory compliance requirements are jointly elevating performance thresholds.
Advanced barrier co-injection technology is modularizing how pharmaceutical and sensitive food applications achieve oxygen and moisture protection. Domestic converters serving COFEPRIS-regulated drug packaging are adopting these systems to replace glass and metal primary containers. The technology is modularizing quality assurance workflows by embedding validation protocols directly into production lines, compressing batch release timelines.
SEMARNAT's packaging waste regulations are mandating minimum recycled content thresholds that cascade through supply contracts. Blow molders must now certify rPET sourcing through approved collection networks like Ecoce and PetStar to maintain brand supplier status. The pharmaceutical segment faces the steepest compliance burden, as COFEPRIS requires additional extractables testing for recycled feedstock containers.
Brand procurement teams are consolidating supplier panels around converters with verified circular feedstock capabilities. Large beverage bottlers are eliminating single-source resin dependencies and demanding documentation of post-consumer content percentages. This pattern concentrates contract awards in the Bajío industrial corridor, where integrated preform-to-bottle operations can demonstrate closed-loop material flows.
Mexico Plastic Bottles Market Segmentation
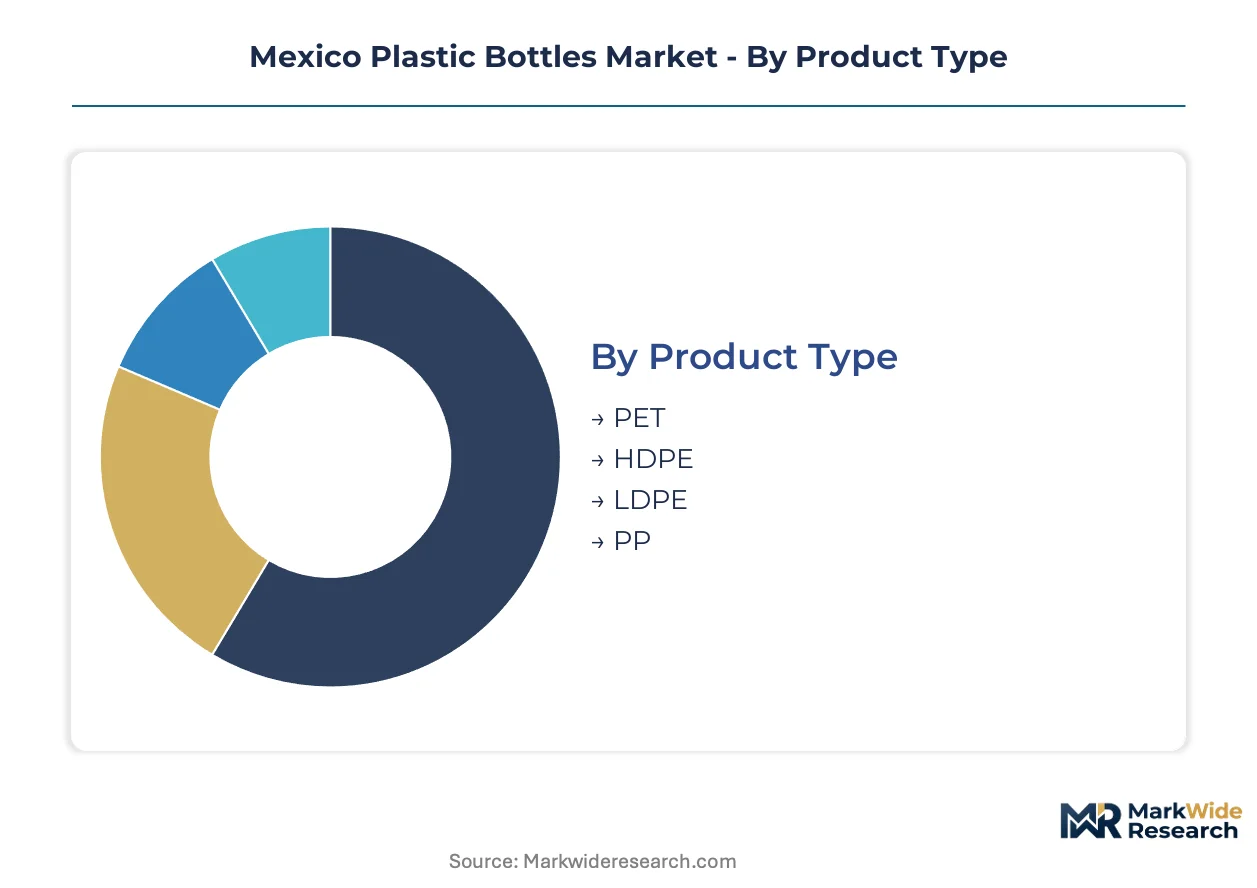
Mexico's plastic bottles market fragments across resin chemistry, closure engineering, and end-use specifications that dictate barrier requirements and regulatory compliance pathways. Converters calibrate production assets to these segment boundaries because resin selection and closure integration determine which SEMARNAT and COFEPRIS standards apply.
Product Type:
PET capacity concentrates around Indorama Ventures' integrated PTA-PET complexes, creating feedstock dependencies that shape converter procurement strategies across the Bajío corridor.
- PET:Polyethylene terephthalate delivers optical clarity and carbonation retention for beverage applications. Demand clusters in Querétaro and Guanajuato bottling corridors where carbonated soft drink and water brands are commissioning dedicated lines. SEMARNAT's rPET mandates are forcing rapid feedstock recalibration before enforcement deadlines crystallize.
- HDPE:High-density polyethylene offers chemical resistance and squeezability for personal care and household formulations. Automotive supplier parks in Aguascalientes are pulling HDPE demand for coolant and washer fluid containers through co-located blow molding investments. PTA price volatility transmits directly to PET economics, making HDPE an attractive margin hedge for converters with multi-resin capability.
- LDPE:Low-density polyethylene serves squeeze tube and flexible bottle applications where softness and conformability outweigh structural rigidity.
- PP:Polypropylene occupies high-temperature food and pharmaceutical segments requiring autoclave sterilization compatibility.
PET absorbs the bulk of installed capacity; PP is expanding most quickly as pharmaceutical barrier specifications tighten.
Closure Type:
Closure engineering determines dispensing convenience and tamper-evidence standards that vary sharply between pharmaceutical serialization and food service applications.
- Screw Cap:Threaded closure systems dominate bulk liquid packaging where resealability and leak resistance are paramount. Beverage bottlers in the Bajío corridor specify 28mm and 38mm PCO neck finishes as standard across carbonated and still water lines.
- Snap Cap:Press-fit closures serve single-serve dairy and juice segments where opening torque must accommodate elderly and pediatric consumers.
- Flip Top:Hinged lid designs are gaining traction in on-the-go condiment and sauce formats as convenience retail channels expand. Food processors are specifying flip-top bottles for single-serve ketchup, mustard, and hot sauce portions in OXXO and 7-Eleven distribution.
- Sports Cap:Push-pull and nozzle closures target fitness beverage and isotonic drink segments where one-handed operation during physical activity is essential.
Screw cap configurations retain the largest production volume; flip top formats are climbing the fastest as convenience-driven consumption patterns reshape single-serve specifications.
End User:
End-use segmentation separates regulated pharmaceutical applications from commodity beverage and household chemical markets with vastly different validation burdens.
- Food & Beverage:Carbonated soft drinks, bottled water, juices, and edible oils constitute the volume foundation. Brand procurement teams are consolidating supplier panels around converters with verified circular feedstock capabilities through Ecoce and PetStar networks.
- Personal Care:Shampoo, conditioner, lotion, and cosmetic bottles demand squeezability and chemical resistance that HDPE delivers. E-commerce penetration is elevating leak-proof performance standards for direct-to-consumer shipping durability.
- Household:Cleaning agents, detergents, and automotive chemicals require chemical compatibility and child-resistant closure integration. Co-location with OEM assembly plants in Guanajuato is reducing logistics costs for coolant and washer fluid containers.
- Pharmaceutical:COFEPRIS-mandated serialization and barrier validation elevate technical specifications for domestic drug packaging. Extractables testing requirements for rPET feedstock containers impose the steepest compliance burden across all segments.
Food and beverage commands the dominant share of converter output; pharmaceutical applications are gaining share fastest as barrier technology investments mature.
Distribution Channel:
Channel structure determines order lot sizes, lead time tolerances, and packaging customization depth that converters must engineer into production workflows.
- Retail:Supermarket and convenience store supply chains require high-volume, standardized SKUs with rapid replenishment cycles. Walmart México and Soriana are consolidating supplier bases around blow molders with rPET certification.
- E-commerce:Direct-to-consumer fulfillment demands enhanced leak resistance and shipping durability that exceed traditional retail specifications. Amazon México and Mercado Libre are driving secondary packaging requirements that cascade back to primary bottle design.
- Wholesale:Cash-and-carry and distributor channels serve smaller format retailers with larger lot sizes and less frequent ordering patterns.
- Direct Sales:Converter-to-brand relationships bypass distribution intermediaries for large beverage and pharmaceutical accounts with dedicated line commitments.
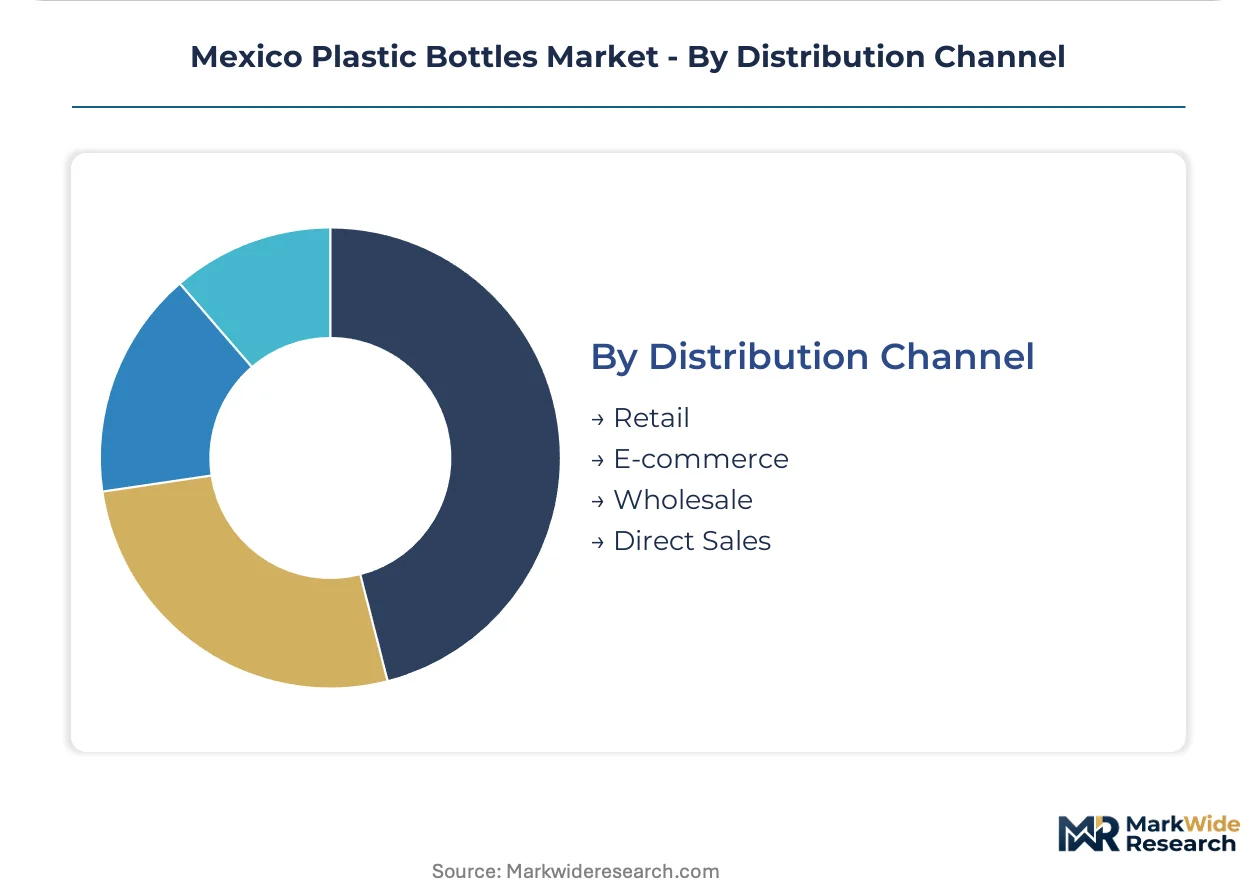
Retail channels absorb the bulk of volume throughput; e-commerce is expanding most quickly as last-mile delivery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PET resin production clusters anchor Mexico's plastic bottle manufacturing geography, with integrated PTA-PET complexes in Veracruz and Tamaulipas feeding blow molding operations across the central highlands. Converter capacity distributes across three distinct industrial corridors shaped by end-use demand concentrations and logistics infrastructure.
Bajío Region
Carbonated soft drink and bottled water brands are commissioning dedicated PET lines in Querétaro and Guanajuato, pulling resin demand upward through supply agreements with Indorama Ventures' regional distribution network. SEMARNAT's NOM-161 packaging waste standards are triggering equipment replacement cycles among legacy converters in León and Celaya. Automotive supplier parks in Silao and Irapuato are spurring co-located blow molding investments for coolant and washer fluid containers.
Nuevo León
Monterrey's industrial base sustains HDPE demand for household chemical and personal care applications where chemical resistance commands premium positioning. The state's environmental regulator enforces waste management protocols that accelerate rPET feedstock validation timelines for exporters serving United States beverage brands. Garcia and Santa Catarina host concentrated converter operations supplying Walmart México and Soriana distribution centers.
Jalisco
Tequila and mezcal exporters in the Highlands retain glass for heritage positioning, capping PET penetration in premium spirits despite lightweighting advances. COFEPRIS-mandated pharmaceutical serialization requirements are elevating technical specifications for domestic drug packaging in Guadalajara's medical device corridor. Zapopan-based converters are investing in barrier co-injection systems to replace glass primary containers for regulated drug applications.
Mexico City Metro
The Valley of Mexico absorbs the highest volume of flip-top closure bottles for on-the-go condiment formats distributed through OXXO and 7-Eleven convenience channels. E-commerce penetration through Amazon México and Mercado Libre is elevating leak-proof performance standards that cascade back to primary bottle design specifications. Toluca and Cuautitlán Izcalli host contract manufacturing operations serving multinational FMCG brand procurement teams.
Northern Border States
Chihuahua and Baja California converters leverage USMCA rules of origin alignment to capture tariff-advantaged volume certifying North American resin content. Maquiladora operations in Ciudad Juárez and Tijuana supply cross-border beverage bottlers with just-in-time replenishment cycles. The Secretariat of Economy's export certification programs are consolidating supplier panels around operations with verified circular feedstock capabilities through Ecoce collection networks.
Mexico Plastic Bottles Market Competitive Landscape
Global majors compete with regional champions across resin integration and barrier technology dimensions, producing a tiered structure where captive feedstock operations command pricing leverage over independent blow molders. Integrated PTA-PET complexes control domestic resin availability, while pharmaceutical-grade specialists occupy premium positioning through COFEPRIS validation protocols. Three archetypes dominate: upstream-integrated resin producers, multi-site blow molding converters, and barrier technology specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with brand procurement teams consolidating supplier panels around verified circular feedstock capabilities.
Within the upstream-integrated tier, Indorama Ventures Public Company Limited anchors domestic PET supply through its regional distribution infrastructure. ALPLA Group exemplifies the multi-site converter archetype with captive preform operations sustaining margin stability. Berry Global Inc. occupies a position among barrier technology specialists serving COFEPRIS-regulated pharmaceutical applications. These three entities represent distinct strategic postures: resin control, operational scale, and technical differentiation.
| Leading Market Players |
|---|
| Plastimax, S.A. |
| Gerresheimer AG |
| ALPLA Group |
| Maxipet S.A de C.V. |
| Indorama Ventures Public Company Limited |
| Amcor Group |
| Pretium Packaging |
| VALGROUP |
| Berry Global Inc. |
| Others |
Pricing and Supply Chain Analysis
Brand procurement consolidation around rPET-certified suppliers is compressing order flow to converters with verified circular feedstock documentation, forcing independent blow molders to absorb certification costs or exit supplier panels. This demand-side filtering is restructuring pricing power toward integrated operations that can demonstrate closed-loop material flows through Ecoce and PetStar networks.
Pricing Analysis
Service bundling separates pharmaceutical-grade barrier validation from commodity beverage contracts, with COFEPRIS serialization protocols commanding substantial premiums over standard PET. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with barrier technology specialists capturing margin premiums while commodity converters face cost compression from PTA price volatility. Pricing pressure stems from SEMARNAT's EPR mandate deadlines accelerating rPET investment requirements. Independent blow molders without backward integration into resin supply exhibit highest price sensitivity; pharmaceutical barrier specialists demonstrate lowest sensitivity due to technical differentiation.
Supply Chain Analysis
COFEPRIS and SEMARNAT qualification requirements gate supplier status, with approved collection network certification becoming mandatory for brand supplier retention. Feedstock availability concentrates in Thailand, Mexico, and the United States through Indorama Ventures' integrated PTA-PET complexes and regional distribution infrastructure. Raw material dependencies center on purified terephthalic acid, ethylene glycol, and post-consumer flake supply from approved collection networks. Single-source vulnerability runs through captive resin concentration at integrated complexes. Distribution runs through dedicated supply agreements with beverage bottlers and pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around converters with verified circular capabilities, with SEMARNAT's EPR enforcement timelines forcing weaker players without rPET infrastructure into acquisition or exit.
For Market Incumbents: Anticipate margin compression from PTA price volatility by securing multi-source resin procurement agreements and accelerating captive preform capacity expansion in the Bajío corridor. Threat from integrated resin producers backward into blow molding necessitates barrier technology investment for pharmaceutical segment defense. Certification leverage through COFEPRIS validation protocols is the critical differentiation lever. For New Entrants and Emerging Players: Launch via pharmaceutical barrier bottle specialization targeting COFEPRIS-regulated serialization requirements, where technical validation barriers limit incumbent response speed. White-space exists in flip-top closure food formats for OXXO and 7-Eleven convenience channels. Go-to-market angle should emphasize rapid rPET certification through Ecoce network partnerships. For Investors and Strategic Acquirers: The window for entry favors mid-cap converters with installed barrier co-injection capacity and incomplete rPET integration, offering bolt-on certification assets. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch for SEMARNAT enforcement deadline announcements as inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Integration Investment | SEMARNAT mandate compliance secures brand supplier status through Ecoce network certification. |
| Barrier Technology Acquisition | COFEPRIS validation capabilities capture pharmaceutical segment premium positioning. |
| Bajío Corridor Capacity Expansion | Co-location with automotive supplier parks reduces logistics costs for coolant containers. |
| Multi-Source Resin Procurement | PTA price volatility hedging sustains margin stability across pricing cycles. |
| Flip-Top Closure Format Launch | Convenience retail channel penetration captures on-the-go consumption growth. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with blow molding plant managers, beverage brand procurement leads, pharmaceutical packaging engineers, and SEMARNAT compliance officers. Secondary sources included COFEPRIS drug registration databases, SEC 10-K filings from listed packaging companies, and Ecoce collection network operational reports. Bottom-up resin demand modeling and top-down packaging consumption estimates were triangulated to calibrate market sizing.
Reconciliation of production capacity data, import-export flows, and end-use consumption patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled included resin chemistry, closure engineering, end-use regulatory pathway, and regional industrial corridor concentration. CAGRs were derived from trend extrapolation of resin demand and equipment investment cycles, with specific inputs from PTA pricing volatility indices and EPR implementation timeline scenarios.
EPR mandate acceleration, PTA feedstock price spikes, and COFEPRIS protocol amendments are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory enforcement schedules and collection network expansion rates. A model refresh is warranted upon material change in SEMARNAT implementation timelines or rPET mandate thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Vietnam Plastic Bottles Market