
 North America Biodegradable Plastic Market | 2026-2036
North America Biodegradable Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biodegradable Plastic Market Intelligence
Food packaging is consolidating as the dominant end-use vertical across North America, displacing conventional petroleum-based films in quick-service restaurant supply chains. NatureWorks LLC leverages its Blair, Nebraska manufacturing complex to anchor domestic PLA resin supply for this channel. Danimer Scientific differentiates through PHA fermentation technology leadership, while TotalEnergies Corbion sustains European-North American integrated production for high-performance applications.
Biodegradable plastics comprise polymers engineered to decompose through microbial action into carbon dioxide, water, and biomass under composting conditions, with PLA requiring industrial composting temperatures above 55 degrees Celsius to achieve full mineralization within 180 days. These materials serve primarily as drop-in replacements for conventional plastics in single-use applications where end-of-life collection infrastructure supports composting streams. PLA dominates current production volume given mature fermentation and ring-opening polymerization infrastructure, while PHA captures expanding margin pools due to marine biodegradability certifications and home-composting compatibility. The packaging application segment leads absolute consumption, though agriculture films represent the fastest structural expansion as soil-biodegradable standards tighten across California and Florida growing regions.
The US EPA and state environmental agencies shape demand through emerging extended producer responsibility frameworks and composting infrastructure investment mandates, while the USDA BioPreferred program creates procurement preference channels for federal and institutional buyers. ASTM D6400 and D6868 certification requirements govern industrial compostability claims, filtering market access for uncertified imports. Stakeholders must monitor regulatory fragmentation between California's SB 54 implementation and pending federal labeling standards to anticipate compliance cost trajectories and qualification timelines.
Market Dynamics
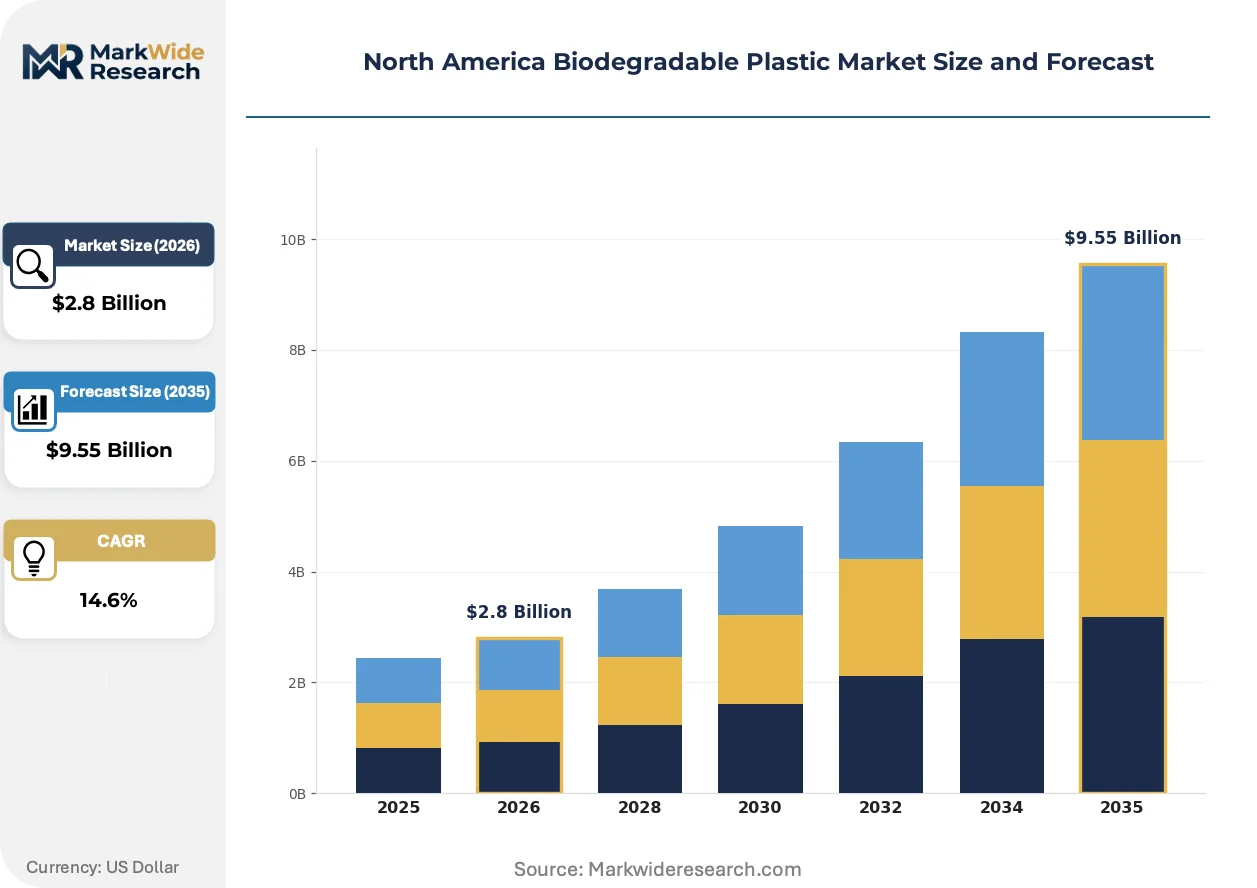
State-level extended producer responsibility mandates are compressing conventional plastic demand across quick-service restaurant supply chains, while industrial composting infrastructure gaps create geographic arbitrage between California's Central Valley agricultural film sector and the US Northeast retail packaging corridor.
Growth Catalysts
- SB 54 Implementation:California's extended producer responsibility law mandates 30% source reduction and recycling targets, forcing material substitution in food service packaging by 2032.
- USDA BioPreferred Program:Federal procurement preference channels create institutional demand anchors for certified biodegradable alternatives across military and school foodservice contracts.
- PHA Fermentation Scale-Up:Marine biodegradability certifications and home-composting compatibility expand addressable markets beyond industrial composting infrastructure constraints.
Market Restraints
- Feedstock Price Volatility:Corn starch and sugarcane price swings transmit directly to PLA resin economics, compressing margin stability for converters.
- Midwest Supply Concentration:NatureWorks' Blair, Nebraska complex controls dominant domestic PLA capacity, creating single-source risk for food packaging supply chains.
- Industrial Composting Temperature Requirements:PLA mineralization demands sustained conditions above 55 degrees Celsius unavailable in most municipal composting facilities.
Strategic Opportunities
- Florida Agricultural Film Demand:Soil-biodegradable mulch film standards tightening in strawberry and tomato growing regions create structural expansion beyond California's established market.
- Quick-Service Restaurant Channel Consolidation:Chain-level sustainability commitments at McDonald's, Chipotle, and Starbucks create volume aggregation points for certified material suppliers.
- Federal Labeling Standardization:Pending EPA biodegradable claims guidance would reduce state-by-state compliance fragmentation and accelerate cross-border supply chain rationalization.
Industry Challenges
- ASTM D6400 Certification Timelines:Six-to-twelve month third-party validation cycles delay product launches and tie up working capital in pre-revenue inventory.
- Composting Infrastructure Skill Gaps:Facility operators lack training to distinguish certified biodegradable streams from conventional plastic contamination, causing feedstock rejection rates above 15%.
- Legacy Equipment Retrofit Costs:Conventional extrusion and thermoforming lines require screw, die, and cooling modifications to process PLA's lower thermal stability versus polypropylene.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biodegradable Plastic Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-Based, PBS Application: Packaging, Agriculture, Consumer Goods, Textiles Form: Films, Rigid Containers, Bags, Coatings End User: Food Industry, Retail Sector, Pharmaceuticals, Electronics |
| Companies Covered | NatureWorks LLC, BASF SE, Novamont S.p.A., Danimer Scientific, Mitsubishi Chemical Corporation, Braskem, Biome Bioplastics, TotalEnergies Corbion, Green Dot Bioplastics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biodegradable Plastic Market Strategic Shifts & Innovations
Material science advances and regulatory compression are converging to redefine competitive advantage around end-of-life performance credentials rather than unit economics alone.
PHA copolymer formulations are overtaking PLA in marine-sensitive applications, with Danimer Scientific's Nodax platform achieving ASTM D6691 marine biodegradability certification. Quick-service restaurant chains with coastal exposure are specifying PHA for cutlery and straws despite 40% unit cost premiums. This material transition is compressing PLA's historical dominance in food service disposables and forcing resin suppliers to defend position through blending partnerships rather than volume scale.
The EPA's emerging sustainable materials management framework is mandating lifecycle assessment disclosure for federal contractors, creating procurement friction for uncertified imports. State environmental agencies in California, Washington, and Maine are layering complementary labeling requirements that exceed federal baselines. Food packaging converters are responding by consolidating supplier qualification around ASTM D6400 and D6868 dual-certified resin sources to minimize compliance fragmentation.
Chain-level sustainability scorecards are displacing unit-cost procurement criteria in quick-service restaurant buying committees, with Scope 3 emissions disclosure requirements penetrating RFP language by 2024. Distributor consolidation at Sysco and US Foods is amplifying this shift by bundling certified packaging with refrigerated logistics contracts. The US Northeast retail packaging corridor from Boston to Washington DC exhibits the fastest behavioral adoption, driven by municipal composting infrastructure density and consumer-facing brand pressure.
North America Biodegradable Plastic Market Segmentation
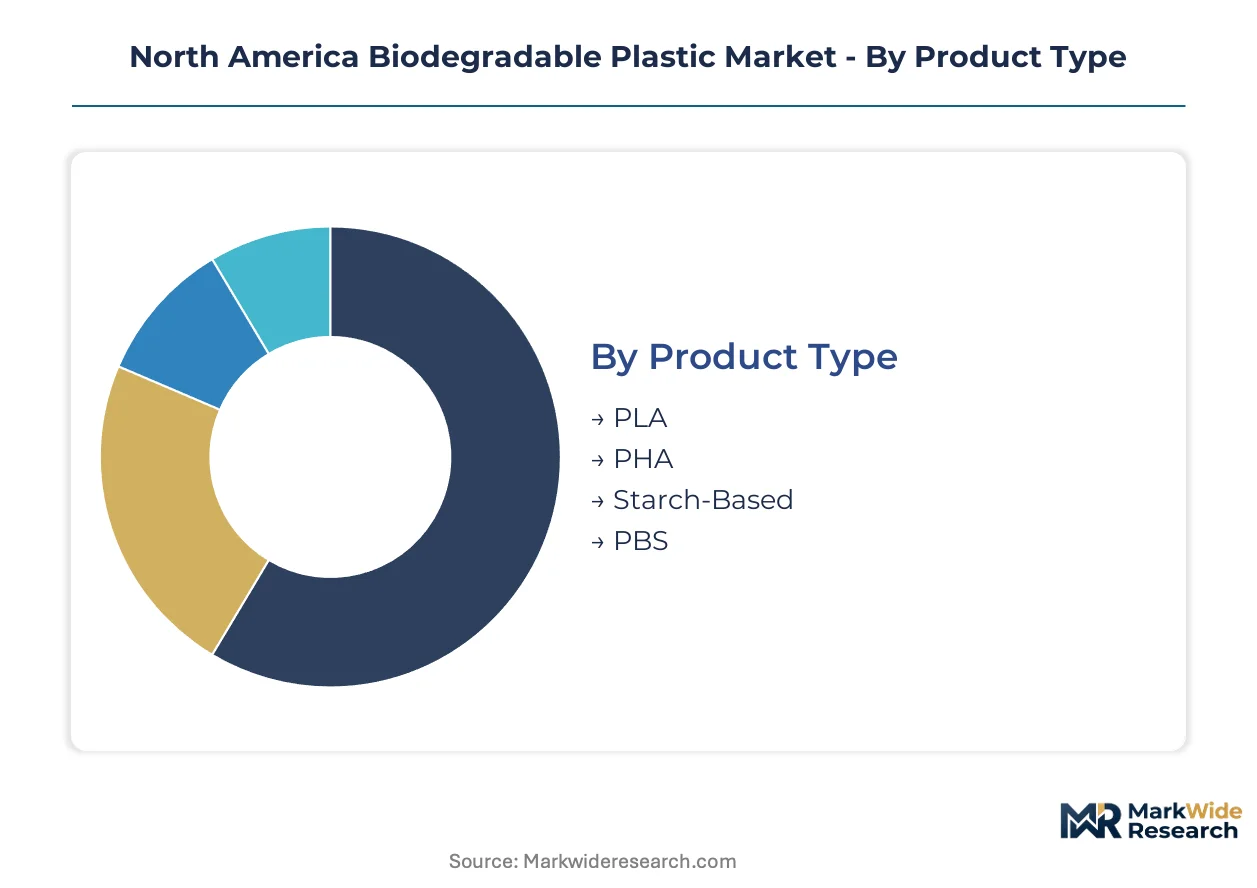
Biodegradable plastic demand fragments across material chemistries, application requirements, and end-user compliance standards. Each segmentation dimension carries distinct supply chain implications for converters and brand owners navigating ASTM certification complexity.
Product Type:
Domestic resin capacity concentrates around fermentation infrastructure in the US Midwest, creating geographic lock-in for specific polymer families.
- PLA:Polylactic acid derives from corn starch through ring-opening polymerization, requiring industrial composting above 55 degrees Celsius for mineralization. Demand concentrates in California's Central Valley agricultural film sector and quick-service restaurant supply chains, where NatureWorks' Blair, Nebraska complex anchors domestic supply security.
- PHA:Polyhydroxyalkanoates achieve marine biodegradability under ASTM D6691 and home-composting compatibility, expanding addressable markets beyond industrial composting infrastructure constraints. Danimer Scientific's fermentation leadership captures premium positioning in coastal quick-service restaurant specifications despite unit cost premiums.
- Starch-Based:Thermoplastic starch compounds blend with synthetic polymers to accelerate disintegration rates in soil environments.
- PBS:Polybutylene succinate offers higher thermal stability than PLA, suiting injection-molded durable goods with biodegradation pathways.
Today's leader: PLA. Tomorrow's challenger: PHA.
Application:
End-use requirements dictate certification tier and composting infrastructure dependency, segmenting margin profiles across the value chain.
- Packaging:Food contact films and rigid containers dominate absolute consumption volume, with quick-service restaurant chains at McDonald's, Chipotle, and Starbucks aggregating procurement through distributor consolidation at Sysco and US Foods. The US Northeast retail packaging corridor from Boston to Washington DC exhibits fastest behavioral adoption.
- Agriculture:Soil-biodegradable mulch films represent the steepest expansion trajectory as California and Florida tighten standards for strawberry and tomato growing regions, displacing conventional polyethylene retrieval costs.
- Consumer Goods:Disposable cutlery, straws, and serviceware face SB 54 compliance pressure in California.
- Textiles:Nonwoven applications in agriculture and hygiene products leverage fiber-grade PLA and PHA.
Packaging commands current volume. Agriculture climbs the fastest.
Form:
Processing technology requirements segment converter capabilities and capital investment thresholds.
- Films:Agricultural mulch and food packaging films require blown extrusion lines with modified cooling profiles for PLA's narrow processing window.
- Rigid Containers:Thermoformed cups and clamshells demand plug-assist tooling adjustments for PLA's lower thermal stability versus polypropylene.
- Bags:T-shirt and carryout bag specifications concentrate in municipal composting jurisdictions with collection infrastructure.
- Coatings:Paperboard barrier coatings for hot cups and food service items require aqueous dispersion compatibility.
Films anchor resin demand. Rigid containers gain share through quick-service restaurant conversion.
End User:
Procurement authority and compliance exposure segment customer lifetime value and contract structure.
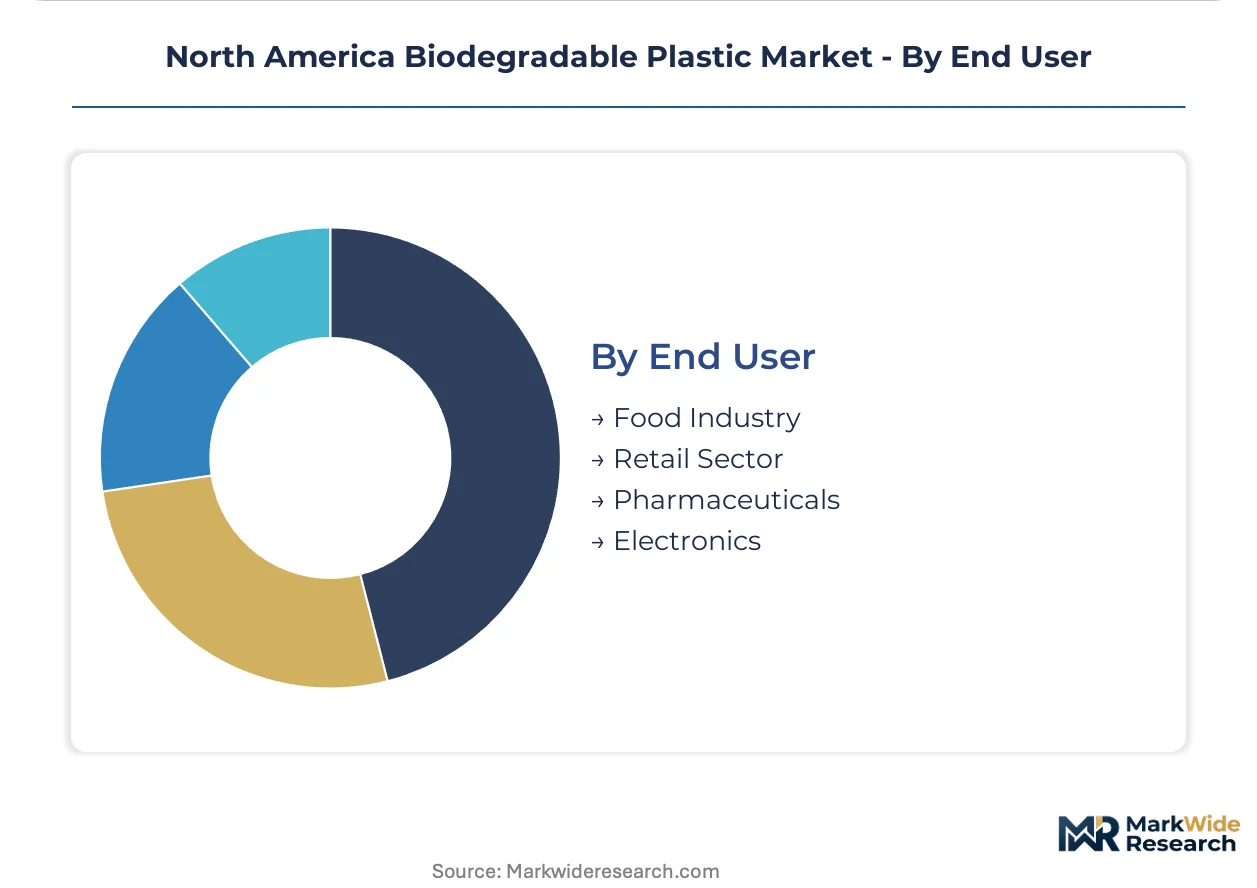
- Food Industry:Quick-service restaurants and foodservice distributors face direct SB 54 extended producer responsibility mandates, forcing material substitution with certified ASTM D6400 sources. USDA BioPreferred program procurement preference creates federal contract anchors.
- Retail Sector:Grocery and consumer packaged goods brands respond to municipal composting infrastructure density and consumer-facing sustainability scorecards.
- Pharmaceuticals:Medical device and packaging applications require US FDA food contact notification compliance alongside biodegradation credentials.
- Electronics:Durable goods and component packaging represent emerging demand with longer product lifecycle considerations.
Food industry drives certified volume. Retail sector expands the addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley agricultural film sector anchors North American demand concentration, with state-level extended producer responsibility mandates compressing conventional plastic substitution timelines across food packaging and agricultural end-uses.
United States
California's SB 54 mandates 30% source reduction and recycling targets by 2032, forcing material substitution across quick-service restaurant supply chains. The EPA's emerging sustainable materials management framework mandates lifecycle assessment disclosure for federal contractors. The US Northeast retail packaging corridor from Boston to Washington DC exhibits fastest behavioral adoption, driven by municipal composting infrastructure density.
Canada
Federal procurement channels through the Canadian Environmental Protection Act create institutional demand anchors for certified biodegradable alternatives. Health Canada and Environment and Climate Change Canada coordinate plastic waste reduction strategy implementation. Ontario and Quebec concentrate converter capacity near Toronto and Montreal, serving cross-border food packaging supply chains.
Mexico
The Secretariat of Environment and Natural Resources (SEMARNAT) advances extended producer responsibility frameworks for single-use plastics, creating compliance pressure in food service and retail channels. Mexico City Metro and Nuevo León industrial corridors concentrate thermoforming and extrusion capacity for North American supply chain integration.
North America Biodegradable Plastic Market Key Industry Players
Capacity expansion dominates the current landscape as fermentation infrastructure scales to meet quick-service restaurant procurement consolidation. The market structure concentrates around integrated resin producers with captive agricultural feedstock supply, creating tiered competition between PLA and PHA technology platforms. Three strategic archetypes define positioning: Midwest-based fermentation specialists, European-North American integrated producers, and marine-biodegradability-certified technology leaders. Competitive moves center on fermentation scale-up and ASTM certification qualification timelines.
Within the integrated production tier, NatureWorks LLC and TotalEnergies Corbion exemplify geographic anchoring strategies, while Danimer Scientific occupies a position as the marine-biodegradability-certified technology specialist. These three companies represent the dominant archetypes: captive Midwest feedstock integration, transatlantic production coordination, and home-composting-compatible fermentation platforms respectively.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| Novamont S.p.A. |
| Danimer Scientific |
| Mitsubishi Chemical Corporation |
| Braskem |
| Biome Bioplastics |
| TotalEnergies Corbion |
| Green Dot Bioplastics |
| Others |
Cost & Logistics Intelligence
Corn starch and sugarcane price swings transmit directly through PLA resin economics, compressing margin stability for converters and forcing tiered pricing stratification across premium ASTM D6400-certified grades, standard industrial composting streams, and economy-grade agricultural film alternatives.
Pricing Analysis
Distributor margin compression at Sysco and US Foods channels price pressure upstream to resin suppliers, while direct-to-OEM volume contracts with McDonald's and Chipotle secure preferential rates. Three-tier pricing structure across premium PHA marine-certified, standard PLA industrial-composting, and economy starch-blend tiers differentiates by certification level and biodegradation pathway. Cost compression in standard PLA grades intensifies because NatureWorks' Blair complex controls dominant domestic capacity. Quick-service restaurant procurement committees exhibit lowest price sensitivity due to SB 54 compliance mandates, while independent agricultural film distributors remain most price-elastic.
Supply Chain Analysis
Fermentation feedstock supply rests on Midwest corn belt production, Thai sugarcane plantations, and Brazilian sugar ethanol operations. Raw material dependencies span dextrose from wet-milling operations, cane sugar for TotalEnergies Corbion's integrated production, and waste glycerol for emerging PHA fermentation pathways. Single-source vulnerability concentrates in Nebraska's Blair complex, which feeds California's Central Valley agricultural film sector and the US Northeast retail packaging corridor. Distribution runs through converter networks near Toronto, Montreal, and Mexico City Metro, with cross-border logistics amplifying tariff exposure under USMCA renegotiation pressures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America biodegradable plastic market compounds steadily as state extended producer responsibility mandates tighten conventional plastic substitution timelines across food packaging and agricultural end-uses.
For Market Incumbents: Acquire fermentation capacity in the US Southeast to diversify feedstock sourcing away from Midwest corn concentration. Secure dual ASTM D6400 and D6691 certification for resin grades to defend margin position against PHA substitution in coastal quick-service restaurant specifications. Channel control through exclusive distributor agreements with Sysco and US Foods locks out emerging competitors. For New Entrants and Emerging Players: Enter via Florida's strawberry and tomato growing regions, where soil-biodegradable mulch film standards are tightening fastest and incumbent supply chains remain underdeveloped. Target agricultural film applications as the most penetrable segment given retrieval cost displacement economics and weaker incumbent certification lock-in. Pursue toll-manufacturing partnerships with existing thermoforming capacity in Mexico City Metro to bypass capital-intensive fermentation buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where ASTM certification timelines and working capital requirements strand sub-scale converters. Long-term viability favors integrated producers with captive agricultural feedstock supply and dual-technology platforms spanning PLA and PHA. The signal to monitor is federal biodegradable claims guidance from the EPA, which would reduce state-by-state compliance fragmentation and accelerate cross-border supply chain rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Fermentation scale-up in the US Southeast diversifies feedstock sourcing beyond Nebraska corn concentration. |
| Backward Integration | Captive sugarcane supply in Thailand secures raw material cost stability for TotalEnergies Corbion's integrated production. |
| Green Manufacturing Transition | Renewable energy procurement for Blair complex operations reduces Scope 3 emissions disclosure pressure from quick-service restaurant buyers. |
| Long-term Supply Agreement | Multi-year offtake contracts with McDonald's and Chipotle aggregate volume and justify fermentation capacity expansion. |
| Joint Venture | Partnerships between PHA technology specialists and Midwest corn processors bridge marine biodegradability credentials with feedstock scale. |
Research Approach
Direct dialogue with resin plant managers, quick-service restaurant procurement directors, agricultural film converters, composting facility operators, and state environmental agency officials grounded qualitative findings, cross-referenced with USDA BioPreferred program databases, EPA sustainable materials management filings, ASTM certification registries, and customs trade flow records. Bottom-up volume estimates from individual production facilities triangulated against top-down demand aggregation from end-use sector consumption patterns.
Segmentation outputs across material chemistry, application requirement, end-user compliance standard, and geographic production hub informed the analytical framework throughout the forecast period. CAGRs derived from regression analysis of historical capacity expansion rates against regulatory mandate implementation timelines, with specific inputs including SB 54 source reduction targets and USDA federal procurement volume commitments.
Inputs from state environmental agency officials and composting facility operators were available through the study window; gaps in real-time industrial composting capacity utilization data introduce uncertainty bands around demand elasticity assumptions. Forecasts reflect documented assumptions regarding SB 54 enforcement timing and federal labeling standardization progress. A small set of triggers—including EPA biodegradable claims guidance release and California agricultural film standard tightening—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Global Biodegradable Tableware Market