
 Agriculture Chemical Packaging Market | 2026-2036
Agriculture Chemical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Chemical Packaging Market Outlook
The agriculture chemical packaging sector is consolidating around a widening split between multi-layer barrier systems for regulated active ingredients and standard polyethylene formats for bulk fertilizer. Greif Inc. leverages its steel drum and intermediate bulk container footprint to dominate industrial-scale herbicide distribution across North American grain corridors. Amcor Plc sustains leadership in high-performance coextruded films through R&D intensity focused on permeation resistance for volatile organophosphates. Mauser Packaging Solutions anchors its position via captive reconditioning networks that lower total cost of ownership for crop protection multinationals.
Agriculture chemical packaging encompasses engineered containers, films, and closures designed to contain pesticides, fertilizers, herbicides, and insecticides with specified barrier properties against moisture ingress, UV degradation, and vapor loss, typically constructed from coextruded polyethylene, polypropylene, fluoropolymer laminates, or coated metals with permeation rates measured in grams per square meter per day. Its primary commercial purpose is to preserve chemical efficacy through shelf life and transport while preventing environmental release and human exposure during field handling. Plastic formats lead volume due to cost scalability, yet metal drums retain margin concentration for corrosive formulations and regulated substances. Bags are capturing application share in soluble fertilizer and seed treatment segments where dosing precision and reduced packaging mass matter. Pesticide applications command the most stringent barrier specifications, creating technology leadership rewards for suppliers with fluoropolymer or ethylene vinyl alcohol expertise.
EPA regulates container integrity and residue removal under the Pesticide Container and Containment Rule, while REACH and EU F-Gas Regulation govern material composition and emissions profiles for products entering European agrochemical channels. Brazil's national environmental regulator enforces ANVISA-aligned packaging standards for glyphosate and neonicotinoid distribution, forcing reformulation of legacy HDPE designs. Stakeholders must monitor tightening residue thresholds and extended producer responsibility frameworks that will reshape material selection and collection infrastructure commitments without warning.
Market Dynamics
Specialty crop protection programs are expanding adoption among precision farming operators, forcing packaging suppliers to engineer dosing-precision formats that bridge bulk agricultural logistics with field-level application accuracy. This structural pull is fragmenting demand between industrial-scale containers and micro-dose sachets.
Growth Catalysts
- REACH compliance mandates:The EU F-Gas Regulation and ECHA material specifications are accelerating replacement of legacy HDPE with fluoropolymer laminates for volatile organophosphate containment.
- Brazil's Cerrado soybean belt:Treated seed volumes are concentrating demand for soluble fertilizer bags with reduced packaging mass and dosing precision features.
- Coextrusion barrier advances:Ethylene vinyl alcohol film technology is enabling thinner-wall constructions without permeation rate degradation, cutting material intensity per container.
Market Restraints
- Fluoropolymer resin supply concentration:Barrier-layer raw material sourcing clusters among specialty chemical producers in Germany and Japan, exposing converters to input cost volatility and allocation constraints.
- Extended producer responsibility frameworks:EU packaging waste directives are forcing capital commitments to collection infrastructure before volume economics justify network density.
- Steel drum substitution limits:Corrosive formulations and regulated substances retain metal format requirements, preventing full plastic conversion in high-margin pesticide segments.
Strategic Opportunities
- Captive reconditioning networks:Industrial-scale herbicide distributors in North American grain corridors can lower total cost of ownership through container pooling and refurbishment services.
- Seed treatment micro-dosing:Neonicotinoid and biological seed coatings are creating white space for unit-dose sachets that eliminate field mixing and reduce operator exposure risk.
- ANVISA-aligned design reformulation:Brazil's glyphosate packaging standards are opening first-mover advantage for suppliers with pre-certified barrier specifications.
Industry Challenges
- Permeation engineering talent scarcity:Coextrusion die design and vapor transmission rate modeling expertise concentrates among aging specialists in European and Japanese technical centers.
- Multi-layer recycling infrastructure gaps:Post-consumer fluoropolymer-polyethylene laminates lack established reprocessing streams, complicating circularity claims under tightening residue thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Chemical Packaging Market |
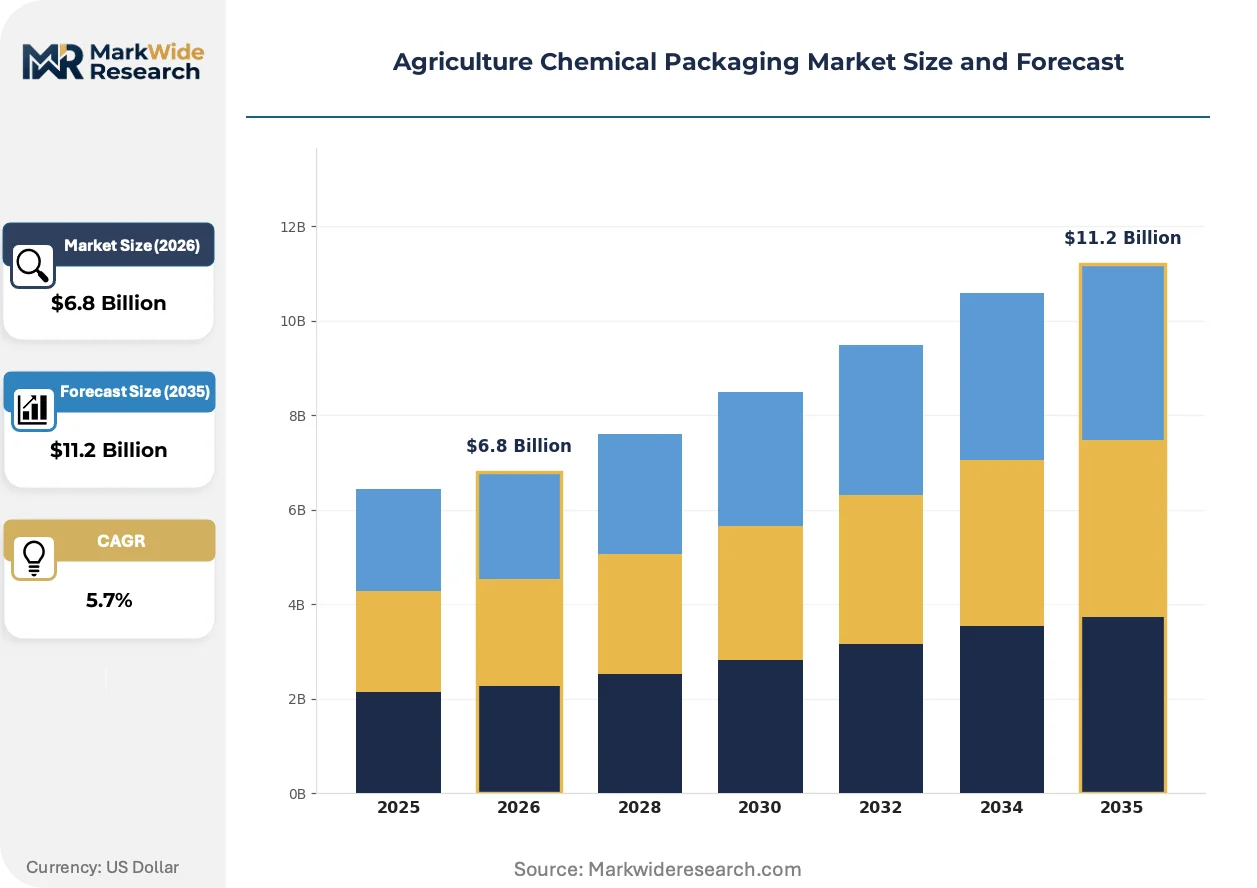
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Bottles, Jars, Drums Material: Plastic, Paper, Glass, Metal Application: Pesticides, Fertilizers, Herbicides, Insecticides End User: Farmers, Distributors, Retailers, Agrochemical Manufacturers |
| Companies Covered | Greif Inc., Amcor Plc, Mauser Packaging Solutions, Sonoco Products Company, ProAmpac, NNZ Group, LC Packaging International BV, Silgan Holdings Inc., Scholle IPN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Chemical Packaging Market Strategic Shifts
Active ingredient volatility management and residue removal mandates are forcing material science convergence with logistics optimization. Packaging formats are splitting between precision-dose disposables and durable industrial containers with integrated tracking.
Fluoropolymer-ethylene vinyl alcohol coextrusion is decentralizing barrier-layer manufacturing by enabling regional converters to achieve permeation specifications previously locked to integrated multinationals. Mid-tier agricultural chemical distributors in Argentina and Ukraine are adopting these films for captive herbicide repackaging. The technology is decentralizing supply chain control from dominant coastal converters to inland form-fill-seal operations serving treated seed processors.
EPA's Pesticide Container and Containment Rule residue thresholds are tightening closure design specifications and mandating triple-rinse compatibility in all new HDPE drum introductions. Formulators serving US row-crop markets must redesign legacy threaded caps and venting systems. The regulatory pressure is most acute in glyphosate and dicamba distribution, where container integrity failures trigger field-level liability exposure.
Buyer concentration among crop protection multinationals is compressing supplier qualification timelines and unbundling after-sales technical service from unit pricing. Procurement teams at major agrochemical firms are demanding real-time inventory visibility through embedded RFID and QR-coded batch tracking. The behavioral shift is most visible in Brazil and the US Midwest, where channel consolidation has reduced viable packaging vendor pools to pre-qualified tier-one suppliers with integrated logistics capabilities.
Agriculture Chemical Packaging Market Segmentation
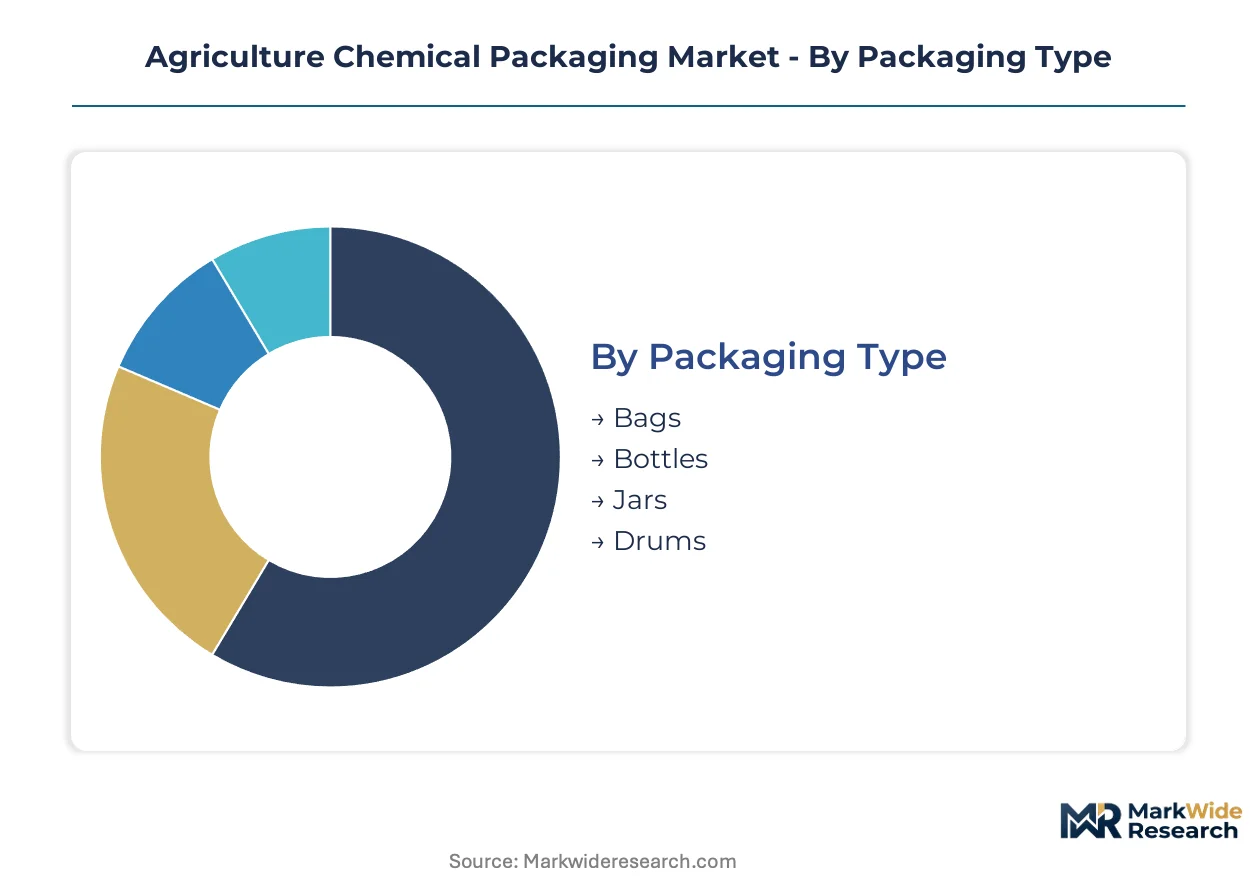
Packaging selection in agricultural chemicals hinges on barrier performance against active ingredient volatility, transport durability, and regulatory residue thresholds. Format and material choices cascade through dosing precision, shelf-life extension, and end-user handling economics.
Packaging Type:
Application volume and chemical stability requirements drive format selection across the value chain.
- Bags:Flexible woven and laminated constructions dominate soluble fertilizer and seed treatment segments where reduced packaging mass lowers logistics costs. Demand concentrates in Brazil's Cerrado soybean belt as treated seed volumes rise, with dosing precision features becoming mandatory for neonicotinoid coatings.
- Drums:Steel and HDPE cylindrical containers anchor industrial-scale herbicide distribution across North American grain corridors. Corrosive formulations and regulated substances retain metal format requirements, preventing full plastic conversion despite weight disadvantages.
- Bottles:Rigid HDPE and fluoropolymer-lined containers serve precision-dose crop protection products requiring venting systems and triple-rinse compatibility under EPA containment rules.
- Jars:Wide-mouth polyethylene containers capture biological inoculant and specialty micronutrient segments where scoop access and resealability matter for smallholder operators.
Drums lead on scale; bags lead on momentum.
Material:
Permeation resistance and regulatory compliance hierarchies stratify raw material adoption.
- Plastic:Coextruded polyethylene, polypropylene, and fluoropolymer laminates command volume leadership through cost scalability and form-factor versatility. REACH and EU F-Gas Regulation are accelerating replacement of legacy HDPE with fluoropolymer laminates for volatile organophosphate containment.
- Metal:Coated steel drums retain margin concentration for corrosive formulations and regulated substances where container integrity failures trigger field-level liability exposure.
- Paper:Multiwall sacks with moisture barriers capture bulk fertilizer segments where temporary weather protection suffices and cost minimization dominates procurement.
- Glass:Borosilicate and treated soda-lime containers persist in laboratory reference standards and high-value biological formulations requiring inert contact surfaces.
Plastic dominates volume; fluoropolymer laminates within plastic are climbing the fastest.
Application:
Active ingredient volatility and environmental release risk determine barrier specification intensity.
- Pesticides:Organophosphates, pyrethroids, and neonicotinoids demand the most stringent barrier specifications, creating technology leadership rewards for suppliers with fluoropolymer or ethylene vinyl alcohol expertise. EPA residue thresholds are tightening closure design specifications across US row-crop markets.
- Herbicides:Glyphosate and dicamba distribution drives container integrity investments where channel consolidation has reduced viable vendor pools to pre-qualified tier-one suppliers with integrated logistics capabilities.
- Fertilizers:Nitrogen, phosphorus, and potassium formulations prioritize moisture ingress prevention over vapor loss containment, favoring standard polyethylene formats and multiwall paper constructions.
- Insecticides:Contact and systemic formulations split between precision-dose disposables for smallholder markets and bulk containers for aerial application contractors.
Pesticides lead on specification intensity; herbicides lead on procurement consolidation pressure.
End User:
Scale and technical sophistication fragment packaging requirements across the distribution chain.
- Agrochemical Manufacturers:Multinational formulators drive qualification timelines and demand real-time inventory visibility through embedded RFID and QR-coded batch tracking, compressing supplier margins in exchange for volume commitments.
- Distributors:Industrial-scale operators in North American grain corridors lower total cost of ownership through container pooling and captive reconditioning networks.
- Farmers:Precision farming operators are forcing packaging suppliers to engineer dosing-precision formats that bridge bulk logistics with field-level application accuracy.
- Retailers:Agricultural supply cooperatives and independent dealers intermediate between manufacturer bulk formats and smallholder unit-dose requirements.
Agrochemical manufacturers lead on specification setting; farmers lead on format fragmentation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado soybean belt commands treated seed packaging volumes that rival North American grain corridor demand, while Germany's REACH enforcement drives material specification shifts across European supply chains.
United States
EPA's Pesticide Container and Containment Rule tightens closure specifications for glyphosate and dicamba distribution. The Iowa-Illinois grain corridor anchors industrial-scale herbicide drum demand. Precision farming operators in the Midwest force dosing-precision format fragmentation between bulk logistics and field-level accuracy.
Brazil
ANVISA-aligned packaging standards for neonicotinoid distribution force HDPE design reformulation. The Cerrado region concentrates soluble fertilizer bag demand as treated seed volumes rise. São Paulo-based converters capture first-mover advantage through pre-certified barrier specifications.
Germany
ECHA material specifications and EU F-Gas Regulation accelerate fluoropolymer laminate adoption for volatile organophosphate containment. The Rhine-Ruhr industrial cluster hosts specialty resin producers that supply barrier-layer converters. REACH compliance mandates reshape material selection across European agrochemical channels.
China
GB standards for agricultural chemical containment drive coextruded film specification upgrades. The Yangtze River Delta concentrates form-fill-seal operations serving domestic herbicide repackaging. Regional converters adopt ethylene vinyl alcohol technology for thinner-wall constructions.
India
BIS packaging standards for pesticide containers tighten residue threshold requirements. Maharashtra's agrochemical manufacturing belt drives HDPE drum and bottle demand for export-oriented formulators. Domestic seed treatment growth creates unit-dose sachet opportunities for neonicotinoid coatings.
Agriculture Chemical Packaging Market Competitive Environment
Top-tier vendors anchor industrial-scale distribution networks, while mid-tier specialists occupy regional reconditioning and precision-dose niches. The market structure stratifies between integrated multinationals with captive logistics capabilities and regional converters leveraging coextrusion technology licensing. Three archetypes dominate: steel drum and IBC incumbents, high-performance film specialists, and captive reconditioning network operators. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for fluoropolymer resin supply security.
Within the integrated multinational tier, Greif Inc. and Amcor Plc exemplify scale-driven positioning across North American and European agrochemical channels. Mauser Packaging Solutions occupies a distinct archetype through captive reconditioning infrastructure that lowers total cost of ownership for crop protection distributors. These three entities represent the dominant competitive anchors against which regional specialists and technology licensors define alternative positioning.
| Leading Market Players |
|---|
| Greif Inc. |
| Amcor Plc |
| Mauser Packaging Solutions |
| Sonoco Products Company |
| ProAmpac |
| NNZ Group |
| LC Packaging International BV |
| Silgan Holdings Inc. |
| Scholle IPN |
| Others |
Value Chain & Pricing Dynamics
Fluoropolymer resin price indices cascade through the agriculture chemical packaging supply chain into three distinct pricing tiers: premium fluoropolymer laminates for volatile organophosphate containment, mid-grade coextruded polyethylene for standard herbicide applications, and economy-grade multiwall paper for bulk fertilizer segments. This tiered pricing structure separates REACH-compliant barrier specifications from legacy HDPE formats and unlined paper constructions.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for coextruded polyethylene films, compressing margins for regional converters in Southeast Asia. Pricing stratifies across premium, standard, and economy tiers based on permeation resistance certification and volume scale. Pricing pressure stems from fluoropolymer resin allocation constraints among German and Japanese specialty chemical producers. Smallholder-focused distributors exhibit highest price sensitivity, while crop protection multinationals prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-agrochemical-manufacturer channels handle hyperscale demand from multinational formulators requiring integrated logistics capabilities. Raw material supply concentrates in Germany, Japan, and China for fluoropolymer resins, ethylene vinyl alcohol films, and coextruded polyethylene respectively. The supply chain draws from specialty chemical producers for barrier-layer inputs and regional converters for form-fill-seal operations. Single-source vulnerability in fluoropolymer resin supply exposes converters to allocation constraints. Distribution runs through captive reconditioning networks for industrial-scale herbicide drums and direct shipment for precision-dose disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agriculture chemical packaging has entered a late-cycle quality phase where fluoropolymer laminate specifications command persistent premiums as REACH and EPA residue thresholds tighten. Demand is shifting toward barrier-engineered formats that eliminate field-level liability exposure.
For Market Incumbents: Cement fluoropolymer resin supply security through long-term offtake agreements with German and Japanese specialty chemical producers. Expand captive reconditioning network density across North American grain corridors to lock in crop protection distributor relationships. Vertical integration into ethylene vinyl alcohol film production defends margin position against mid-tier converters adopting licensed coextrusion technology.
For New Entrants and Emerging Players: Capture white space in seed treatment micro-dosing formats for neonicotinoid and biological coatings where unit-dose sachet demand outpaces incumbent capacity. Target Brazil's Cerrado region with ANVISA-pre-certified barrier specifications to bypass qualification timelines that exclude late entrants from multinational vendor pools. Lead with dosing-precision engineering capabilities rather than commodity volume scale.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional converters holding licensed fluoropolymer-ethylene vinyl alcohol coextrusion technology and established relationships with treated seed processors. The five-to-ten year viability window favors specialists with backward integration into barrier-layer resin sourcing. Watch for inflection in EU extended producer responsibility enforcement that would revalue reconditioning network assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Resin Supply Agreement | Locks in barrier-layer raw material allocation from German and Japanese specialty chemical producers. |
| Captive Reconditioning Network Expansion | Lowers total cost of ownership for crop protection distributors across Iowa-Illinois grain corridors. |
| ANVISA-Aligned Design Certification | Captures first-mover advantage in Brazil's glyphosate packaging standard reformulation cycle. |
| Ethylene Vinyl Alcohol Film Licensing | Enables regional converters to achieve permeation specifications without integrated multinational scale. |
| Seed Treatment Micro-Dose Format Development | Addresses precision farming operator demand for field-level application accuracy in neonicotinoid coatings. |
Study Parameters
Direct dialogue with agrochemical packaging plant managers, procurement leads at crop protection multinationals, distribution channel partners in North American grain corridors, and technical R&D directors at coextrusion film specialists grounded the qualitative foundation. Secondary validation drew from EPA Pesticide Container and Containment Rule filings, ECHA REACH substance registrations, ANVISA packaging standard notifications, and SEC 10-K disclosures from listed packaging vendors. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates across the analysis window.
Segment-level projections incorporated packaging format splits, material grade tiers, application-specific barrier requirements, and regional regulatory clusters. CAGRs derived from trend extrapolation of treated seed volume growth, fluoropolymer laminate adoption curves, and extended producer responsibility implementation timelines. Key forecast inputs included coextrusion technology diffusion rates among regional converters and qualification timeline compression at crop protection multinationals.
Fluoropolymer resin supply disruptions, accelerated EU packaging waste directive enforcement, and breakthroughs in recyclable mono-material barrier films are the dominant revision risks to base-case projections. Forecasts reflect assumptions about regulatory implementation pacing and technology substitution elasticities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Baffle Bags Market
Packaging
Bag Closure Clips Market
Packaging
Bottle Shippers Market
Packaging
Flexible End-Load Cartoner Market
Packaging
Food Contact Paper and Board Market
Packaging
Middle East and Africa Metal Cans Market
Packaging
United States Plastic Packaging Films Market
Packaging
Flexible Film Market
Packaging
Metal Banding Machine Market
Packaging
Electrostatic Discharge (ESD) Flooring Market
Packaging
Sandwich Containers Market
Packaging
Middle East and Africa Eco-Friendly Packaging Market
Packaging
Insulated Delivery Bag Market
Packaging
Flexible Containers Market
Packaging
Beauty and Personal Care Packaging Market
Packaging
Polyolefin (POF) Shrink Film Market