
 Biodegradable Plastic Bags and Sacks Market | 2026-2036
Biodegradable Plastic Bags and Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Plastic Bags and Sacks Market Analysis
The biodegradable plastic bags and sacks market is consolidating around a widening gap between premium certified compostable grades and commodity starch blends that fail industrial composting thresholds. Mondi Group leverages its European pulp and paper infrastructure to anchor integrated biopolymer film production. Symphony Environmental Ltd. competes through oxo-biodegradable additive technology, while BioBag specializes in home-compostable sack formulations for Nordic retail channels.
Biodegradable plastic bags and sacks are flexible packaging products manufactured from biopolymers such as polylactic acid or thermoplastic starch, designed to decompose through microbial action under composting conditions within 90 to 180 days depending on certification standard. Their primary commercial purpose is to replace conventional polyethylene bags in waste collection, retail carryout, and protective shipping applications where end-of-life organic processing is available. Grocery bags lead material throughput among product types, though mailers represent the fastest-expanding segment as e-commerce fulfillment networks adopt padded biodegradable envelopes. Starch-based materials dominate unit economics for high-volume trash bag production, while PLA commands premium positioning in food service applications requiring clarity and heat resistance.
The EU Green Deal and REACH frameworks mandate compostability certification for products marketed as biodegradable across member states, effectively barring uncertified starch blends from premium retail shelf placement. FDA food contact regulations and EPA sustainable materials management guidelines shape parallel demand patterns in the United States, where industrial composting infrastructure gaps create regional availability constraints. Stakeholders must monitor composting facility buildout rates and certification harmonization between home and industrial standards before committing capacity to specific biopolymer platforms.
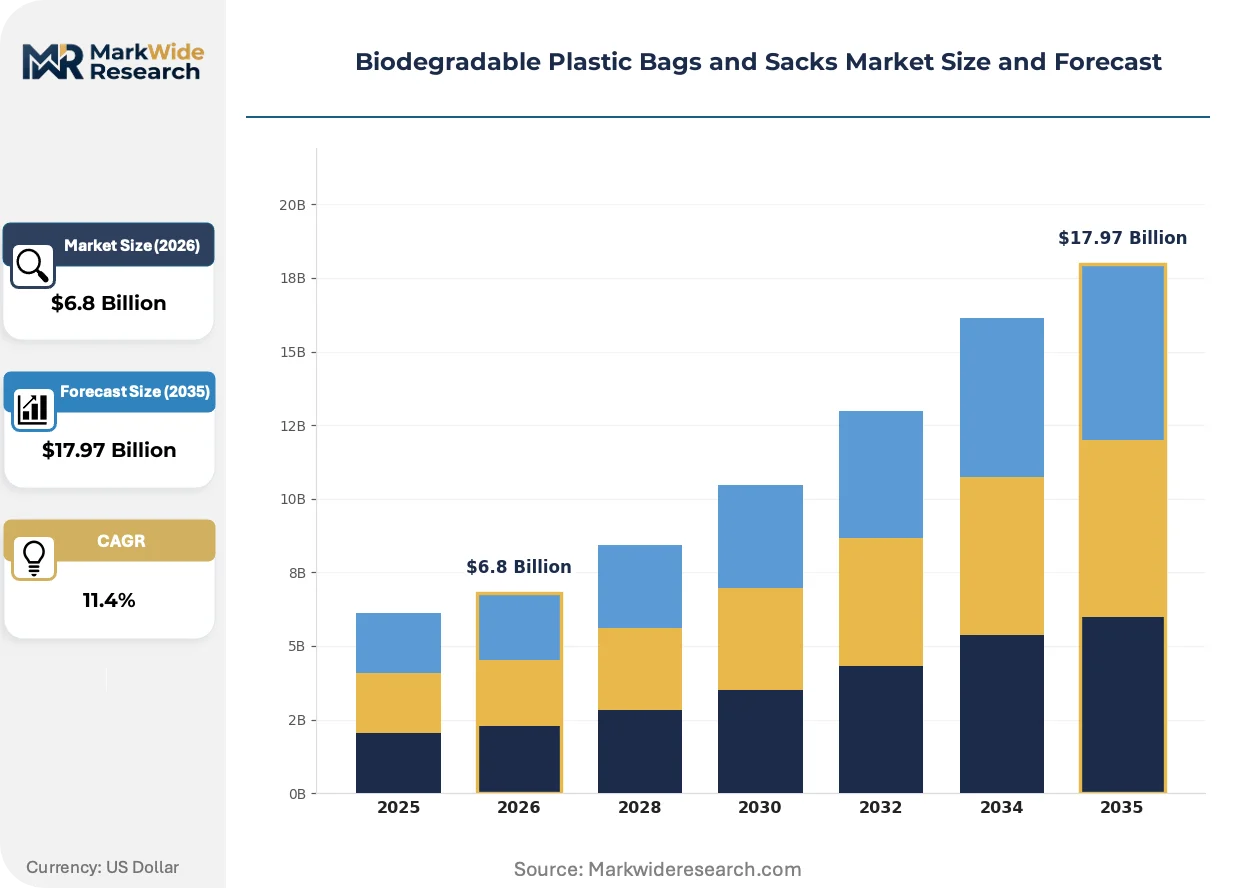
Market Dynamics
The biodegradable plastic bags and sacks market is bifurcating sharply between certified compostable grades commanding shelf space in regulated retail channels and uncertified starch blends relegated to price-sensitive bulk procurement. This structural rift is compressing margins for commodity producers while rewarding integrated biopolymer manufacturers with captive certification pathways.
Growth Catalysts
- EU Green Deal enforcement:The EU Green Deal's tightening single-use plastic restrictions are accelerating procurement shifts across German and Italian grocery distribution networks toward certified compostable carry bags.
- Starch-based material economics:Thermoplastic starch formulations now capture volume demand in high-throughput waste collection applications where unit cost sensitivity dominates specification decisions.
- E-commerce fulfillment pivot:Nordic retail channels are driving padded biodegradable envelope adoption as mailers emerge as the fastest-expanding product segment within flexible biopolymer packaging.
Market Restraints
- Industrial composting infrastructure gaps:Regional availability constraints in the United States limit end-of-life processing options despite EPA sustainable materials management guidelines encouraging adoption.
- Feedstock price volatility:Corn and cassava starch input costs fluctuate with agricultural commodity cycles, compressing margin stability for volume producers dependent on starch-based formulations.
- Performance limitations in food service:PLA's heat resistance threshold restricts hot-fill applications, ceding share to conventional polyethylene in temperature-critical food contact segments.
Strategic Opportunities
- Home-compostable certification expansion:The gap between industrial and home composting standards creates white space for sack formulations achieving Vincotte OK Compost HOME certification in residential waste markets.
- FDA food contact pathway development:Clarified FDA regulations for polylactic acid in direct food contact applications could unlock premium positioning in deli and prepared food retail segments.
- Reverse logistics integration:Closed-loop collection partnerships with municipal composting operators offer channel innovation potential for bag-in-bag programs in concentrated urban waste systems.
Industry Challenges
- Certification timeline compression:REACH and EU Green Deal harmonization demands are extending third-party validation cycles for multi-standard compliance, delaying product launches.
- Biopolymer processing skill scarcity:Extrusion and film conversion expertise for thermoplastic starch and PLA remains concentrated among legacy bioplastics specialists, constraining workforce scaling.
- Legacy polyethylene integration friction:Converting existing blown film assets to biopolymer-compatible temperature and moisture profiles requires substantial capex reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Plastic Bags and Sacks Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trash Bags, Grocery Bags, Retail Bags, Mailers Material: PLA, PHA, Starch-based, Cellulose End User: Retail, Hospitality, E-commerce, Food Services Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Mondi Group, Symphony Environmental Ltd., BioBag, ProAmpac LLC, Natur-Tec, Naturepoly, Novolex Holdings, Sealed Air Corporation, Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Plastic Bags and Sacks Market Emerging Trajectories
Active innovation across the biodegradable plastic bags and sacks market centers on automation of quality assurance, regulatory precision in certification alignment, and procurement model restructuring toward specification-driven sourcing. These forces are compressing development cycles while elevating technical barriers to competitive participation.
Machine vision systems integrated into blown film extrusion lines are automating defect detection for compostable film gauge consistency and seal integrity. German packaging converters deploying these systems report reduced batch rejection rates in certified compostable grocery bag production. The technology is automating real-time process adjustments that previously required manual intervention, compressing quality assurance labor costs while tightening specification compliance for EU Green Deal procurement requirements.
REACH frameworks mandating compostability certification for products marketed as biodegradable are reshaping formulation disclosure and supply chain documentation obligations across member states. Industrial consequences include mandatory third-party testing protocols and polymer traceability requirements that extend upstream to agricultural feedstock sourcing. Food service applications requiring clarity and heat resistance are most affected, with PLA suppliers accelerating EFSA-compliant additive packages to maintain premium positioning.
Retail chain procurement committees are consolidating supplier rosters around dual-certified industrial and home-compostable product lines, displacing single-standard vendors from preferred vendor lists. This concentration is reshaping competitive access to Nordic and Western European grocery distribution networks where sustainability scorecards determine shelf placement. The shift is most visible in German supermarket private-label programs, where procurement specifications now mandate Vincotte or TÜV Austria certification as baseline qualification criteria.
Biodegradable Plastic Bags and Sacks Market Segmentation
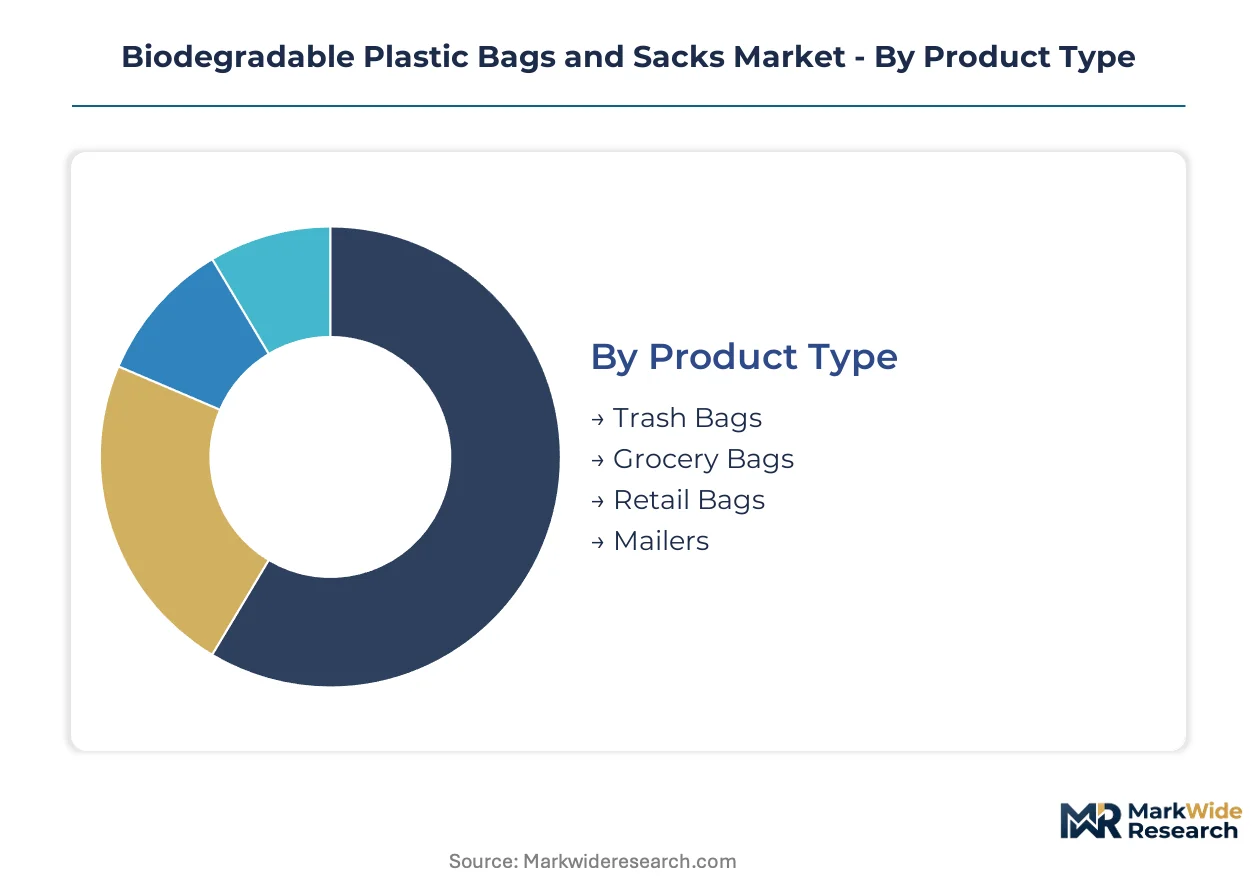
Biodegradable plastic bags and sacks fragment across four distinct dimensions, each governing different competitive dynamics. Product type determines extrusion equipment requirements and certification pathways. Material selection locks in feedstock sourcing strategies and composting standard compliance.
Product Type:
Capital intensity peaks with mailer production, where padded envelope lamination and adhesive integration demand specialized coating lines absent from simple bag extrusion.
- Grocery Bags:These carryout sacks utilize blown film extrusion of PLA or starch blends at 15-25 micron thickness, with heat-sealed handles and printed branding surfaces. German and Italian supermarket chains now mandate Vincotte OK Compost HOME certification as a baseline procurement filter, displacing uncertified suppliers from preferred vendor rosters. Grocery bags absorb the bulk of installed capacity; mailers are expanding most quickly.
- Mailers:Padded biodegradable envelopes integrate kraft paper or biopolymer bubble lamination with pressure-sensitive adhesive strips for e-commerce fulfillment. Nordic retail channels are driving specification tightening as sustainability scorecards determine shelf placement for private-label shipping supplies.
- Trash Bags:High-volume waste collection sacks prioritize unit economics through thermoplastic starch formulations at 30-50 micron thickness for puncture resistance.
- Retail Bags:Boutique carryout applications emphasize printed clarity and tactile finish for brand differentiation in specialty retail environments.
Volume concentration in grocery applications reflects regulatory enforcement patterns across EU member states.
Material:
Cost tier stratification separates premium-certified grades from commodity starch blends failing industrial composting thresholds.
- Starch-based:Thermoplastic starch derived from corn or cassava offers the lowest unit cost for high-throughput trash bag production, though agricultural commodity cycles introduce margin volatility. REACH frameworks now mandate polymer traceability upstream to feedstock sourcing, extending compliance documentation burdens.
- PLA:Polylactic acid delivers optical clarity and heat resistance to 110°C for deli and prepared food retail segments. FDA food contact pathway development remains incomplete, constraining premium positioning in US food service applications.
- PHA:Polyhydroxyalkanoates provide marine biodegradability certification for coastal waste management systems with industrial composting infrastructure gaps.
- Cellulose:Regenerated cellulose films from wood pulp offer home-compostable pathways where municipal collection systems remain underdeveloped.
Starch-based formulations dominate unit economics; PLA commands the steepest expansion trajectory in food contact applications.
End User:
Application maturity varies sharply, with retail procurement committees consolidating supplier rosters around dual-certified product lines.
- Retail:Supermarket private-label programs in Germany now specify Vincotte or TÜV Austria certification as mandatory qualification criteria, compressing vendor pools.
- E-commerce:Fulfillment networks adopt padded biodegradable envelopes as sustainability scorecards penetrate logistics procurement decisions.
- Food Services:Deli and prepared food segments require PLA's heat resistance and optical clarity, though temperature-critical hot-fill applications remain constrained.
- Hospitality:Hotel and restaurant waste collection prioritizes odor containment and leak resistance in high-moisture organic waste streams.
Retail channels concentrate procurement volume; e-commerce fulfillment is gaining share fastest.
Distribution Channel:
Customer type fragmentation shapes margin structures, with specification-driven sourcing displacing price-only procurement.
- Supermarkets:German grocery distribution networks anchor volume demand through centralized procurement committees mandating compostability certification.
- Online:Direct-to-consumer channels enable specialty biopolymer formulations for home-composting consumers outside municipal collection zones.
- Convenience Stores:Smaller format retail prioritizes pre-printed branded sacks with lower minimum order quantities and rapid replenishment cycles.
- Specialty Shops:Boutique retailers emphasize tactile finish and custom printing for premium positioning in gift and specialty food segments.
Supermarket channels absorb dominant procurement volume; online distribution is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European procurement gravity for certified compostable films, with German supermarket chains mandating Vincotte certification as baseline qualification criteria.
Germany
Frankfurt and Hamburg concentrate blown film extrusion capacity serving Rewe and Edeka procurement committees. The EU Green Deal's single-use plastic restrictions enforce REACH-compliant compostability certification for shelf placement. Bavarian converters report extended third-party validation cycles as multi-standard harmonization demands intensify.
Italy
Milan and Bologna host starch formulation specialists supplying Coop Italia and Conad distribution networks. EFSA compliance requirements for food contact applications shape PLA additive package development. Emilia-Romagna's packaging cluster experiences margin compression from agricultural commodity price volatility in corn feedstock sourcing.
United States
Chicago and Minneapolis-St. Paul anchor Midwest industrial composting infrastructure buildout for municipal bag-in-bag programs. FDA food contact pathway gaps for polylactic acid constrain deli segment penetration despite EPA sustainable materials management guidelines. California's SB 54 regulations drive specification tightening ahead of federal harmonization.
France
Paris and Lyon retail procurement committees consolidate supplier rosters around dual-certified industrial and home-compostable product lines. ANSM disclosure requirements extend polymer traceability obligations upstream to agricultural sourcing. Carrefour's private-label sustainability scorecards displace single-standard vendors from preferred lists.
Netherlands
Amsterdam and Rotterdam distribution hubs pivot e-commerce fulfillment networks toward padded biodegradable envelope adoption. CSRD reporting requirements penetrate logistics procurement decisions for sustainability disclosure. Randstad converters specialize in mailer lamination lines absent from simple bag extrusion operations.
Biodegradable Plastic Bags and Sacks Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-tier stratification, with Vincotte or TÜV Austria dual-certified suppliers commanding preferred vendor status while uncertified starch blend producers face shelf displacement. The vendor base concentrates around integrated biopolymer manufacturers with captive pulp and paper infrastructure, specialty additive technology licensors, and home-compostable formulation specialists. Three archetypes dominate: integrated materials-to-film producers, additive technology licensors, and certified compostable specialists. Competitive moves center on certification pathway acceleration and municipal composting operator partnership structures.
Within the integrated materials tier, Mondi Group anchors European supply through captive pulp infrastructure leverage. Symphony Environmental Ltd. exemplifies additive technology licensing archetypes with oxo-biodegradable positioning. BioBag occupies the home-compostable specialist position for Nordic retail channel penetration.
| Leading Market Players |
|---|
| Mondi Group |
| Symphony Environmental Ltd. |
| BioBag |
| ProAmpac LLC |
| Natur-Tec |
| Naturepoly |
| Novolex Holdings |
| Sealed Air Corporation |
| Berry Global Group |
| Others |
Supply Flow & Price Mechanics
German supermarket procurement committees concentrate volume demand for certified compostable carry bags, compressing supplier margins through specification-driven sourcing that rewards Vincotte or TÜV Austria dual certification with preferred vendor status. This buyer concentration forces pricing stratification across certification tiers rather than commodity grades.
Pricing Analysis
Certification-attained compostability serves as the value-based pricing anchor, with Vincotte OK Compost HOME commanding 15-25% premiums over industrial-only certified grades. Three-tier pricing structure across premium dual-certified, standard single-certified, and uncertified starch blend levels reflects REACH compliance burden allocation. Cost compression in commodity starch formulations is intensifying because agricultural feedstock volatility erodes margin buffers for volume producers lacking captive sourcing. Municipal waste collection departments exhibit highest price sensitivity, while Nordic retail chains demonstrate lowest sensitivity due to sustainability scorecard procurement mandates.
Supply Chain Analysis
REACH and EU Green Deal certification gating restricts qualified supplier pools to converters with validated polymer traceability upstream to agricultural feedstock sourcing. Manufacturing concentrates in Germany, Italy, and the Netherlands, where blown film extrusion infrastructure aligns with retail distribution gravity. Corn and cassava starch inputs draw from agricultural commodity markets, while PLA resin supplies hinge on lactic acid fermentation capacity. Single-source vulnerability in thermoplastic starch formulation expertise constrains workforce scaling. Distribution runs through centralized supermarket procurement committees and e-commerce fulfillment hubs rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodegradable plastic bags and sacks market is becoming a vertical-integration race, with players pursuing captive pulp and biopolymer film production to secure certification pathway control and margin capture.
For Market Incumbents: To counter margin compression from agricultural commodity price volatility, Mondi Group and integrated producers should deepen backward integration into wood pulp and starch feedstock sourcing. Securing EFSA-compliant additive packages for PLA food contact applications provides defensive moats against specialty biopolymer entrants. Capacity concentration in Bavarian and Emilia-Romagna clusters reinforces logistics cost advantages for EU Green Deal procurement fulfillment. For New Entrants and Emerging Players: Capture home-compostable certification white space in US municipal markets where industrial composting infrastructure gaps persist. Target padded biodegradable envelope production for Nordic e-commerce fulfillment networks, where mailer lamination expertise remains scarce relative to simple bag extrusion. Position through direct-to-consumer online channels to bypass supermarket procurement committee consolidation. For Investors and Strategic Acquirers: The window for entry favors additive technology licensors with oxo-biodegradable or enzymatic degradation platforms that bridge industrial and home composting standards. Long-term viability rests on certification harmonization completion across EU member states. Watch for FDA food contact pathway clarification for PLA as inflection signal for US deli segment premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pathway Acceleration | Vincotte or TÜV Austria dual certification unlocks preferred vendor status with Rewe and Edeka procurement committees. |
| Backward Integration into Feedstock | Captive corn or cassava starch sourcing insulates margin stability from agricultural commodity cycle volatility. |
| Home-Compostable Formulation Development | OK Compost HOME certification captures US municipal markets lacking industrial composting infrastructure. |
| Mailer Lamination Capacity Buildout | Padded biodegradable envelope production serves Nordic e-commerce fulfillment network sustainability mandates. |
| Municipal Composting Partnership | Closed-loop collection agreements with urban waste operators secure channel access for bag-in-bag programs. |
Methodological Framework
Document review covered customs and trade data, SEC filings from packaging converters, EU Green Deal regulatory texts, and Vincotte certification databases, complemented by interviews with blown film extrusion plant managers, supermarket procurement committee members, municipal waste collection directors, and biopolymer R&D specialists. Secondary validation drew from ECHA REACH guidance documents, EFSA food contact assessments, and industrial composting facility buildout records. Bottom-up capacity estimates from German and Italian converter networks were triangulated against top-down demand projections from retail distribution channel analysis.
Segment-level value outputs across product type, material formulation, end-use application, and distribution channel dimensions were generated through structured modeling. CAGRs were derived from installation base growth rates for blown film extrusion lines, certification adoption curves, and procurement specification tightening trajectories. Feedstock price elasticity parameters and composting facility capacity buildout schedules served as industry-specific forecast inputs.
The model holds under continued EU Green Deal enforcement and REACH framework stability; deviation in certification harmonization timelines or FDA food contact pathway completion would shift volume projections. Forecasts reflect assumptions regarding industrial composting infrastructure deployment rates and agricultural commodity price band persistence. A model refresh is warranted upon material change in EU member state transposition of single-use plastic restrictions or breakthrough in enzymatic degradation technology performance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Bioplastic Packaging Market