
 Biodegradable Paper and Plastic Packaging Market | 2026-2036
Biodegradable Paper and Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Paper and Plastic Packaging Market Analysis
Specialized polymer chemists and composting infrastructure engineers is reorganizing how quickly biodegradable packaging scales from pilot to commercial volumes. Huhtamäki leverages its global molded fiber network to supply quick-service restaurants with certified compostable food containers. Stora Enso anchors Nordic supply through its integrated pulp-to-package operations across Finland and Sweden. TIPA specializes in compostable films that match conventional plastic barrier properties for fresh produce and snack applications.
Biodegradable paper and plastic packaging comprises materials engineered to decompose through microbial action under industrial composting or marine conditions, typically meeting ASTM D6400 or EN 13432 standards for complete disintegration within 180 days. These solutions serve primarily to replace petroleum-based packaging in sectors facing regulatory pressure or corporate sustainability commitments. Paper bags and molded fiber dominate current volume due to mature recycling streams and lower unit costs, while bioplastics and compostable films capture expanding margin pools as performance gaps narrow against conventional films. Food service and e-commerce end users are pulling disproportionate growth because their single-use intensity intersects directly with visible plastic reduction pledges.
The EPA oversees compostability claims in the United States, while the EU Green Deal and F-Gas Regulation frame material phase-out timelines across Europe, and China's MEE enforces plastic restriction orders that redirect investment toward certified biodegradable alternatives. These frameworks create demand certainty but fragment certification requirements, forcing producers to maintain multiple testing protocols. Stakeholders must monitor whether industrial composting capacity buildout keeps pace with material supply expansion, as infrastructure gaps risk undermining consumer confidence and regulatory compliance.
Market Dynamics
Single-use plastic bans in food service and retail are compressing substitution timelines, forcing converters to certify biodegradable alternatives under ASTM D6400 and EN 13432 ahead of infrastructure readiness. This regulatory pull is creating capacity bottlenecks in industrial composting and reshaping polymer formulation priorities.
Growth Catalysts
- EU Green Deal packaging mandates:Germany's Packaging Act enforces extended producer responsibility fees that penalize fossil-based materials, redirecting brand procurement toward certified compostable films and molded fiber.
- Quick-service restaurant pledges:North American food service chains are binding franchise operators to eliminate polystyrene and conventional polyethylene by specified deadlines, pulling volume into PLA-lined paperboard and bagasse containers.
- PHA fermentation advances:Microbial production of polyhydroxyalkanoates is achieving heat resistance above 120°C, closing performance gaps with polypropylene in hot-fill applications.
Market Restraints
- Feedstock cost volatility:Corn and sugarcane prices swing with agricultural commodity cycles, squeezing PLA and bagasse converter margins when petroleum-based resin costs drop.
- Composting infrastructure concentration:Industrial composting facilities cluster in Germany, Netherlands, and California, leaving vast North American and Asian markets without certified disposal pathways.
- Technical shelf-life limitations:Moisture-sensitive biopolymers degrade in humid supply chains, restricting distribution radius for fresh produce packaging.
Strategic Opportunities
- India's plastic waste rules:The country's central environmental regulator enforces thickness bans and extended producer responsibility that redirect investment toward certified biodegradable alternatives in food delivery.
- Marine-degradable formulations:Algae-based polymers meeting ASTM D6691 standards for ocean breakdown are opening seafood and aquaculture export packaging segments.
- Home-compostable certification:TÜV Austria's OK Compost HOME label is creating premium positioning for e-commerce mailers in jurisdictions lacking industrial composting access.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in microbial polyester synthesis concentrates in academic and startup clusters, constraining scaled production engineering.
- Multi-standard certification timelines:Producers must sequence ASTM D6400, EN 13432, and BPI approvals for cross-border sales, extending product launch cycles.
- Legacy equipment retrofit costs:Conventional extrusion and thermoforming lines require screw, die, and cooling modifications to process hygroscopic biopolymers without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Paper and Plastic Packaging Market |
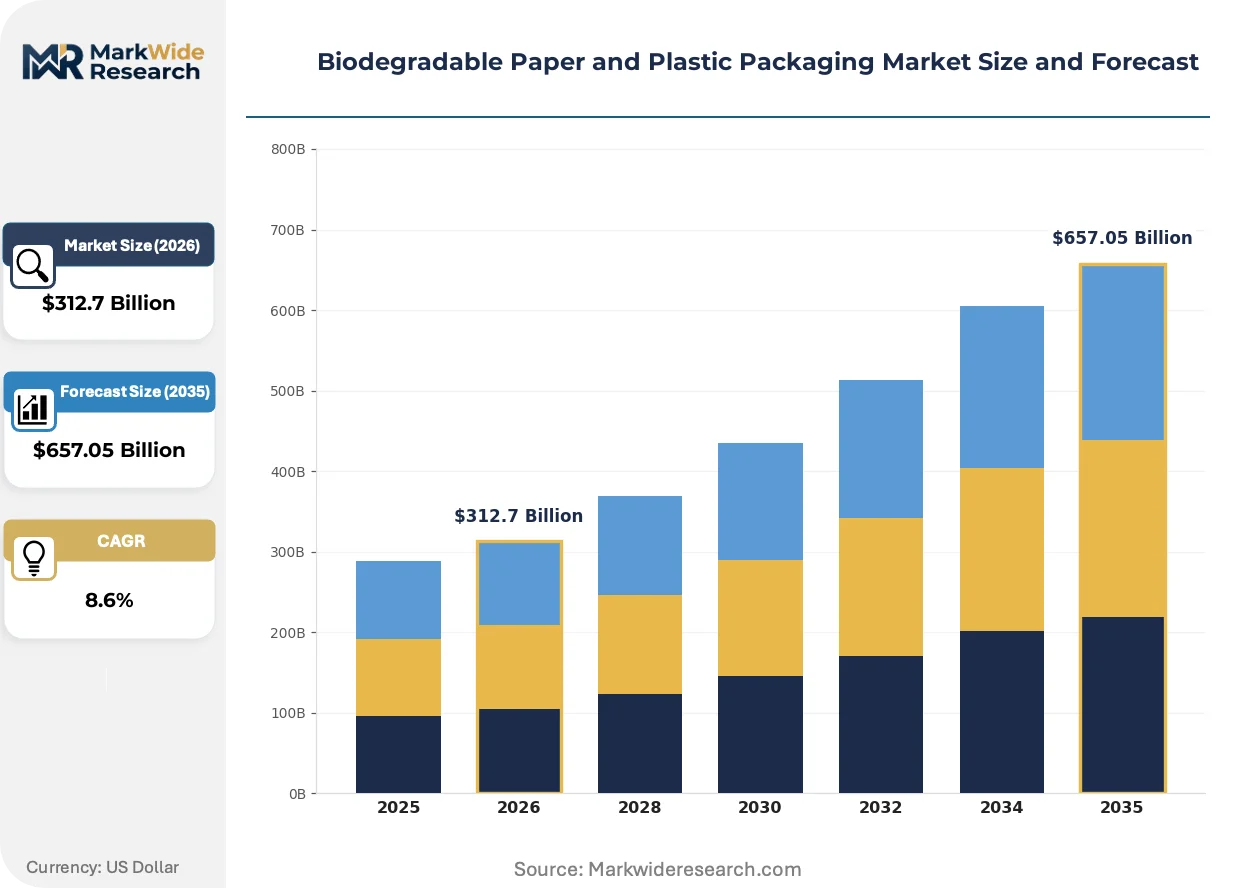
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Bags, Bioplastics, Compostable Films, Molded Fiber End User: Food Service, E-commerce, Retail, Consumer Goods Material: PLA, PHA, Recycled Paper, Starch-based Materials Application: Packaging, Wrapping, Labeling, Carry Bags |
| Companies Covered | Xiamen Bioleader, Pactiv Evergreen, Huhtamäki, Stora Enso, Detpak, BioPak, Eco-Products, TIPA, Vegware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Paper and Plastic Packaging Market Emerging Trajectories
Material scientists and packaging engineers are converging on barrier-performance parity with conventional plastics while compressing certification and scale-up timelines. Three developments are restructuring competitive positioning.
Multilayer compostable films incorporating bio-based ethylene vinyl alcohol are fragmenting the snack and fresh produce packaging landscape. European retail chains are specifying these structures for private-label products with six-month shelf-life requirements. The technology is fragmenting incumbent petroleum-film supplier relationships as converters establish direct polymer sourcing partnerships.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical coatings from paper food packaging. European converters are pivoting to bio-wax and clay-based barrier formulations. Quick-service chains operating across Germany, France, and Netherlands are accelerating qualification of these alternatives to maintain compliance deadlines.
Centralized corporate sustainability procurement is displacing decentralized category buying in multinational food and beverage manufacturers. Category managers now coordinate polymer selection across regional operating units, consolidating supplier relationships and prioritizing vendors with multi-continent certification coverage. This concentration is most visible in North American and European headquarters of global CPG conglomerates.
Biodegradable Paper and Plastic Packaging Market Segmentation
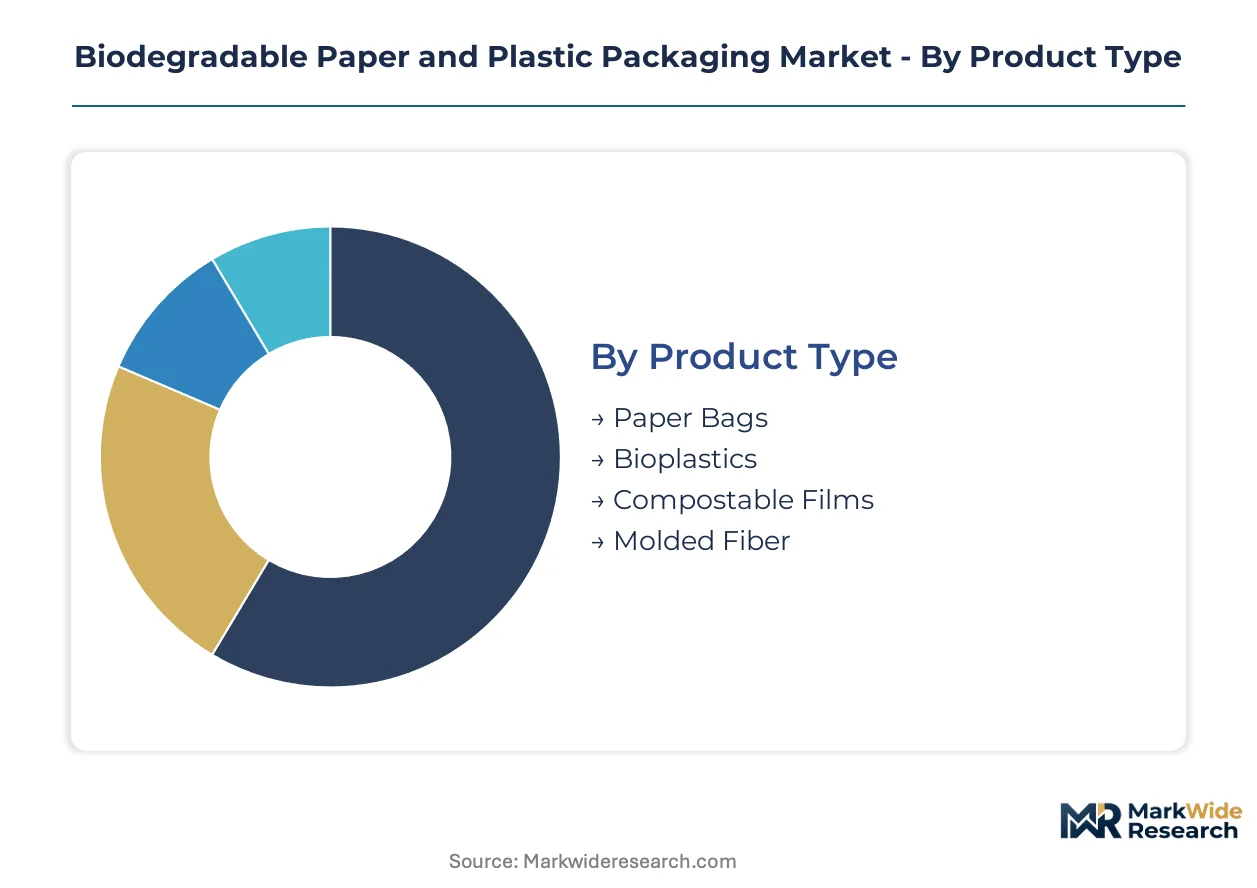
Material composition and disposal pathway requirements fragment procurement decisions across biodegradable packaging categories. End-use certification demands and regional composting infrastructure availability determine which segments capture volume versus margin.
Product Type:
Paper bags and molded fiber dominate domestic procurement in Germany and the Netherlands where industrial composting capacity is mature, while bioplastics and compostable films concentrate in export-oriented supply chains serving North American quick-service restaurant networks.
- Paper Bags:Kraft and sulfite pulp constructions with water-based adhesives meet EN 13432 disintegration standards. German retail chains and French supermarket groups are specifying these for bakery and dry grocery applications under EU Green Deal extended producer responsibility frameworks.
- Bioplastics:Thermoplastic formulations derived from corn starch or sugarcane include PLA and PHA grades engineered for film extrusion and injection molding. North American food service chains are pulling these into cold beverage cups and cutlery as polystyrene bans tighten across California and New York.
- Compostable Films:Multilayer structures incorporating bio-based barrier polymers.
- Molded Fiber:Pressed pulp trays and clamshells for hot food containment.
Paper bags hold the largest share; momentum sits with bioplastics as heat-resistant PHA formulations close performance gaps with polypropylene.
End User:
Cost tier stratification separates premium-certified segments from economy-grade alternatives, with food service and e-commerce commanding formulation investments that retail and consumer goods segments cannot justify at equivalent scale.
- Food Service:Quick-service restaurants and institutional cafeterias require ASTM D6400 or BPI certification for all single-use items. Chains operating across California, Germany, and the United Kingdom are binding franchisees to eliminate conventional polyethylene-lined paperboard by contract deadlines, pulling volume into PLA-lined alternatives.
- E-commerce:Mailers and protective packaging face pressure from corporate plastic reduction pledges visible to consumers. Home-compostable certification under TÜV Austria OK Compost HOME is creating premium positioning for vendors serving jurisdictions lacking industrial composting access.
- Retail:Private-label grocery and apparel applications.
- Consumer Goods:Electronics and personal care secondary packaging.
Food service commands the deepest formulation investments; e-commerce is climbing the fastest as home-compostable certification unlocks premium positioning.
Material:
Supply concentration for fermentation feedstocks shapes regional production economics, with corn-based PLA dominating North American supply and sugarcane-based alternatives anchoring European and Brazilian output.
- PLA:Polylactic acid polymerized from corn or sugarcane-derived lactide offers clarity and processability comparable to polystyrene. German packaging converters are prioritizing this material for thermoformed trays and cold-fill bottles under Packaging Act extended producer responsibility fee structures that penalize fossil-based alternatives.
- PHA:Microbial polyesters produced through fermentation achieve heat resistance above 120°C in next-generation formulations. California-based food service suppliers are qualifying these for hot-fill soup containers and microwaveable trays where PLA performance fails.
- Recycled Paper:Post-consumer pulp integrated into molded fiber and corrugated applications.
- Starch-based Materials:Thermoplastic starch blends for loose-fill and agricultural films.
PLA holds the largest share; PHA is gaining share fastest as heat resistance specifications harden across hot-fill applications.
Application:
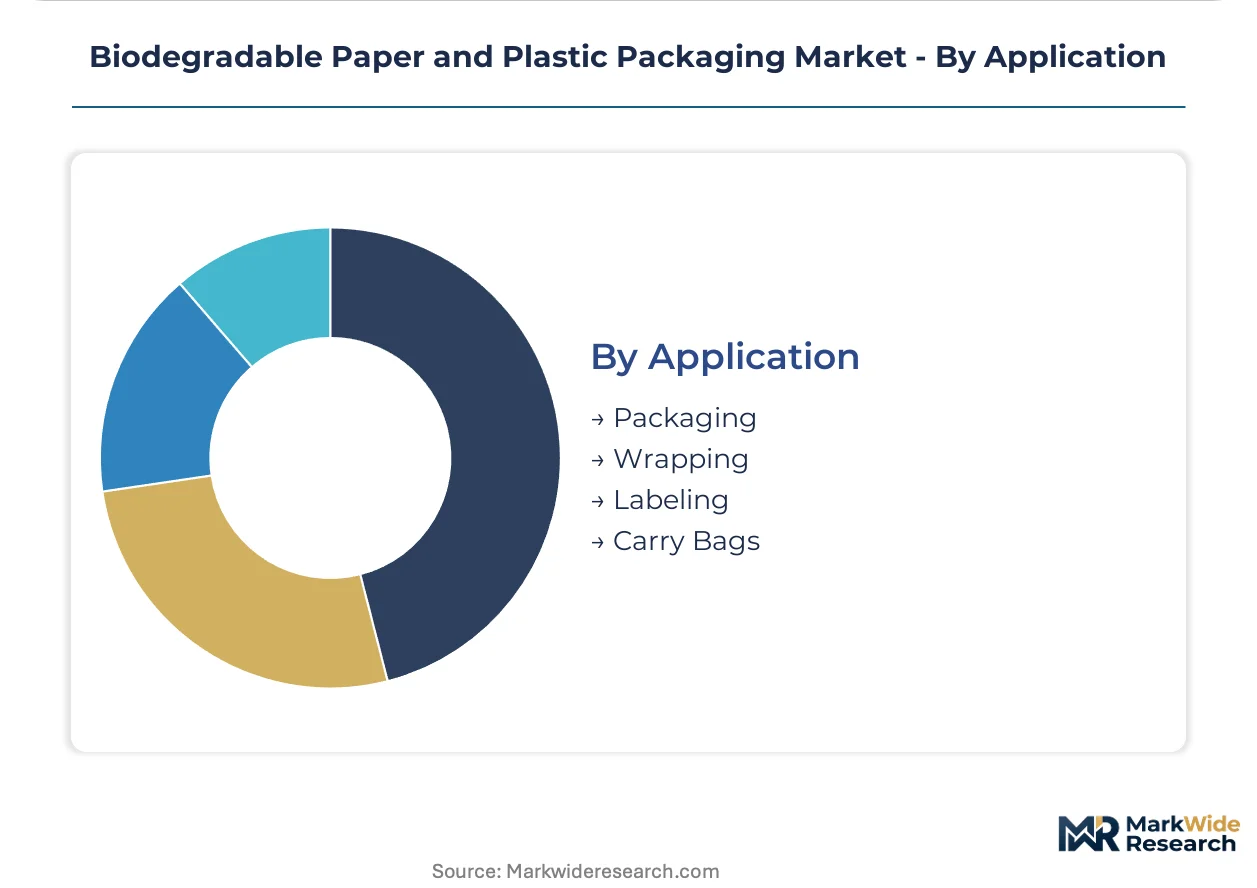
Volume concentration in primary packaging functions contrasts with margin capture in specialized wrapping and labeling formats where barrier performance requirements justify premium material selection.
- Packaging:Primary containment structures including bottles, trays, and pouches. German dairy and fresh produce distributors are specifying multilayer compostable films incorporating bio-based ethylene vinyl alcohol for six-month shelf-life requirements under EU Green Deal compliance timelines.
- Wrapping:Stretch films and protective overwrap for palletized goods. Netherlands-based logistics operators are piloting PHA-based alternatives for export shipments to jurisdictions with strict plastic waste regulations.
- Labeling:Pressure-sensitive and in-mold labels requiring adhesive compatibility with compostable substrates.
- Carry Bags:Retail checkout bags subject to thickness bans and material restrictions.
Packaging holds the largest share; wrapping follows the steepest expansion trajectory as export compliance requirements multiply across destination markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command premium pricing for certified compostable packaging while Indian suppliers compete on volume for food delivery applications. This asymmetry reflects divergent regulatory enforcement timelines and composting infrastructure maturity. Brand owners now route procurement decisions through regional compliance filters rather than centralized cost optimization.
Germany
Extended producer responsibility fees under the Packaging Act penalize fossil-based materials, redirecting brand procurement toward certified compostable films. The EU Green Deal targets enforce material phase-out timelines that accelerate converter qualification cycles. Industrial composting clusters in North Rhine-Westphalia and Bavaria process volume from quick-service restaurant chains bound by franchise elimination deadlines for conventional polyethylene.
United States
California and New York state-level polystyrene bans pull volume into PLA-lined paperboard and bagasse containers for cold beverage applications. The EPA oversees compostability claims through ASTM D6400 enforcement, creating certification bottlenecks for cross-border suppliers. Food service procurement concentrates in the Pacific Northwest and Northeast Corridor where municipal composting access supports premium positioning for BPI-certified alternatives.
India
Central environmental regulator enforcement of thickness bans and extended producer responsibility redirects investment toward certified biodegradable alternatives in food delivery. The country's plastic waste rules create demand certainty for compostable films serving quick-service restaurant networks. Manufacturing clusters in Maharashtra and Gujarat supply molded fiber and PLA formulations to domestic aggregators and export markets across Southeast Asia.
Netherlands
Logistics operators pilot PHA-based stretch films for export shipments to jurisdictions with strict plastic waste regulations. National composting infrastructure supports industrial-scale processing of multilayer compostable structures. Rotterdam and Amsterdam distribution hubs qualify bio-based barrier films for six-month shelf-life private-label grocery applications under EU Green Deal compliance timelines.
Brazil
Sugarcane-based PLA feedstock integration anchors regional production economics for thermoformed tray applications. ANVISA regulatory frameworks for food-contact materials shape polymer selection for export-oriented meat and produce packaging. São Paulo state converters supply bagasse and molded fiber structures to quick-service chains operating across Mercosur trade bloc markets.
Biodegradable Paper and Plastic Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized polymer chemists commanding premium positioning against scale-driven molded fiber producers. The market structures around three tiers: integrated pulp-to-package operators with captive fiber supply, dedicated bioplastic compounders with fermentation partnerships, and regional converters with certification specialization. Consolidation pressure concentrates among mid-scale European and North American players seeking multi-continent approval coverage. Dominant competitive moves include backward integration into agricultural feedstock sourcing and technology licensing agreements for heat-resistant PHA formulations.
Within the integrated fiber tier, Huhtamäki and Stora Enso exemplify archetypes with pulp network control and Nordic supply anchoring. Among specialized film producers, TIPA occupies a position representing barrier-performance parity with conventional plastics. These three companies sit within competitive positions defined by feedstock access, certification breadth, and end-use segment concentration rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Xiamen Bioleader |
| Pactiv Evergreen |
| Huhtamäki |
| Stora Enso |
| Detpak |
| BioPak |
| Eco-Products |
| TIPA |
| Vegware |
| Others |
Supply Flow & Price Mechanics
ASTM D6400 and EN 13432 certification regimes gate both supplier qualification and price differentiation simultaneously, forcing converters to absorb testing costs that separate certified premium tiers from uncertified commodity supply. Brand owners in Germany and California route procurement through these compliance filters, concentrating margin capture among multi-standard holders while squeezing single-certification players into spot-market competition.
Pricing Analysis
Configured-to-order pricing for custom multilayer films commands spreads against standard PLA-lined paperboard due to formulation complexity and barrier-performance specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification breadth, with BPI-plus-OK-Compost-HOME dual holders capturing top-tier positioning. Pricing pressure stems from agricultural feedstock volatility, particularly corn and sugarcane price swings that compress converter margins when petroleum-based resin costs drop. Quick-service restaurant chains exhibit highest price sensitivity due to franchise-scale procurement volumes, while pharmaceutical and premium food exporters show lowest sensitivity given compliance-driven material mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate bioplastic resin procurement due to moisture sensitivity and shelf-life degradation risks, though strategic stockpiling of kraft pulp and bagasse fiber secures molded fiber operations against agricultural harvest cycles. Supply concentrates in Germany, the United States, and India for finished packaging, with fermentation-based polymer production anchored in China, Thailand, and Brazil. Raw material dependencies include corn starch, sugarcane bagasse, and sulfite pulp, with supply chain risk centering on single-source vulnerability for specialized bio-based barrier polymers. Distribution runs through regional converter networks qualified under local composting infrastructure standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHA fermentation breakthroughs above 120°C heat resistance represent a technological inflection disrupting polypropylene substitution economics, while EU Green Deal packaging mandates compress adoption timelines from pilot to commercial scale.
For Market Incumbents: Fortify multi-continent certification coverage by sequencing ASTM D6400, EN 13432, and BPI approvals ahead of competitor qualification cycles. Invest in backward integration into agricultural feedstock sourcing to buffer margin compression from corn and sugarcane price volatility. Capacity expansion in Germany and California anchors supply proximity to premium demand clusters.
For New Entrants and Emerging Players: Anchor in India's food delivery packaging segment where central environmental regulator enforcement of thickness bans redirects investment toward certified biodegradable alternatives with limited incumbent saturation. Target home-compostable certification under TÜV Austria OK Compost HOME for e-commerce mailer applications in jurisdictions lacking industrial composting access. Pursue direct polymer sourcing partnerships with European retail chains specifying multilayer compostable films for private-label qualification.
For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape by consolidating procurement decisions through centralized corporate sustainability offices that prioritize vendors with multi-continent certification coverage. Long-term viability frames around industrial composting capacity buildout keeping pace with material supply expansion, with acquisition target archetypes being specialized polymer compounders with heat-resistant PHA formulation partnerships. Watch industrial composting facility permitting velocity across North American and Asian markets as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock | Corn and sugarcane sourcing partnerships buffer PLA converters against commodity price volatility squeezing margins. |
| Multi-Standard Certification Sequencing | ASTM D6400, EN 13432, and BPI approvals unlock cross-border sales for German and North American brand procurement. |
| Heat-Resistant PHA Formulation Partnerships | Microbial polyester synthesis above 120°C closes performance gaps with polypropylene in hot-fill soup applications. |
| Home-Compostable Certification Investment | TÜV Austria OK Compost HOME labeling creates premium positioning for e-commerce mailers in infrastructure-limited jurisdictions. |
| Industrial Composting Infrastructure Partnerships | Facility co-location agreements in California and Germany secure disposal pathway certainty for certified volume offtake. |
Methodological Framework
Initial hypotheses were tested against primary input from polymer chemists, composting infrastructure engineers, quick-service restaurant procurement directors, and packaging converter operations managers and refined through secondary validation against customs trade data, EPA compostability claim filings, EU Green Deal implementation reports, and SEC 10-K disclosures from listed packaging manufacturers. Bottom-up volume modeling triangulated against top-down demand aggregation across material composition, end-use segment, and regional regulatory cluster dimensions.
Variance decomposition across the projection horizon isolates drivers by segmentation dimension including material type, application function, disposal pathway requirement, and regional composting infrastructure maturity. CAGRs derive from modeled volume trajectories incorporating polymer formulation performance improvements, regulatory enforcement timelines, and industrial composting facility permitting rates. Industry-specific forecast inputs include PHA fermentation yield curves and extended producer responsibility fee structures under Germany's Packaging Act.
Material uncertainties — industrial composting capacity buildout delays, agricultural commodity price spikes, and multi-standard certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and polymer shelf-life stability in humid supply chains. Revision becomes warranted when industrial composting facility permitting velocity crosses thresholds that materially alter disposal pathway availability for certified volume.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market